
 Pouch Dispensing Fitment Market | 2026-2036
Pouch Dispensing Fitment Market Size, Share, and Industry Trends Forecast 2026-2036
Pouch Dispensing Fitment Market Outlook
Single-source to multi-source procurement is recalibrating how brand owners secure pouch dispensing fitments. Liquibox leverages its integrated film and fitment operations to shorten lead times for beverage customers. Aptar sustains technology leadership in precision-molded spout systems for personal care applications. WestRock anchors North American supply through its corrugated and flexible packaging network, competing on scale with specialized fitment producers.
Pouch dispensing fitments are injection-molded or thermoformed closure devices—typically LDPE, PP, or bio-based resins—that attach to flexible film structures to enable controlled product discharge without full package opening. Spout pouches dominate liquid food applications where resealability and pour control justify higher unit costs, while press-to-seal variants occupy growing positions in single-serve condiment segments where tear-notch simplicity reduces manufacturing complexity. Plastic materials lead volume but biodegradable films represent the fastest-growing material category as European packaging directives tighten.
FDA food contact notifications govern polymer selection for US-bound fitments, while EU REACH and the Packaging and Packaging Waste Regulation shape material compliance obligations for European exports. The EU Green Deal's recyclability targets are forcing redesign of multi-layer fitment-to-film interfaces. Stakeholders must monitor how mechanical recycling infrastructure investments alter acceptable fitment material specifications before committing to capital-intensive mold programs.
Market Dynamics
The EU Green Deal's recyclability mandates are forcing a complete redesign of multi-layer fitment-to-film interfaces, compelling converters to abandon legacy LDPE-PP combinations in favor of mono-material or chemically recyclable alternatives before mechanical recycling infrastructure matures.
Growth Catalysts
- REACH chemical compliance:European converters accelerating bio-based resin adoption for fitment production to preempt regulatory penalties.
- Ready-to-drink beverage segment:North American brands expanding spout pouch formats for on-the-go consumption occasions.
- Germany:Dairy and beverage converters leading continental adoption of precision-molded dispensing systems.
Market Restraints
- Petrochemical input volatility:LDPE and PP resin prices fluctuate with crude oil benchmarks, compressing converter margins on fixed-price contracts.
- Specialized mold fabrication:Precision spout tooling requires 16-24 week lead times from German and Japanese equipment suppliers.
- Multi-layer incompatibility:Existing fitment-film lamination adhesives interfere with current mechanical recycling sortation systems.
Strategic Opportunities
- US condiment segment:Press-to-seal fitment formats remain underpenetrated in single-serve sauce and dressing applications.
- FDA food contact notification:Streamlined approval pathways for post-consumer recycled content in fitment resins.
- Direct-to-retail channels:E-commerce fulfillment networks creating demand for puncture-resistant spout pouch formats.
Industry Challenges
- Polymer science specialization:Shortage of formulation chemists capable of balancing seal integrity with recyclability performance.
- Validation timeline compression:Brand owners demanding accelerated migration testing for new fitment materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouch Dispensing Fitment Market |
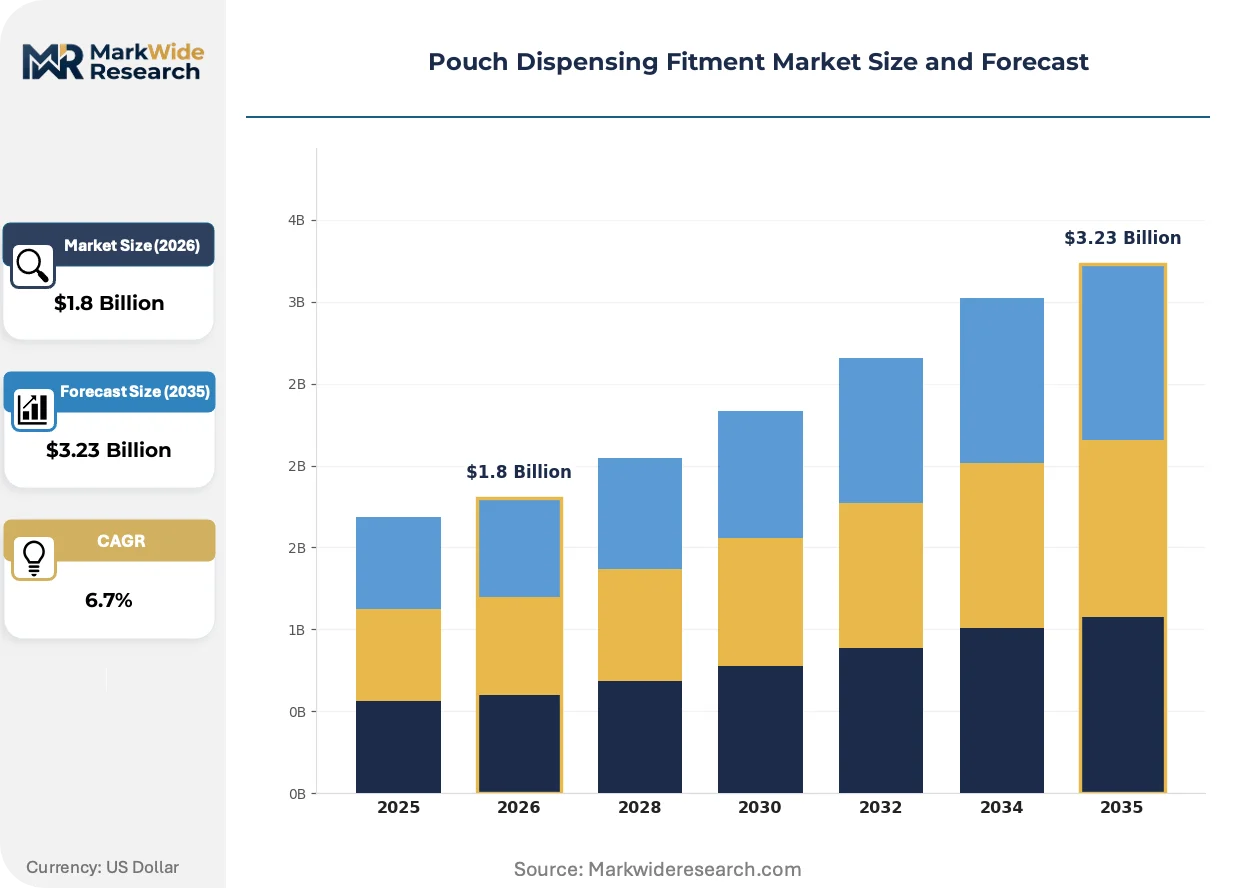
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Press-To-Seal Pouches, Spout Pouches Material: Plastic, Aluminum, Paper, Biodegradable Films End User: Food & Beverage, Personal Care, Home Care, Pharmaceuticals Closure Type: zipper, Spout, Tear Notch, Screw Cap |
| Companies Covered | Liquibox, MJS Packaging, IMPAK Corporation, K-Flex, Eagle Flexible Packaging, WestRock, Aptar, Worldwide Dispensers, PPC Flex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouch Dispensing Fitment Market Strategic Shifts
Material science breakthroughs and regulatory pressure are converging to transform how fitment producers design closure systems, with sustainability performance now rivaling functional specifications in procurement criteria.
Bio-based polyethylene derived from sugarcane ethanol is expanding into premium beverage fitment applications. German dairy brands have adopted these resins for organic product lines. The technology is expanding into conventional price tiers as Brazilian feedstock supply scales and conversion cost premiums compress below fifteen percent.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds for plastic packaging components. This forces fitment producers to secure food-grade rPP and rLDPE supply chains before certified volumes become scarce. German converters are responding fastest, locking multi-year offtake agreements with chemical recyclers.
Brand technical buyers now require fitment suppliers to provide third-party recyclability certifications before contract award. This displaces historical reliance on supplier self-declarations. The shift is most visible in France and the Netherlands, where retailer sustainability scorecards determine shelf access.
Pouch Dispensing Fitment Market Segmentation
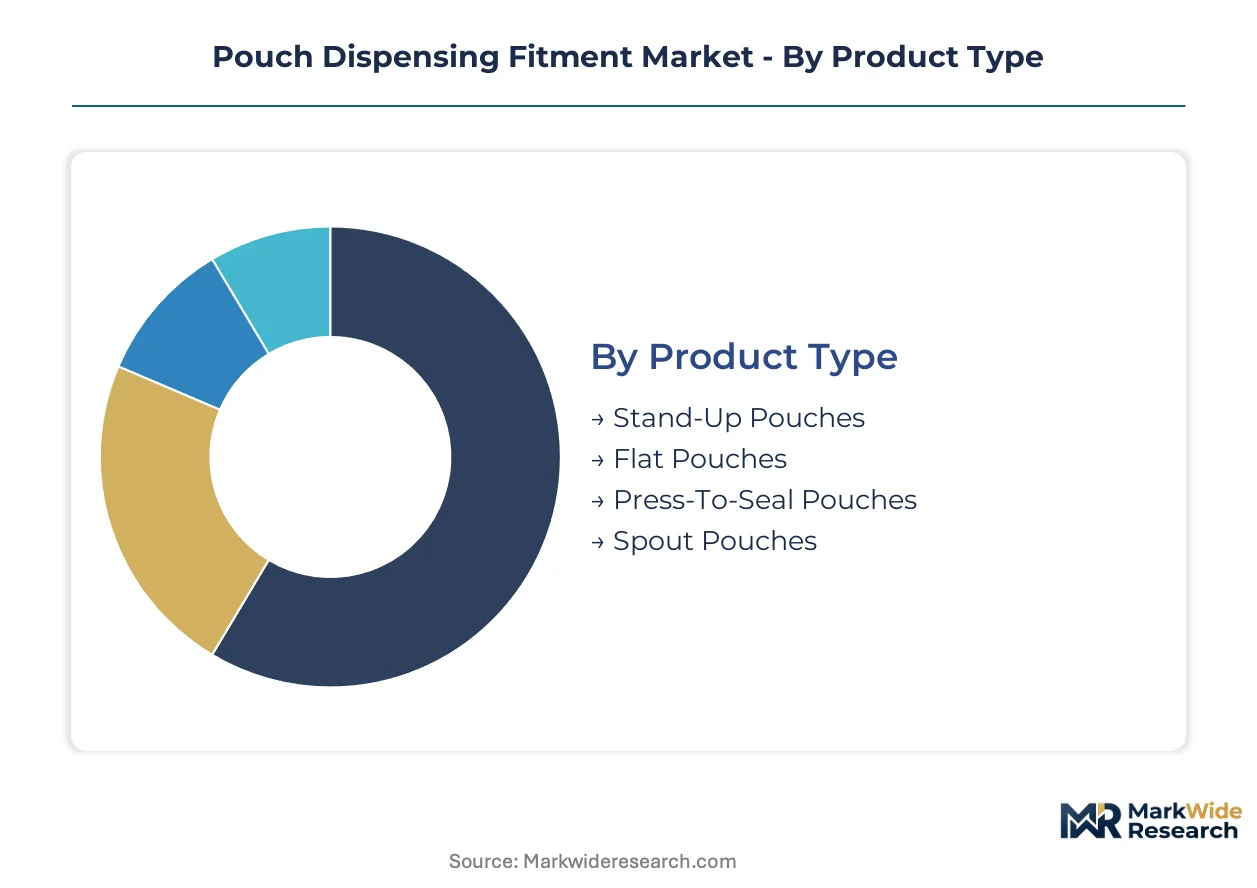
Pouch dispensing fitment configurations diverge sharply by product viscosity, shelf stability requirements, and consumer usage occasions. Material selection and closure mechanics determine recyclability compliance and manufacturing cost structures.
Product Type:
Standardization dominates high-volume beverage applications while customization concentrates in premium personal care and pharmaceutical formats requiring precise dosing control.
- Spout Pouches:Precision-molded LDPE or PP fitments attach to laminated film structures, enabling controlled pour rates for liquid foods. German dairy converters and North American ready-to-drink brands drive specification standards for resealability performance.
- Stand-Up Pouches:Gusseted bottom structures with integrated fitments provide shelf stability and billboard branding surface. Food and beverage brands in the United States specify these for condiment and sauce applications where vertical display matters.
- Press-To-Seal Pouches:Simplified closure mechanisms reduce tooling investment for single-serve condiment portions.
- Flat Pouches:Minimal material usage suits sample and trial-size personal care products with one-time dispensing needs.
Leading the category by volume: Spout Pouches. Growing fastest: Press-To-Seal Pouches.
Material:
Cost tiers separate commodity resins from certified sustainable alternatives, with regulatory pressure compressing the premium gap.
- Plastic:LDPE and PP dominate injection-molded fitment production, offering seal integrity and chemical resistance. REACH compliance obligations and EU Green Deal recyclability mandates are accelerating bio-based resin substitution in European supply chains.
- Biodegradable Films:Polylactic acid and starch-based alternatives address compostability requirements for organic food lines. French and Dutch retailer sustainability scorecards now require third-party certifications, displacing supplier self-declarations.
- Aluminum:Barrier properties suit oxygen-sensitive pharmaceutical and personal care formulations.
- Paper:Fiber-based structures gain traction in dry goods segments where moisture barrier demands are minimal.
Highest volume concentration: Plastic. Steepest expansion trajectory: Biodegradable Films.
End User:
Application-specific performance requirements dictate fitment specification, with food safety regulations imposing the strictest material validation protocols.
- Food & Beverage:FDA food contact substance notifications govern polymer selection for US-bound products, while EFSA standards apply to European exports. Spout pouch adoption concentrates in German dairy and North American condiment segments where resealability justifies unit cost premiums.
- Personal Care:Precision-molded dispensing systems for lotions and serums demand aesthetic finish and controlled dosing accuracy.
- Home Care:Chemical resistance requirements favor PP fitments for detergent and cleaning product applications.
- Pharmaceuticals:Migration testing and child-resistance specifications extend validation timelines for fitment suppliers.
Dominant demand source: Food & Beverage. Fastest specification evolution: Pharmaceuticals.
Closure Type:
Customer type stratification separates mass-market convenience from premium resealability, with manufacturing complexity determining converter margin profiles.
- Spout:Threaded or snap-fit precision-molded closures enable repeated opening and controlled dispensing. German equipment suppliers command 16-24 week lead times for specialized tooling, constraining capacity expansion for beverage converters.
- Screw Cap:Standardized thread specifications allow cross-supplier compatibility, reducing supply risk for brand owners.
- Zipper:Press-to-close tracks suit dry goods and multi-serve applications where full resealability is essential.
- Tear Notch:Single-use simplicity minimizes fitment cost for portion-controlled condiment and sample applications.
Widest deployment: Spout. Fastest format innovation: Screw Cap.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LDPE and PP resin supply chains from the US Gulf Coast and Rotterdam-Antwerp corridor anchor regional production economics for pouch dispensing fitment converters. German dairy packaging clusters and North American beverage bottlers generate concentrated demand for precision-molded spout systems. Regulatory divergence between FDA food contact notifications and EU REACH compliance is fragmenting material specification standards across export markets.
United States
Ready-to-drink beverage brands in California and Texas are expanding spout pouch formats for on-the-go consumption. FDA food contact substance notification timelines shape polymer selection for converters supplying national retail chains. Chicago-area flexible packaging clusters compete on integrated film-to-fitment production capabilities.
Germany
Dairy and beverage converters in Bavaria and Baden-Württemberg lead continental adoption of precision-molded dispensing systems. EU REACH chemical compliance obligations accelerate bio-based resin substitution in European supply chains. The Stuttgart industrial corridor hosts specialized mold fabrication suppliers commanding 16-24 week equipment lead times.
China
Domestic food brands in the Yangtze River Delta are adopting spout pouches for condiment and sauce applications. GB standards for food contact materials govern polymer selection for domestic and export-bound production. Shenzhen and Dongguan manufacturing clusters specialize in high-volume injection molding for cost-sensitive export markets.
France
Organic food lines in the Île-de-France region specify bio-based polyethylene fitments derived from sugarcane ethanol. Retailer sustainability scorecards in Paris and Lyon now require third-party recyclability certifications for shelf access. The Auvergne-Rhône-Alpes packaging corridor concentrates compostable film-to-fitment lamination expertise.
India
Single-serve condiment producers in Maharashtra and Gujarat are evaluating press-to-seal fitment formats for portion-controlled packaging. FSSAI food safety standards extend validation timelines for imported fitment materials. The Ahmedabad-Surat industrial belt hosts emerging flexible packaging converters serving domestic FMCG brands.
Pouch Dispensing Fitment Market Competitive Environment
Global majors compete with regional champions across technology licensing and mold fabrication capabilities. The market structures around three tiers: integrated film-fitment producers, specialized precision molding houses, and diversified packaging conglomerates. Strategic archetypes include captive resin-to-fitment operators, equipment-integrated solution providers, and regional converters with backward integration into film extrusion. Dominant competitive moves center on multi-year offtake agreements with chemical recyclers and accelerated FDA notification pathways for post-consumer recycled content.
Among US-based diversified packaging groups, WestRock occupies a position exemplifying scale-driven supply chain integration. German precision molding specialists represented by Aptar sit within the technology-leadership tier for controlled dispensing applications. Liquibox anchors the integrated film-fitment archetype with captive operations shortening lead times for beverage customers.
| Leading Market Players |
|---|
| Liquibox |
| MJS Packaging |
| IMPAK Corporation |
| K-Flex |
| Eagle Flexible Packaging |
| WestRock |
| Aptar |
| Worldwide Dispensers |
| PPC Flex |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA-notified precision-molded fitments and uncertified commodity alternatives manifests in both unit economics and supply chain topology, with German and Japanese tooling dependencies compressing margins at the premium tier while spot resin markets govern pricing volatility at the commodity end.
Pricing Analysis
Warranty and validation-service bundling separates precision-molded spout systems from unbundled press-to-seal alternatives, with the former commanding sustained premiums through guaranteed migration-test documentation and accelerated FDA notification support. Price differentiation hinges on REACH compliance certification tier and volume scale, with European organic dairy brands least sensitive to unit cost and single-serve condiment producers in India most reactive to resin price movements. Cost compression in the biodegradable film segment is intensifying as Brazilian sugarcane ethanol feedstock scales, though mechanical recyclability certification premiums remain sticky.
Supply Chain Analysis
Workforce availability constraints in Stuttgart and Nagoya industrial corridors extend specialized mold fabrication timelines, anchoring capacity expansion limits for precision dispensing systems. Raw material flows draw from US Gulf Coast LDPE complexes, Rotterdam-Antwerp PP corridors, and emerging Brazilian bio-ethylene clusters. Single-source vulnerability concentrates in German equipment suppliers for 16-24 week tooling programs. Distribution runs through integrated film-fitment producers serving beverage bottlers directly, with specialized molding houses relying on converter intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized mold fabrication bottlenecks in Germany and Japan prop pricing power for precision-molded fitment tiers, constraining volume expansion regardless of downstream brand owner demand.
For Market Incumbents: Extend multi-year offtake agreements with chemical recyclers before food-grade rPP and rLDPE certified volumes tighten under EU Packaging and Packaging Waste Regulation mandates. Lock dedicated capacity at Stuttgart-area tooling suppliers to preempt emerging converter competition. Backward integration into film extrusion insulates margin position against LDPE-PP resin volatility. For New Entrants and Emerging Players: Single-serve condiment producers in the US Southeast represent the most penetrable buyer archetype, with press-to-seal formats remaining underpenetrated against spout pouch dominance. Target Indian domestic FMCG brands evaluating portion-controlled packaging as FSSAI validation timelines compress for local material alternatives. Lead with rapid prototyping capabilities and 8-12 week tooling alternatives to German equipment lead times. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking film-fitment integration, with sponsor-to-sponsor transactions secondary. Five-to-ten year viability favors converters with locked chemical recycling feedstock and FDA notification pathway expertise. Watch German dairy brand sustainability scorecard enforcement as the inflection signal for bio-based resin premium persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Chemical Recycling Offtake | Locks food-grade rPP supply before EU recycled content mandates tighten. |
| Integrated Film-Fitment Capacity Expansion | Liquibox model shortens lead times for North American beverage customers. |
| Accelerated FDA Notification Pathway | Post-consumer recycled content approvals open premium positioning. |
| Bio-Based Resin Scale-Up Partnership | Brazilian sugarcane ethanol feedstock integration compresses cost premiums. |
| Specialized Mold Fabrication Acquisition | Stuttgart or Nagoya tooling capabilities remove capacity expansion constraints. |
Study Parameters
Document review covered FDA food contact substance notifications, EU REACH compliance filings, and flexible packaging trade association technical standards, complemented by interviews with polymer formulation chemists, beverage brand procurement directors, and German dairy converter operations managers. Secondary sources included customs data on LDPE and PP resin flows, SEC filings from diversified packaging groups, and ECHA substance volume tracking. Bottom-up fitment demand modeling triangulated against top-down flexible packaging consumption estimates.
Segment-level value and volume outputs derived from cross-referencing spout versus press-to-seal adoption rates, bio-based resin penetration curves, and regional regulatory implementation timelines across the projection horizon. Modeled dimensions included product type, material certification tier, closure mechanism complexity, and end-use application. CAGRs synthesized from converter capacity expansion announcements, brand owner packaging format shift disclosures, and mechanical recycling infrastructure investment tracking.
Revisions become necessary when EU Green Deal recyclability mandates accelerate ahead of chemical recycling capacity deployment, or when FDA streamlines post-consumer recycled content approval pathways faster than modeled. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Colombia Pouch Packaging Market
Pouch
Foam Pouch Market
Pouch
Liquid Pouch Market
Pouch
Slider Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Egypt Pouch Packaging Market
Pouch
Peelable Pouches Market
Pouch
Portion Control Packs Market
Pouch
Benelux Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Sterilization Pouches Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Box Pouch Market