
 Electronic Wrapper Market | 2026-2036
Electronic Wrapper Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Wrapper Market Analytics
A capital-intensity divergence between integrated substrate houses and modular packaging assemblers is rotating competitive dynamics toward captive wafer-level capacity. Amkor Technology leverages its scale in advanced system-in-package formats to sustain margin capture at the high-density end. ASE Technology Holding anchors volume throughput across Greater China with dedicated fan-out lines. Jabil competes through vertically controlled medical-grade cleanroom operations that extend its pharmaceutical wrapper credentials.
An electronic wrapper constitutes a functional enclosure—typically comprising multilayer polymer laminates, metallized films, or molded fiber structures with barrier coefficients below 0.1 g/m²/day oxygen transmission—that protects active electronic components from moisture, electrostatic discharge, and mechanical stress during transit and shelf life. Flexible films dominate unit economics in consumer electronics logistics where cost-per-thousand units governs procurement, while biodegradable materials represent the fastest-expanding material class as EU Packaging and Packaging Waste Regulation compliance deadlines approach. RFID technology leads the smart wrapper segment by value, though NFC adoption accelerates in pharmaceutical authentication where unit-level traceability commands premium pricing.
The FDA enforces Unique Device Identification through 21 CFR Part 820 quality system requirements that directly shape validation protocols for medical electronic wrappers. EU MDR and REACH substance restrictions further constrain material selection, forcing reformulation of halogenated flame retardants in transit packaging. Stakeholders must monitor convergence between ESG disclosure frameworks and evolving substrate recyclability mandates to preempt compliance-driven sourcing disruptions.
Market Dynamics
Pharmaceutical serialization mandates from the FDA and EU MDR are compressing adoption timelines for RFID-enabled electronic wrappers, forcing packaging converters to reconfigure substrate portfolios around traceability-embedded laminates.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system requirements for Unique Device Identification drive validation protocols that embed serialization layers directly into medical-grade wrapper specifications.
- Automotive OEM clusters in Germany:Stuttgart and Munich corridor manufacturers specify ESD-compliant metallized films for power electronics transit, creating pull-through demand for barrier-grade substrate houses.
- Biodegradable polymer formulations:EU Packaging and Packaging Waste Regulation deadlines accelerate reformulation of multilayer laminates toward compostable barrier alternatives.
Market Restraints
- Metallized film supply concentration:BOPP and PET metallization capacity clusters in China's Yangtze Delta, exposing buyers to input volatility from regional energy rationing.
- REACH substance restrictions:ECHA constraints on halogenated flame retardants force costly reformulation of transit packaging for electronics, extending qualification cycles.
- RFID inlay cost structure:Silicon chip and antenna substrate costs limit unit economics in high-volume consumer electronics logistics where cost-per-thousand governs procurement.
Strategic Opportunities
- India pharmaceutical export corridor:CDSCO alignment with FDA serialization standards creates whitespace for track-and-trace wrapper providers serving generic drug manufacturers in Hyderabad and Ahmedabad.
- NFC-pharmaceutical authentication convergence:Unit-level traceability commands premium pricing in cold-chain biologics where temperature logging integrates with patient-facing verification apps.
- Automated packaging line integration:Machine vision-readable wrapper formats enable direct-to-line feeding that eliminates manual handling in high-speed pharmaceutical serialization operations.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 validation for medical-grade wrapper production extends facility commissioning by 12-18 months, constraining capacity expansion.
- Multi-substrate recycling complexity:Separation of metallized films from biodegradable cores requires specialized de-metallization infrastructure that most municipal waste streams lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Wrapper Market |
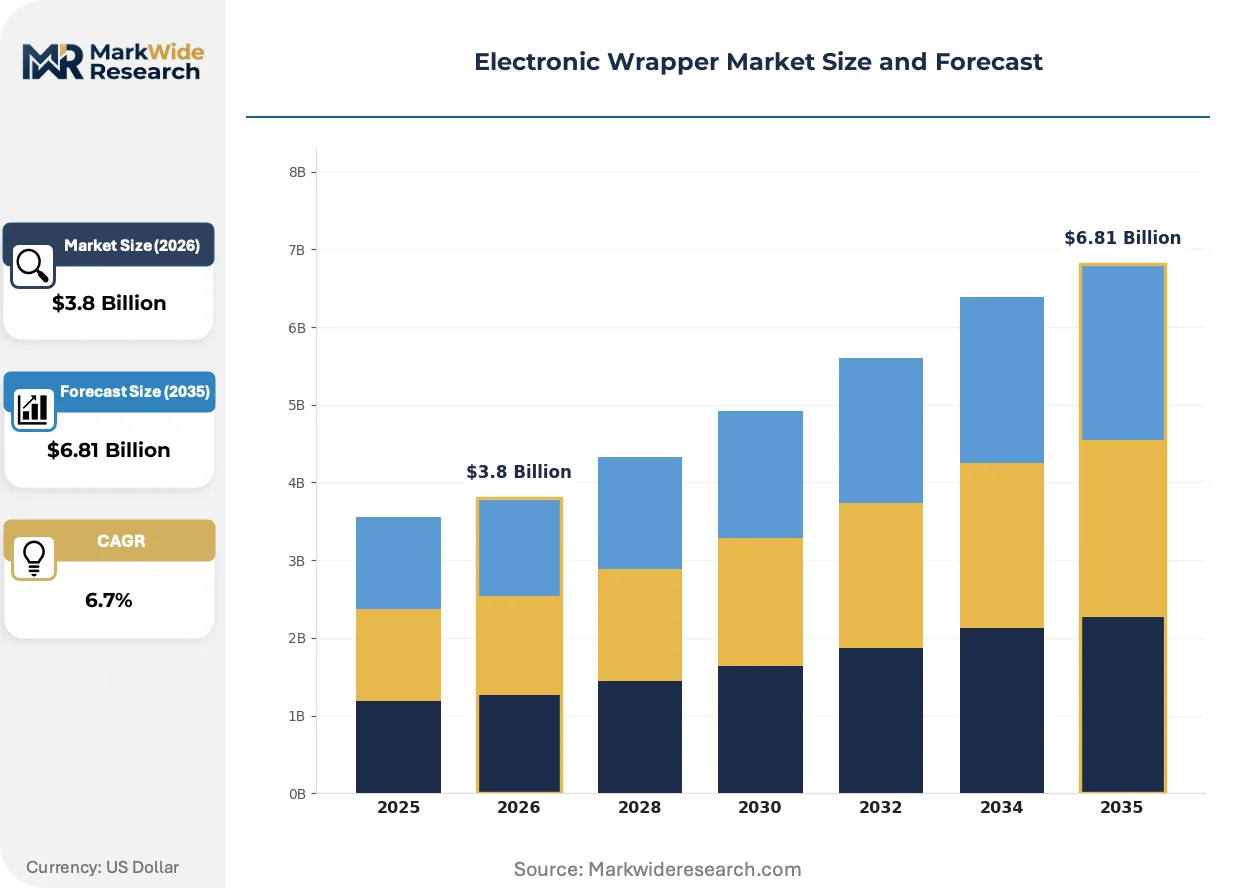
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
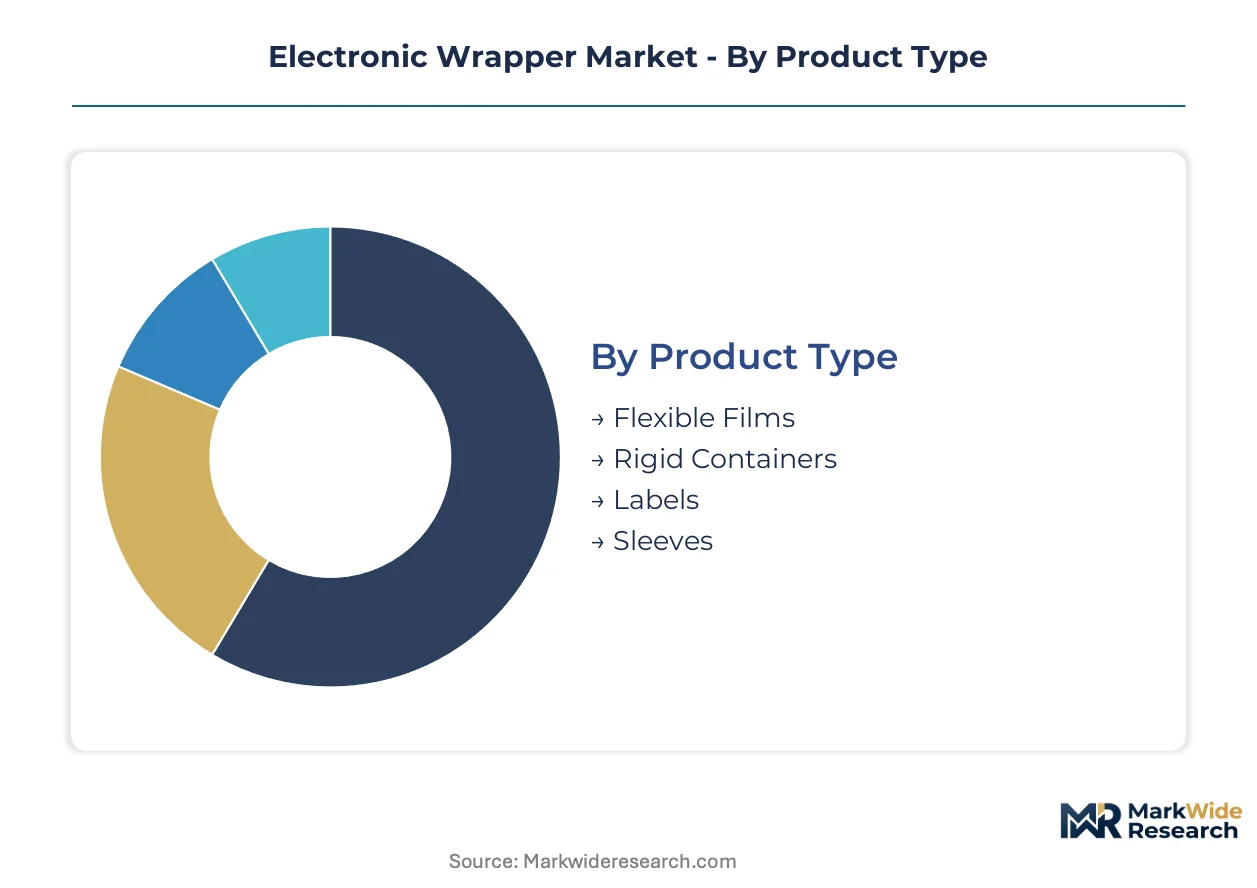
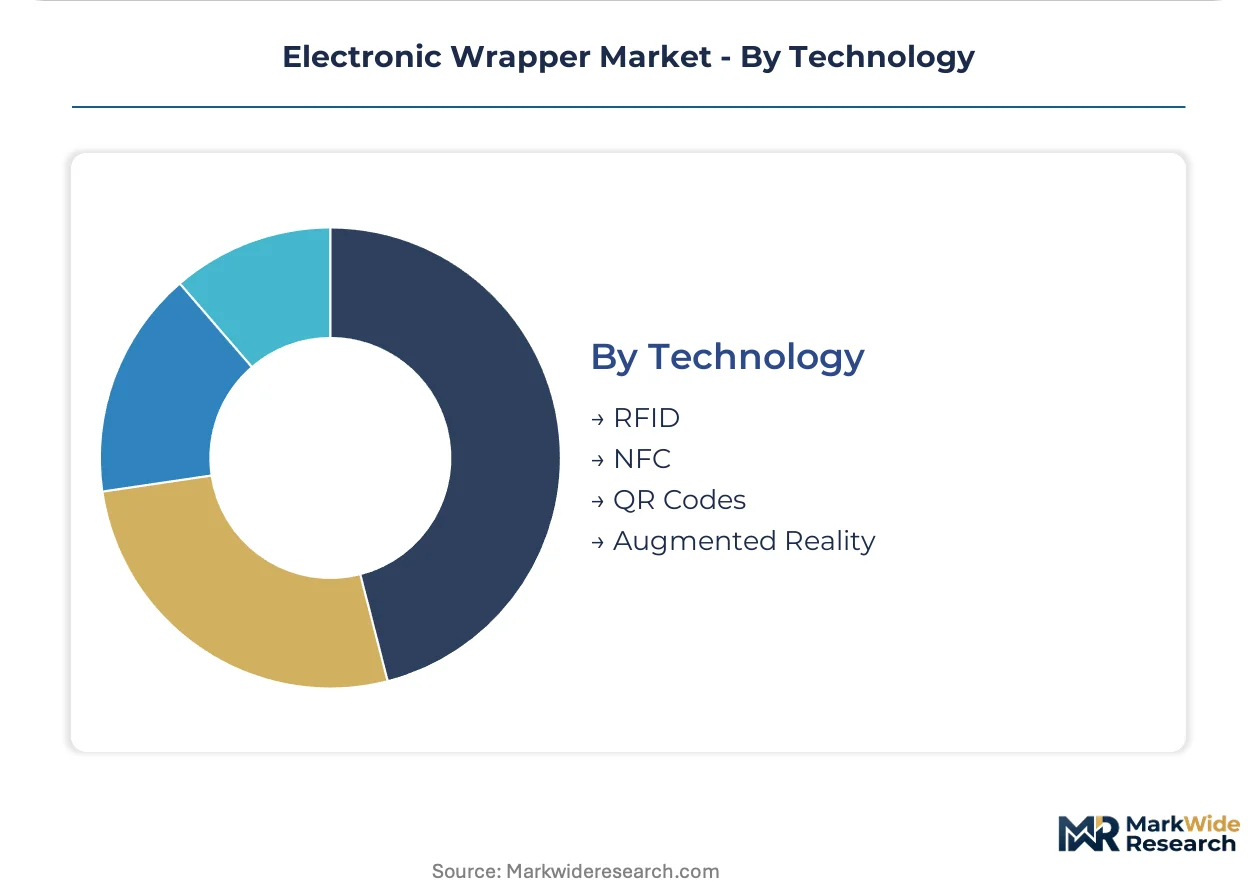
| Segmentation | Product Type: Flexible Films, Rigid Containers, Labels, Sleeves Material: Plastic, Paper, Aluminum, Biodegradable Materials Application: Food Packaging, Beverage Packaging, Consumer Goods, Pharmaceuticals Technology: RFID, NFC, QR Codes, Augmented Reality |
| Companies Covered | Amkor Technology, ASE Technology Holding, Jabil, UFP Technologies, Sealed Air Corporation, Sonoco Products Company, DuPont de Nemours, SCHOTT AG, BE Semiconductor Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Wrapper Market Evolving Landscape
Material science advances and regulatory compression are reconfiguring competitive advantage around substrate customization speed rather than commodity volume scale.
Printed electronics integration is fragmenting the traditional smart wrapper value chain. Conductive ink antenna patterns on flexible polymer substrates replace etched copper inlays for RFID-enabled pharmaceutical packaging. Contract packagers in the Netherlands and Massachusetts are qualifying roll-to-roll gravure lines that deposit silver nanoparticle traces at 15-meter-per-minute speeds. This capability is fragmenting procurement relationships as brand owners bypass legacy inlay converters to source directly from substrate houses with printed electronics capacity.
EU MDR Annex I general safety and performance requirements now mandate that device packaging maintain sterility and traceability across the full labeled shelf life. EMA guidance on electronic instructions for use is accelerating adoption of QR-embedded wrappers that link to dynamic regulatory content. German orthopedic implant manufacturers have responded by specifying laser-etched polymer films that survive ethylene oxide sterilization without delamination.
Pharmaceutical buyers are consolidating wrapper specifications across therapeutic categories to compress supplier management overhead. Novartis and Roche have reduced qualified substrate vendors from 40-plus to under 15 across their global packaging operations. This consolidation is most visible in Basel and Basel-Area manufacturing clusters where procurement teams now mandate single-source accountability for serialization hardware, substrate, and line integration.
Electronic Wrapper Market Segmentation
Electronic wrapper procurement patterns diverge sharply between domestic consumption corridors and export-oriented manufacturing hubs. Pharmaceutical serialization mandates in Germany and the United States concentrate demand for high-assurance formats, while consumer electronics logistics in Greater China drive volume throughput of cost-optimized substrates.
Product Type:
German pharmaceutical OEMs source flexible films and rigid containers domestically for EU MDR compliance, whereas sleeve and label procurement for Asian consumer goods export clusters runs through regional converting hubs.
- Flexible Films:Multilayer polymer laminates with metallized barrier layers achieve oxygen transmission rates below 0.1 g/m²/day. Stuttgart automotive power electronics manufacturers specify ESD-compliant metallized PET films for component transit, pulling supply from captive substrate houses in the Baden-Württemberg corridor.
- Rigid Containers:Thermoformed or injection-molded structures with integrated desiccant chambers protect moisture-sensitive semiconductors. Basel-area pharmaceutical packaging lines demand ISO 14644 Class 7 cleanroom-certified rigid formats for implantable device sterilization cycles.
- Labels:Pressure-sensitive or shrink-sleeve formats carry serialization data and authentication features.
- Sleeves:Full-body shrink formats conform to irregular electronic component geometries for pallet-level protection.
Flexible films command the established base. The steepest expansion runs through rigid containers.
Material:
Cost-tier stratification separates commodity plastics from premium biodegradable formulations, with aluminum serving as the pivot point for barrier-performance specifications.
- Plastic:BOPP, PET, and PE substrates dominate unit economics in high-volume consumer electronics logistics. China's Yangtze Delta metallization capacity feeds global demand for barrier-grade plastic films, though energy rationing exposes buyers to input volatility.
- Biodegradable Materials:PLA, PHA, and cellulose-based laminates reformulate multilayer structures for EU Packaging and Packaging Waste Regulation compliance. Dutch contract packagers qualify compostable barrier alternatives at 15-meter-per-minute gravure speeds, fragmenting traditional procurement relationships.
- Paper:Molded fiber or coated paperboard structures serve secondary cushioning applications.
- Aluminum:Metallized foil layers provide ultra-high barrier performance for moisture-critical active components.
Plastic substrates anchor current volume. Biodegradable materials are gaining share fastest.
Application:
Customer-type concentration splits between validated medical-grade procurement and price-sensitive consumer logistics, with pharmaceutical authentication commanding premium positioning.
- Pharmaceuticals:FDA 21 CFR Part 820 quality systems and EU MDR Annex I requirements embed serialization layers directly into wrapper specifications. Novartis and Roche have consolidated qualified substrate vendors from 40-plus to under 15 across Basel manufacturing clusters.
- Consumer Goods:Smartphone and wearable electronics transit demands cost-per-thousand optimization over barrier performance. High-volume logistics in Greater China prioritize flexible film formats that minimize dimensional weight in air freight.
- Food Packaging:Modified atmosphere barrier requirements for moisture-sensitive electronics crossover applications.
- Beverage Packaging:Limited direct application; primarily serves secondary protective transit for bottling equipment electronics.
Pharmaceutical applications concentrate margin capture. Consumer goods drive absolute volume expansion.
Technology:
Supply concentration in silicon chip and antenna substrate costs constrains unit economics, while printed electronics integration fragments legacy converter relationships.
- RFID:UHF and HF inlays enable pallet- and unit-level traceability through pharmaceutical cold chains. Silicon chip costs and antenna substrate expenses limit deployment in cost-sensitive consumer electronics logistics where cost-per-thousand governs procurement decisions.
- NFC:Near-field communication enables patient-facing authentication apps for cold-chain biologics. Massachusetts contract packagers qualify roll-to-roll gravure lines depositing silver nanoparticle antenna patterns, bypassing traditional etched copper inlay converters.
- QR Codes:Static or dynamic 2D barcodes link to electronic instructions for use under EMA guidance.
- Augmented Reality:Marker-embedded wrappers enable interactive assembly guidance for complex electronic devices.
RFID holds the installed base. NFC is climbing the fastest as pharmaceutical authentication premiums justify hardware costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical corridors where EU MDR compliance commands premium substrate qualification, while Chinese metallization clusters compete on throughput volume with thinner margin capture. This asymmetry rotates procurement leverage toward validated medical-grade suppliers in Western Europe against cost-optimized Asian converters.
United States
FDA 21 CFR Part 820 quality systems and Unique Device Identification mandates drive serialization-embedded wrapper specifications for medical electronics. Massachusetts contract packagers qualify roll-to-roll gravure lines for printed electronics integration. Greater Boston pharmaceutical clusters specify laser-etched polymer films that survive ethylene oxide sterilization cycles without delamination.
Germany
EU MDR Annex I general safety requirements mandate sterility maintenance across full labeled shelf life for implantable devices. EMA guidance on electronic instructions for use accelerates QR-embedded wrapper formats. Stuttgart and Munich automotive OEM corridors specify ESD-compliant metallized PET films for power electronics transit, pulling supply from captive substrate houses in Baden-Württemberg.
China
NMPA pharmaceutical serialization alignment with international standards creates track-and-trace wrapper demand for export-oriented generic manufacturers. Yangtze Delta metallization capacity clusters expose buyers to input volatility from regional energy rationing policies. Shanghai and Suzhou converting hubs dominate BOPP and PET barrier film production for consumer electronics logistics.
India
CDSCO alignment with FDA serialization standards generates whitespace for authentication-enabled wrapper providers serving pharmaceutical exporters. PLI scheme incentives for active pharmaceutical ingredients extend toward packaging material localization. Hyderabad and Ahmedabad generic drug manufacturing clusters consolidate qualified substrate vendors to compress supplier management overhead.
Netherlands
EU Packaging and Packaging Waste Regulation deadlines accelerate biodegradable laminate qualification at Dutch contract packaging operations. REACH substance restrictions on halogenated flame retardants force reformulation of transit packaging for electronics. Eindhoven and Rotterdam converting hubs qualify compostable barrier alternatives at 15-meter-per-minute gravure speeds.
Electronic Wrapper Market Competitive Landscape
Concentration sits with integrated packaging assemblers and specialized substrate houses that control captive cleanroom capacity. The vendor base spans three tiers: global-scale converters with pharmaceutical validation credentials, regional metallized film specialists serving automotive logistics, and emerging biodegradable material formulators. Competitive dynamics rotate around M&A activity targeting serialization technology assets and capacity expansion into ISO 14644 Class 7 cleanroom facilities.
Within the integrated assembler tier, Amkor Technology and ASE Technology Holding exemplify scale-driven positioning across advanced system-in-package and fan-out line formats. Jabil occupies a position among vertically controlled medical-grade operators with pharmaceutical wrapper credentials. These three anchors represent divergent strategic vectors: semiconductor packaging scale, Greater China volume throughput, and regulated medical device compliance.
| Leading Market Players |
|---|
| Amkor Technology |
| ASE Technology Holding |
| Jabil |
| UFP Technologies |
| Sealed Air Corporation |
| Sonoco Products Company |
| DuPont de Nemours |
| SCHOTT AG |
| BE Semiconductor Industries |
| Others |
Value Network & Pricing Analysis
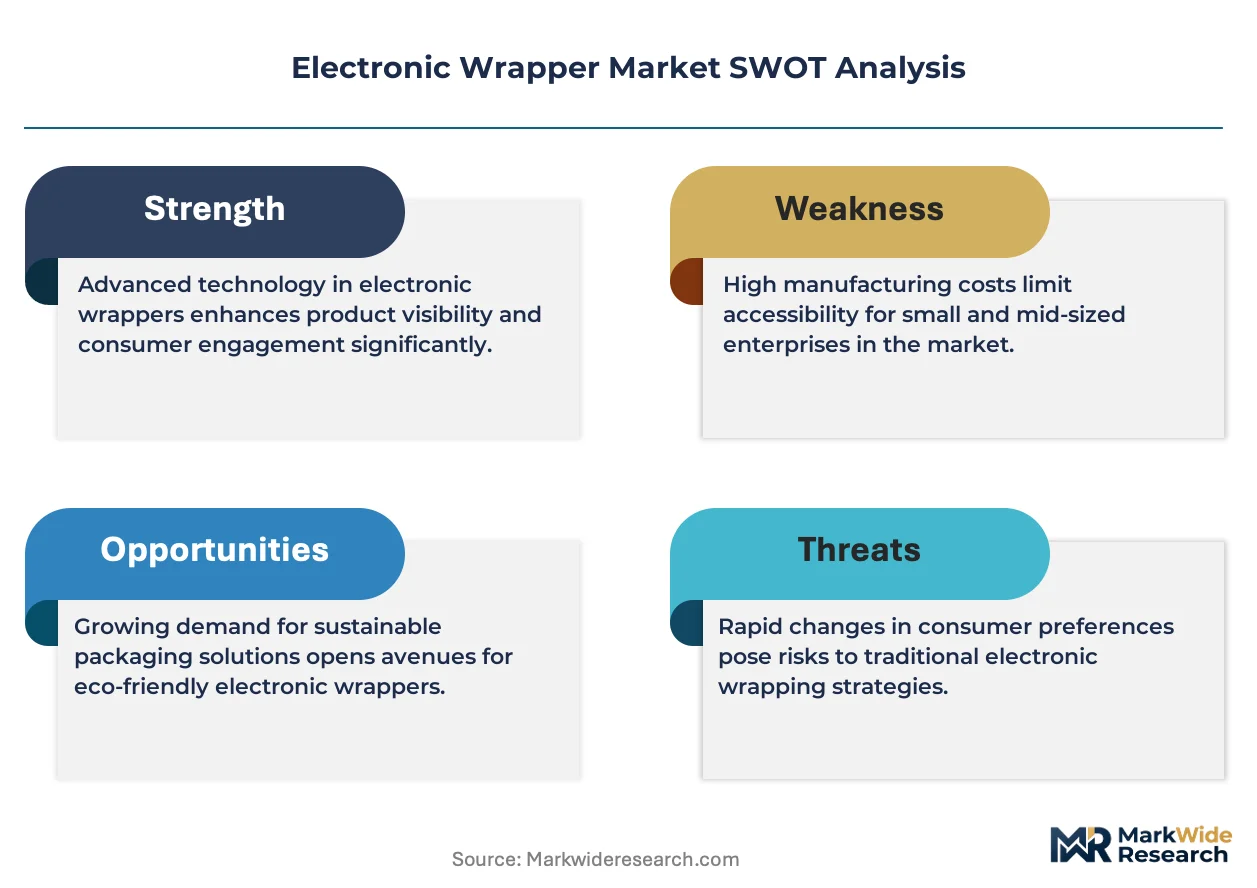
ISO 14644 Class 7 cleanroom certification gates both supplier qualification and price stratification simultaneously, forcing medical-grade substrate houses to recover validation costs through premium positioning while commodity converters compete on throughput economics.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical wrappers from standard consumer electronics formats. Three-tier pricing structure across validated medical-grade, industrial-specification, and economy logistics tiers reflects certification burden and barrier performance. Price differentiation rests on FDA 21 CFR Part 820 compliance tier and volume scale, with Basel-area pharmaceutical OEMs showing lowest sensitivity and Greater China consumer electronics procurement most responsive to unit-cost compression. Cost compression in economy-tier flexible films is intensifying because metallized PET input volatility from Yangtze Delta energy rationing squeezes converter margins.
Supply Chain Analysis
Inventory lead times for RFID inlays and metallized barrier films have extended as silicon chip supply concentrates in Taiwan and antenna substrate production clusters in South Korea. Raw material dependencies include silver nanoparticle conductive inks, BOPP and PET base films, and halogen-free flame retardant formulations. Single-source vulnerability sits with Yangtze Delta metallization capacity exposed to regional energy policy shifts. Distribution runs through captive substrate houses serving German automotive corridors, contract packagers in Massachusetts and the Netherlands, and regional converting hubs in Greater China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EU MDR, and emerging market serialization standards creates niche openings for specialized substrate houses that can compress qualification timelines faster than integrated assemblers.
For Market Incumbents: Shield market position by deepening captive cleanroom capacity in Baden-Württemberg and Basel-Area corridors where pharmaceutical OEMs consolidate qualified vendors. Prioritize ISO 14644 Class 8-to-7 upgrades ahead of EU MDR enforcement waves. Secure metallized film supply through backward integration into polymer extrusion or long-term offtake agreements with Yangtze Delta converters.
For New Entrants and Emerging Players: Lead with printed electronics qualification to bypass legacy RFID inlay converters and capture pharmaceutical authentication premiums. Target the India pharmaceutical export corridor where CDSCO-FDA alignment creates whitespace for track-and-trace wrapper providers. Establish gravure line partnerships with Dutch contract packagers already qualifying compostable barrier alternatives.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-grade cleanroom substrate production as ISO 14644 validation timelines extend facility commissioning. Five-to-ten year viability favors acquiring specialized substrate houses with existing pharmaceutical credentials over greenfield capacity builds. Watch NMPA serialization alignment progress as the signal indicating when Chinese export-oriented generic manufacturers will accelerate wrapper procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14644 Class 7 Cleanroom Certification | Validates medical-grade wrapper production for EU MDR sterility requirements in Basel manufacturing clusters. |
| Printed Electronics Capacity Addition | Enables roll-to-roll gravure deposition of silver nanoparticle antennas bypassing traditional copper inlay converters. |
| Backward Integration into Polymer Extrusion | Captures BOPP and PET base film supply to insulate against Yangtze Delta metallization volatility. |
| Biodegradable Barrier Formulation | Qualifies compostable laminates for EU Packaging and Packaging Waste Regulation compliance deadlines. |
| Pharmaceutical Serialization Hardware Integration | Consolidates single-source accountability for substrate, hardware, and line integration per Novartis and Roche procurement mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging development directors, regulatory affairs specialists at pharmaceutical OEMs, substrate procurement managers, and cleanroom facility engineers; and secondary validation through FDA 21 CFR Part 820 guidance documents, EMA MDR implementation reports, EU Packaging and Packaging Waste Regulation drafts, and SEC filings from publicly traded packaging converters. Bottom-up demand modeling across application segments triangulated against top-down market sizing from trade flow data and industry association estimates.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by product type, material class, end-use application, and technology integration level. CAGRs were derived from regression analysis of historical procurement patterns and regulatory mandate timelines. Industry-specific forecast inputs included pharmaceutical serialization compliance deadlines, automotive OEM ESD specification evolution, and EU biodegradable packaging adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of serialization mandates or accelerated biodegradable material cost parity would require recalibration. Forecasts reflect documented assumptions about cleanroom capacity expansion rates and metallized film supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market