
 Self-Sealed Bubble Bags Market | 2026-2036
Self-Sealed Bubble Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sealed Bubble Bags Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for European suppliers of self-sealed bubble bags. Sealed Air Corporation leverages its global manufacturing footprint to sustain certification across multiple regulatory jurisdictions. Pregis Corporation differentiates through specialized biodegradable film technologies that navigate tightening environmental standards.
Self-sealed bubble bags are protective packaging enclosures manufactured from polyethylene or polypropylene films incorporating air-retention chambers, sealed via integrated adhesive strips or zip-lock mechanisms to enable tool-free closure without additional tape or heat sealing. The primary commercial purpose centers on impact absorption and surface protection for goods during transit, with film thickness typically ranging from 40 to 120 microns depending on payload fragility. Biodegradable bags represent the fastest-expanding material segment as brand owners face Scope 3 emissions accountability, while multi-layer laminated configurations command premium positioning in electronics and pharmaceutical cold-chain applications where moisture and thermal insulation converge.
The EPA regulates volatile organic compound emissions from adhesive sealing systems used in domestic U.S. production, while ISO 18606 and ASTM D642 establish performance benchmarks for cushioning efficiency and seal integrity under compressive load. FDA food-contact material approvals govern polyethylene formulations destined for meal-kit and perishable e-commerce channels, creating a multi-layer compliance architecture that shapes supplier qualification timelines. Stakeholders must monitor emerging extended producer responsibility frameworks in California and New York, as state-level packaging fee structures will reshape total cost of ownership calculations for national distribution networks.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing protective packaging suppliers to prioritize automated sealing compatibility over manual handling efficiency. This operational imperative is restructuring material specifications and procurement relationships across the value chain.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandated recycled content thresholds are pulling converters toward certified post-consumer polyethylene streams, creating first-mover advantages for compliant suppliers in German automotive parts distribution.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics shipments require multi-layer laminated bags with thermal retention properties, opening premium positioning for specialized film configurations in export corridors.
- Biodegradable film technology maturation:Starch-based and PLA-blend formulations have achieved seal integrity parity with conventional polyethylene, enabling substitution in meal-kit and perishable channels governed by FDA food-contact approvals.
Market Restraints
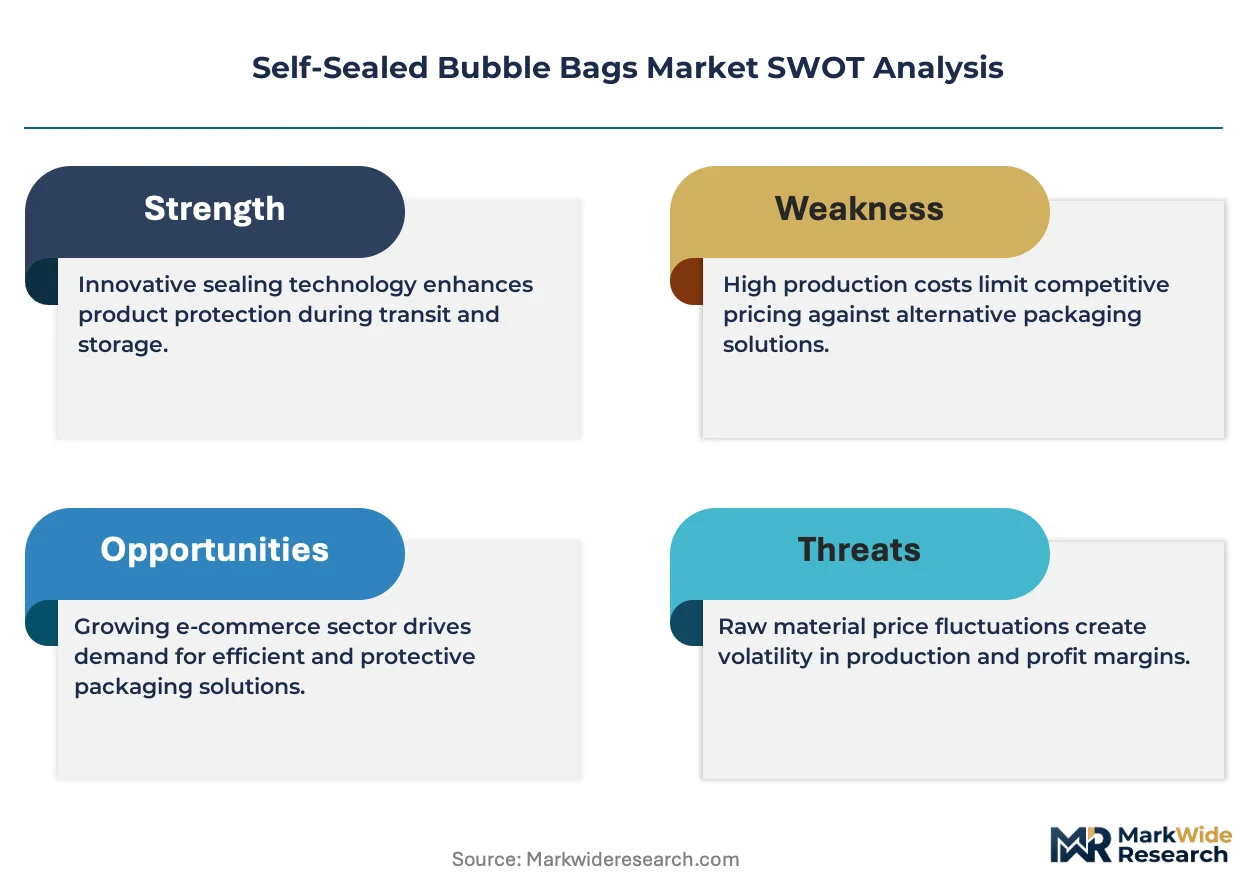
- Resin price volatility:Ethylene and propylene feedstock costs fluctuate with crude oil benchmarks, squeezing converter margins and complicating long-term contract pricing for fulfillment center buyers.
- Adhesive VOC compliance costs:EPA emission limits on solvent-based sealing systems require capital-intensive abatement equipment, raising effective cost-of-entry for domestic U.S. production capacity.
- Thin-film substitution threat:Paper-based honeycomb and molded pulp protective formats are gaining traction in electronics retail, displacing bubble configurations in consumer-facing unboxing experiences.
Strategic Opportunities
- Indian e-commerce logistics buildout:Flipkart and Amazon India fulfillment networks lack standardized protective packaging specifications, creating specification-setting opportunities for converters with BIS-certified film grades.
- California extended producer responsibility frameworks:Pending packaging fee structures will reward recycled content and penalize virgin material use, favoring suppliers with established post-consumer supply chains.
- RFID-embedded smart packaging convergence:Integration of track-and-trace chips with self-sealed bags enables theft detection and chain-of-custody verification for high-value pharmaceutical and electronics shipments.
Industry Challenges
- REACH certification timeline compression:European chemical substance registration requirements demand 12-18 month pre-market qualification periods, delaying revenue recognition for new biodegradable formulations.
- Automated fulfillment line integration:Bag dimension tolerances and seal-strength consistency must match robotic handling specifications, requiring precision calibration that exceeds legacy extrusion equipment capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sealed Bubble Bags Market |
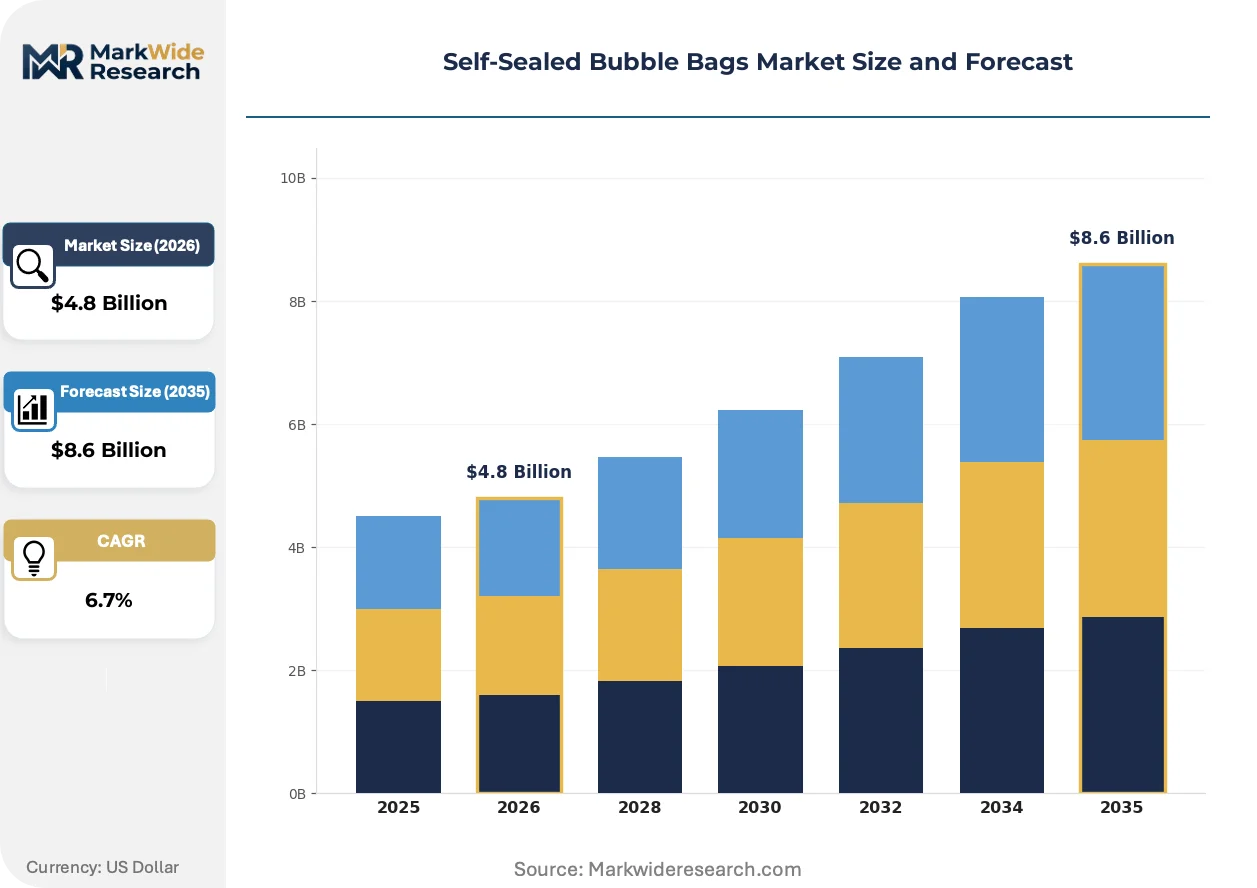
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Custom Bags, Biodegradable Bags, Multi-Layer Bags Material: Polyethylene, Polypropylene, Recycled Material, Laminated Material End User: E-Commerce, Retail, Electronics, Pharmaceuticals Packaging Type: Bulk Packaging, Individual Packaging, Made-to-Order Packaging, Stock Packaging |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Intertape Polymer Group, 3M Company, Uline, Smurfit Kappa Group, International Plastics, Jiffy Packaging Co., Veritiv Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sealed Bubble Bags Market Evolving Landscape
Material science breakthroughs and regulatory stringency are converging to redefine competitive advantage in protective packaging. Converters are racing to align product portfolios with emerging compliance architectures while capturing automation-driven efficiency gains.
Multi-layer co-extruded barrier films incorporating EVOH oxygen-blocking layers are overtaking conventional monolayer polyethylene in pharmaceutical and organic food channels. Cold-chain distributors in Germany and the Netherlands are specifying these configurations for temperature-sensitive exports. The technology is compressing acceptable shelf-life variance from ±48 hours to ±12 hours, enabling premium positioning in compliance-driven procurement.
REACH substance restriction amendments are forcing reformulation of slip agents and anti-static additives used in polyethylene films. ECHA's 2023-2027 restriction roadmap targets phthalate-based plasticizers prevalent in legacy bag production. German automotive parts exporters and Dutch flower bulb distributors are accelerating supplier audits to preempt supply disruption from non-compliant inventory.
Direct-to-fulfillment-center procurement contracts are displacing traditional distributor intermediaries in North American e-commerce packaging supply. Amazon, Walmart, and Target are consolidating supplier panels and demanding volume-commitment pricing with embedded sustainability reporting. This concentration is most visible in Pennsylvania and Ohio distribution clusters, where three buyers account for substantial regional protective packaging procurement.
Self-Sealed Bubble Bags Market Segmentation
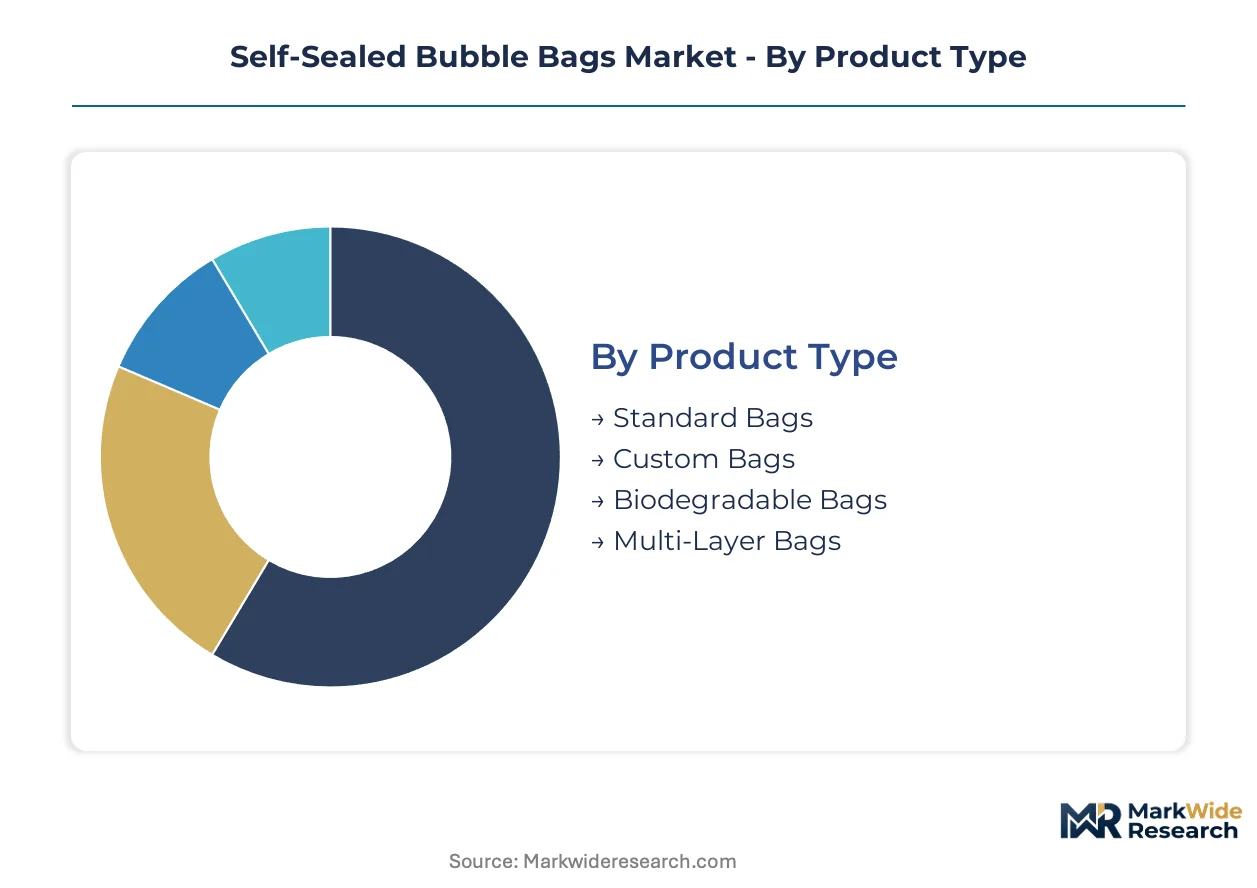
Segmentation in self-sealed bubble bags reveals how procurement specifications diverge across fulfillment channels. Buyers prioritize automation compatibility, regulatory compliance, or sustainability credentials depending on their operational constraints.
Product Type:
Material thickness and seal mechanism determine unit economics and automation throughput for fulfillment center buyers.
- Standard Bags:Monolayer polyethylene construction with integrated adhesive strips, typically 40-80 microns thickness. E-commerce fulfillment centers in Germany specify these for high-velocity consumer goods where cost-per-unit dominates procurement decisions.
- Biodegradable Bags:Starch-based or PLA-blend films achieving seal integrity parity with conventional polyethylene. EU Green Deal packaging waste directives are pulling brand owners toward these formulations for Scope 3 emissions accountability in meal-kit and perishable channels.
- Custom Bags:Dimension-specific manufacturing for irregular payload geometries. Electronics manufacturers in the Netherlands specify anti-static variants for semiconductor component protection.
- Multi-Layer Bags:Co-extruded barrier films incorporating EVOH oxygen-blocking layers. Pharmaceutical cold-chain distributors use these for temperature-sensitive biologics requiring thermal retention and moisture protection.
Standard bags lead on scale; biodegradable bags lead on momentum.
Material:
Feedstock selection shapes compliance trajectories and resin price exposure across converter operations.
- Polyethylene:Dominant feedstock for cost-sensitive applications, available in LDPE and HDPE variants. Automotive parts distributors in Germany favor this for REACH-compliant cushioning of machined components.
- Recycled Material:Post-consumer polyethylene streams certified under EU packaging waste directives. California's pending extended producer responsibility frameworks will penalize virgin material use, accelerating specification shifts.
- Polypropylene:Higher stiffness and temperature resistance than polyethylene. Electronics retail channels specify this for surface protection in unboxing experiences.
- Laminated Material:Multi-ply constructions combining polyethylene with aluminum or metallized films. Cold-chain pharmaceutical exporters in the Netherlands require these for thermal insulation performance.
Polyethylene dominates volume; recycled material climbs the fastest.
End User:
Payload value and damage liability thresholds determine specification stringency and pricing tolerance.
- E-Commerce:Automated fulfillment networks demand consistent seal strength and dimensional tolerance for robotic handling. Amazon and Flipkart procurement panels are consolidating supplier relationships around sustainability reporting requirements.
- Pharmaceuticals:FDA food-contact approvals and cold-chain validation govern material selection. Biologics shipments require multi-layer laminated configurations with documented thermal retention properties.
- Retail:Consumer-facing unboxing experiences drive aesthetic specifications. Electronics retailers are testing paper-based honeycomb substitutes in visible packaging layers.
- Electronics:Anti-static additives and surface protection priorities dominate. Semiconductor manufacturers specify ionic contamination thresholds below legacy polyethylene capabilities.
E-commerce commands volume concentration; pharmaceuticals sustain premium positioning.
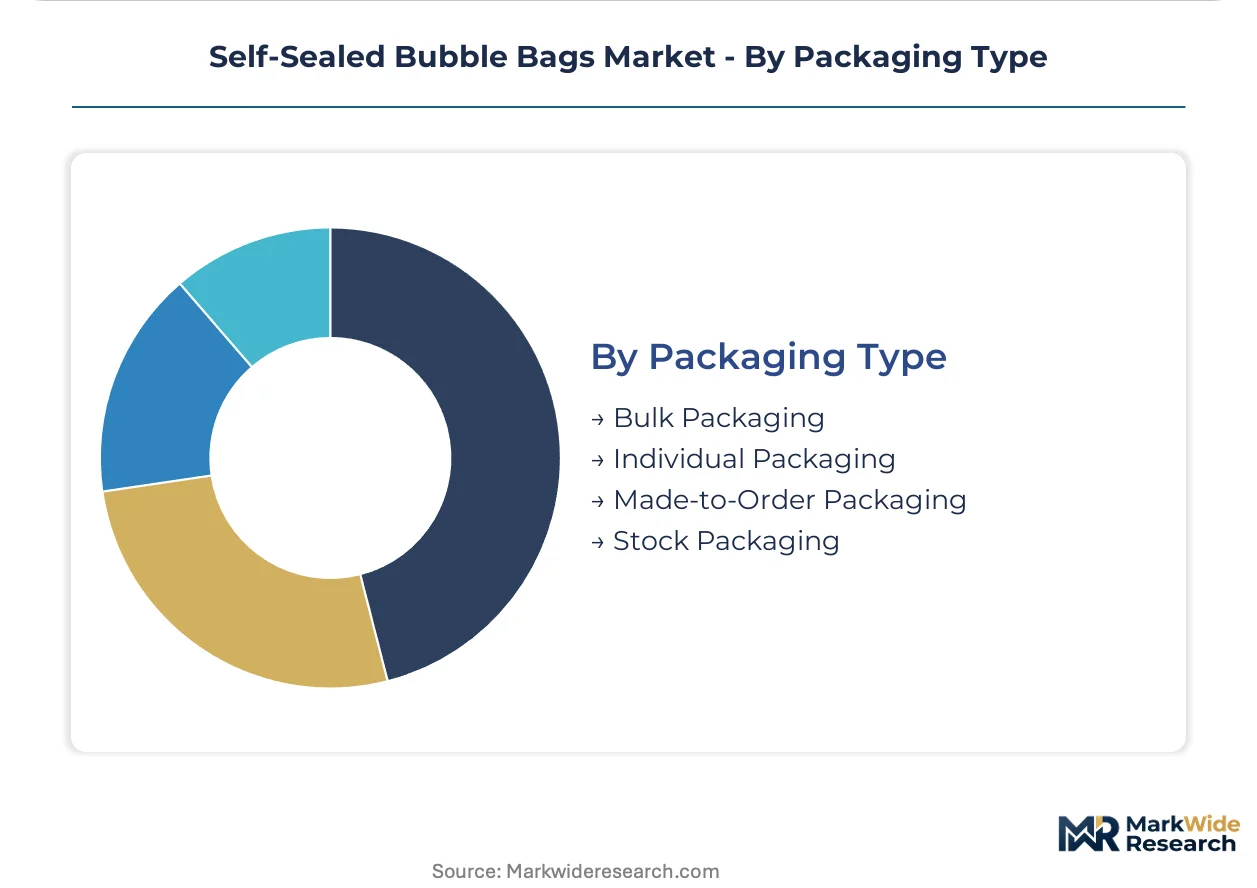
Packaging Type:
Order pattern predictability shapes inventory carrying costs and converter capacity planning.
- Bulk Packaging:Pallet-scale shipments to fulfillment centers with standardized specifications. Ohio and Pennsylvania distribution clusters consolidate procurement through direct-to-facility contracts.
- Made-to-Order Packaging:Dimension and print customization for branded unboxing experiences. Direct-to-consumer retailers specify short-run production with embedded sustainability messaging.
- Individual Packaging:Unit-level bags for small-parcel shipping. E-commerce platforms specify these for marketplace seller compliance programs.
- Stock Packaging:Pre-manufactured standard sizes available through distributor channels. Small and mid-sized retailers rely on these for procurement flexibility.
Bulk packaging anchors converter throughput; made-to-order packaging gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extrusion technicians and polymer chemists concentrate in Germany's Rhine-Ruhr corridor and the Netherlands' Eindhoven region, anchoring European protective packaging innovation. These talent clusters supply formulation expertise for biodegradable film development and multi-layer barrier technologies.
Germany
Automotive parts distributors in Stuttgart and Munich require REACH-compliant cushioned shipping for machined components. The EU Green Deal's packaging waste directives mandate recycled content thresholds, pulling converters toward certified post-consumer polyethylene streams. The Rhine-Ruhr industrial corridor hosts extrusion facilities serving pharmaceutical exporters in Frankfurt and Hamburg.
United States
Amazon, Walmart, and Target consolidate procurement through direct-to-facility contracts in Pennsylvania and Ohio distribution clusters. EPA volatile organic compound limits on adhesive sealing systems require capital-intensive abatement equipment for domestic production. California's pending extended producer responsibility frameworks will penalize virgin material use, reshaping national supply chain calculations.
Netherlands
Cold-chain distributors in Rotterdam and Amsterdam specify multi-layer laminated bags with EVOH oxygen-blocking layers for temperature-sensitive biologics exports. ECHA's substance restriction amendments target phthalate-based plasticizers in legacy film production. The Eindhoven region concentrates co-extrusion expertise for barrier film configurations serving Dutch flower bulb exporters.
India
Flipkart and Amazon India fulfillment networks lack standardized protective packaging specifications, creating specification-setting opportunities for converters. BIS-certified film grades qualify suppliers for national e-commerce logistics buildout. Maharashtra and Karnataka host emerging extrusion capacity serving Mumbai and Bangalore distribution hubs.
China
E-commerce platform consolidation drives demand for automated sealing compatibility in Shenzhen and Guangzhou fulfillment centers. The country's dual carbon goals pressure converters toward recycled material streams. The Yangtze River Delta concentrates blown film production for export-oriented electronics manufacturers.
Self-Sealed Bubble Bags Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with integrated film extrusion and adhesive formulation capabilities. Tiered specialization separates mass-market polyethylene suppliers from premium multi-layer barrier specialists. Three archetypes dominate: global protective packaging platforms with cross-regional certification maintenance, regional converters with biodegradable film specialization, and private-label distributors leveraging direct e-commerce relationships. M&A activity concentrates on post-consumer recycling supply chain control, while capacity expansion targets automated fulfillment line integration.
Among North American protective packaging platforms, Sealed Air Corporation and Pregis Corporation exemplify the certification-intensive archetype required for pharmaceutical and food-contact channels. Sealed Air's global manufacturing footprint represents sustained multi-jurisdictional compliance architecture, while Pregis occupies a position within biodegradable film specialization. Intertape Polymer Group anchors the mid-market converter tier with integrated adhesive and film operations.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Intertape Polymer Group |
| 3M Company |
| Uline |
| Smurfit Kappa Group |
| International Plastics |
| Jiffy Packaging Co. |
| Veritiv Corporation |
| Others |
Value Network & Pricing Analysis
Co-extruded multi-layer barrier film adoption is compressing unit economics for conventional monolayer polyethylene while concentrating production capability among converters with EVOH lamination expertise. This technology transition simultaneously elevates capital requirements for new capacity and tightens supply availability for pharmaceutical cold-chain specifications.
Pricing Analysis
Bundled sustainability certification and automated line integration services command 15-25% premiums over unbundled commodity bag supply. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer pharmaceutical grades from biodegradable meal-kit formulations and virgin polyethylene bulk fulfillment specifications. Cost compression in standard monolayer tiers is intensifying because resin price volatility and thin-film substitution pressure squeeze converter margins. E-commerce fulfillment centers exhibit highest price sensitivity due to volume-scale procurement leverage, while pharmaceutical exporters accept premium positioning for documented cold-chain validation.
Supply Chain Analysis
Direct-to-fulfillment-center channels handle hyperscale buyer demand from Amazon, Walmart, and Target procurement panels in Pennsylvania and Ohio distribution clusters. Production gravity centers on Germany, the United States, and China, with extrusion capacity tethered to specialized polymer chemist talent pools in the Rhine-Ruhr corridor and Yangtze River Delta. Feedstock exposure runs through ethylene and propylene resin streams, adhesive formulation chemicals, and EVOH barrier film substrates. Single-source vulnerability concentrates in post-consumer recycled polyethylene certification streams qualifying for EU Green Deal compliance. Distribution runs through consolidated supplier panels displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal packaging waste directives and California extended producer responsibility frameworks accelerate specification turnover and consolidate compliant supplier positions.
For Market Incumbents: Acquire post-consumer recycling supply chain assets to preempt feedstock scarcity as recycled content mandates tighten. Secure BIS-certified film grades for Indian e-commerce logistics buildout before specification standards crystallize. Defensive positioning requires embedding RFID track-and-trace capabilities to capture pharmaceutical and electronics premium tiers before technology convergence commoditizes smart packaging features. For New Entrants and Emerging Players: Fulfillment center sustainability officers represent the most accessible channel partner type for specification-setting influence in India's unstandardized procurement environment. White-space concentration sits in biodegradable film formulations for EU meal-kit channels and anti-static custom bags for Dutch semiconductor exporters. Target direct-to-facility contracts in Ohio and Pennsylvania clusters by leading with embedded carbon accounting reporting that incumbent distributors cannot match. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with biodegradable film specialization but limited multi-jurisdictional certification maintenance. Long-term viability over the next decade hinges on post-consumer recycling supply chain control and automated line integration capability. Watch California packaging fee implementation timing as the inflection signal for national specification shifts rewarding recycled content suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycling Supply Chain Acquisition | Secures certified polyethylene streams for EU Green Deal compliance ahead of mandate deadlines. |
| Automated Fulfillment Line Integration Partnership | Aligns bag dimension tolerances with Amazon and Walmart robotic handling specifications. |
| Biodegradable Film Formulation R&D Expansion | Accelerates starch-based and PLA-blend seal integrity parity with conventional polyethylene. |
| BIS Certification Investment for Indian Market Entry | Qualifies suppliers for Flipkart and Amazon India specification-setting opportunities. |
| RFID-Embedded Smart Packaging Convergence | Enables theft detection and chain-of-custody verification for pharmaceutical cold-chain shipments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The analysis triangulates perspectives from polymer chemists at extrusion facilities, procurement directors at e-commerce fulfillment centers, sustainability officers at brand owners, and regulatory affairs specialists navigating REACH and FDA compliance. Secondary sources include customs and trade data for resin feedstock flows, SEC 10-K filings from packaging conglomerates, EPA emission disclosure databases, and ECHA substance restriction amendments. Bottom-up capacity and demand modeling reconciles with top-down market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects and segment-migration dynamics. The analytical framework models product type, material feedstock, end-use industry, and packaging format dimensions throughout the forecast period. CAGRs derive from regression analysis against e-commerce shipment velocity indices, pharmaceutical cold-chain expansion rates, and regulatory implementation timelines. Industry-specific inputs include EU packaging waste directive compliance thresholds and California extended producer responsibility fee structures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resin price volatility, adhesive VOC regulatory amendments, and thin-film substitution acceleration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Block Sack Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Non-Barrier Bag Market