
 Sterile Wraps Market | 2026-2036
Sterile Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Wraps Market Analytics
Hospital group purchasing organization contracts are reshaping how sterile wrap suppliers secure volume commitments. Cardinal Health leverages backward integration into medical-grade nonwoven supply to sustain margin stability across volatile raw material cycles. Owens & Minor anchors its position through direct distribution to integrated delivery networks, while Medline Industries competes via private-label wrap portfolios that undercut branded equivalents on unit economics.
Sterile wraps are engineered barrier materials, typically spunbond-meltblown-spunbond polypropylene laminates or cellulose-based substrates, designed to maintain sterility of packaged medical items through steam, ethylene oxide, or gamma sterilization cycles while permitting gas exchange. Non-woven wraps dominate unit volume due to superior tear resistance and breathable membrane structures, whereas paper-based formats retain share in cost-sensitive clinic environments where instrument turnover remains moderate. Application demand skews heavily toward surgical instruments, as complex procedural kits require multi-layer wrap configurations that command premium pricing over standard device packaging.
FDA enforces 21 CFR Part 820 quality system regulations for sterile barrier manufacturers, while EPA oversees chemical emissions from ethylene oxide sterilization facilities that process wrapped loads. The EU Medical Device Regulation imposes stricter clinical evidence requirements on barrier systems sold in European markets, elevating compliance costs for exporters. Stakeholders must monitor evolving sterilization modality shifts as hospitals evaluate hydrogen peroxide vapor alternatives that demand compatible wrap chemistries.
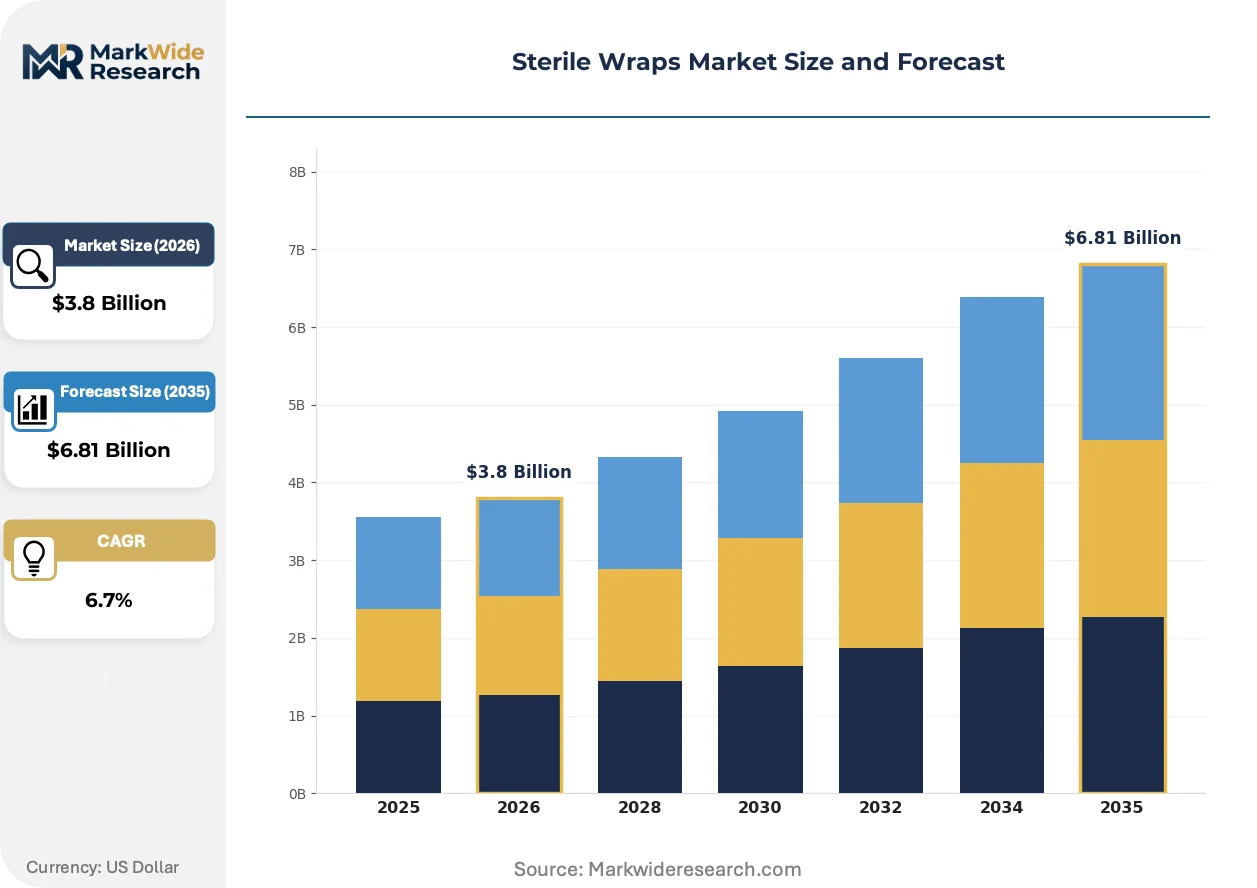
Market Dynamics
Hospital sterilization departments are consolidating wrap procurement through multi-year group purchasing organization contracts, compressing supplier margins while demanding validated compatibility with hydrogen peroxide vapor sterilization cycles.
Growth Catalysts
- Surgical volume recovery:Ambulatory surgery centers in the United States are rebuilding instrument throughput, driving wrap consumption for procedural kits.
- EPA emission controls:Tightening ethylene oxide sterilization facility regulations are accelerating hospital transitions to alternative modalities that require compatible barrier materials.
- Spunbond-meltblown-spunbond laminates:Superior tear resistance and breathable membrane structures in non-woven wraps are displacing paper-based formats in high-turnover surgical environments.
Market Restraints
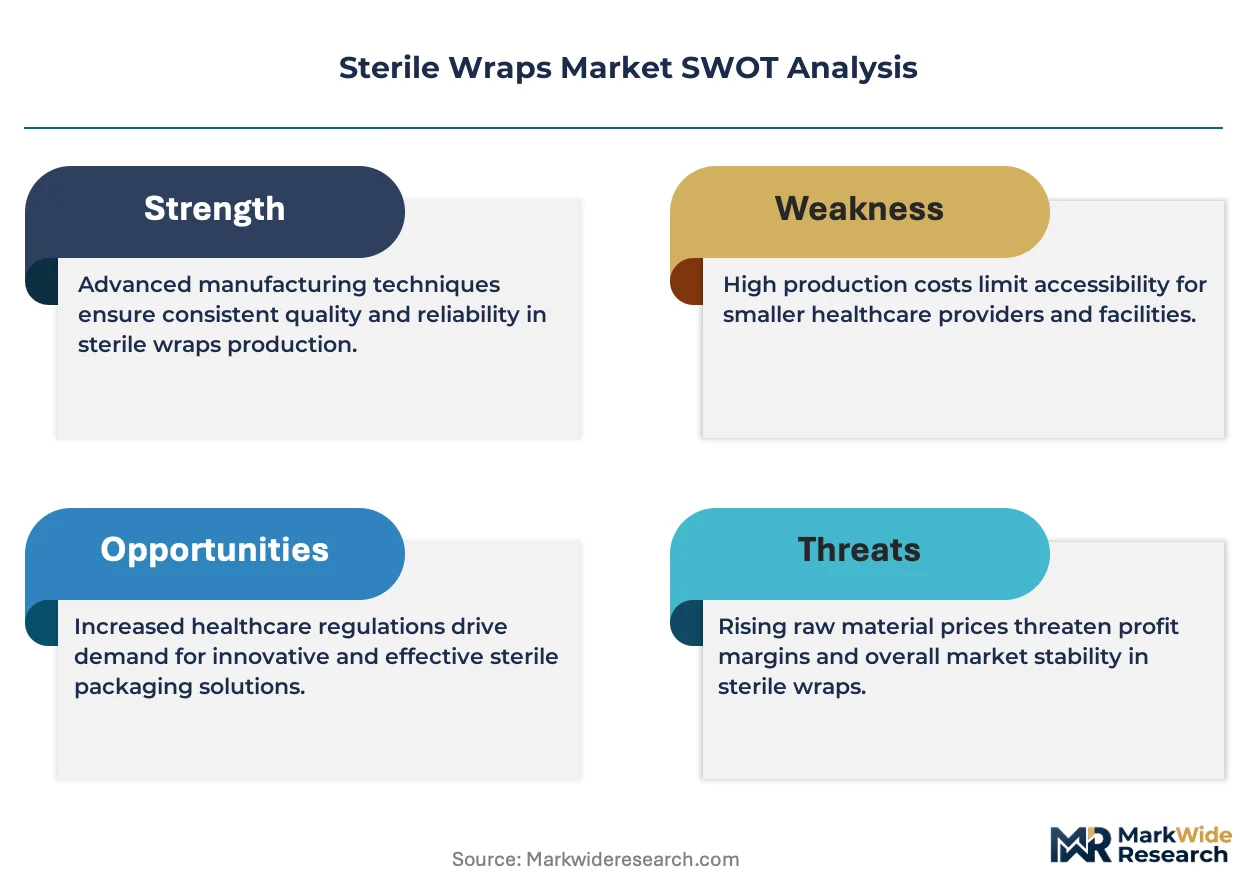
- Polypropylene feedstock volatility:Medical-grade nonwoven production depends on petrochemical inputs subject to energy price swings.
- EU MDR clinical evidence requirements:Stricter barrier system documentation for European market access elevates compliance costs for exporters.
- Reusable rigid container substitution:Some hospital systems are evaluating hard-shell sterilization cases for high-value instrument sets, threatening wrap volume in premium segments.
Strategic Opportunities
- India clinic infrastructure:Cost-sensitive outpatient surgical centers present volume potential for cellulose-based wrap formats.
- ISO 11607 harmonization:Global standardization of sterile barrier validation protocols reduces multi-market certification burden for manufacturers.
- Direct distribution to integrated delivery networks:Bypassing traditional distributor markups captures margin in concentrated hospital buying systems.
Industry Challenges
- Validation chemist scarcity:Shortage of specialists capable of certifying wrap compatibility across steam, ethylene oxide, gamma, and hydrogen peroxide modalities extends product launch timelines.
- Legacy sterilizer fleet incompatibility:Hospital capital constraints delay replacement of aging equipment, forcing wrap suppliers to maintain multi-generation compatibility portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Wraps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Woven, Woven, Paper-Based, Plastic-Based Application: Surgical Instruments, Medical Devices, Pharmaceuticals, Laboratory Supplies End User: Hospitals, Clinics, Research Institutes, Pharmacies Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Owens & Minor, Ahlstrom-Munksjo, Medline Industries, Cardinal Health, STERIS, 3M Company, Dynarex Corporation, Berry Global, Crosstex International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Wraps Market Evolving Landscape
Barrier material science and sterilization modality evolution are converging to redefine validation protocols and procurement specifications across hospital supply chains.
Smart wrap technologies incorporating RFID-enabled traceability layers are virtualizing inventory tracking from sterilization through point-of-use. Large academic medical centers in the United States are piloting these systems to reduce surgical delays from missing instruments. The technology is virtualizing traditional manual count sheets and enabling real-time location data that compresses kit preparation cycles.
EPA's National Emission Standards for Hazardous Air Pollutants are forcing ethylene oxide sterilization facility retrofits or closures. Industrial consequence includes accelerated hospital evaluation of vaporized hydrogen peroxide and nitrogen dioxide alternatives. Wrap manufacturers serving United States markets are reformulating barrier chemistries to maintain sterility assurance levels under shorter-cycle, lower-temperature sterilization protocols.
Consolidated procurement through healthcare group purchasing organizations is compressing supplier margins while demanding validated multi-modality compatibility. Integrated delivery networks are replacing fragmented hospital-level purchasing with centralized contracts that specify barrier performance tiers. This concentration is most visible in United States ambulatory surgery center networks upgrading sterilization infrastructure to support higher procedural volumes.
Sterile Wraps Market Segmentation
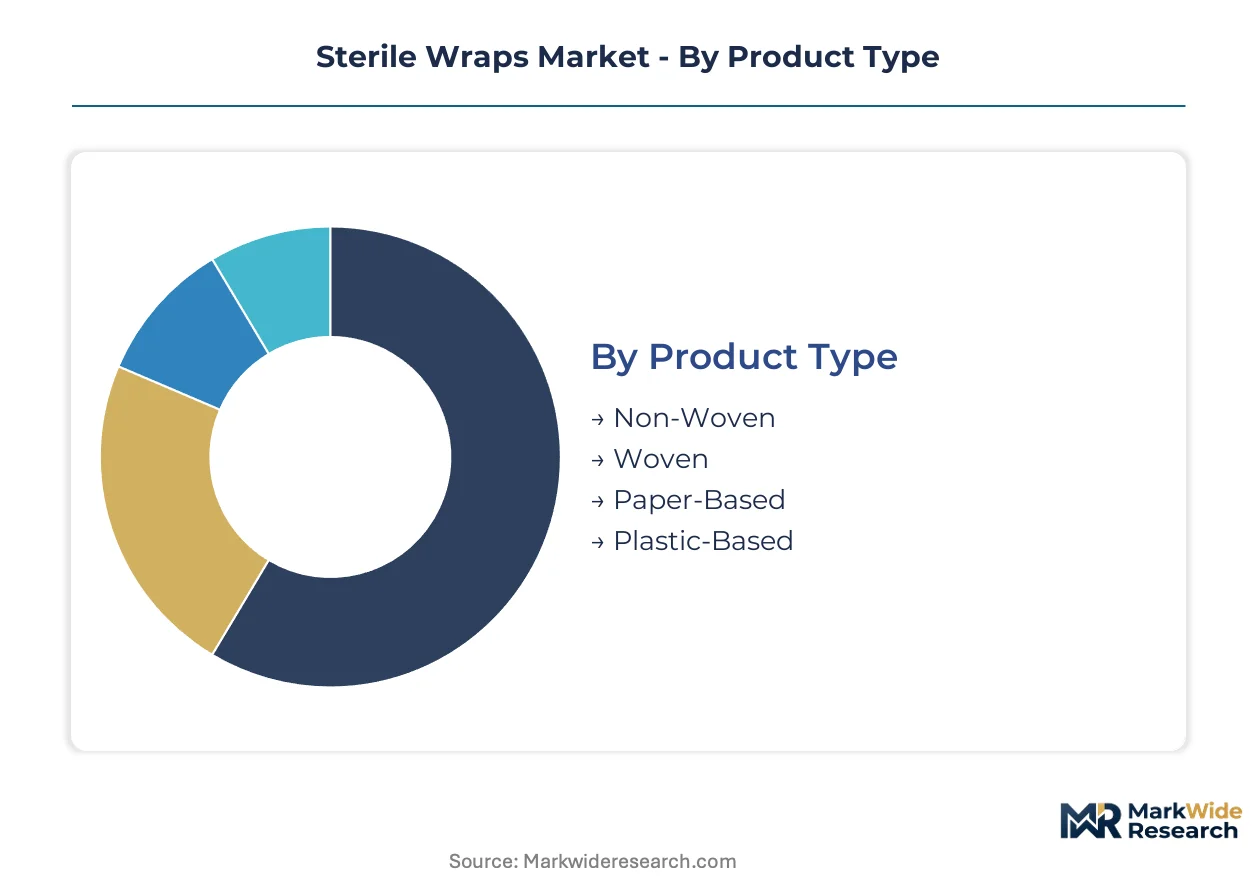
Sterile wrap procurement patterns diverge sharply across material formats, use cases, and institutional buyers. Understanding these fault lines exposes where margin pools concentrate and which customer relationships demand intensive technical support investment.
Product Type:
After-sales service intensity runs highest for multi-layer laminate systems requiring sterilization modality validation and field troubleshooting support.
- Non-Woven:Spunbond-meltblown-spunbond polypropylene laminates deliver superior tear resistance and breathable membrane structures essential for high-turnover surgical environments. Hospital sterilization departments in the United States concentrate procurement of these formats as ambulatory surgery center networks expand procedural throughput.
- Paper-Based:Cellulose substrates retain cost advantages for moderate instrument turnover settings where breathability requirements remain less stringent. Clinic infrastructure in India presents volume potential for these formats as outpatient surgical centers scale sterilization capabilities without premium material budgets.
- Woven:Reusable textile barriers serve niche applications in facilities with established laundering and re-sterilization workflows.
- Plastic-Based:Polyethylene and polypropylene films target pharmaceutical packaging where moisture vapor transmission rates demand precise control.
By volume, Non-Woven leads. By growth pace, Plastic-Based is ahead as pharmaceutical serialization requirements expand barrier specifications.
Application:
Cost tier stratification separates complex procedural kits commanding premium validation support from commodity device packaging with standardized specifications.
- Surgical Instruments:Complex procedural kits require multi-layer wrap configurations with validated compatibility across steam, ethylene oxide, gamma, and hydrogen peroxide modalities. Academic medical centers in the United States pilot RFID-enabled traceability layers to compress kit preparation cycles and reduce surgical delays.
- Medical Devices:Implantable and single-use devices demand sterile barrier systems meeting ISO 11607 validation protocols for global market access. Integrated delivery networks specify performance tiers that consolidate procurement through multi-year group purchasing organization contracts.
- Pharmaceuticals:Drug product packaging emphasizes moisture and oxygen barrier properties with documented stability data.
- Laboratory Supplies:Research-grade sterilization accepts broader material compatibility given lower sterility assurance level requirements.
Surgical Instruments captures the largest revenue pool. Pharmaceuticals climbs fastest as biologic drug formats proliferate.
End User:
Customer type determines whether procurement flows through centralized supply chain contracts or fragmented spot purchasing with diverging technical support expectations.
- Hospitals:Integrated delivery networks and academic medical centers anchor demand through sterilization department consolidation and multi-modality equipment fleets. FDA 21 CFR Part 820 quality system regulations enforce rigorous barrier manufacturer documentation that elevates supplier qualification barriers.
- Clinics:Ambulatory surgery centers in the United States are rebuilding instrument throughput, driving wrap consumption for procedural kits with compressed turnaround requirements.
- Research Institutes:Laboratory sterilization loads prioritize cost efficiency over clinical-grade sterility assurance levels.
- Pharmacies:Compounding operations require barrier materials compatible with small-batch sterilization cycles.
Hospitals dominate absolute consumption. Clinics are expanding most quickly as surgical migration to outpatient settings accelerates.
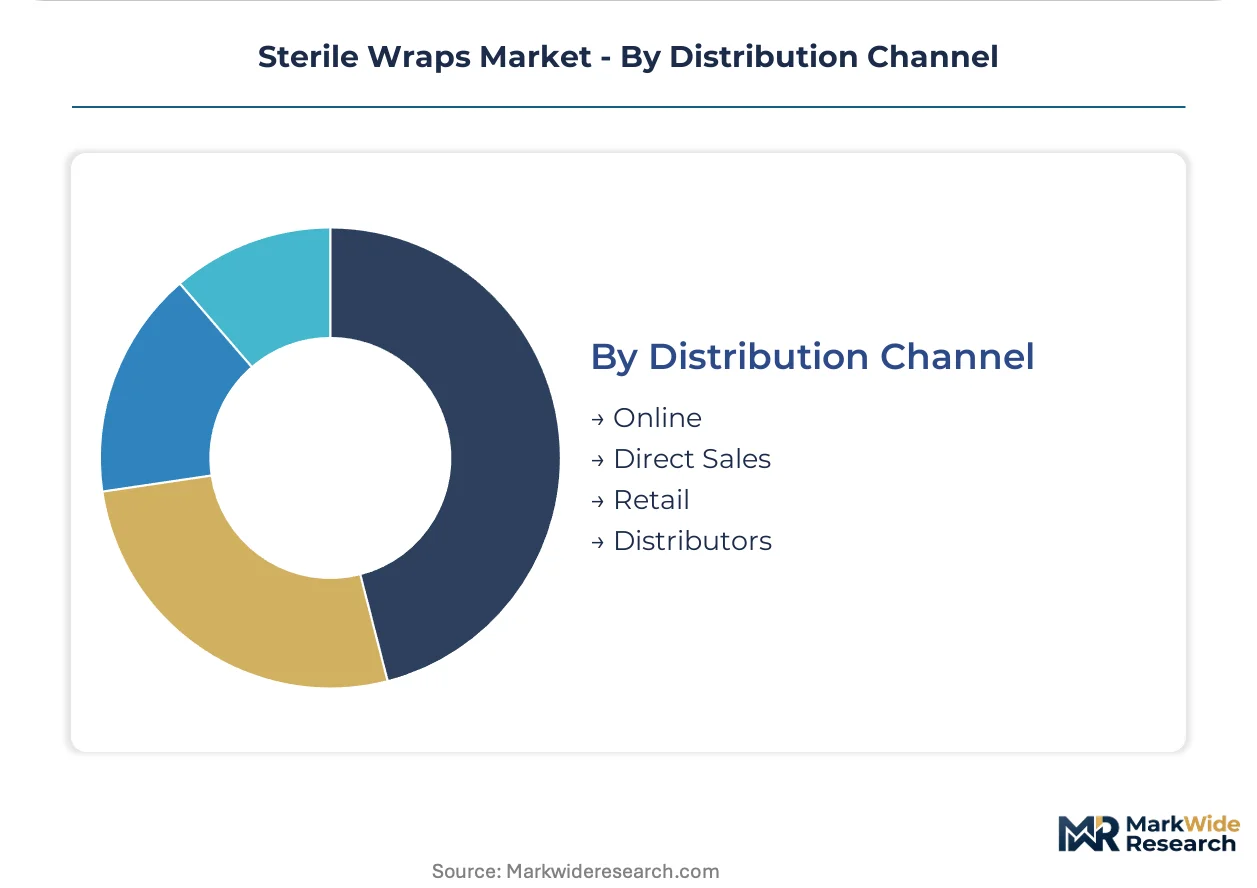
Distribution Channel:
Supply concentration among integrated delivery networks favors direct relationships that bypass traditional distributor markups and enable technical service integration.
- Direct Sales:Owens & Minor anchors market position through distribution to integrated delivery networks, while Cardinal Health leverages backward integration into medical-grade nonwoven supply to sustain margin stability. Large hospital systems negotiate multi-year contracts specifying validated compatibility with hydrogen peroxide vapor sterilization cycles.
- Distributors:Regional medical-surgical distributors serve fragmented clinic and research institute accounts with higher service costs per revenue dollar.
- Online:E-procurement platforms gain traction among smaller clinics with standardized product requirements and lower technical support needs.
- Retail:Limited to emergency replenishment and small-quantity purchases by independent practitioners.
Direct Sales commands the largest revenue share. Online channels are gaining share fastest as procurement digitization penetrates mid-tier accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where integrated delivery networks command multi-year contracts, while Indian clinic markets operate on thin margins driven by cellulose-based format competition. This asymmetry shapes where suppliers deploy technical validation resources versus basic volume plays.
United States
FDA 21 CFR Part 820 quality system regulations enforce rigorous barrier manufacturer documentation that elevates supplier qualification barriers for hospital sterilization departments. Ambulatory surgery center networks in Texas and Florida are rebuilding instrument throughput, driving wrap consumption for procedural kits with compressed turnaround requirements. The EPA's National Emission Standards for Hazardous Air Pollutants are forcing ethylene oxide sterilization facility retrofits, accelerating hospital transitions to hydrogen peroxide vapor alternatives in the Southeast corridor.
Germany
The EU Medical Device Regulation imposes stricter clinical evidence requirements on barrier systems, elevating compliance costs for sterile wrap exporters serving European markets. Academic medical centers in Baden-Württemberg pilot RFID-enabled traceability layers to compress kit preparation cycles and reduce surgical delays. Industrial sterilization infrastructure concentrates in the Rhine-Ruhr region where hospital group purchasing organization contracts are consolidating procurement through multi-year agreements.
India
Cost-sensitive outpatient surgical centers in Maharashtra and Gujarat present volume potential for cellulose-based wrap formats as clinic infrastructure scales sterilization capabilities. The Central Drugs Standard Control Organization oversees medical device quality standards that barrier manufacturers must navigate for market access. Sterilization equipment clusters in Bangalore and Hyderabad are expanding capacity to serve domestic surgical instrument reprocessing demand without premium material budgets.
China
The National Medical Products Administration enforces sterile barrier validation protocols as domestic surgical volume expands in tier-one hospital systems. Yangtze River Delta manufacturing hubs in Shanghai and Jiangsu province are spinning up medical-grade nonwoven capacity to reduce import dependence for polypropylene laminates. Hospital procurement centralization in Beijing and Guangdong is compressing supplier margins while demanding validated multi-modality compatibility.
Japan
The Ministry of Health, Labour and Welfare maintains stringent sterile barrier standards that foreign manufacturers must satisfy for pharmaceutical packaging applications. Kansai region medical device clusters around Osaka anchor demand for high-performance barrier materials serving complex procedural kits. Aging sterilizer fleets in rural prefectures force wrap suppliers to maintain backward compatibility portfolios across steam, ethylene oxide, and gamma modalities.
Sterile Wraps Market Competitive Landscape
Vertically integrated conglomerates and specialized medical-surgical distributors split the market into distinct competitive spheres with divergent margin structures. Three archetypes dominate: backward-integrated nonwoven producers controlling raw material input costs, direct-distribution specialists capturing margin in concentrated hospital buying systems, and private-label portfolio operators competing on unit economics. M&A activity concentrates among distributors seeking geographic density, while capacity expansion focuses on hydrogen peroxide-compatible barrier chemistries.
Among diversified healthcare suppliers, Cardinal Health exemplifies the backward-integrated archetype through captive medical-grade nonwoven supply chains. Owens & Minor occupies a position within the direct-distribution tier, anchoring relationships with integrated delivery networks that bypass traditional distributor markups. Medline Industries represents the private-label competitive vector, competing via portfolio breadth that undercuts branded equivalents on unit economics in cost-sensitive segments.
| Leading Market Players |
|---|
| Owens & Minor |
| Ahlstrom-Munksjo |
| Medline Industries |
| Cardinal Health |
| STERIS |
| 3M Company |
| Dynarex Corporation |
| Berry Global |
| Crosstex International |
| Others |
Value Network & Pricing Analysis
Polypropylene feedstock volatility determines both pricing tier spreads and supply chain shape in the sterile wraps market. Medical-grade nonwoven manufacturers face compressed margins when petrochemical inputs swing, forcing tiered pricing structures that separate hydrogen peroxide-compatible premium laminates from standard cellulose formats.
Pricing Analysis
The customization-premium spread separates configured-to-order multi-layer laminates from standard spunbond-meltblown-spunbond formats. Contract-based long-term offtake dominates hospital procurement through group purchasing organization agreements, with price differentiation driven by sterilization modality validation breadth and volume scale. Cost compression in standard-grade wraps intensifies as private-label portfolios undercut branded equivalents. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize validated multi-modality compatibility over unit economics.
Supply Chain Analysis
Supplier-financing facilities from integrated distributors extend payment terms to hospital systems, compressing working capital cycles for nonwoven producers. Medical-grade polypropylene supply concentrates in the United States, Germany, and China, with raw material dependencies on petrochemical feedstocks, meltblown machinery, and medical-grade certification services. Single-source vulnerability runs through specialized meltblown equipment suppliers. Distribution runs through direct sales to integrated delivery networks, bypassing traditional distributor markups in concentrated hospital buying systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as sterilization modality diversification creates distinct validation niches. Hospital transitions from ethylene oxide to hydrogen peroxide vapor split demand between legacy-compatible and next-generation barrier chemistries.
For Market Incumbents: Harden supply security through backward integration into medical-grade nonwoven production, insulating margin stability from polypropylene volatility. Expand hydrogen peroxide-compatible capacity ahead of EPA-mandated ethylene oxide facility retrofits. Secure multi-year GPO contracts specifying validated modality breadth to lock out private-label competitors. For New Entrants and Emerging Players: Pursue cost-sensitive clinic infrastructure in India with cellulose-based wrap formats, exploiting the gap between premium nonwoven laminates and budget-constrained outpatient surgical centers. Target direct-to-clinic distribution models bypassing established hospital supply chains. Lead with ISO 11607 harmonization credentials to reduce multi-market certification burden. For Investors and Strategic Acquirers: EPA emission standard enforcement reshapes the acquisition landscape toward hydrogen peroxide-compatible barrier specialists. Long-term viability centers on validation chemist capabilities and sterilization modality breadth rather than commodity volume scale. Watch for hospital capital constraint signals indicating accelerated legacy fleet replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Peroxide Compatibility Certification | EPA emission controls force hospital sterilization modality transitions requiring reformulated barrier chemistries. |
| Backward Integration into Nonwoven Supply | Captive medical-grade polypropylene production insulates margin stability from petrochemical input volatility. |
| RFID-Enabled Traceability Layer Development | Academic medical centers pilot smart wrap technologies to compress surgical kit preparation cycles. |
| Direct Distribution to Integrated Delivery Networks | Bypassing traditional distributor markups captures margin in concentrated hospital buying systems. |
| ISO 11607 Harmonization Investment | Global standardization of sterile barrier validation protocols reduces multi-market certification burden for exporters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 820 filings, EPA National Emission Standards documentation, hospital procurement databases, and GPO contract disclosures. Interviews with sterilization department managers, biomedical engineers, GPO contracts managers, and validation chemists anchor demand-side intelligence. Secondary validation draws from customs trade data, SEC filings of publicly traded distributors, and ISO 11607 technical committee outputs. Bottom-up volume modeling triangulates against top-down healthcare expenditure allocation analysis.
Forecast inputs include surgical volume recovery trajectories, sterilization equipment fleet replacement cycles, and regulatory modality shift timelines across the analysis window. Segmentation dimensions span material format, application complexity, end-user institution type, and distribution channel structure. CAGRs derive from instrument throughput projections, wrap consumption per procedure ratios, and pricing elasticity assumptions. Industry-specific inputs incorporate EPA enforcement pace for ethylene oxide facilities and hydrogen peroxide vapor adoption curves in ambulatory surgery center networks.
Sensitivities concentrate around EPA regulatory enforcement intensity, polypropylene feedstock price volatility, and hospital capital constraint duration. Forecasts reflect documented assumptions on sterilization modality transition timelines and GPO contract renewal patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Surgical Instruments Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Medical Tray Sealers Market