
 GNSS IC Market | 2026-2036
GNSS IC Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS IC Market Foresight
Multi-constellation precision is rotating the GNSS IC market toward higher-specification tiers. Qualcomm Technologies leverages its modem-integrated approach to dominate smartphone positioning stacks. STMicroelectronics sustains automotive-grade qualification leadership through AEC-Q100 certified Teseo platforms. u-blox specializes in industrial IoT modules where sub-meter accuracy commands premium positioning.
A GNSS IC integrates RF front-end, baseband processor, and embedded firmware to decode satellite signals from GPS, GLONASS, Galileo, and BeiDou constellations, typically fabricated on 40nm to 22nm CMOS processes for power-constrained devices. Chipset architectures capture the dominant value pool as dual-frequency L1/L5 designs displace legacy single-band solutions in mobile and automotive applications. Consumer Electronics anchors volume demand through smartphone integration, while Fleet Management represents the fastest-growing application as telematics mandates expand across commercial vehicle segments.
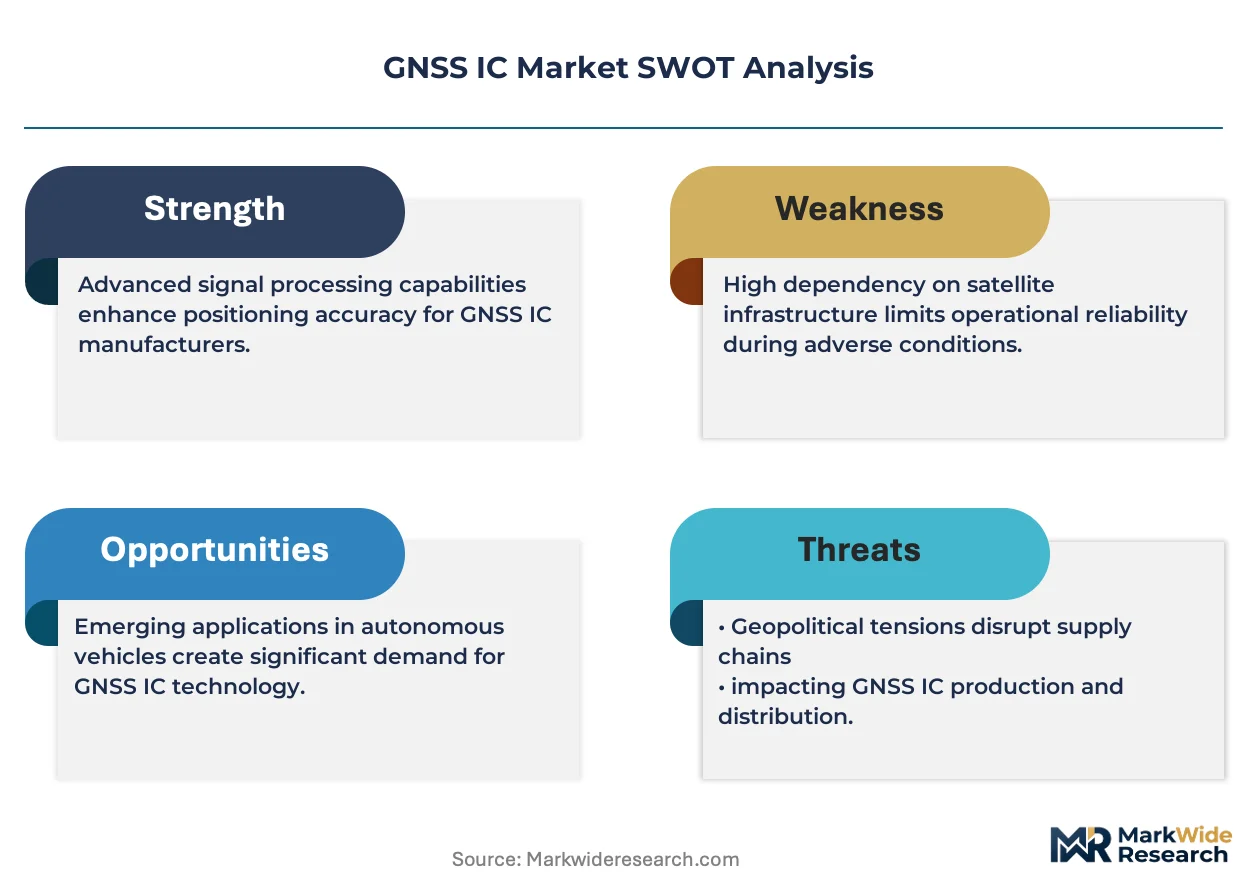
FCC equipment authorization rules in the United States shape transmitter spurious emission limits, while ETSI Galileo standards in Europe mandate open-service signal authentication for automotive safety systems. Japan's METI promotes QZSS augmentation adoption through industrial policy, tightening performance benchmarks for precision agriculture equipment. Stakeholders must monitor constellation modernization timelines and regional certification divergence to calibrate R&D allocation across receiver architectures.
Market Dynamics
Dual-frequency L1/L5 receiver architectures are compressing legacy single-band silicon economics while ETSI authentication mandates force automotive OEMs toward certified multi-constellation chipsets. This technical-regulatory convergence concentrates procurement power with tier-1 suppliers capable of AEC-Q100 qualification.
Growth Catalysts
- ETSI Galileo OSNMA Mandates:Europe's open-service navigation message authentication standards for automotive safety systems are accelerating dual-frequency chipset qualification cycles.
- Telematics Mandates:Commercial vehicle tracking requirements across fleet management segments are expanding addressable hardware volumes for multi-constellation modules.
- QZSS Augmentation:Japan's industrial policy promoting centimeter-level augmentation services is tightening performance benchmarks for precision agriculture equipment procurement.
Market Restraints
- RF Front-End Concentration:SAW filter and LNA supply concentrates among specialized compound semiconductor foundries, creating input cost volatility for fabless GNSS designers.
- AEC-Q100 Certification Timelines:Automotive-grade qualification cycles extend 18-24 months, freezing out mid-tier IC vendors from safety-critical navigation module supply.
- Cellular Modem Integration:Smartphone positioning stacks are migrating into baseband-integrated solutions, eroding discrete GNSS IC attach rates in consumer electronics.
Strategic Opportunities
- Industrial IoT Positioning:Sub-meter accuracy requirements in asset tracking and drone navigation are opening premium module tiers beyond consumer price bands.
- FCC Equipment Authorization:Updated transmitter spurious emission rules in the United States are creating compliance service adjacencies for domestic module vendors.
- Sensor Fusion Convergence:Tight coupling between GNSS receivers and IMU arrays is enabling new product categories in autonomous robotics and precision surveying.
Industry Challenges
- RF/Analog Design Talent Scarcity:Mixed-signal IC expertise for low-noise amplification and interference mitigation remains concentrated among veteran engineering cohorts.
- Constellation Modernization Lag:Receiver firmware must synchronize with GPS III, Galileo FOC, and BeiDou-3 signal deployments, fragmenting validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS IC Market |
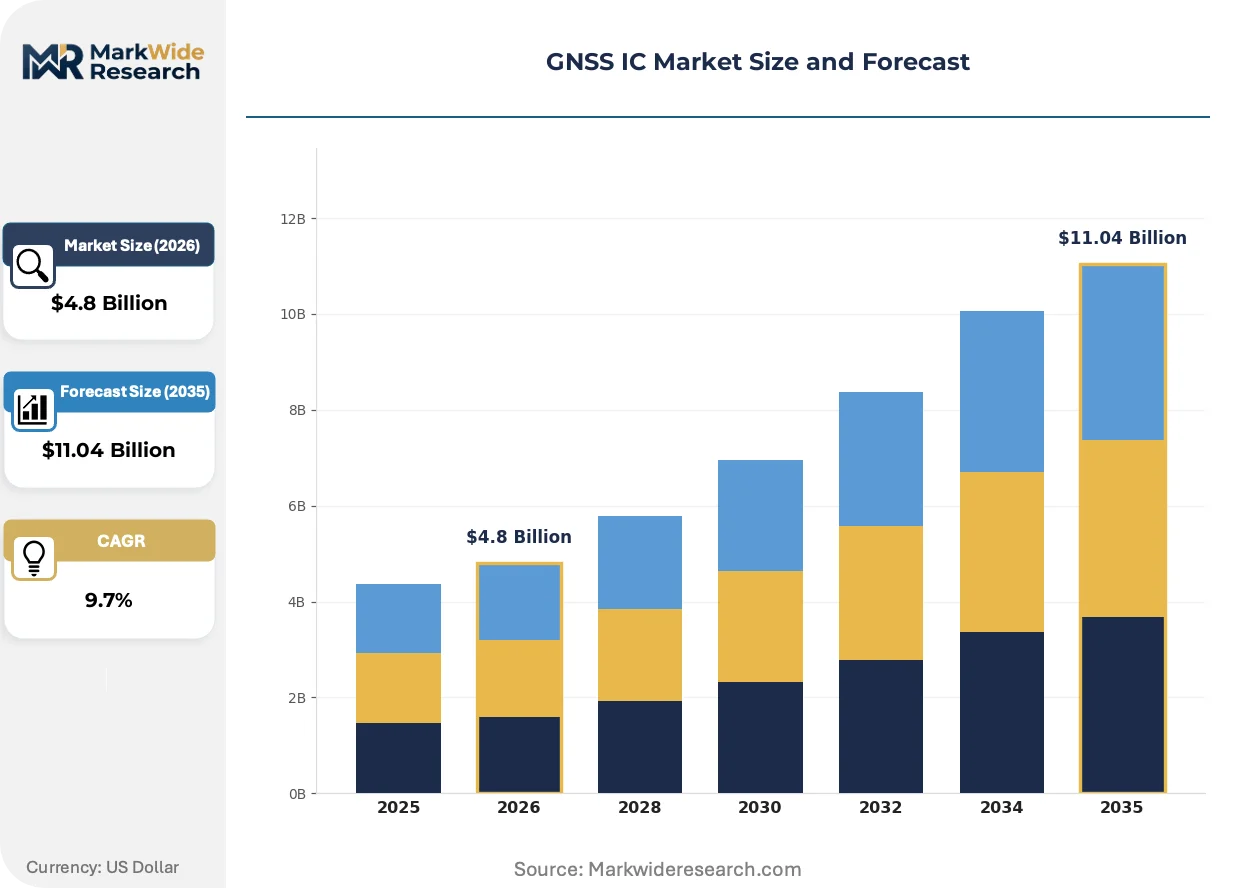
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Receiver, Transmitter, Module, Chipset End User: Aerospace, Automotive, Consumer Electronics, Industrial Application: Navigation, Surveying, Agriculture, Fleet Management Technology: GPS, GLONASS, Galileo, BeiDou |
| Companies Covered | Qualcomm Technologies, Inc., MediaTek Inc., STMicroelectronics N.V., Broadcom Inc., u-blox AG, Intel Corporation, Texas Instruments Inc., Trimble Inc., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS IC Market Shifts & Advancements
Open-source receiver firmware stacks are commoditizing baseband processing while specialized RF front-ends retain margin concentration. This separation is reshaping how vendors defend positioning in automotive and industrial tiers.
Software-defined GNSS baseband processing is decomposing traditional integrated chipset value pools. Automotive tier-1 suppliers are adopting configurable DSP cores for constellation flexibility. This decomposition enables faster signal algorithm updates without silicon respins, compressing legacy fixed-architecture vendor margins.
Europe's ETSI standards for Galileo signal authentication are mandating cryptographic verification in automotive safety systems. Germany's KBA type-approval processes now incorporate these requirements for autonomous driving platforms. Module suppliers are re-architecting secure element integration to satisfy Munich and Stuttgart procurement specifications.
Buyer concentration among automotive tier-1s is compressing negotiation cycles for GNSS module vendors. Discrete IC suppliers face bundling pressure from modem-integrated competitors in smartphone and telematics segments. Germany anchors this consolidation, with Bosch, Continental, and ZF Group consolidating multi-source positioning procurement under single-supplier frameworks.
GNSS IC Market Segmentation
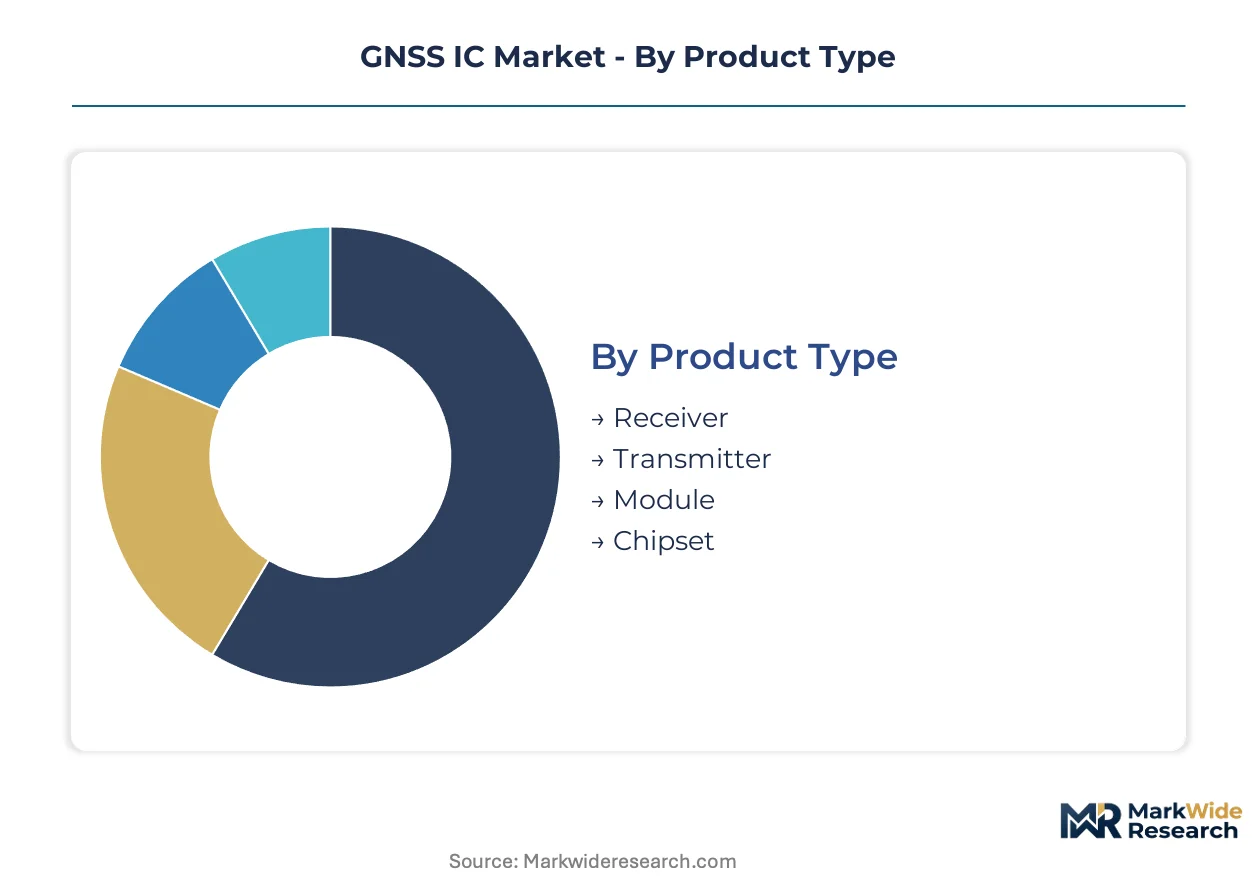
GNSS IC architectures fragment across RF integration levels and constellation support tiers, with margin pools concentrating where automotive safety certification or precision agriculture benchmarks command premium positioning. Understanding these segment boundaries clarifies where fabless designers capture value versus where module integrators dominate.
Product Type:
Margin pools concentrate in complete chipset solutions where baseband-RF integration meets automotive qualification requirements, while discrete receiver components face commoditization pressure from open-source firmware alternatives.
- Chipset:Integrated baseband processor, RF front-end, and embedded firmware on 40nm to 22nm CMOS nodes. Automotive tier-1 suppliers in Germany anchor procurement for AEC-Q100 qualified variants serving autonomous driving platforms.
- Module:Pre-certified positioning subsystems combining antenna, LNA, and receiver IC with shielding. Industrial IoT deployments in precision agriculture and drone navigation drive sub-meter accuracy specifications at premium price tiers.
- Receiver:Discrete RF-to-digital signal chains requiring external baseband processing.
- Transmitter:Specialized augmentation broadcast hardware for differential correction services.
The dominant share belongs to Chipset, while Module is closing the gap fastest.
End User:
Volume scales diverge sharply between billion-unit consumer electronics attach rates and thousand-unit automotive safety-critical procurements where qualification timelines stretch 18-24 months.
- Automotive:Safety-critical navigation modules for ADAS and autonomous driving systems. Germany's KBA type-approval processes mandate ETSI Galileo OSNMA authentication, compressing supplier qualification to tier-1s with Continental, Bosch, and ZF Group procurement frameworks.
- Consumer Electronics:Smartphone positioning stacks where modem-integrated solutions from Qualcomm Technologies displace discrete IC attach. FCC equipment authorization rules shape transmitter spurious emission compliance for US-bound devices.
- Industrial:Asset tracking, precision agriculture, and autonomous robotics requiring sub-meter accuracy.
- Aerospace:Aviation-certified receivers for commercial and unmanned aerial platforms.
Consumer Electronics commands unit volume leadership, though Automotive delivers the steepest expansion trajectory as telematics mandates proliferate.
Application:
Performance benchmarks stratify by accuracy requirements, with centimeter-level specifications in surveying and precision agriculture supporting 3-5x price multiples over standard navigation tiers.
- Fleet Management:Commercial vehicle telematics for regulatory compliance and route optimization. ELD mandates across North American and European commercial fleets are expanding hardware refresh cycles for multi-constellation modules.
- Agriculture:Autosteering and variable-rate application systems requiring RTK-level precision. Japan's METI industrial policy promotes QZSS augmentation adoption, tightening procurement benchmarks for domestic equipment manufacturers.
- Navigation:Standard positioning for consumer and automotive mass-market applications.
- Surveying:Geodetic-grade receivers for construction and mapping professionals.
Navigation retains installed base dominance, while Fleet Management gains share most rapidly as commercial vehicle tracking mandates expand across jurisdictions.
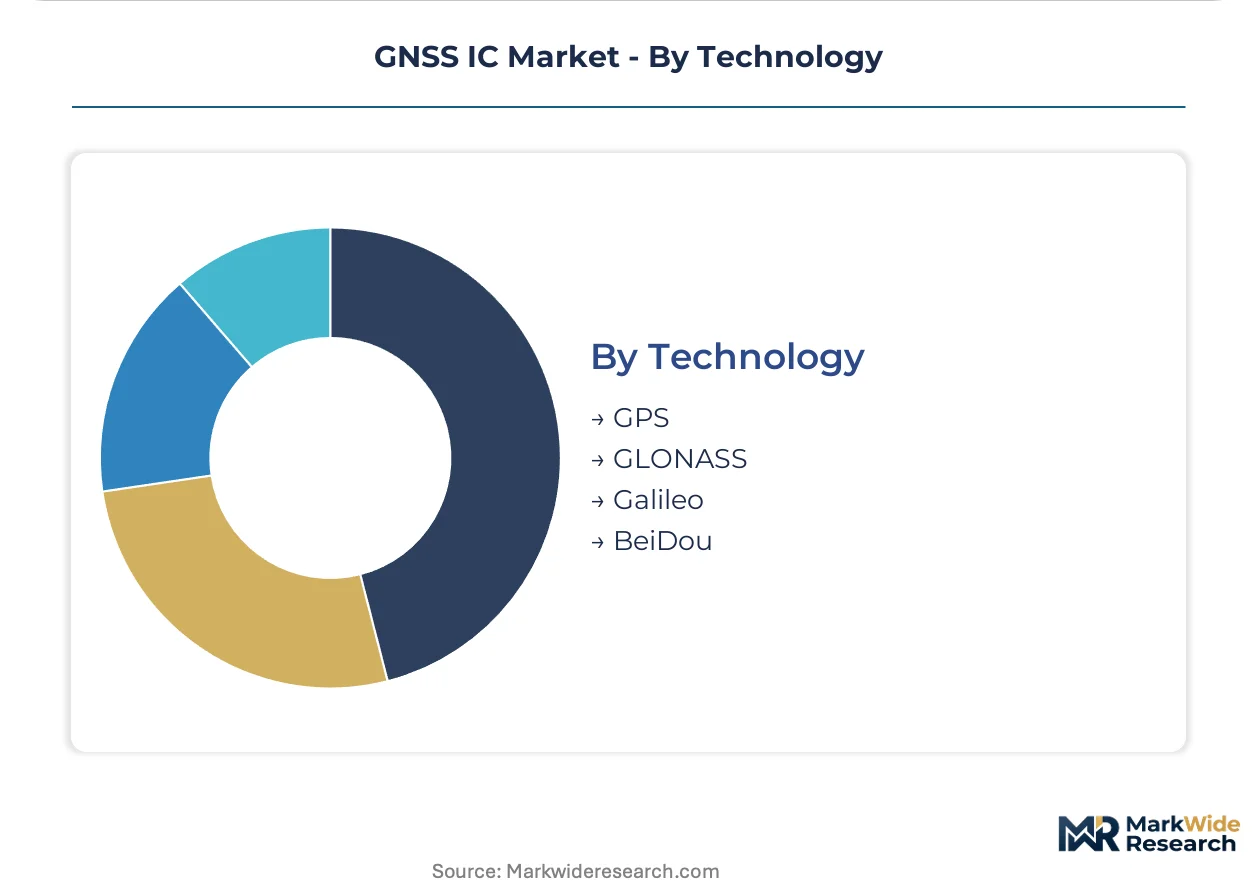
Technology:
Constellation support tiers now function as competitive segmentation, with dual-frequency L1/L5 architectures displacing legacy GPS-only designs in premium automotive and industrial tiers.
- GPS:Legacy L1 C/A code receivers face margin compression as multi-constellation support becomes baseline. Single-frequency variants persist in cost-constrained consumer tiers where BOM minimization outweighs accuracy requirements.
- Galileo:Europe's civil GNSS with Open Service Navigation Message Authentication enabling cryptographic verification. ETSI standards mandate Galileo reception for automotive safety systems, forcing receiver architecture updates for Germany-targeted platforms.
- BeiDou:China's completed global constellation with B1I/B1C and B2a signals.
- GLONASS:Russia's FDMA-based system with renewed satellite deployment.
GPS maintains broadest compatibility, while Galileo climbs fastest as European regulatory mandates harden authentication requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tier-1 suppliers in Germany pay premium pricing for AEC-Q100 qualified chipsets, while smartphone manufacturers in China drive volume at compressed margins. Fleet operators in the United States absorb mid-tier pricing for ELD-compliant telematics modules. Precision agriculture buyers in Japan accept the highest per-unit costs for centimeter-level augmentation systems.
United States
FCC equipment authorization rules govern transmitter spurious emission limits for GNSS modules bound for commercial vehicle telematics. The ELD mandate for interstate trucking fleets sustains hardware refresh demand across North American logistics networks. Silicon Valley chip designers and Detroit automotive suppliers coordinate on next-generation positioning stacks for autonomous driving platforms.
Germany
KBA type-approval processes now incorporate ETSI Galileo OSNMA authentication requirements for safety-critical navigation systems. Bosch, Continental, and ZF Group consolidate multi-source positioning procurement under single-supplier qualification frameworks. Munich and Stuttgart anchor the continent's densest concentration of automotive-grade GNSS module sourcing.
China
BeiDou-3 constellation completion drives domestic chipset substitution in smartphone and automotive applications. MIIT standards shape receiver performance benchmarks for industrial IoT deployments. Shenzhen and Shanghai fabrication clusters specialize in cost-optimized multi-constellation receiver designs for export markets.
Japan
METI industrial policy promotes QZSS centimeter-level augmentation adoption through precision agriculture equipment subsidies. Domestic farm machinery manufacturers face tightening procurement benchmarks for RTK-capable positioning modules. Nagoya industrial corridors concentrate autonomous robotics development requiring tight GNSS-IMU fusion.
South Korea
Seoul-based electronics conglomerates integrate multi-constellation positioning into smartphone and wearable device roadmaps. The country's national space agency advances KASS augmentation service deployment for aviation and maritime safety applications. Pangyo Techno Valley hosts fabless GNSS design houses targeting automotive lidar fusion applications.
GNSS IC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Modem-integrated specialists dominate smartphone positioning stacks through baseband consolidation, while discrete IC vendors defend automotive and industrial tiers through qualification barriers. Three archetypes define the landscape: integrated platform providers, automotive-grade specialists, and precision-focused module vendors. Consolidation pressure intensifies as tier-1 automotive suppliers reduce qualified vendor lists, and smartphone OEMs eliminate discrete GNSS attach opportunities.
Within the integrated platform tier, Qualcomm Technologies and MediaTek exemplify modem-centric positioning strategies that compress standalone IC economics. STMicroelectronics occupies a distinctive position as an automotive-grade qualification leader through its Teseo platform lineage. u-blox AG anchors the precision module segment where sub-meter accuracy commands pricing separation from consumer tiers. These three representations illustrate how competitive boundaries harden around certification regimes rather than raw technical performance.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| MediaTek Inc. |
| STMicroelectronics N.V. |
| Broadcom Inc. |
| u-blox AG |
| Intel Corporation |
| Texas Instruments Inc. |
| Trimble Inc. |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Wafer-scale CMOS economics at 22nm nodes compress marginal costs for fabless GNSS designers while concentrating pricing power with automotive tier-1s capable of AEC-Q100 qualification. This scale asymmetry forces discrete IC vendors into defensive positioning against modem-integrated competitors.
Pricing Analysis
ETSI Galileo OSNMA mandates dictate the pricing tier structure across automotive safety-critical modules. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 certified chipsets for autonomous driving from industrial IoT modules and consumer-grade receivers. Price differentiation centers on certification grade and volume scale, with Germany's KBA type-approval processes adding compliance premiums. Cost compression in smartphone positioning stacks is intensifying because Qualcomm's modem-integrated solutions displace discrete attach opportunities. Consumer electronics OEMs exhibit highest price sensitivity, while precision agriculture buyers in Japan accept premium positioning for centimeter-level augmentation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound lead time volatility for SAW filter and LNA shipments from compound semiconductor foundries. Geographic supply concentration centers on Taiwan for RF front-end fabrication, South Korea for advanced CMOS nodes, and Germany for automotive module integration. Raw material dependencies include high-purity silicon substrates, gallium arsenide for LNAs, and ceramic packaging materials. Single-source vulnerability in SAW filter supply creates procurement risk for fabless designers. Distribution runs through direct OEM qualification frameworks rather than open channel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive tier-1 consolidation in Germany has shifted procurement leverage toward Bosch, Continental, and ZF Group, compressing qualified vendor lists and extending negotiation cycles for GNSS module suppliers.
For Market Incumbents: Secure AEC-Q100 certification renewals ahead of ETSI Galileo OSNMA enforcement timelines to defend module attach rates against modem-integrated competitors. Deepen backward integration into RF front-end design to mitigate SAW filter supply concentration. Prioritize R&D investment in sensor fusion architectures where tight GNSS-IMU coupling creates defensible product categories. For New Entrants and Emerging Players: FCC equipment authorization fast-track services offer service-layer entry points without silicon fabrication exposure. Industrial IoT asset tracking presents the most penetrable white-space segment where sub-meter accuracy commands pricing separation from consumer tiers. Precision agriculture in Japan offers geographic entry through METI-subsidized QZSS augmentation adoption. A compliance-focused go-to-market angle bypasses direct competition with Qualcomm's smartphone dominance. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-grade specialists with established tier-1 relationships over consumer-exposed fabless designers. Long-term viability over the next decade hinges on constellation modernization agility and secure element integration capabilities. Acquisition targets should demonstrate firmware update velocity without silicon respins. The signal to watch is KBA type-approval timeline compression as ETSI mandates harden.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Certification Investment | Unlocks procurement frameworks with Germany's automotive tier-1 suppliers. |
| Dual-Frequency L1/L5 Architecture Migration | Addresses ETSI mandates while displacing legacy single-band economics. |
| Secure Element Integration | Satisfies Munich and Stuttgart specifications for cryptographic verification. |
| Sensor Fusion Partnership | Enables autonomous robotics categories through tight GNSS-IMU coupling. |
| QZSS Augmentation Service Launch | Captures METI-subsidized precision agriculture demand in Japan. |
Research Methodology
A standing panel of automotive platform engineers, RF IC design leads, fleet telematics procurement managers, and precision agriculture equipment manufacturers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, ETSI standardization documents, KBA type-approval filings, and METI industrial policy directives. Bottom-up triangulation across module shipment data and top-down reconciliation against semiconductor foundry capacity disclosures anchored value estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture tier, constellation support level, end-use application, and regional regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated automotive telematics mandate expansion timelines and smartphone modem integration penetration curves.
Underlying assumptions cover ETSI Galileo OSNMA enforcement adherence, AEC-Q100 qualification timeline stability, and SAW filter supply continuity, with deviation risk concentrated in constellation modernization schedule slippage and automotive OEM vendor consolidation acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Americas Analog IC Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Global 3D Ics Market