
 Comparator IC Market | 2026-2036
Comparator IC Market Size, Share, and Industry Trends Forecast 2026-2036
Comparator IC Market Analytics
Modular voltage-reference bundling with comparator cores is realigning procurement patterns across industrial automation buyers. Texas Instruments leverages its analog portfolio depth to sustain bundled solution sales. Infineon Technologies anchors automotive-grade comparator supply through its power electronics channel control. STMicroelectronics differentiates via CMOS process leadership in low-power configurations.
A comparator integrated circuit is an active electronic device that accepts two analog input voltages and produces a digital output indicating which input is higher, typically operating with microsecond propagation delays and millivolt input offset specifications. It serves as a fundamental signal-conditioning element in power management, sensor interfaces, and timing circuits across industrial and consumer systems. High-speed comparator variants capture margin pools in telecommunications infrastructure where picosecond response thresholds determine system performance. Voltage comparator segments dominate unit volume in automotive battery management and motor control applications. CMOS technology leads installation scale, while bipolar processes retain niche positions in high-temperature industrial environments.
The US FCC and FDA shape electromagnetic compatibility and medical device signal-path requirements that comparator designs must satisfy for market access. China's SAMR enforces GB standards on energy efficiency and semiconductor reliability that directly constrain product qualification thresholds. Japan's METI JIS standards and South Korea's MFDS medical device regulations add further certification layers for suppliers targeting precision instrumentation segments. Stakeholders must monitor evolving automotive functional-safety standards and regional carbon-efficiency mandates to align R&D roadmaps with compliance timelines.
Market Dynamics
Automotive electrification is compressing comparator qualification timelines as battery management systems demand sub-millivolt precision across temperature extremes. Tier-1 suppliers now bundle voltage-reference cores with comparator die to reduce BOM complexity and thermal drift.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's GB standards for energy efficiency are forcing industrial motor drives to adopt precision voltage comparators for real-time power factor correction.
- Telecommunications Infrastructure:5G base station deployments require picosecond-response comparators for clock recovery circuits, pulling high-speed variants into volume production.
- East Asian Manufacturing Clusters:Concentrated semiconductor fabrication in South Korea, Taiwan, and Japan creates localized demand spikes for automotive-grade comparator die.
Market Restraints
- Silicon Wafer Cost Volatility:300mm wafer spot pricing swings constrain gross margins for commodity comparator producers serving consumer electronics.
- Single-Source Bipolar Capacity:High-temperature industrial comparators rely on legacy bipolar processes concentrated at two foundry locations, creating supply vulnerability.
- Functional Safety Certification Burden:ISO 26262 ASIL compliance for automotive comparators extends development cycles and locks out mid-tier suppliers.
Strategic Opportunities
- India Industrial Automation:PLI scheme incentives for domestic electronics manufacturing are opening procurement channels for precision comparators in process control.
- Photovoltaic String Monitoring:Arc-fault detection mandates in residential solar installations are creating new demand for isolated comparator arrays.
- AI Inference at Edge:Comparator-based analog compute primitives are converging with machine learning accelerators to enable sub-microwatt pattern recognition.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Comparator architectures requiring precision layout expertise face recruitment bottlenecks in analog semiconductor hubs.
- Legacy System Integration Friction:Replacing electromechanical relays with solid-state comparators in existing industrial control panels demands retrofit engineering services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Comparator IC Market |
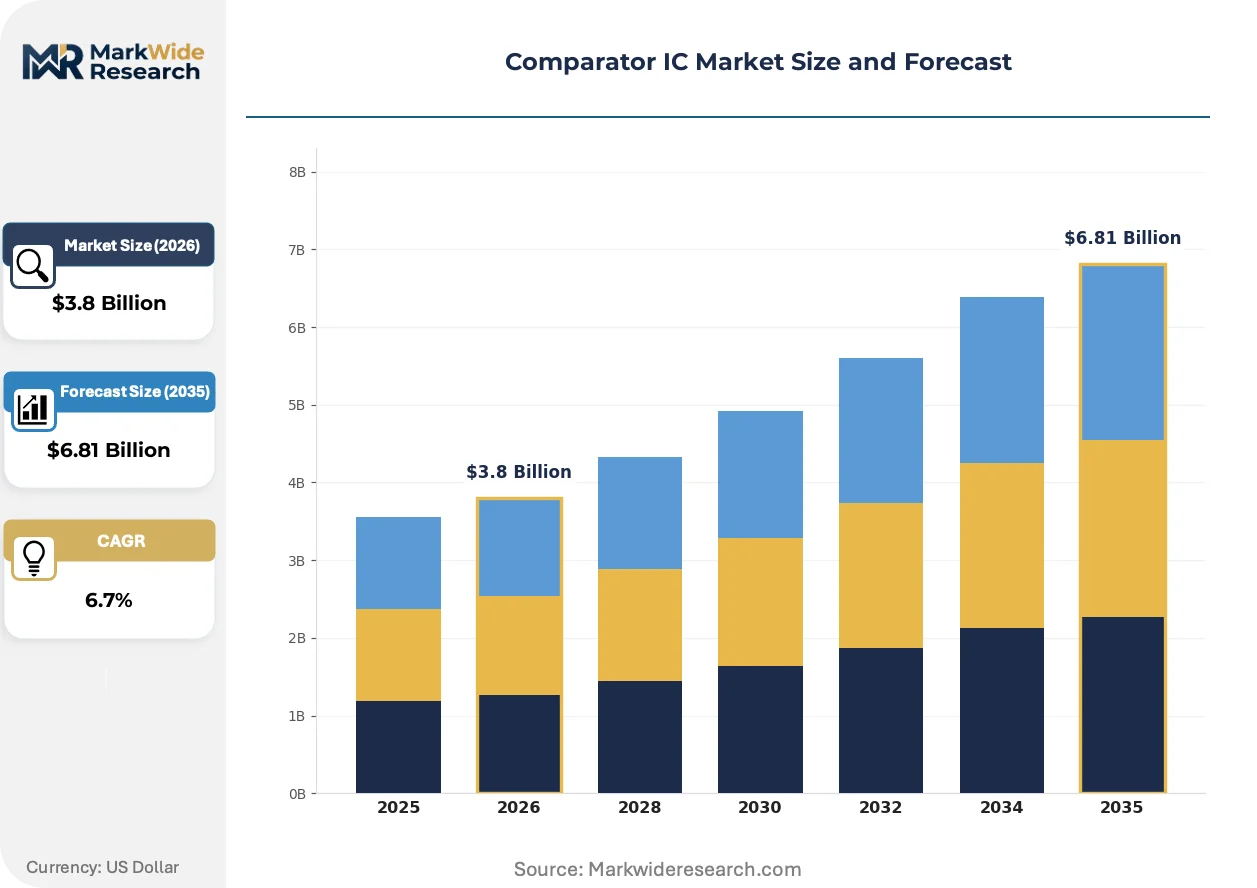
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Comparator, Voltage Comparator, Window Comparator, High-Speed Comparator Technology: CMOS, Bipolar, Hybrid, Low-Power End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Installation: Through-Hole, Surface Mount, Chip-On-Board, Direct Chip Attachment |
| Companies Covered | onsemi, Renesas Electronics, Texas Instruments, Nexperia, NXP Semiconductors, Analog Devices, Microchip Technology, Infineon Technologies, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Comparator IC Market Evolving Landscape
Comparator architectures are bifurcating between ultra-low-power IoT-optimized cores and high-voltage automotive-qualified die, with process technology choices determining accessible market segments rather than feature differentiation alone.
Chopper-stabilized comparator topologies are converging with sub-threshold CMOS design techniques to eliminate offset voltage drift in battery-powered sensor nodes. Wearable device manufacturers in Japan and South Korea are adopting these configurations for continuous glucose monitoring patches. The structural consequence is compressing addressable market share for traditional auto-zero comparator architectures in sub-1.8V applications.
EU F-Gas Regulation phase-down schedules are pressuring industrial refrigeration OEMs to adopt comparator-driven leak detection circuits with tighter threshold accuracy. This policy is forcing comparator suppliers to recalibrate noise specifications for harsh electromagnetic environments found in compressor housings. German and Italian HVAC manufacturers are responding by qualifying automotive-grade comparators originally developed for electric vehicle thermal management.
Consolidated procurement by East Asian contract manufacturers is displacing fragmented distributor relationships for standard comparator SKUs. Foxconn and Pegatron are now sourcing die-level comparators directly from foundry partners, bypassing traditional semiconductor distributors for high-volume consumer electronics. This channel compression is most visible in smartphone and tablet production lines across Shenzhen and Taipei manufacturing corridors.
Comparator IC Market Segmentation
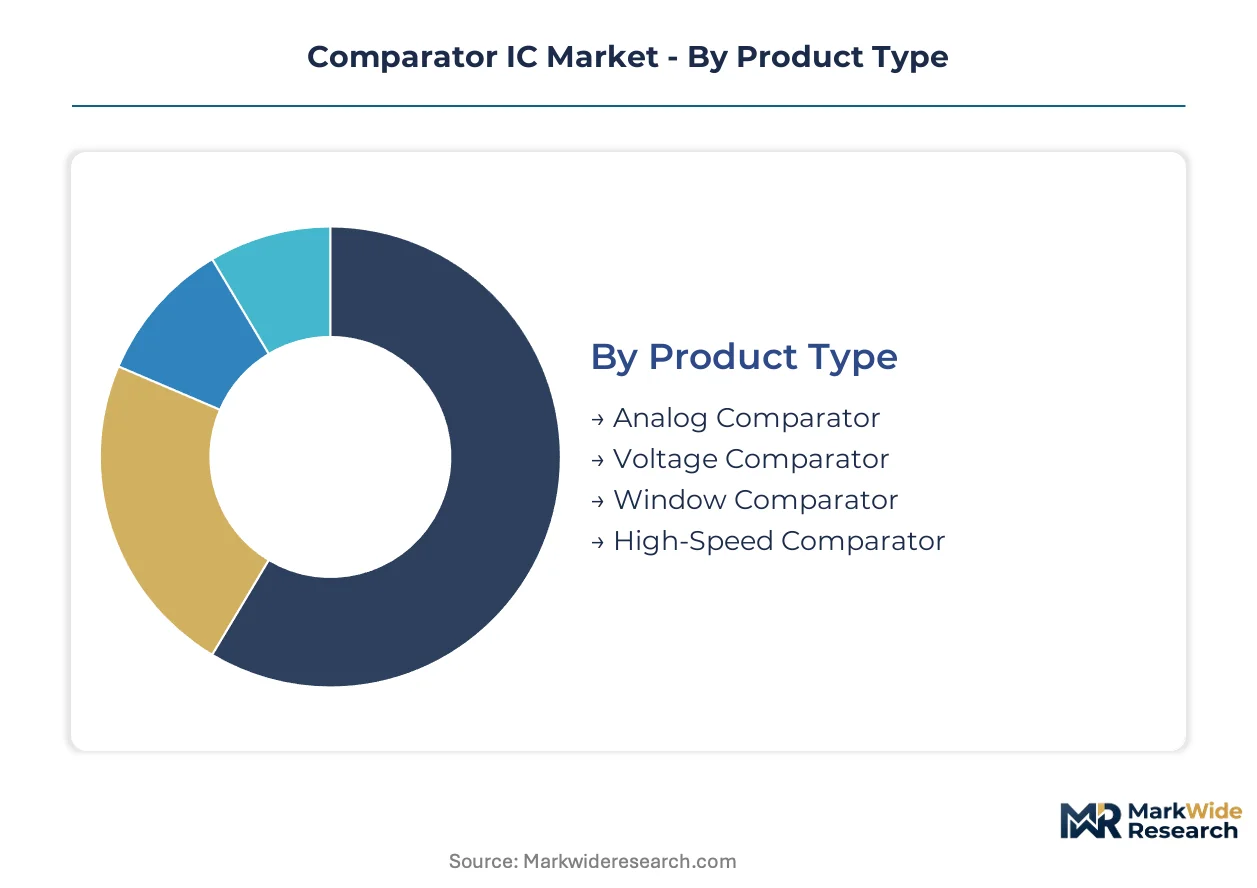
Comparator IC architectures diverge sharply across voltage thresholds, propagation speeds, and thermal envelopes. Product positioning hinges on matching process technology to application-specific precision requirements rather than feature stacking.
Product Type:
Voltage threshold and response latency specifications determine accessible application tiers and pricing power.
- Analog Comparator:Continuous-output architectures without internal hysteresis dominate legacy industrial control retrofit projects. Demand concentrates in German machine tool upgrades where replacing electromechanical relays requires signal-compatible drop-in solutions.
- Voltage Comparator:Discrete-threshold detection cores with millivolt precision anchor battery management systems in electric vehicles. South Korean and Japanese automotive Tier-1s specify these for cell balancing circuits where sub-millivolt accuracy prevents thermal runaway.
- Window Comparator:Dual-threshold configurations with built-in hysteresis simplify overvoltage/undervoltage protection logic. Medical device manufacturers in Switzerland and the United States specify these for infusion pump safety interlocks.
- High-Speed Comparator:Picosecond propagation variants serve clock recovery and signal integrity applications in 5G base stations. Telecommunications infrastructure deployments in Taiwan and South Korea pull these into volume production.
Voltage Comparator leads on scale; High-Speed Comparator leads on momentum.
Technology:
Process node selection locks suppliers into specific thermal, voltage, and cost envelopes.
- CMOS:Sub-micron lithography enables sub-microamp quiescent current for wearable sensor nodes. Japanese continuous glucose monitoring patch manufacturers specify CMOS comparators for 1.8V operation with nanoamp standby draw.
- Bipolar:Junction-isolated structures retain sub-5-microvolt offset stability across −55°C to +125°C extremes. High-temperature industrial applications in Texas and Alberta oilfield equipment specify bipolar die for flameproof instrumentation.
- Hybrid:BiCMOS process combinations merge CMOS density with bipolar analog precision. Aerospace signal conditioning in France and Italy specifies these for satellite power distribution units.
- Low-Power:Sub-threshold design techniques with chopper-stabilized topologies eliminate drift in energy-harvesting sensor networks. Smart building automation in Singapore and Dubai specifies these for battery-less environmental monitors.
CMOS dominates unit volume; Low-Power expands most quickly as IoT endpoint proliferation accelerates.
End User:
Application-specific certification requirements and procurement scale shape supplier prioritization.
- Consumer Electronics:High-volume, cost-optimized specifications for smartphone and tablet power management. Foxconn and Pegatron procurement in Shenzhen and Taipei corridors bypass traditional distribution for die-level sourcing.
- Automotive:ISO 26262 ASIL-compliant variants with AEC-Q100 qualification for battery management and motor control. China's MIIT dual carbon mandates tighten precision requirements for power factor correction circuits.
- Telecommunications:Picosecond-response specifications for 5G clock recovery and optical signal conditioning. Base station deployments across South Korea and Taiwan create localized demand concentration.
- Industrial Automation:Harsh-environment specifications with extended temperature ranges and EMI immunity. India's PLI scheme incentives open procurement channels for process control equipment in Gujarat and Tamil Nadu manufacturing corridors.
Automotive commands premium pricing; Industrial Automation offers the steepest expansion trajectory as factory digitization accelerates.
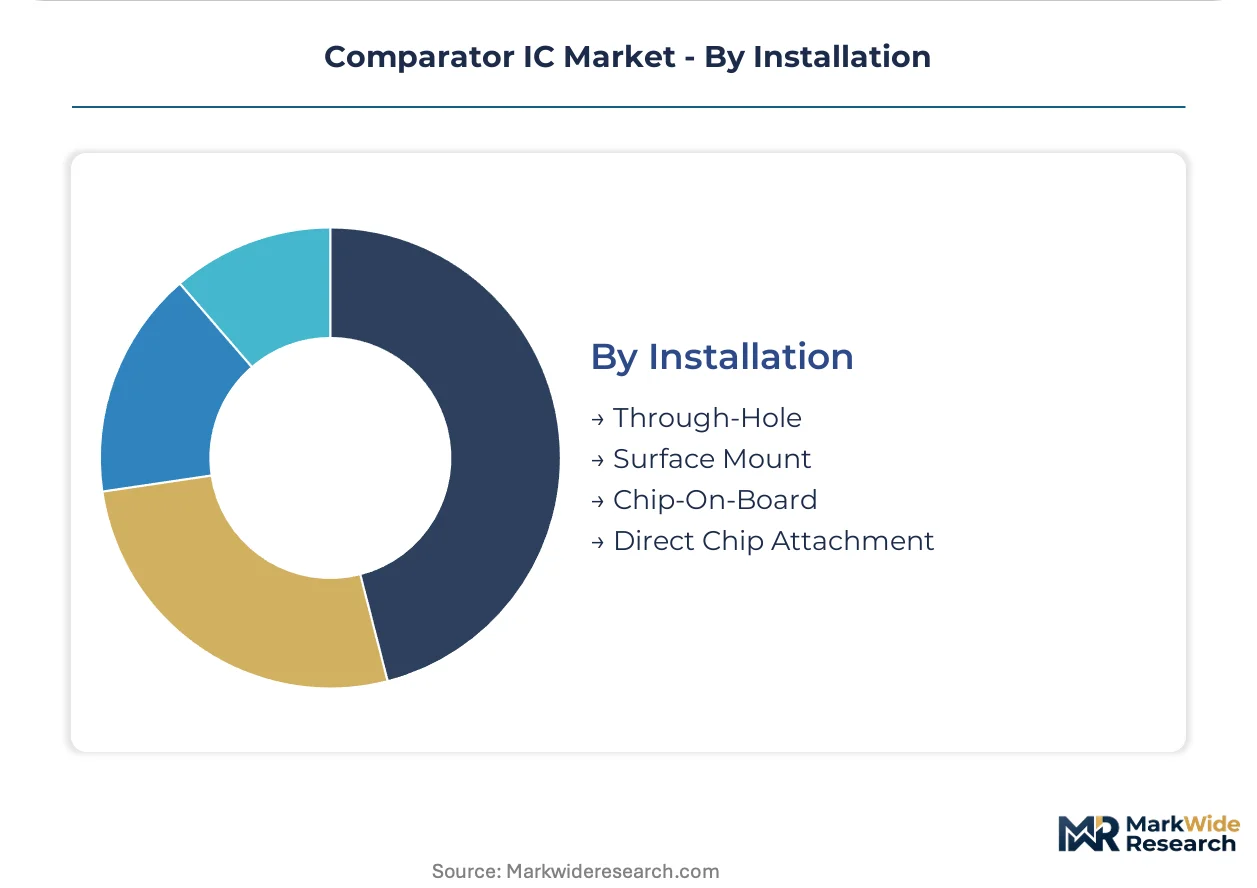
Installation:
Packaging format determines thermal performance, board space, and assembly automation compatibility.
- Through-Hole:Leaded packages for legacy equipment repair and high-reliability military applications. Existing industrial control panels in the United States and Germany retain through-hole comparators for field serviceability.
- Surface Mount:Standard SOT and QFN packages for high-density consumer and automotive electronics. South Korean memory module manufacturers specify these for voltage monitoring in DDR5 DIMMs.
- Chip-On-Board:Bare die attachment for ultra-compact wearable and implantable medical devices. Japanese hearing aid manufacturers specify COB comparators for cochlear implant signal processing.
- Direct Chip Attachment:Flip-chip and copper-pillar interconnects for high-frequency telecommunications modules. 5G mmWave beamforming arrays in Taiwan specify DCA for minimized parasitic inductance.
Surface Mount leads on scale; Direct Chip Attachment climbs the fastest as millimeter-wave deployment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision voltage comparator manufacturing originated in Japanese and American semiconductor fabs during the 1970s analog revolution. East Asian fabrication clusters now concentrate the bulk of automotive-grade die production. Regional regulatory divergence around carbon efficiency and functional safety is fragmenting qualification requirements.
United States
Telecommunications infrastructure and medical device manufacturers drive precision comparator procurement. The FDA enforces electromagnetic compatibility requirements for signal-path components in infusion pumps and diagnostic equipment. Texas and California host design centers serving 5G base station and aerospace applications.
Germany
Industrial automation retrofit projects and automotive Tier-1 supply chains absorb high-temperature comparator variants. The KBA coordinates with EU F-Gas Regulation enforcement to mandate leak detection circuits in refrigeration systems. Bavarian machine tool manufacturers specify bipolar comparators for flameproof oilfield instrumentation.
China
Battery management system production for electric vehicles dominates voltage comparator volume demand. MIIT dual carbon mandates and GB energy efficiency standards tighten precision requirements for industrial motor drives. Semiconductor fabrication clusters in Shanghai and Shenzhen scale CMOS comparator die output for domestic automotive OEMs.
Japan
Wearable medical devices and continuous glucose monitoring patches propel ultra-low-power comparator adoption. METI JIS standards govern reliability specifications for precision instrumentation segments. Tokyo and Osaka manufacturing corridors specialize in sub-threshold CMOS chopper-stabilized architectures.
South Korea
Memory module voltage monitoring and 5G telecommunications infrastructure create dual demand streams. The MFDS regulates medical device signal-path components for domestic and export markets. Seoul and Busan fabrication hubs supply automotive-grade comparators to domestic battery manufacturers.
Comparator IC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and thermal performance specifications. The vendor base organizes into three tiers: broad-line analog portfolio holders, automotive-qualified specialists, and low-power CMOS-focused innovators. Two strategic moves dominate competitive positioning: foundry partnerships for bipolar process access and bundled voltage-reference solutions to reduce customer BOM complexity.
Within the broad-line analog tier, Texas Instruments and Analog Devices occupy positions spanning industrial automation through telecommunications infrastructure. STMicroelectronics anchors the European automotive-qualified segment with CMOS process leadership. Among Japanese precision specialists, Renesas Electronics exemplifies the low-power configuration archetype serving wearable medical applications.
| Leading Market Players |
|---|
| onsemi |
| Renesas Electronics |
| Texas Instruments |
| Nexperia |
| NXP Semiconductors |
| Analog Devices |
| Microchip Technology |
| Infineon Technologies |
| STMicroelectronics |
| Others |
Value Network & Pricing Analysis
Captive bipolar foundry partnerships anchor supply positions for high-temperature industrial comparators while simultaneously locking in premium pricing power against commodity CMOS alternatives. This integration choice concentrates margin capture among automotive-qualified specialists who control legacy process access, forcing mid-tier suppliers toward outsourced CMOS fabrication with corresponding price compression.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-certified, and consumer-economy levels separates comparator procurement into distinct margin pools. Price differentiation rests on ISO 26262 ASIL certification tier and foundry process geometry, with AEC-Q100 qualified die commanding substantial premiums over standard industrial variants. Cost compression in consumer-grade segments intensifies as Foxconn and Pegatron consolidate die-level procurement directly with foundries. Smartphone power management teams exhibit highest price sensitivity, while German automotive Tier-1s prioritize thermal stability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and telecommunications buyer demand, bypassing traditional semiconductor distribution. Geographic supply concentrates in Taiwan, South Korea, and Japan, with 300mm CMOS wafer output feeding consumer and automotive lines. Raw material dependencies include silicon wafers, copper pillar interconnects, and epoxy molding compounds for QFN packaging. Single-source bipolar capacity at legacy foundries creates supply vulnerability for high-temperature industrial applications. Distribution runs through consolidated East Asian contract manufacturers for standard SKUs, while specialized medical and aerospace variants retain distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Comparator IC Market functions as a stable compounder anchored by automotive electrification's insatiable demand for precision battery management components. Electrification mandates across major economies ensure sustained volume expansion regardless of consumer electronics cyclicality.
For Market Incumbents: Anchor automotive qualification pipelines through AEC-Q100 and ISO 26262 ASIL-D certification investments to defend against emerging CMOS specialists. Deepen backward integration into voltage-reference core production to reduce BOM complexity for Tier-1 customers. Lock foundry partnerships for bipolar process access before capacity constraints tighten. Channel control through bundled solutions protects margin position against price-aggressive entrants.
For New Entrants and Emerging Players: Launch via India's PLI scheme procurement channels targeting industrial automation retrofit projects in Gujarat and Tamil Nadu manufacturing corridors. Photovoltaic string monitoring for residential solar arc-fault detection offers penetrable white-space with lower certification barriers than automotive. Edge AI analog compute primitives represent an emerging application tier where sub-microwatt pattern recognition demands novel comparator architectures. Direct technical sales to smart building automation integrators bypasses entrenched distribution relationships.
For Investors and Strategic Acquirers: Roll-up economics work for automotive-qualified analog specialists because functional safety certification creates defensible moats that compound over multiple design cycles. Target acquisition profiles should emphasize CMOS process leadership in low-power configurations and existing AEC-Q100 qualified product lines. Long-term viability frames around the 5-10 year electrification investment cycle. The signal to watch is MIIT dual carbon mandate enforcement tightening, which accelerates precision comparator specification in Chinese industrial motor drives.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | AEC-Q100 and ISO 26262 ASIL qualification unlocks Tier-1 battery management procurement. |
| Voltage-Reference Core Integration | Bundled solutions reduce customer BOM complexity and thermal drift in precision applications. |
| Bipolar Foundry Partnership | Legacy process access secures high-temperature industrial supply positions against CMOS displacement. |
| India PLI Scheme Channel Development | Domestic electronics manufacturing incentives open process control procurement corridors. |
| Chopper-Stabilized Sub-Threshold R&D | Eliminating offset voltage drift captures wearable medical device specification in Japan and South Korea. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and South Korea, with primary inputs from each comparator IC manufacturing cluster. The analysis combines structured interviews with analog semiconductor design leads, automotive Tier-1 procurement officers, industrial automation system integrators, and medical device biomedical engineers with secondary validation from SEC 10-K filings, MIIT GB standard documentation, FDA 510(k) device registrations, and foundry capacity announcements. Bottom-up die shipment estimates triangulate against top-down OEM procurement budget allocations.
Granularity-level modeling spans product type, process technology, end-use application, and installation format dimensions. Voltage comparator and high-speed comparator segments were modeled separately with distinct propagation delay and precision specifications. CMOS, bipolar, hybrid, and low-power technology categories incorporate foundry utilization rates and process node migration timelines. CAGRs derive from regression analysis against automotive production forecasts and telecommunications infrastructure deployment schedules. Wafer cost assumptions and certification timeline distributions inform margin trajectory projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silicon wafer spot pricing volatility and single-source bipolar foundry disruption scenarios. Automotive electrification policy acceleration or deceleration in China, Europe, and North America represents the dominant forecast revision driver. Periodic stress-testing of base assumptions against MIIT mandate enforcement patterns and EU F-Gas Regulation phase-down schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market