
 Global Patient Monitoring Market | 2026-2036
Global Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Monitoring Market Outlook
The EU Medical Device Regulation is rebalancing the cost-of-entry calculus for patient monitoring systems sold across European member states. Philips Healthcare leverages its integrated informatics platform to sustain software-hardware bundling advantages in intensive care settings. GE Healthcare anchors its position through deep manufacturing scale in multi-parameter bedside monitors for tier-one hospitals.
Patient monitoring encompasses devices and systems that measure, record, and transmit physiological parameters including heart rate, blood oxygen saturation, respiratory rate, and blood pressure through sensors, signal processors, and display interfaces; these systems serve the primary commercial purpose of enabling early clinical intervention by detecting physiological deterioration before critical events occur. Wearable devices represent the fastest-expanding product category as ambulatory and post-acute settings demand continuous data streams outside traditional hospital walls. Remote monitoring systems capture disproportionate margin pools by embedding recurring software subscription revenues alongside hardware deployment.
The FDA governs premarket clearance and post-market surveillance for patient monitoring devices in the United States, while the EMA coordinates notified body oversight under MDR requirements across Europe; Japan's PMDA enforces JIS standards for electromagnetic compatibility and measurement accuracy in connected monitoring equipment. These regulatory frameworks shape demand by mandating cybersecurity validation, interoperability standards, and clinical evidence thresholds that determine market access timelines. Stakeholders must monitor evolving software-as-a-medical-device classifications and data localization requirements that will determine competitive positioning in cloud-connected monitoring architectures.
Market Dynamics
Wireless telemetry architectures are consolidating bedside, ambulatory, and home-based monitoring into unified cloud platforms, compressing hardware margins while expanding recurring software revenue pools across hospital networks.
Growth Catalysts
- Reimbursement reform:Hospital systems in Germany and the United States expand remote patient monitoring programs to reduce readmission penalties under Medicare and Gesetzliche Krankenversicherung frameworks.
- Wearable sensor miniaturization:Ambulatory care settings demand continuous data streams outside traditional hospital walls, driving adoption of patch-based cardiac monitors and pulse oximetry devices.
- Cloud-based integration platforms:Tertiary care networks replace wired bedside systems with wireless telemetry that enables centralized command centers and predictive analytics workflows.
Market Restraints
- Semiconductor supply concentration:Custom ASICs and MEMS sensors for multi-parameter monitors face sourcing constraints from concentrated East Asian foundry capacity.
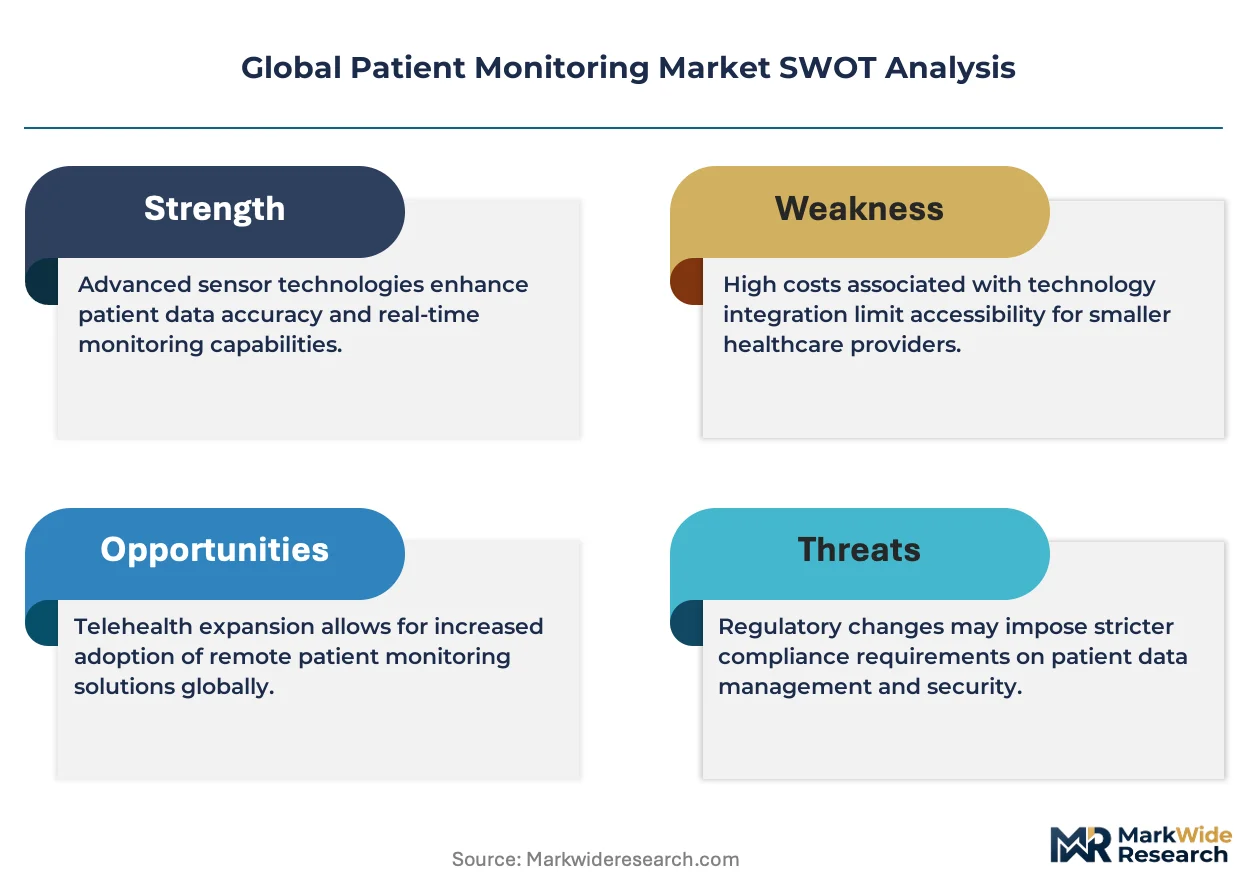
- MDR compliance friction:The EU Medical Device Regulation extends notified body review timelines and clinical evidence requirements for software-as-a-medical-device classifications.
- Interoperability fragmentation:Proprietary data protocols from incumbent manufacturers create integration barriers with third-party electronic health record systems.
Strategic Opportunities
- Post-acute care penetration:Skilled nursing facilities and home health agencies in Japan represent underpenetrated demand for continuous glucose monitoring and respiratory surveillance systems.
- AI-enabled early warning:Machine learning algorithms processing multi-parameter streams enable predictive deterioration alerts before critical events, creating premium pricing tiers.
- Subscription revenue models:Remote monitoring platforms embed recurring software fees alongside hardware deployment, capturing disproportionate margin pools from hospital system customers.
Industry Challenges
- Cybersecurity validation complexity:FDA premarket submissions for connected monitoring devices require documented threat modeling and penetration testing that extends development cycles.
- Biomedical engineering talent scarcity:Signal processing and clinical workflow design expertise concentrates in established medical device clusters, constraining new entrant scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Monitoring Market |
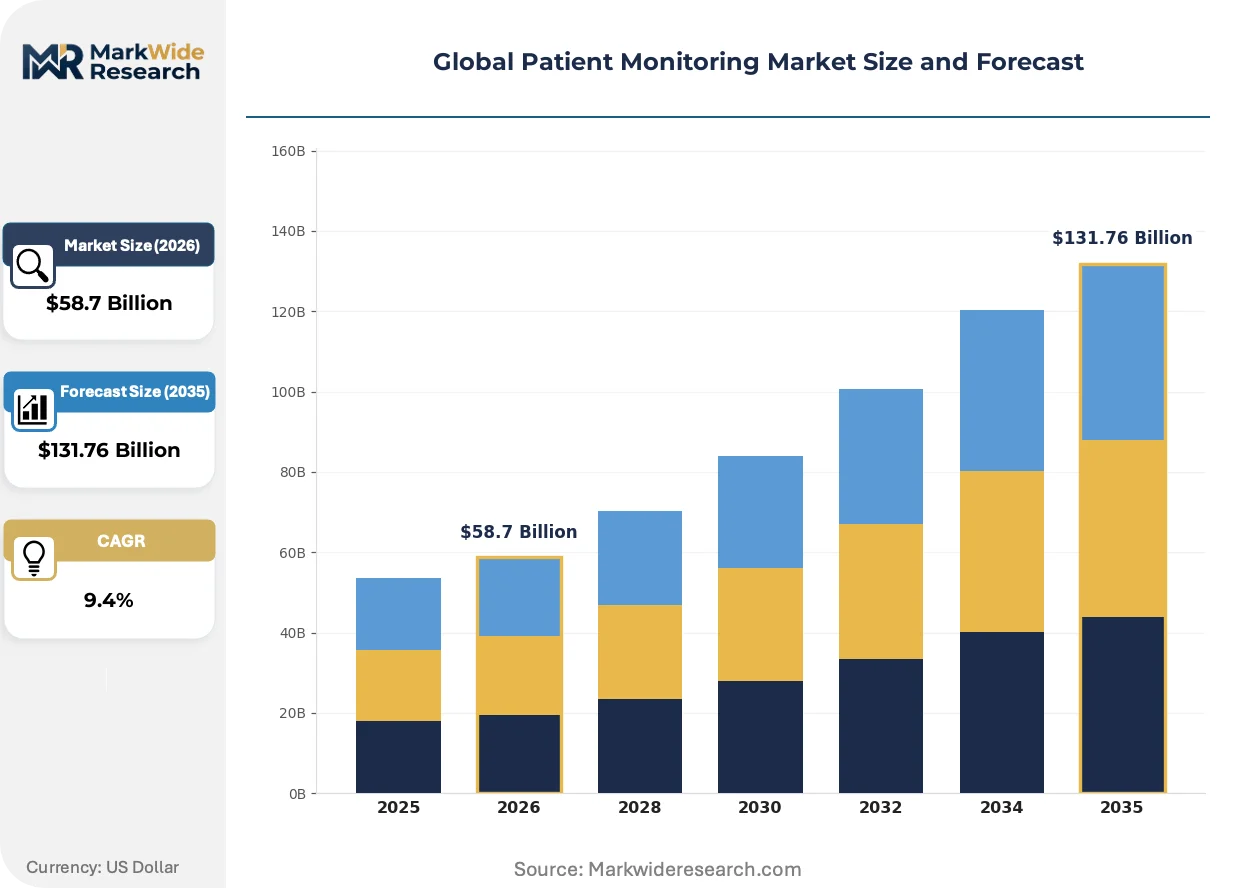
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Portable Monitors, Remote Monitoring Systems End User: Hospitals, Home Care, Ambulatory Surgical Centers, Diagnostic Centers Technology: Continuous Monitoring, Telemetry, Wireless Technology, Integration Platforms Application: Cardiac Monitoring, Respiratory Monitoring, Neurological Monitoring, Maternal Monitoring |
| Companies Covered | Philips Healthcare, GE Healthcare, Medtronic, Masimo, Mindray Medical, Abbott Laboratories, Siemens Healthineers, Drägerwerk AG & Co. KGaA, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Monitoring Market Strategic Shifts
Digital biomarker extraction and edge computing architectures are compressing the latency between physiological signal capture and clinical decision support, enabling real-time intervention protocols that were previously confined to intensive care units.
Edge computing nodes embedded within patient monitoring devices are consolidating signal processing, alarm generation, and local data storage functions that previously required separate bedside hardware and central server infrastructure. Hospital systems in the United States and Germany deploy these architectures to reduce network dependency and enable sub-second alarm response times. Philips Healthcare and GE Healthcare anchor their competitive positioning through proprietary edge platforms that lock in software-hardware bundling advantages.
The EU Medical Device Regulation and FDA's software-as-a-medical-device guidance are consolidating premarket clearance pathways for algorithm-driven monitoring features that previously escaped formal oversight. Manufacturers must submit clinical validation studies demonstrating equivalence to predicate devices or independent performance benchmarks. Wearable cardiac monitors and continuous glucose monitoring systems face the steepest compliance burdens given their direct therapeutic implications.
Hospital procurement departments are consolidating vendor relationships through enterprise-wide monitoring contracts that bundle hardware, software, and clinical support services under single-source agreements. Group purchasing organizations and integrated delivery networks in North America negotiate these arrangements, displacing decentralized department-level purchasing. This concentration rewards vendors with comprehensive informatics platforms and penalizes point-solution specialists lacking workflow integration depth.
Global Patient Monitoring Market Segmentation
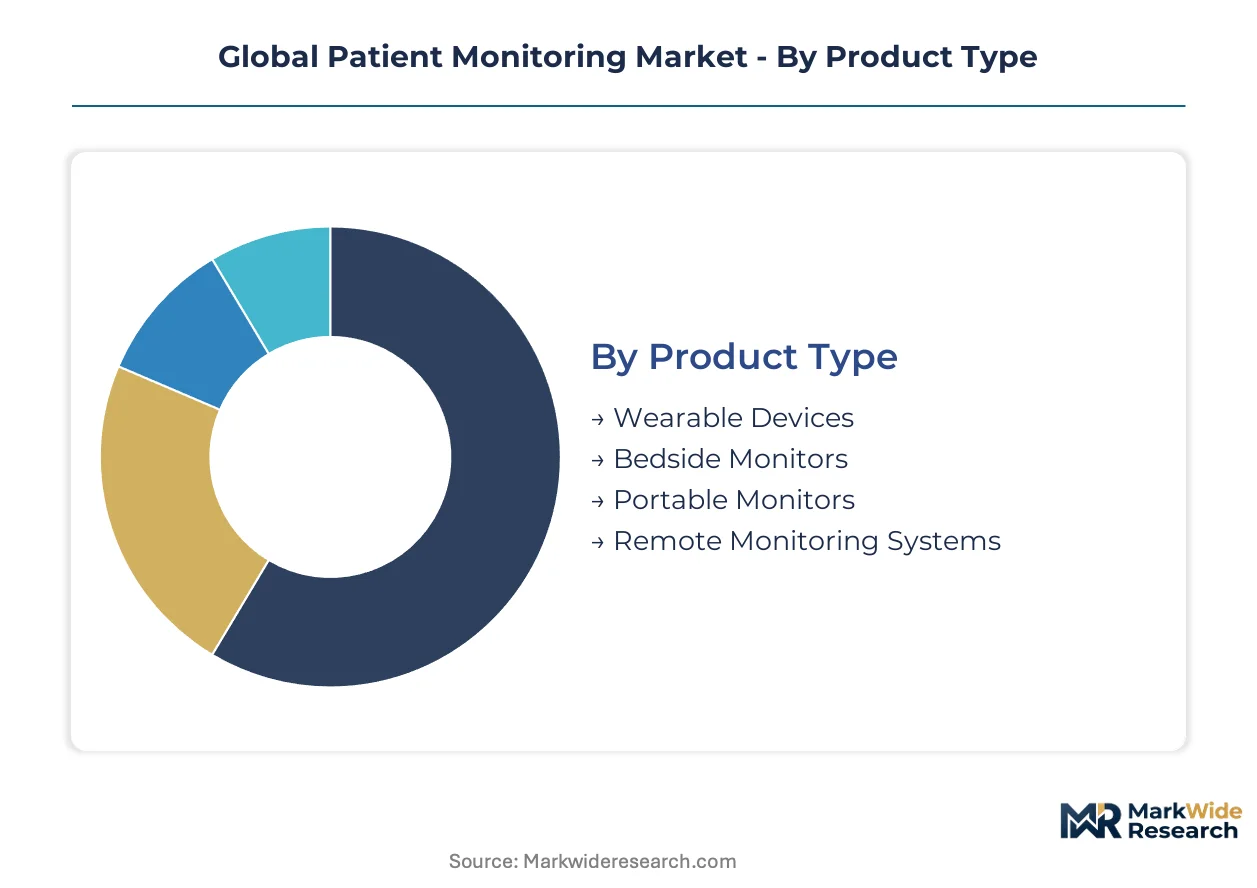
Patient monitoring segmentation reflects a fundamental split between embedded bedside infrastructure and distributed ambulatory systems. Procurement patterns diverge sharply across these boundaries, with hospital networks prioritizing integration depth while home care settings emphasize portability and connectivity.
Product Type:
Wearable devices and bedside monitors anchor opposite ends of the integration spectrum, with portable and remote systems bridging deployment contexts.
- Wearable Devices:Patch-based sensors and wrist-worn units capture electrocardiography, pulse oximetry, and accelerometry data through miniaturized MEMS arrays. Demand concentrates in German home care networks and United States post-acute programs seeking to extend monitoring beyond hospital walls under reimbursement reform. The segment climbs the fastest as ambulatory settings demand continuous physiological surveillance without tethered infrastructure.
- Bedside Monitors:Multi-parameter units integrate electrocardiogram, invasive blood pressure, and capnography modules through centralized signal processing architectures. Tertiary hospitals in the United States and Japan deploy these systems for intensive care and perioperative monitoring where sub-second alarm latency remains non-negotiable. Semiconductor sourcing constraints for custom ASICs limit supply elasticity in this category.
- Portable Monitors:Handheld or transportable units serve emergency departments and intra-hospital transfers with battery-powered operation and wireless telemetry backhaul.
- Remote Monitoring Systems:Cloud-integrated platforms aggregate data from distributed sensors, embedding software subscription revenues alongside hardware deployment.
Bedside monitors lead volumes today; wearable devices are gaining share fastest.
End User:
Customer type determines purchasing authority and contract structure, from enterprise-wide hospital agreements to individual consumer transactions.
- Hospitals:Integrated delivery networks in the United States and Germany negotiate multi-year enterprise contracts bundling hardware, software, and clinical support services. Group purchasing organizations consolidate vendor relationships, rewarding comprehensive informatics platforms over point solutions. Procurement departments prioritize interoperability with existing electronic health record systems.
- Home Care:Skilled nursing facilities and direct-to-consumer channels in Japan represent underpenetrated demand for continuous glucose monitoring and respiratory surveillance. Reimbursement pathways under Japan's public health insurance framework determine adoption velocity in this segment.
- Ambulatory Surgical Centers:Freestanding facilities prioritize compact, transportable monitors with rapid setup protocols for same-day discharge workflows.
- Diagnostic Centers:Imaging and cardiology clinics deploy specialized monitoring during stress testing and procedural sedation, requiring synchronized data export to picture archiving systems.
Hospitals dominate revenue concentration today; home care channels are expanding most quickly.
Technology:
Technical architecture determines regulatory pathway and margin structure, from hardware-centric continuous monitoring to software-heavy integration platforms.
- Continuous Monitoring:Real-time physiological surveillance through hardwired or wireless sensor arrays enables immediate clinical intervention for deteriorating patients. FDA premarket submissions for connected implementations require documented threat modeling and penetration testing that extends development cycles.
- Integration Platforms:Cloud-native architectures consolidate data from heterogeneous device fleets into centralized command centers with predictive analytics overlays. Hospital systems in Germany deploy these systems to reduce network dependency and enable centralized alarm management across distributed campuses.
- Telemetry:Radio-frequency transmission architectures replace wired bedside connections, enabling patient mobility during monitoring.
- Wireless Technology:Bluetooth Low Energy and proprietary protocols enable ambulatory data capture with smartphone or gateway relay to clinical repositories.
Continuous monitoring leads installed base today; integration platforms are climbing the fastest.
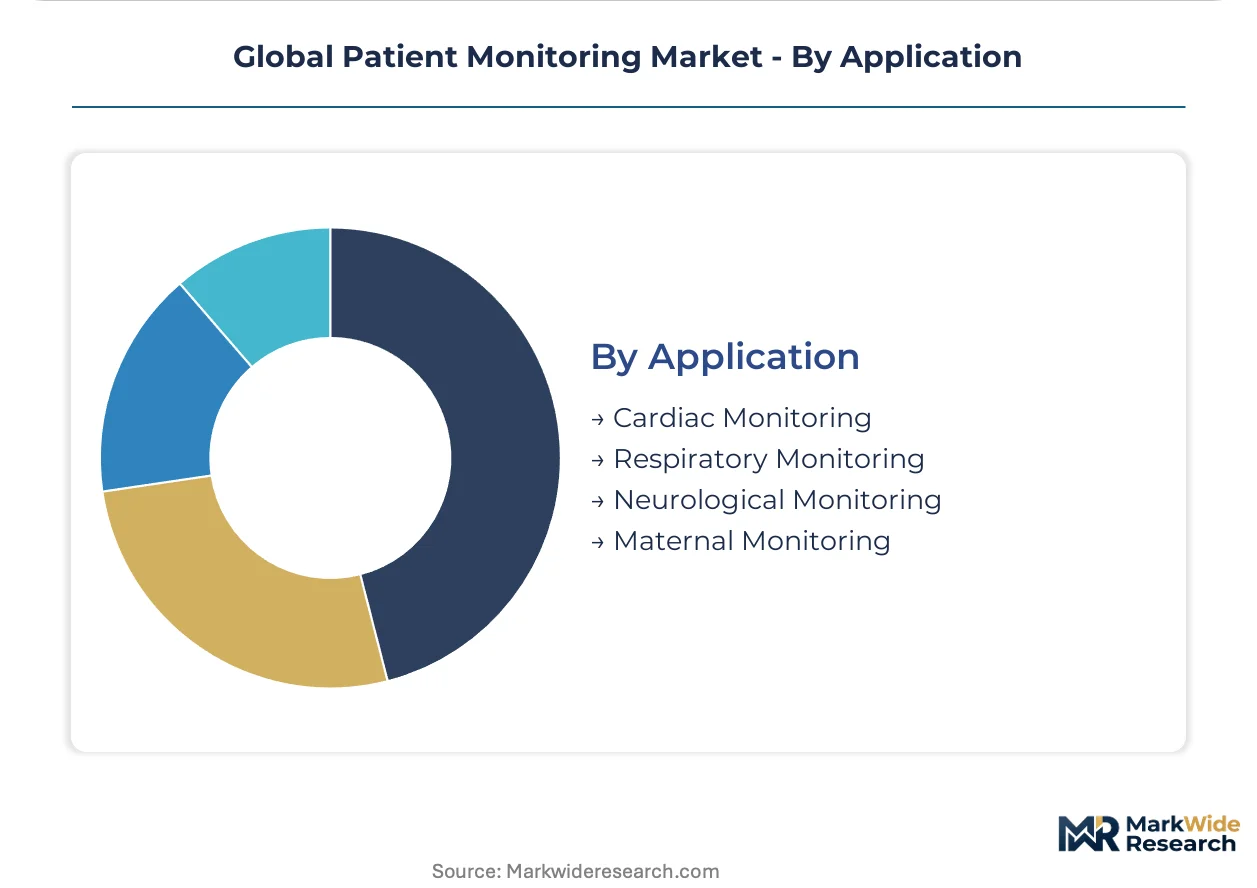
Application:
Clinical use case dictates sensor configuration, alarm thresholds, and regulatory classification intensity.
- Cardiac Monitoring:Electrocardiography and hemodynamic surveillance systems detect arrhythmias and ischemia through multi-lead configurations or patch-based single-lead alternatives. Wearable cardiac monitors face the steepest compliance burdens under FDA software-as-a-medical-device guidance and EU MDR requirements given direct therapeutic implications.
- Respiratory Monitoring:Capnography, pulse oximetry, and respiratory rate detection enable early warning for respiratory failure and opioid-induced depression. Demand concentrates in United States hospital systems seeking to reduce rapid response team activations through predictive deterioration algorithms.
- Neurological Monitoring:Electroencephalography and intracranial pressure systems serve neurocritical care units with specialized signal processing requirements.
- Maternal Monitoring:Fetal heart rate and uterine activity surveillance supports labor and delivery units with dual-patient safety considerations.
Cardiac monitoring leads procedure volumes today; respiratory monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The patient monitoring industry traces its commercial origins to post-war medical electronics development in the United States and Germany, where intensive care unit instrumentation first achieved scale during the 1960s and 1970s. These two markets remain the primary demand anchors today, though manufacturing and clinical deployment patterns have diffused across multiple continents.
United States
Hospital systems across the United States deploy remote patient monitoring programs to reduce Medicare readmission penalties under value-based reimbursement frameworks. The FDA governs premarket clearance and post-market surveillance for connected devices, mandating documented threat modeling and cybersecurity validation. The Boston-Cambridge corridor concentrates biomedical engineering talent and digital health venture activity, with tertiary care networks in this region pioneering predictive analytics integration.
Germany
German hospital systems expand ambulatory monitoring under Gesetzliche Krankenversicherung reimbursement reforms that incentivize post-acute surveillance outside traditional facilities. The EU Medical Device Regulation extends notified body review timelines and clinical evidence requirements for software-as-a-medical-device classifications. The Rhine-Ruhr industrial belt hosts manufacturing operations for multi-parameter bedside systems, with Siemens Healthineers anchoring production scale in this region.
Japan
Japan's aging demographic strain creates demand for continuous glucose monitoring and respiratory surveillance in skilled nursing facilities and home health channels. The PMDA enforces JIS standards for electromagnetic compatibility and measurement accuracy in connected monitoring equipment. The Kanto region surrounding Tokyo concentrates procurement authority for hospital networks deploying centralized command center architectures.
China
Chinese hospital networks modernize provincial tertiary care infrastructure with wireless telemetry replacing wired bedside systems in tier-one cities. The NMPA coordinates premarket approval pathways for imported and domestically manufactured monitoring devices. The Yangtze River Delta industrial corridor hosts contract manufacturing operations for MEMS sensors and signal processing components serving both domestic and export markets.
United Kingdom
NHS integrated care systems consolidate vendor relationships through enterprise-wide monitoring contracts bundling hardware, software, and clinical support services. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR requirements while establishing independent conformity assessment procedures. The Oxford-Cambridge-London golden triangle concentrates digital health research and early-stage commercialization of edge computing architectures for physiological surveillance.
Global Patient Monitoring Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with established hospital procurement relationships and integrated informatics platforms. Three to five manufacturers capture disproportionate revenue concentration in bedside and telemetry segments, while wearable and remote monitoring categories sustain more fragmented participation. Two strategic archetypes dominate: hardware-software bundlers leveraging workflow integration depth, and point-solution specialists seeking acquisition or partnership exits. Competitive moves concentrate on enterprise contract consolidation and AI-enabled feature differentiation.
Within the diversified conglomerate tier, Philips Healthcare and GE Healthcare exemplify hardware-software bundling strategies through proprietary edge computing platforms and comprehensive informatics integration. Medtronic occupies a position representing the therapeutic device-to-monitoring convergence archetype, leveraging cardiac and diabetes care footprints to embed continuous surveillance into chronic disease management workflows. These three anchors demonstrate how scale and integration depth determine competitive positioning in procurement environments favoring single-source agreements.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| Masimo |
| Mindray Medical |
| Abbott Laboratories |
| Siemens Healthineers |
| Drägerwerk AG & Co. KGaA |
| Nihon Kohden Corporation |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States and Germany anchor procurement volume and impose enterprise-wide contracting structures that compress hardware margins while elevating software subscription pricing power. Hospital systems negotiate multi-year bundled agreements that lock in recurring revenue streams for cloud-integrated monitoring platforms, shifting value capture from device manufacturers toward informatics vendors with workflow integration depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared intensive care systems from CE-marked general ward monitors and unregulated consumer wearables. Certification grade and after-sales service bundling drive price differentiation, with MDR compliance costs widening spreads between European and non-European sourced equipment. Pricing pressure stems from semiconductor sourcing constraints that elevate bill-of-materials costs for multi-parameter bedside units. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while tertiary ICU departments prioritize alarm latency performance over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian component hubs elevates landed costs for MEMS sensors and custom ASICs destined for United States and European assembly facilities. Manufacturing concentrates in China for consumer-grade wearables, Germany for multi-parameter bedside systems, and Japan for specialized neuromonitoring equipment. Custom silicon and medical-grade plastics constitute critical input dependencies. Single-source vulnerability around Taiwan semiconductor foundries poses structural risk to supply continuity. Distribution runs through group purchasing organizations and integrated delivery networks that consolidate vendor relationships under enterprise contracting frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient monitoring market functions as a stable compounder anchored by chronic disease prevalence and aging demographics that sustain replacement demand across hospital networks. Reimbursement reforms in major economies institutionalize remote monitoring as standard-of-care, embedding recurring revenue visibility for platform vendors.
For Market Incumbents: Extend software-hardware bundling advantages through proprietary edge computing architectures that lock hospital systems into integrated informatics ecosystems. Deepen backward integration into MEMS sensor design to insulate margin structures from Taiwan foundry concentration. Counter emerging entrant pressure in wearable cardiac monitoring by accelerating FDA software-as-a-medical-device submissions for algorithm-driven early warning features. For New Entrants and Emerging Players: Home health agencies in Japan represent the most penetrable channel for continuous glucose monitoring and respiratory surveillance systems given reimbursement pathway expansion under public health insurance frameworks. Skilled nursing facilities across Germany's ambulatory care networks offer secondary white-space opportunity for patch-based cardiac monitors. Pursue white-label partnerships with established medical device distributors to bypass hospital procurement committee barriers. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking point-solution specialists with AI-enabled algorithm portfolios or regional channel access. The market supports long-term viability through embedded subscription revenue models that generate predictable cash flows across replacement cycles. Monitor FDA software-as-a-medical-device enforcement patterns as inflection indicator for compliance cost trajectories affecting valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks access to German hospital procurement frameworks under Gesetzliche Krankenversicherung reforms. |
| Hospital System Partnership | Enterprise-wide contracts with United States integrated delivery networks consolidate vendor relationships and displace point solutions. |
| Software Companion Development | AI-enabled early warning algorithms embedded in cloud platforms create premium pricing tiers and subscription lock-in. |
| Reimbursement Strategy | Medicare remote monitoring codes in the United States and Japanese public health insurance pathways determine adoption velocity in home care channels. |
| FDA Submission | Premarket clearance for connected devices requires documented cybersecurity validation that extends development cycles but protects incumbent positioning. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster. The analysis combines structured interviews with hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, end user, technology, and application segments. The analytical framework models continuous monitoring versus integration platform adoption patterns, cardiac versus respiratory surveillance procedure volumes, and wearable versus bedside deployment contexts throughout the forecast period. CAGRs derive from installed base replacement cycles, reimbursement expansion trajectories, and semiconductor supply elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-a-medical-device enforcement intensity, EU MDR notified body capacity constraints, and Taiwan semiconductor foundry allocation priorities. Forecasts reflect assumptions around reimbursement stability and clinical evidence requirements without anticipating fundamental regulatory regime shifts. A model refresh is warranted upon material change in Medicare remote monitoring code valuations or Taiwan Strait logistics disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Asia-Pacific Patient Monitoring Market
Patient Monitoring
Middle East and Africa Cardiac Monitoring Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
United States Patient Monitoring Market