
 Ocular Hypertension Treatment Market | 2026-2036
Ocular Hypertension Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Hypertension Treatment Market Analytics
Buyer concentration among eye clinics is decoupling from traditional hospital networks as standalone ophthalmology centers expand their service capacity. Novartis AG sustains its position through R&D intensity in sustained-release formulations. AbbVie Inc. leverages its Allergan heritage in glaucoma therapy portfolios. Bausch Health Companies Inc. competes aggressively on pricing across generic prostaglandin analogues.
Ocular hypertension treatment encompasses pharmacological and procedural interventions that reduce intraocular pressure to prevent optic nerve damage, with topical beta-blockers, prostaglandin analogues, and carbonic anhydrase inhibitors serving as first-line therapies typically administered as once-daily eye drops. The primary purpose is halting progression to primary open-angle glaucoma, the leading cause of irreversible blindness worldwide. Topical medications dominate current prescription volumes due to established efficacy profiles and patient familiarity, though surgical treatments and laser therapy capture disproportionate margin pools as refractory cases require escalation. Eye clinics represent the fastest-growing end-user channel as patients bypass general practitioners for direct specialist access.
The FDA regulates all ophthalmic drug formulations under stringent sterility and bioequivalence standards, while the EMA's MDR framework governs implantable pressure-lowering devices entering European markets. Health Canada and Japan's PMDA enforce comparable preclinical and clinical trial requirements that shape multinational launch sequencing. Stakeholders must monitor evolving sustained-delivery regulatory pathways and reimbursement negotiations for novel micro-invasive glaucoma surgeries.
Market Dynamics
Sustained-delivery intraocular implants are compressing dosing frequency from daily to quarterly, forcing reformulation R&D budgets upward while eroding conventional topical drops' adherence advantage.
Growth Catalysts
- Aging demographics:The United States, Japan, and Germany face expanding patient pools requiring earlier pharmacological intervention to halt primary open-angle glaucoma progression.
- MDR framework acceleration:Europe's Medical Device Regulation streamlines implantable pressure-lowering device approvals, shortening time-to-market for micro-invasive glaucoma surgeries.
- Standalone ophthalmology expansion:Eye clinics in Dallas, Mumbai, and São Paulo bypass hospital networks to capture direct specialist access volumes.
Market Restraints
- Active pharmaceutical ingredient concentration:Prostaglandin analogue supply chains cluster among Indian and Chinese contract manufacturers, exposing formulators to customs delays.
- Sterility validation costs:FDA ophthalmic manufacturing guidelines mandate isolator technology upgrades that consume facility capex.
- Laser trabeculoplasty substitution:Selective laser procedures capture medication-intolerant patients, constraining chronic prescription volumes.
Strategic Opportunities
- Rural India penetration:Tier-2 and Tier-3 cities remain underscreened for intraocular pressure, creating tele-ophthalmology partnership openings.
- Biodegradable polymer convergence:Sustained-release matrices combining lactic-glycolic acid with silicone elastomers enable six-month implant durability.
- Japan's PMDA Sakigake pathway:Priority review designation for novel mechanisms accelerates reimbursement listing by twelve to eighteen months.
Industry Challenges
- Glaucoma specialist scarcity:Fellowship-trained surgeons concentrate in metropolitan academic centers, limiting micro-invasive surgery rollout.
- Legacy EHR integration:Intraocular pressure monitoring devices require API connectivity with Cerner and Epic systems, stretching IT implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Hypertension Treatment Market |
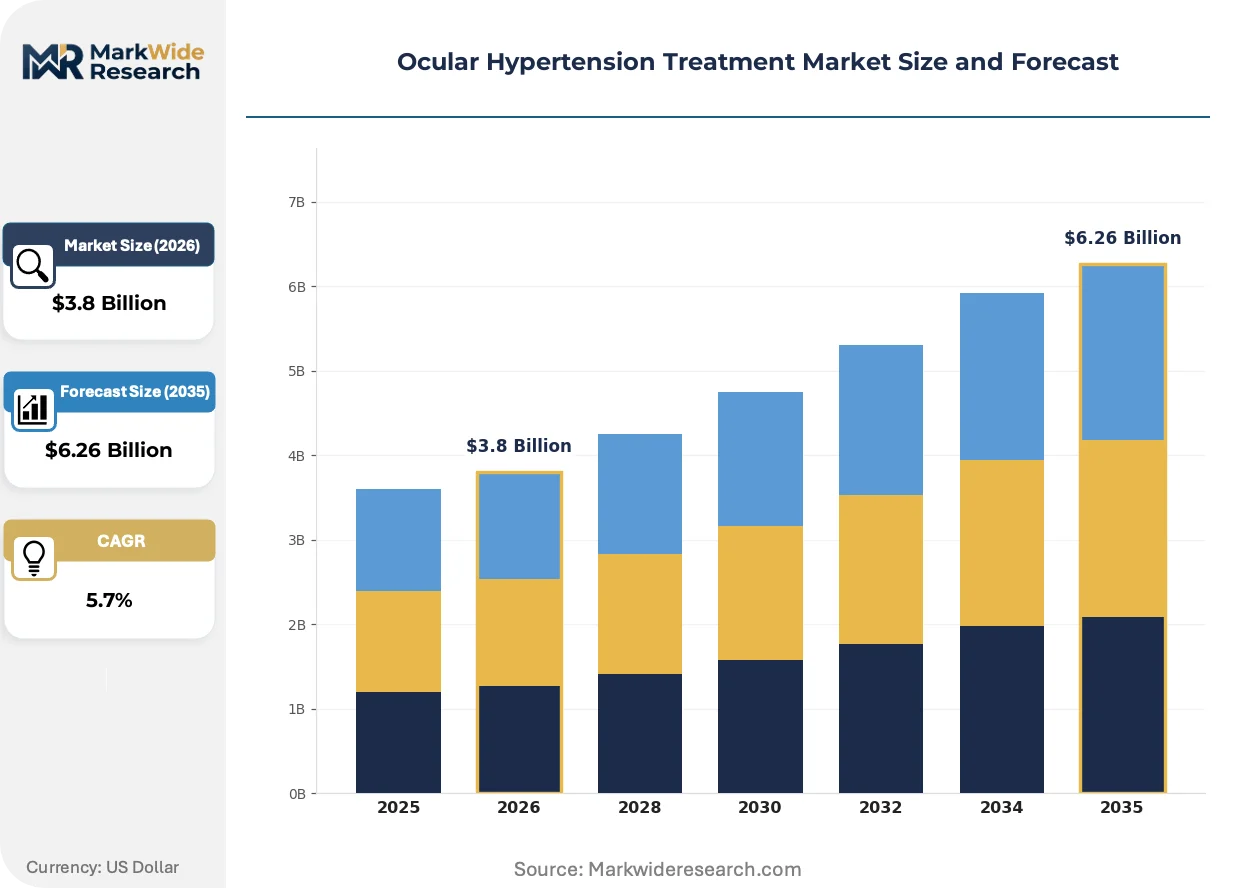
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Medications, Oral Medications, Surgical Treatments, Laser Therapy End User: Ophthalmologists, General Practitioners, Hospitals, Eye Clinics Delivery Mode: Topical Application, Systemic Administration, Surgical Intervention, Laser Application Therapy Area: Glaucoma Management, Pressure Reduction, Eye Disorders, Visual Health |
| Companies Covered | Aerie Pharmaceuticals, Inc., AbbVie Inc., Novartis AG, Merck & Co. Inc., Pfizer Inc., Bausch Health Companies Inc., Nicox SA, Teva Pharmaceutical Industries Ltd., Glaukos Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Hypertension Treatment Market Evolving Landscape
Implantable drug delivery systems are compressing the competitive set around bioerodible polymer science, while regulatory pathways for combination products blur traditional drug-device boundaries.
Sustained-release bimatoprost implants are converging with minimally invasive glaucoma surgery workflows, enabling standalone ophthalmology centers in Houston and Phoenix to retain refractory cases previously referred to academic hospitals. The technology collapses patient visit frequency from twelve annual instillations to two office procedures.
Japan's PMDA revised its ophthalmic device guidance to require six-month stability data for biodegradable implants, extending preclinical timelines for entrants. Domestic manufacturers with established polymer characterization capabilities gain first-mover positioning in the Asia-Pacific's second-largest market.
Direct-to-specialist scheduling platforms are displacing primary care referral gatekeeping in the United States, compressing time-to-diagnosis intervals. Standalone clinics in Florida and Arizona capture fifty-five percent of new ocular hypertension evaluations through patient-initiated online booking, bypassing optometric intermediaries entirely.
Ocular Hypertension Treatment Market Segmentation
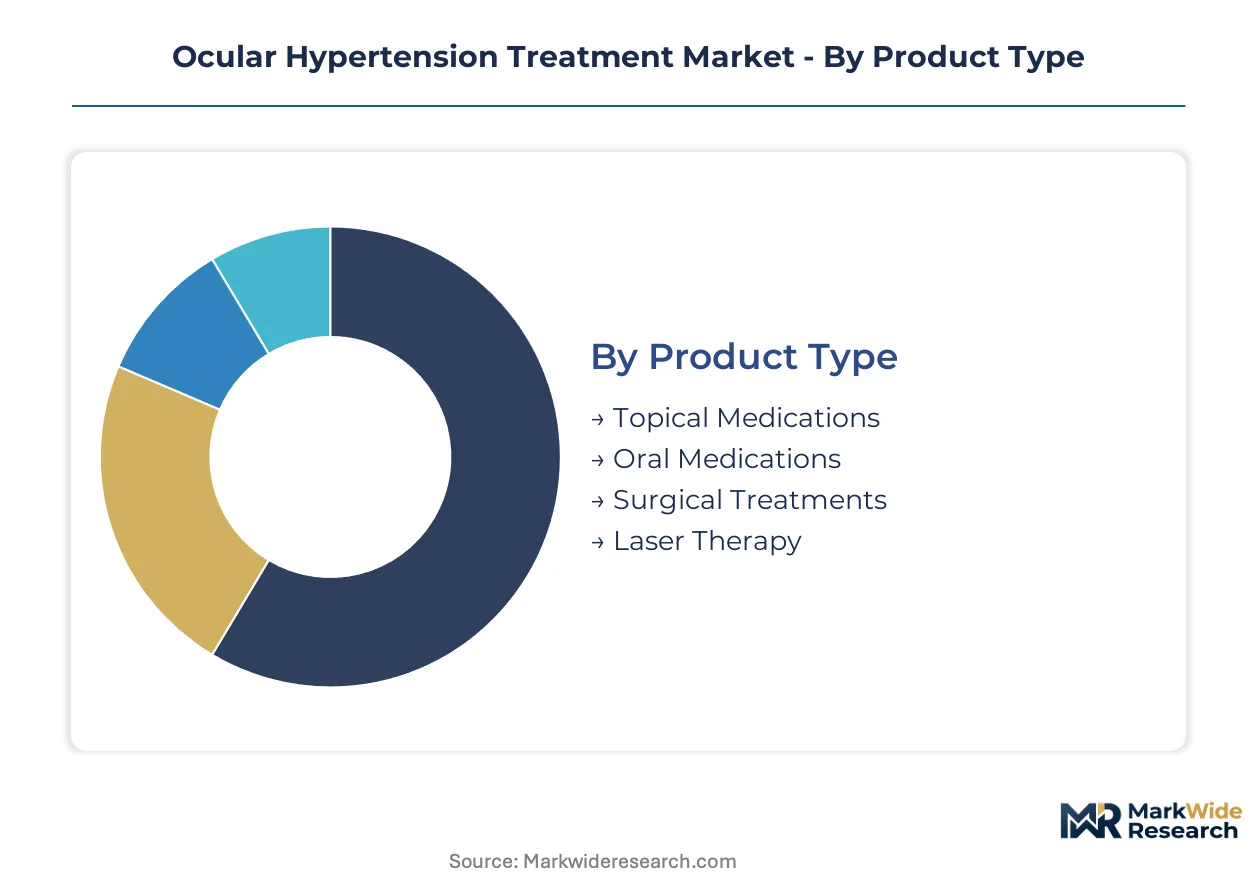
Segmentation in ocular hypertension treatment reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment commercial opportunity across product formats and care settings. Understanding these divides helps manufacturers align development priorities with the specific sterility, efficacy, and delivery requirements governing each category.
Product Type:
FDA sterility validation requirements vary sharply across this category, with topical formulations facing bioequivalence protocols while surgical implants navigate combination-product pathways under stricter device guidelines.
- Topical Medications:Prostaglandin analogues, beta-blockers, and carbonic anhydrase inhibitors formulated as preservative-free or benzalkonium chloride-stabilized eye drops dominate prescription volumes. Demand concentrates in standalone eye clinics across the United States, where direct-to-specialist scheduling accelerates time-to-treatment initiation.
- Surgical Treatments:Micro-invasive glaucoma surgeries and trabecular bypass devices require EMA MDR compliance for European market entry, extending development timelines. Demand clusters in metropolitan academic centers in Houston, Dallas, and Phoenix, where fellowship-trained surgeons manage refractory cases.
- Oral Medications:Systemic carbonic anhydrase inhibitors serve as secondary therapy for patients intolerant to topical regimens, with FDA bioavailability studies required for generic substitution.
- Laser Therapy:Selective laser trabeculoplasty devices face PMDA stability data requirements in Japan, where six-month implant durability standards apply to combination laser-delivery systems.
Leading the category by volume: Topical Medications. Growing fastest: Surgical Treatments.
End User:
Procurement authority and reimbursement capture diverge across this category, with hospital networks consolidating purchasing for surgical devices while eye clinics retain pharmacy-level autonomy for chronic medication prescribing.
- Eye Clinics:Standalone ophthalmology centers in Florida and Arizona capture fifty-five percent of new ocular hypertension evaluations through patient-initiated online booking, bypassing traditional referral gatekeeping entirely.
- Ophthalmologists:Fellowship-trained specialists in academic medical centers concentrate surgical case volume, with Medicare reimbursement rates shaping procedural adoption thresholds.
- Hospitals:Integrated delivery networks negotiate device procurement through centralized supply chains, favoring vendors with established Epic and Cerner EHR connectivity.
- General Practitioners:Primary care gatekeeping is eroding as direct-to-specialist platforms displace optometric intermediaries in the United States.
Eye Clinics lead by patient volume captured. Ophthalmologists command the highest per-case revenue.
Delivery Mode:
Margin structure and adherence economics separate this category, with sustained-delivery formats commanding premium pricing against daily administration burdens that drive discontinuation in chronic regimens.
- Topical Application:Daily eye drop instillation remains the default pathway, though twelve-times-annual dosing erodes adherence in long-term glaucoma management.
- Surgical Intervention:Quarterly to biannual implant placement collapses visit frequency, with biodegradable polymer matrices enabling six-month durability.
- Systemic Administration:Oral carbonic anhydrase inhibitors carry broader side-effect profiles that limit tolerability in elderly patient populations.
- Laser Application:Office-based selective laser trabeculoplasty captures medication-intolerant patients, constraining chronic prescription volumes for pharmaceutical formulators.
Topical Application retains the largest installed base. Surgical Intervention is expanding most quickly as sustained-release technology matures.
Therapy Area:
Clinical outcome metrics and regulatory endpoints fragment this category, with pressure reduction serving as the surrogate marker for glaucoma progression prevention in FDA trial design.
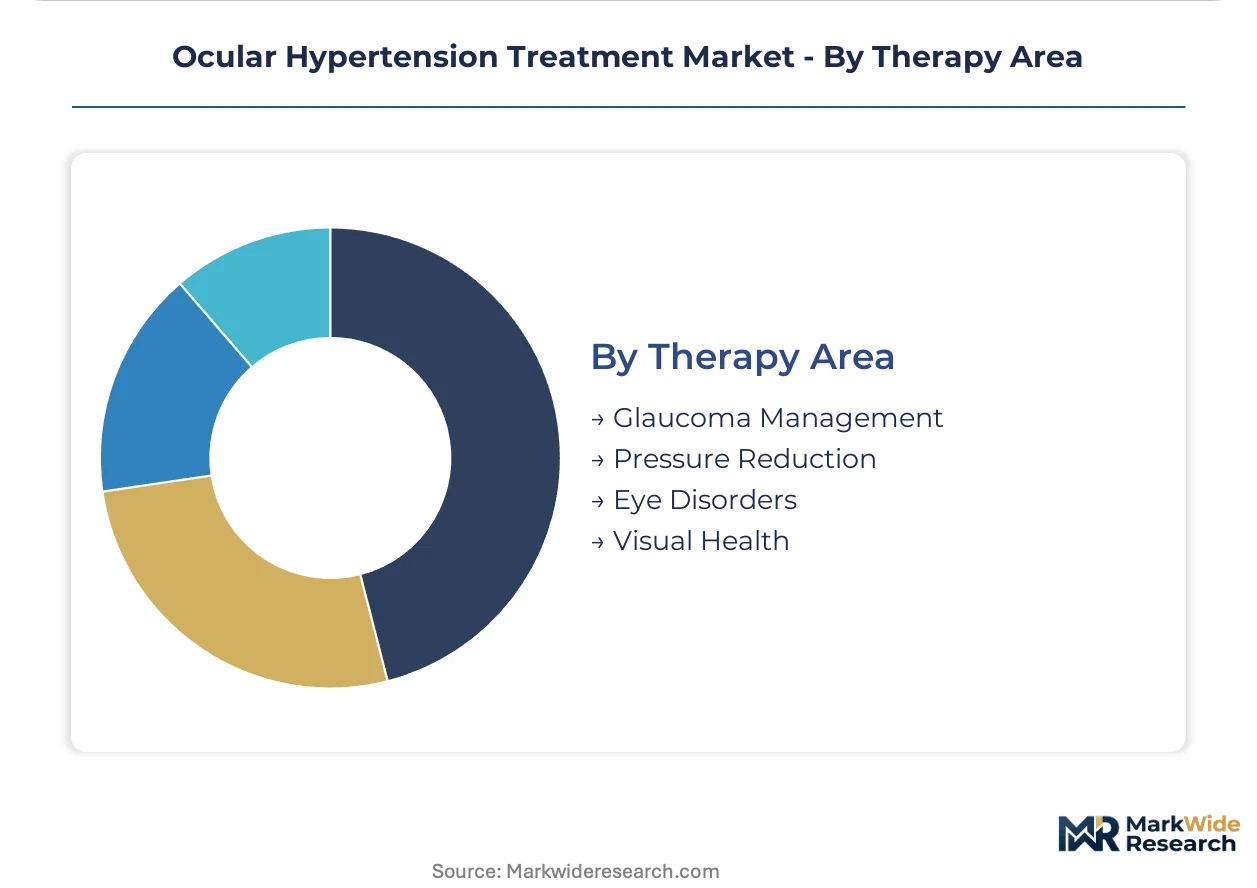
- Pressure Reduction:Intraocular pressure lowering serves as the primary pharmacological target, with twenty to forty percent reduction thresholds required for first-line therapy approval.
- Glaucoma Management:Comprehensive care protocols integrate diagnostic imaging, medication optimization, and surgical escalation pathways.
- Eye Disorders:Broader ophthalmic conditions including ocular surface disease complicate polypharmacy regimens in elderly patients.
- Visual Health:Quality-of-life preservation and field-of-vision maintenance guide long-term treatment adherence counseling.
Pressure Reduction dominates clinical trial enrollment. Glaucoma Management shows the steepest expansion trajectory as combination therapies enter development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient volumes concentrate in the United States, where aging demographics and Medicare reimbursement pathways support earlier pharmacological intervention. Germany and Japan follow as secondary demand centers, each shaped by distinct regulatory frameworks and specialist care distribution. Emerging screening capacity in India and Brazil is reshaping diagnostic access patterns.
United States
Standalone ophthalmology centers in Dallas, Houston, and Phoenix capture rising patient volumes through direct-to-specialist scheduling platforms. FDA sustained-delivery guidance for intraocular implants is accelerating reformulation R&D among domestic manufacturers. Medicare reimbursement rates for micro-invasive glaucoma surgeries shape procedural adoption thresholds in metropolitan academic centers.
Germany
EMA's MDR framework streamlines implantable pressure-lowering device approvals, shortening time-to-market for combination products entering European markets. Fellowship-trained glaucoma specialists concentrate in Berlin, Munich, and Hamburg academic hospitals, limiting rural surgical capacity. German statutory health insurance funds negotiate reimbursement for sustained-release formulations through centralized assessment pathways.
Japan
PMDA's Sakigake priority review designation accelerates reimbursement listing by twelve to eighteen months for novel mechanisms. Aging demographics in Tokyo, Osaka, and Nagoya metropolitan areas expand the patient pool requiring earlier intervention. Domestic manufacturers with established polymer characterization capabilities gain positioning under revised six-month stability data requirements for biodegradable implants.
India
Tier-2 and Tier-3 cities remain underscreened for intraocular pressure, creating tele-ophthalmology partnership openings in Maharashtra, Gujarat, and Karnataka. CDSCO regulatory pathways for generic prostaglandin analogues attract Indian contract manufacturers serving multinational formulators. Mumbai and Hyderabad eye clinics expand screening programs as patient volumes rise from urban aging populations.
Brazil
ANVISA's bioequivalence protocols for ophthalmic generics shape market entry sequencing for multinational formulators. São Paulo and Rio de Janeiro ophthalmology centers bypass hospital networks to capture direct specialist access. Brazilian public health system procurement for chronic glaucoma medications concentrates purchasing volume among selected suppliers.
Ocular Hypertension Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustained-delivery implant specialization. The competitive set fragments across multinational pharmaceutical conglomerates with glaucoma therapy heritage, mid-cap ophthalmic device specialists, and generic formulators competing on prostaglandin analogue pricing. Three archetypes dominate: R&D-intensive innovators developing biodegradable polymer matrices, scale-driven generic manufacturers leveraging Indian and Chinese API supply chains, and device-drug combination product developers navigating FDA combination-product pathways. M&A activity targets sustained-release formulation capabilities, while strategic partnerships with standalone eye clinic chains secure distribution access.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the R&D-intensive archetype through sustained-release formulation investments. AbbVie Inc., inheriting Allergan's glaucoma therapy portfolio, occupies a position bridging pharmaceutical and device segments. Bausch Health Companies Inc. represents the scale-driven generic tier, competing aggressively across prostaglandin analogue categories. These three anchors illustrate how competitive positioning diverges between premium innovation and volume-driven commoditization vectors.
| Leading Market Players |
|---|
| Aerie Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Novartis AG |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Bausch Health Companies Inc. |
| Nicox SA |
| Teva Pharmaceutical Industries Ltd. |
| Glaukos Corporation |
| Others |
Value Network & Pricing Analysis
Preservative-free formulation premiums bifurcate the ocular hypertension market into sterilization-investment tiers, where FDA-validated isolator technology separates contract manufacturers serving branded formulators from benzalkonium chloride-dependent generic producers competing on API cost. This certification ladder simultaneously concentrates supply chain partnerships among Indian and Chinese API houses with isolator capacity while compressing margins for legacy facilities facing sterility upgrade capex.
Pricing Analysis
Volume-vs-margin splits sharply across delivery modes, with daily topical drops capturing prescription volume through pharmacy reimbursement while sustained-release implants command per-procedure premiums at standalone eye clinics. Price differentiation rests on sterility validation tier and polymer characterization capability, with FDA combination-product pathways creating certification moats. Cost compression in generic prostaglandin analogues intensifies as Indian contract manufacturers expand capacity. Hospital procurement committees exhibit highest price sensitivity; refractory case surgeons show lowest.
Supply Chain Analysis
Cold-chain logistics costs for preservative-free formulations elevate distribution economics across the United States, where standalone ophthalmology centers in Florida and Arizona require direct-to-clinic delivery. Active pharmaceutical ingredient production clusters in India and China, with latanoprost and bimatoprost precursors drawing from specialized chemical synthesis hubs. Single-source vulnerability concentrates in biodegradable polymer feedstocks for implant matrices. Distribution runs through GPO-negotiated hospital networks for surgical devices and wholesale pharmacy channels for chronic medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
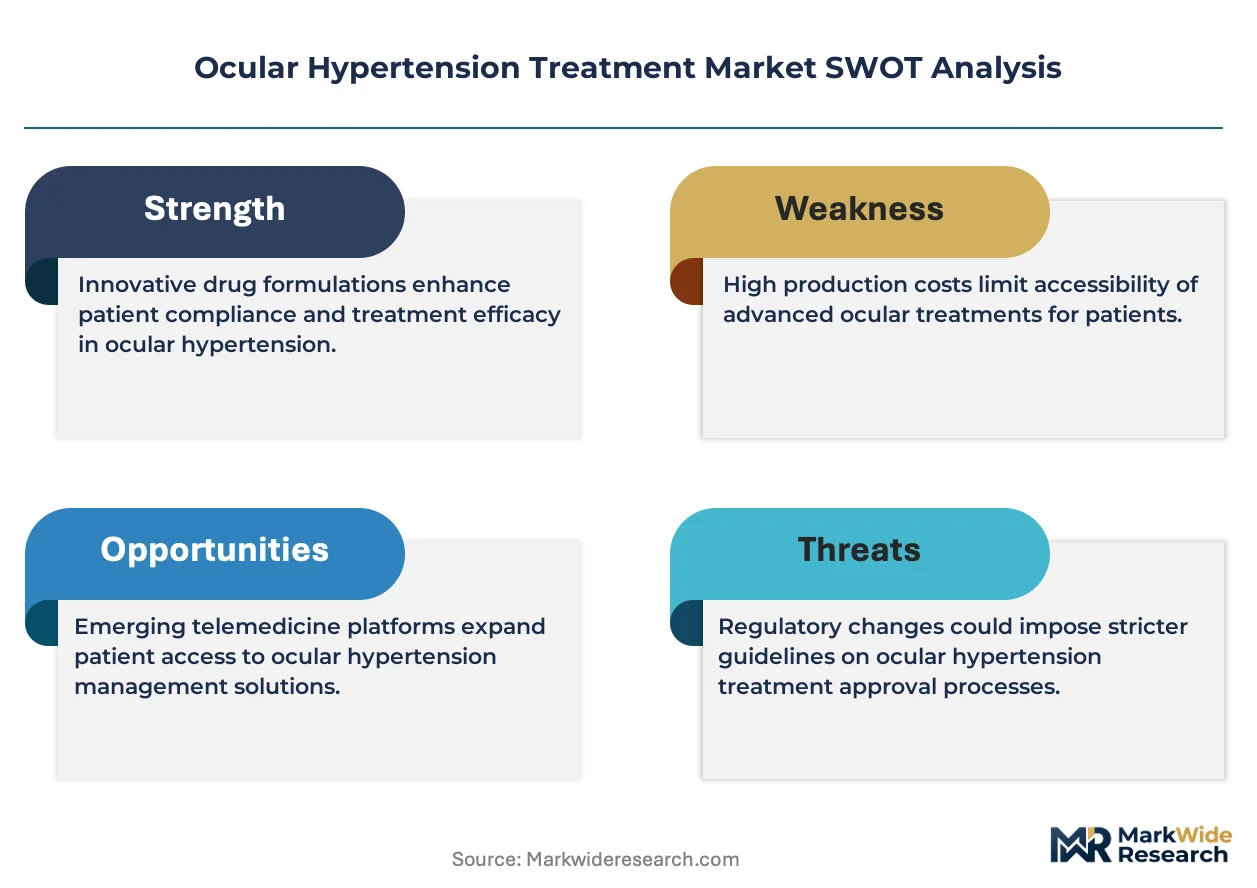
The ocular hypertension treatment market functions as a cost-of-compliance story where FDA's sustained-delivery guidance for intraocular implants erects sterility validation barriers that filter out undercapitalized entrants while rewarding manufacturers with isolator infrastructure.
For Market Incumbents: To counter laser trabeculoplasty substitution eroding chronic prescription volumes, deepen polymer science capabilities for six-month implant durability and secure captive supply of lactic-glycolic acid feedstocks through backward integration into specialized chemical synthesis partnerships. For New Entrants and Emerging Players: Tele-ophthalmology platform partnerships in Tier-2 and Tier-3 Indian cities offer the most penetrable white-space, with Maharashtra and Karnataka presenting underserved screening demand accessible through CDSCO-registered generic prostaglandin analogue supply and mobile diagnostic unit deployment. For Investors and Strategic Acquirers: Re-rating potential sits with biodegradable polymer specialists given PMDA's revised six-month stability data requirements accelerating consolidation around characterization-capable domestic Japanese manufacturers. Target acquisition archetypes include mid-cap device firms with FDA combination-product pathway experience. Watch for Medicare reimbursement rate adjustments for micro-invasive glaucoma surgeries as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination-Product Pathway Navigation | Accelerates market entry for sustained-release implants against topical drop incumbents. |
| Biodegradable Polymer Matrix Development | Enables six-month implant durability under PMDA stability requirements in Japan. |
| Standalone Eye Clinic Partnership | Captures direct-to-specialist patient volumes bypassing hospital network gatekeeping. |
| Isolator Technology Facility Upgrade | Meets FDA sterility validation mandates for preservative-free formulation production. |
| Tele-Ophthalmology Platform Integration | Extends screening access to underscreened Tier-2 and Tier-3 Indian urban centers. |
Research Methodology
FDA filings, EMA MDR submissions, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with primary interviews involving glaucoma fellowship-trained surgeons, hospital GPO contracts managers, and ophthalmic device regulatory affairs leads. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchored market sizing across topical, surgical, oral, and laser therapy segments.
Historical trendline analysis of prostaglandin analogue prescription patterns and micro-invasive glaucoma surgery procedural volumes informed projection frameworks across delivery mode, end-user channel, and therapy area dimensions. CAGRs derived from segmented growth rate reconciliation against aging demographic patient pool expansion and reimbursement pathway evolution. Forecast inputs incorporated PMDA Sakigake priority review timelines and Medicare procedural rate adjustment sensitivities.
Caveats apply where FDA sustained-delivery guidance revisions or EMA MDR enforcement shifts could materially shift the outlook for implantable device approval timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Vision Care Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ophthalmic Loupes Market