
 Asia-Pacific Patient Monitoring Market | 2026-2036
Asia-Pacific Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Patient Monitoring Market Outlook
Project finance and equipment leasing is reshaping competitive access across the Asia-Pacific patient monitoring landscape. Mindray Medical International leverages its Shenzhen manufacturing base to sustain cost advantages in portable monitor exports. GE Healthcare anchors premium positioning through R&D intensity in digital telemetry platforms. Nihon Kohden dominates neurological monitoring specialization across Japanese hospital networks.
Patient monitoring encompasses continuous or intermittent physiological measurement systems incorporating sensors, signal processors, and display interfaces for vital signs including ECG, SpO2, blood pressure, and respiratory rate, primarily deployed to detect clinical deterioration and guide therapeutic intervention. Multi-parameter monitors lead product category revenue by integrating modular cardiac, respiratory, and neurological channels into centralized nursing station displays. Wireless technology segments are expanding fastest as hospital IT infrastructure migrates toward cloud-connected telemetry reducing bedside hardware density.
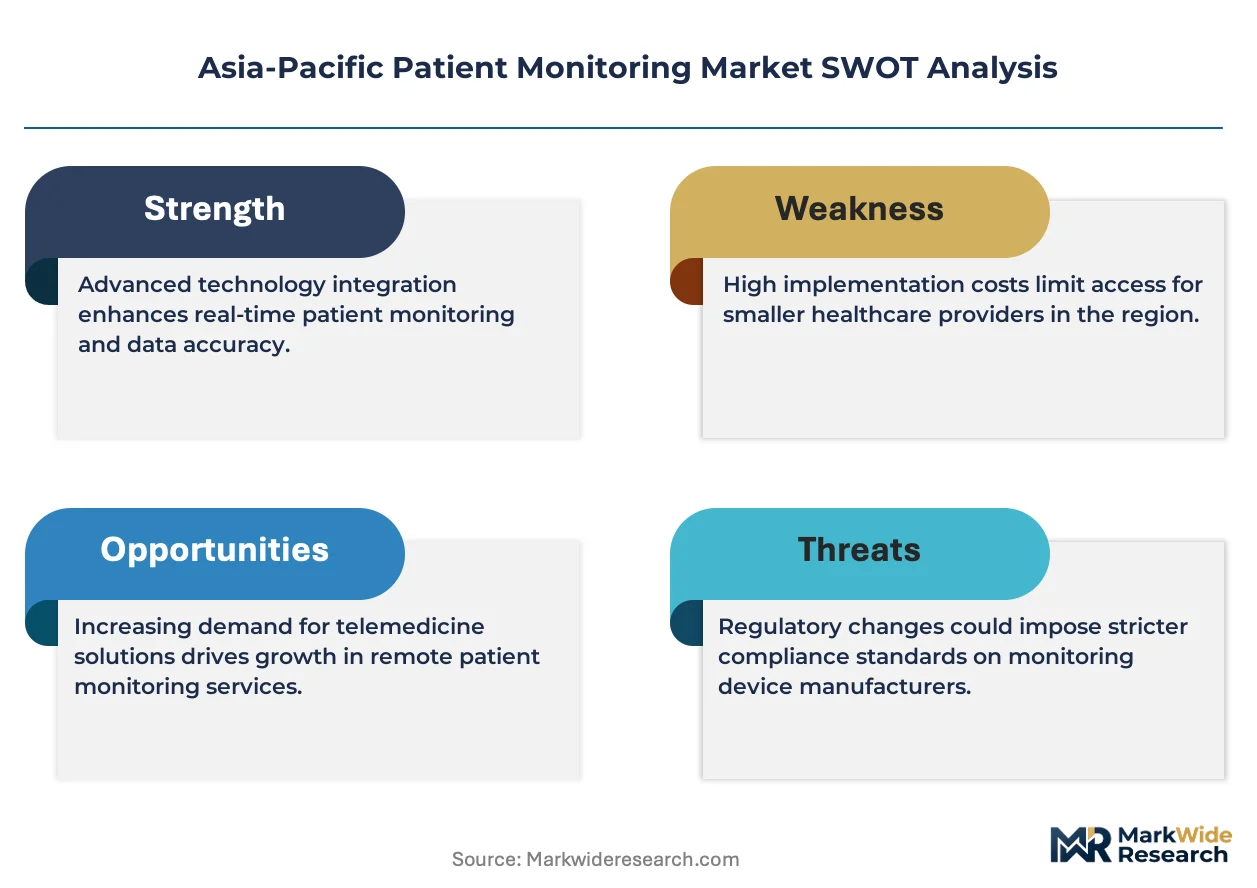
Japan's PMDA and China's NMPA enforce divergent clinical evidence requirements that fragment product registration timelines and inflate compliance costs for cross-border manufacturers. India's CDSCO medical device rules under the Drugs and Cosmetics Act are tightening post-market surveillance obligations for imported monitors. Australia's TGA alignment with EU MDR standards is creating a regulatory convergence corridor that simplifies market entry for European-certified systems. Stakeholders must weigh certification pathway economics against the margin compression from localized manufacturing mandates.
Market Dynamics
Wireless telemetry infrastructure is collapsing the traditional bedside hardware model across Asia-Pacific hospitals, compressing capital deployment cycles and forcing manufacturers to pivot toward software-recurring revenue architectures.
Growth Catalysts
- India's PLI scheme for medical electronics:Domestic manufacturing incentives are attracting component assembly investments that reduce import dependency for multi-parameter monitors.
- China's tier-two city hospital expansion:Bed capacity additions in provincial capitals are outpacing metropolitan saturation, creating concentrated procurement windows for mid-range monitoring systems.
- Cloud-connected telemetry platforms:Hospital IT modernization programs are displacing wired nursing station architectures with centralized patient data lakes.
Market Restraints
- Semiconductor component volatility:MEMS sensor and microcontroller supply concentration in Taiwan and South Korea creates input cost instability for portable monitor production.
- Regulatory fragmentation:Divergent clinical evidence requirements between Japan's PMDA and China's NMPA inflate compliance costs and extend product registration timelines for cross-border manufacturers.
- Refurbished equipment substitution:Secondary market flows from Australian and Japanese hospital upgrades are undercutting new equipment pricing in Southeast Asian procurement tenders.
Strategic Opportunities
- Indonesia's archipelago healthcare access gaps:Remote island clinics lack continuous monitoring infrastructure, creating white space for solar-powered portable systems with satellite uplink capability.
- Vietnam's public hospital PPP frameworks:Equipment leasing partnerships with private operators are opening capital-efficient market entry paths for foreign manufacturers.
- AI-enabled predictive deterioration algorithms:Integration of machine learning classifiers with vital sign streams is enabling early warning systems that command premium positioning.
Industry Challenges
- Biomedical engineering talent scarcity:Hospital IT departments across Thailand and the Philippines lack personnel trained in wireless telemetry troubleshooting and cybersecurity maintenance.
- Legacy system integration friction:Southeast Asian public hospitals operate mixed-vendor monitoring fleets that resist seamless cloud platform consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Patient Monitoring Market |
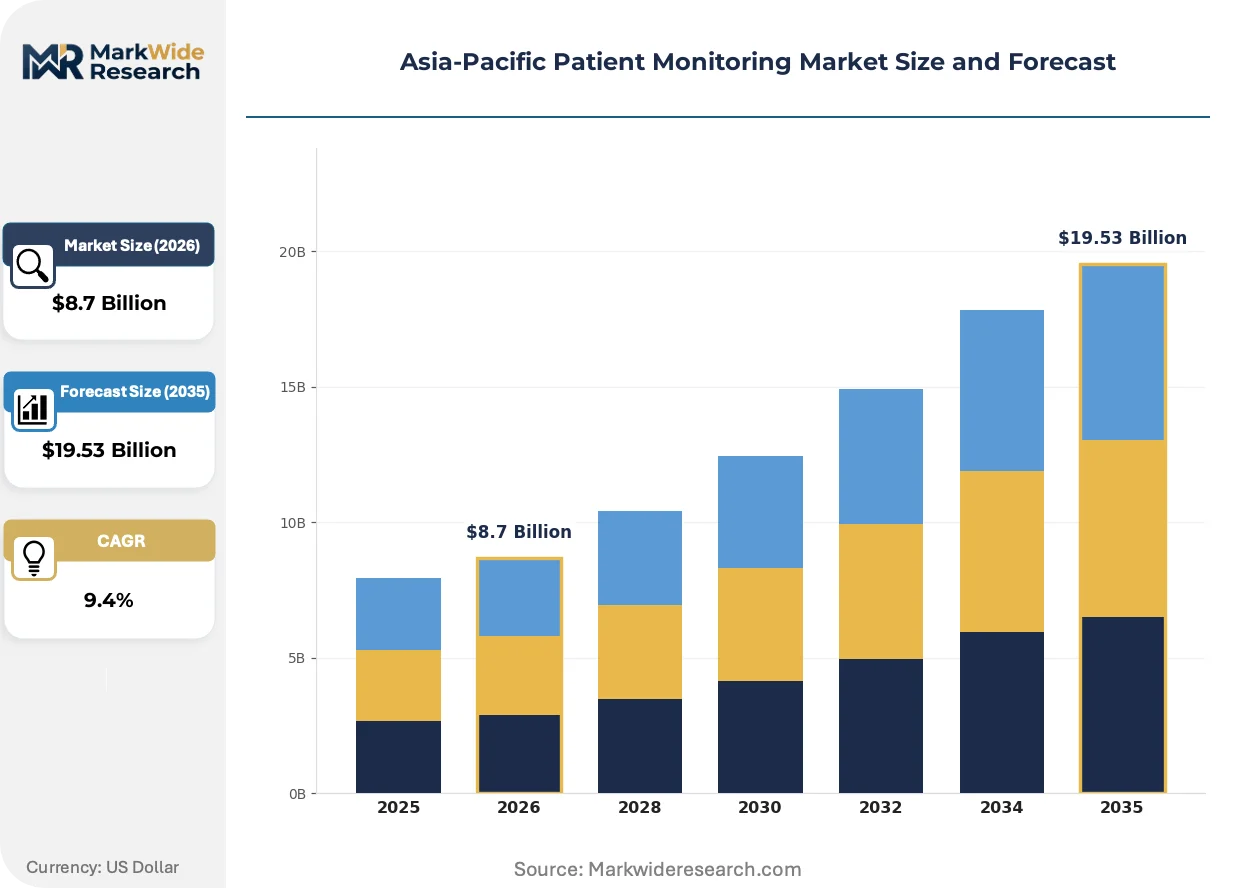
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitor, Respiratory Monitor, Neurological Monitor, Multi-Parameter Monitor Technology: Wireless, Wearable, Digital, Portable End User: Hospitals, Home Care, Ambulatory Surgical Centers, Rehabilitation Centers Application: Chronic Disease Management, Post-operative Care, Emergency Response, Patient Surveillance |
| Companies Covered | Koninklijke Philips N.V., General Electric Company (GE Healthcare), Mindray Medical International Co. Ltd., Nihon Kohden Corporation, Dragerwerk AG, BPL Group, Siemens Healthineers, Medtronic plc, Omron Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Patient Monitoring Market Strategic Shifts
Edge computing architectures are relocating signal processing from central servers to bedside devices, reducing latency for critical alarm generation while complicating cybersecurity postures.
Software-defined monitoring is virtualizing hardware functions previously locked in dedicated circuit boards. Chinese tertiary hospitals are piloting firmware-upgradable monitors that extend device lifecycles through feature subscriptions rather than hardware replacement. This virtualization is compressing capital expenditure recovery timelines and forcing manufacturers to build recurring revenue capabilities.
Australia's TGA alignment with EU MDR standards is creating a regulatory convergence corridor that simplifies market entry for European-certified systems. Medical device sponsors now leverage mutual recognition pathways to accelerate product registration, though post-market surveillance obligations have tightened comparably. Premium-tier manufacturers with existing EU certifications are capturing first-mover advantage in Australian public hospital tenders.
Equipment-as-a-service contracting is displacing outright purchase in Southeast Asian private hospital chains. Leasing arrangements bundle hardware, maintenance, and software updates into per-bed monthly fees that align vendor incentives with uptime performance. This model is most visible in Malaysia's expanding private healthcare sector, where capital discipline favors operational expenditure structures over balance-sheet asset accumulation.
Asia-Pacific Patient Monitoring Market Segmentation
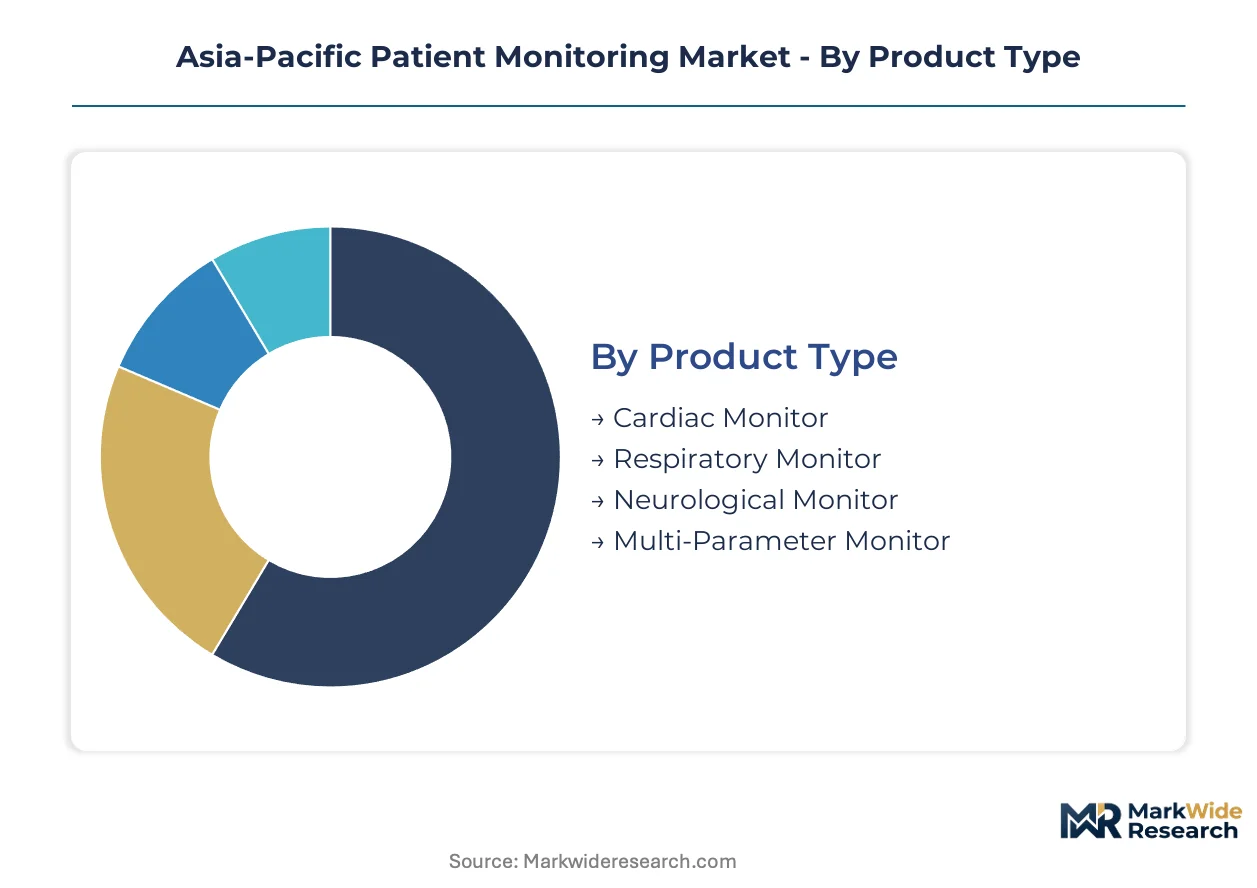
Patient monitoring segmentation in Asia-Pacific reflects divergent procurement economics across public hospital networks and private healthcare chains. Product configuration decisions hinge on after-sales service density, with wireless platforms demanding continuous firmware support that reshapes vendor selection criteria.
Product Type:
After-sales service intensity varies sharply across monitor categories, with multi-parameter systems requiring specialized biomedical engineering support that concentrates vendor relationships in tier-one hospital networks.
- Multi-Parameter Monitor:Modular architectures integrate cardiac, respiratory, and neurological channels into centralized nursing station displays. China's provincial hospitals in Chengdu and Wuhan are standardizing on these systems as bed capacity expansion accelerates in tier-two cities.
- Cardiac Monitor:ECG and arrhythmia detection systems with real-time ST-segment analysis. Japanese tertiary centers in Osaka and Nagoya prioritize these for post-surgical units where continuous rhythm surveillance is mandatory.
- Respiratory Monitor:Capnography and spirometry systems for ventilation management.
- Neurological Monitor:EEG and intracranial pressure systems for critical care neurology.
By volume, multi-parameter monitors lead. By growth pace, neurological monitors are expanding most quickly as stroke center accreditation spreads across Southeast Asia.
Technology:
Cost tier stratification separates premium wireless telemetry from economy portable units, with procurement budgets in Vietnam and Indonesia favoring lower-capital options despite higher lifetime service costs.
- Wireless:Cloud-connected telemetry platforms displacing wired nursing station architectures. Australian public hospitals in Queensland and New South Wales are consolidating patient data lakes through these systems as TGA-aligned procurement favors EU-certified equipment.
- Portable:Battery-powered monitors for transport and emergency use. India's district hospitals under the PLI scheme are absorbing these units as domestic assembly reduces import duties on compact SpO2 and NIBP modules.
- Wearable:Patch-based continuous monitors for ambulatory patients.
- Digital:Software-defined platforms with firmware-upgradable feature sets.
By installed base, portable systems dominate. By margin expansion, wireless platforms are gaining share fastest as recurring software revenue displaces hardware-only economics.
End User:
Customer type determines pricing elasticity, with private hospital chains in Malaysia accepting per-bed leasing structures that public systems in Thailand reject due to budget cycle constraints.
- Hospitals:Acute care facilities with 24-hour monitoring infrastructure. China's tier-two city expansions in Xi'an and Changsha are driving concentrated procurement windows for mid-range systems as metropolitan saturation limits Beijing and Shanghai demand.
- Home Care:Remote patient monitoring for chronic disease management. Australia's aged care providers in Victoria are deploying these systems as hospital-at-home programs reduce readmission penalties.
- Ambulatory Surgical Centers:Short-stay facilities requiring pre- and post-operative surveillance.
- Rehabilitation Centers:Post-acute facilities monitoring recovery trajectories.
By revenue concentration, hospitals dominate. By expansion trajectory, home care is climbing the fastest as reimbursement shifts favor decentralized care models.
Application:
Application maturity separates established post-operative surveillance from emerging predictive surveillance, with AI integration creating premium positioning in Japanese and Australian tertiary networks.
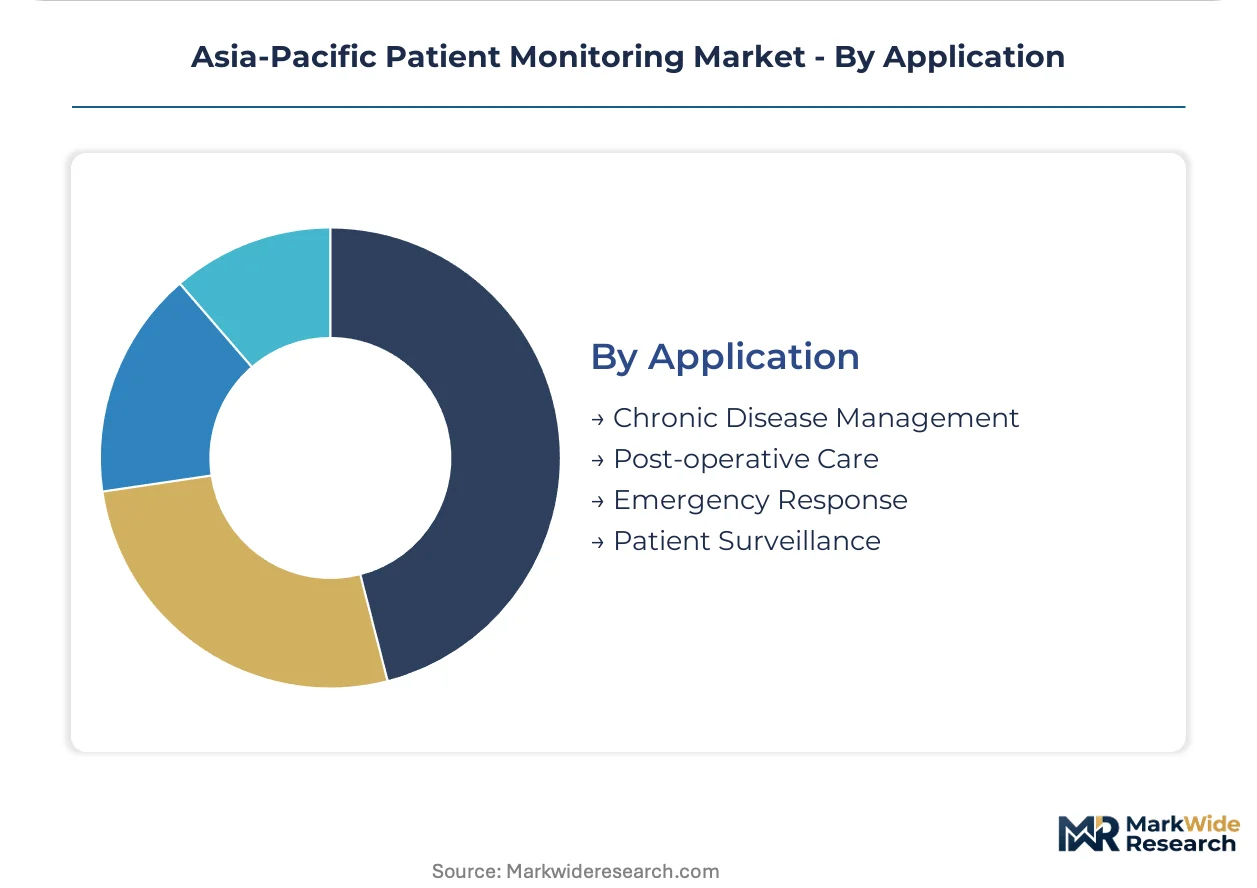
- Chronic Disease Management:Continuous glucose, blood pressure, and cardiac rhythm monitoring for diabetes and cardiovascular patients. India's urban clinics in Mumbai and Bangalore are scaling these programs as CDSCO post-market surveillance rules tighten data integrity requirements.
- Patient Surveillance:Early warning systems integrating vital sign streams with machine learning classifiers. South Korean tertiary centers in Seoul are piloting these platforms as MFDS fast-tracks AI-enabled device approvals.
- Post-operative Care:Recovery unit monitoring for surgical complications.
- Emergency Response:Pre-hospital and trauma bay vital sign acquisition.
By deployment scale, chronic disease management leads. By technology premium, patient surveillance shows the steepest expansion trajectory as predictive algorithms command pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Shenzhen and Osaka manufacturing clusters dominate regional supply, while import dependency concentrates in Indonesian and Vietnamese hospital procurement channels. Tier-two Chinese cities and Indian district hospitals are absorbing capacity as metropolitan markets saturate.
China
Tier-two provincial capitals including Chengdu, Wuhan, Xi'an, and Changsha are expanding bed capacity faster than Beijing or Shanghai. NMPA digital telemetry approval pathways are compressing registration timelines for cloud-connected platforms. Manufacturing concentration in Shenzhen sustains cost advantages for portable monitor exports across Southeast Asia.
India
Domestic assembly of multi-parameter monitors is accelerating under CDSCO medical device rules and the PLI scheme for medical electronics. District hospitals in Maharashtra and Karnataka are standardizing on compact SpO2 and NIBP modules as domestic production reduces import duties. Mumbai and Bangalore urban clinics are scaling chronic disease management programs with tightened post-market surveillance obligations.
Japan
Osaka and Nagoya tertiary centers prioritize cardiac and neurological monitoring for post-surgical units where continuous rhythm surveillance is mandatory. PMDA clinical evidence requirements for AI-enabled devices are more stringent than regional counterparts, fragmenting cross-border registration timelines. Kanto region hospitals anchor premium-tier demand for digital telemetry platforms.
Australia
Queensland and New South Wales public hospitals are consolidating patient data lakes through cloud-connected telemetry systems. TGA alignment with EU MDR standards creates a regulatory convergence corridor that simplifies market entry for European-certified equipment. Victorian aged care providers are deploying home monitoring systems as hospital-at-home programs reduce readmission penalties.
South Korea
Seoul tertiary centers are piloting AI-integrated patient surveillance platforms as MFDS fast-tracks approvals for machine learning classifiers. Daegu-Gyeongbuk medical device clusters are expanding component manufacturing for wireless telemetry hardware. Public hospital IT modernization programs are displacing wired nursing station architectures with centralized monitoring infrastructure.
Asia-Pacific Patient Monitoring Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers: premium digital telemetry specialists, mid-range modular system fabricators, and economy portable device assemblers. Strategic archetypes include Shenzhen-based cost-optimized exporters, Japanese neurological monitoring specialists, and European-certified premium platform providers. Competitive moves center on equipment-as-a-service contracting structures and AI-enabled predictive algorithm integration.
Among Asia-Pacific headquartered manufacturers, Mindray Medical International Co. Ltd. and Nihon Kohden Corporation occupy positions reflecting divergent specialization strategies, while Koninklijke Philips N.V. and General Electric Company exemplify the premium-tier multinational archetype with established regulatory certification portfolios across multiple national jurisdictions.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| General Electric Company (GE Healthcare) |
| Mindray Medical International Co. Ltd. |
| Nihon Kohden Corporation |
| Dragerwerk AG |
| BPL Group |
| Siemens Healthineers |
| Medtronic plc |
| Omron Healthcare |
| Others |
Value Chain & Pricing Dynamics
Semiconductor component volatility in Taiwan and South Korea determines both tier spreads in portable monitor pricing and the geographic configuration of assembly networks across Asia-Pacific. MEMS sensor concentration compresses margins in economy segments while inflating premium-tier spreads as manufacturers pass input instability through differentiated warranty terms.
Pricing Analysis
Hospital procurement committees anchor pricing structures around three-tier certification-grade differentiation separating EU MDR-aligned telemetry platforms from standard modular systems and economy portable units. Price differentiation hinges on NMPA registration tier and after-sales engineering density, with cloud-connected platforms commanding subscription premiums. Cost compression in the portable segment intensifies as India's PLI scheme absorbs domestic assembly capacity. Public hospital networks in Thailand exhibit highest price sensitivity; Australian private chains anchored by TGA-aligned procurement show lowest.
Supply Chain Analysis
Extended payment terms from Shenzhen assemblers to Southeast Asian distributors are compressing working capital cycles for tier-two city hospital tenders. Component manufacturing draws from Taiwan, South Korea, and Japan for MEMS sensors, microcontrollers, and display modules. Single-source vulnerability concentrates in wafer fabrication for specialized signal processors. Distribution runs through regional equipment leasing partnerships that bundle hardware with firmware support obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in tier-two city hospital networks where procurement decentralization creates niche windows for mid-range system specialists. Cloud-connected telemetry migration splits vendor relationships between legacy bedside hardware incumbents and software-native entrants.
For Market Incumbents: Harden service infrastructure density in provincial Chinese markets before NMPA digital telemetry pathways mature. Defend margin position through backward integration into firmware development capabilities rather than hardware cost reduction. Consolidate relationships with Australian GPO contracts managers as TGA-EU MDR convergence accelerates premium-tier procurement concentration. For New Entrants and Emerging Players: Indonesia's remote island clinic networks represent the most penetrable entry point for solar-powered portable systems with satellite uplink capability. Vietnam's public hospital PPP frameworks offer capital-efficient leasing structures that bypass upfront procurement committee resistance. Lead with AI-enabled early warning algorithm integration to differentiate from established hardware vendors. For Investors and Strategic Acquirers: MFDS fast-track approvals for machine learning classifiers reshape the acquisition landscape toward Seoul-based AI surveillance platform developers. Long-term viability centers on recurring software revenue architectures that displace hardware replacement cycles. Target acquisition archetype: mid-cap specialists with existing neurological monitoring certification and dormant wireless telemetry R&D pipelines. Watch MFDS approval velocity as inflection signal for regional AI-enabled device adoption.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Digital Telemetry Pathway | Accelerates cloud-connected platform registration for tier-two city hospital procurement. |
| Hospital System Partnership | Locks in multi-year equipment-as-a-service contracts with Malaysian private chains. |
| Software Companion Development | Enables firmware-upgradable feature subscriptions extending device lifecycle revenue. |
| CE Marking Pathway | Opens TGA-aligned Australian public hospital tenders through mutual recognition. |
| Reimbursement Strategy | Aligns predictive surveillance algorithms with Japan's post-acute care payment reforms. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers across China, India, and Australia; and secondary validation through NMPA registration databases, TGA approval records, hospital procurement disclosures, and ASEAN medical device trade flows. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Forecast inputs span product type, technology tier, end-user category, and application maturity across the projection horizon. CAGRs derive from segment-level demand elasticity calibrated to hospital bed expansion trajectories and IT modernization spend patterns. Modeled inputs include PLI scheme absorption rates, tier-two city infrastructure investment pipelines, and wireless telemetry adoption curves in public hospital networks.
Macroeconomic conditions sit as an overlay; deviation in semiconductor pricing cycles, cross-border tariff regimes, or hospital capital expenditure freezes would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and reimbursement policy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Dehydration Monitoring Systems Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Heart Monitoring Devices Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Europe Patient Monitoring Devices Market