
 Artificial Intelligence (AI) in Remote Patient Monitoring Market | 2026-2036
Artificial Intelligence (AI) in Remote Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Remote Patient Monitoring Market Outlook
Buyer concentration among integrated hospital networks is expanding as health systems consolidate vendor relationships across multiple facilities. GE Healthcare leverages its imaging and monitoring installed base to embed AI analytics directly into clinical workflows. Biofourmis competes through FDA-cleared digital therapeutics that combine biomarker monitoring with algorithmic dosing guidance. Medtronic plc anchors its position via deep integration between its device portfolio and cloud-based patient management platforms.
Artificial Intelligence in Remote Patient Monitoring encompasses machine learning algorithms, sensor fusion architectures, and edge-computing inference engines that process continuous physiological data streams to detect deterioration events before acute decompensation occurs. These systems typically operate on wearable biosensors sampling at 250 Hz or higher, with cloud pipelines executing predictive models against longitudinal patient records to generate risk scores for clinical teams. Machine Learning and Deep Learning segments dominate current deployment, with Natural Language Processing gaining traction for automated documentation of patient-reported outcomes. Wearable Devices and Software Platforms capture the deepest margin pools, while Telehealth Solutions face commoditization pressure from platform-agnostic video vendors.
FDA software-as-a-medical-device regulations and HIPAA security requirements shape product architecture decisions, mandating locked-down data pipelines and algorithmic transparency documentation that slow release cycles but raise competitive barriers. The European Union's MDR and AI Act impose additional conformity burdens on vendors seeking CE marking for predictive monitoring tools. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and England evaluate clinical economic evidence for AI-augmented remote monitoring when making coverage determinations.
Market Dynamics
Hospital procurement departments now mandate AI-native monitoring platforms that integrate directly with Epic and Cerner EHR systems, compressing vendor evaluation cycles and privileging incumbents with existing interoperability certifications.
Growth Catalysts
- CMS reimbursement expansion:Medicare's 2024 remote therapeutic monitoring codes now cover AI-augmented physiological data interpretation, accelerating hospital CFO approval for platform investments.
- Edge computing maturation:On-device inference chips from NVIDIA and Qualcomm enable real-time arrhythmia detection without cloud latency, expanding deployment to rural broadband-constrained regions.
- Chronic disease burden:Heart failure and COPD readmission penalties under the Hospital Readmissions Reduction Program create institutional urgency for predictive deterioration alerts.
Market Restraints
- Algorithmic validation costs:FDA 510(k) submissions for machine learning-based SaMD require prospective clinical trials exceeding twelve million dollars per indication.
- Sensor supply concentration:Photoplethysmography modules for wearable oximetry depend on three Taiwanese contract manufacturers, exposing procurement to geopolitical disruption.
- Interoperability fragmentation:HL7 FHIR implementation varies across health systems, forcing vendors to maintain multiple integration pipelines and elevating engineering overhead.
Strategic Opportunities
- Post-acute care penetration:Skilled nursing facilities in Texas and Florida lack AI monitoring infrastructure, presenting greenfield deployment potential for predictive fall-detection systems.
- FDA breakthrough device designation:The expedited review pathway for AI diagnostics addressing unmet neurological needs compresses time-to-revenue for seizure prediction algorithms.
- Multimodal sensor fusion:Combining continuous glucose monitors with accelerometer-derived activity signatures enables hypoglycemic event prediction before symptomatic onset.
Industry Challenges
- Clinical workflow integration:Alert fatigue from high-sensitivity algorithms strains nursing staff, requiring human-factors engineering investment to optimize signal-to-noise ratios.
- Cybersecurity certification:HIPAA Security Rule compliance for cloud-based AI inference demands SOC 2 Type II audits and penetration testing cycles that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Remote Patient Monitoring Market |
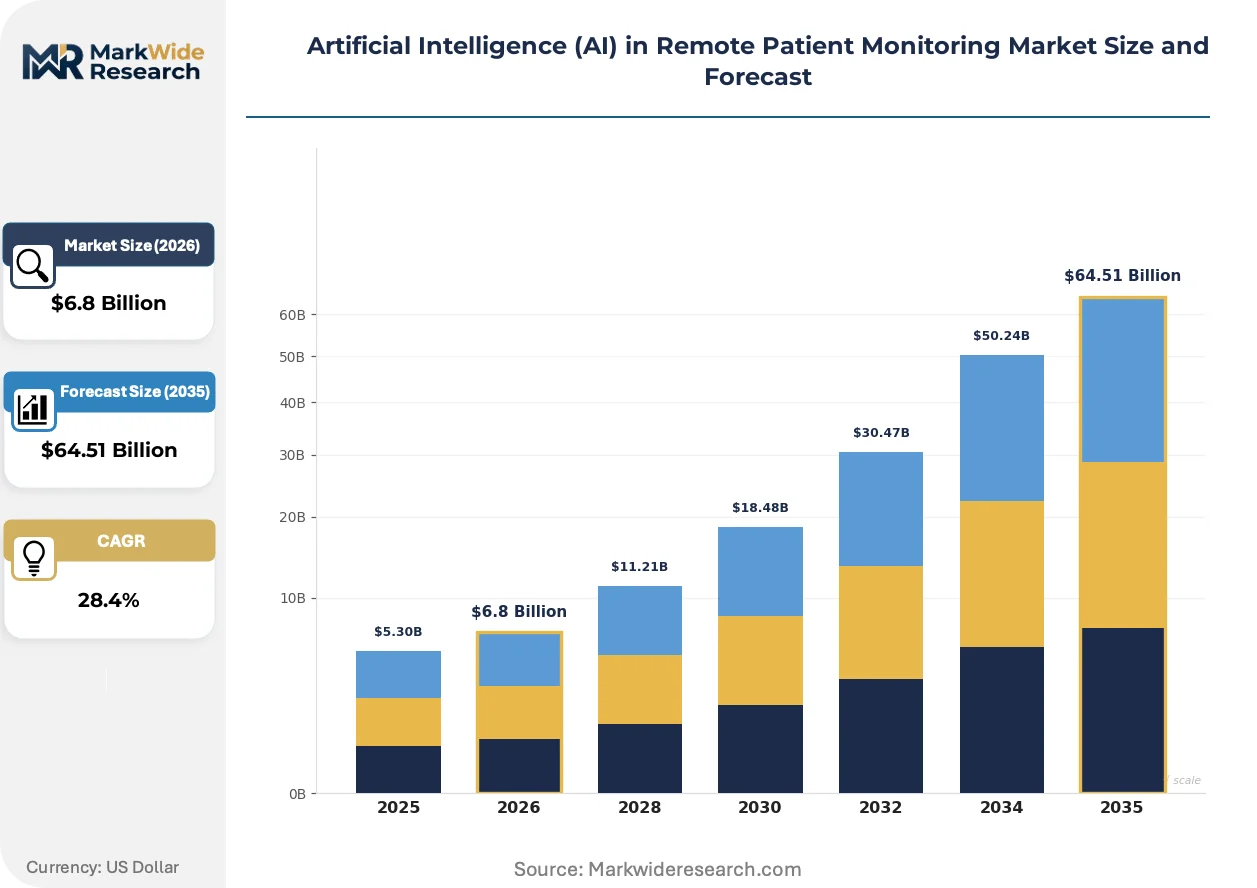
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Product Type: Wearable Devices, Mobile Applications, Software Platforms, Telehealth Solutions End User: Hospitals, Home Care Agencies, Patients, Healthcare Providers Data Type: Vital Signs, Activity Levels, Medical History, Patient Feedback |
| Companies Covered | GE Healthcare, Biofourmis, Medtronic plc, Current Health, BioIntelliSense, Siemens Healthineers, DexCom Inc, Vivify Health, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Remote Patient Monitoring Market Strategic Shifts
Algorithm architectures are migrating from cloud-centric batch processing toward federated learning frameworks that train models across distributed hospital datasets without centralizing protected health information.
Transformer-based neural networks are consolidating dominance in electrocardiogram interpretation, with attention mechanisms outperforming convolutional architectures on atrial fibrillation detection benchmarks. Academic medical centers in Boston and Stanford are deploying these models at the point of care, compressing specialist cardiology consultation queues and enabling same-day therapeutic intervention.
The FDA's predetermined change control plans for machine learning-enabled devices are tightening documentation requirements for algorithm updates, forcing vendors to lock performance specifications before commercialization. SaMD manufacturers must now submit algorithm change protocols alongside initial clearance applications, extending pre-market preparation cycles but reducing post-launch regulatory friction.
Integrated delivery networks are consolidating vendor relationships around platforms offering both hardware and algorithmic components, displacing point-solution specialists. Procurement committees at Kaiser Permanente and Mayo Clinic now require single-contract accountability for device uptime, data pipeline integrity, and clinical decision support accuracy, compressing the addressable market for pure-play software vendors.
Artificial Intelligence (AI) in Remote Patient Monitoring Market Segmentation
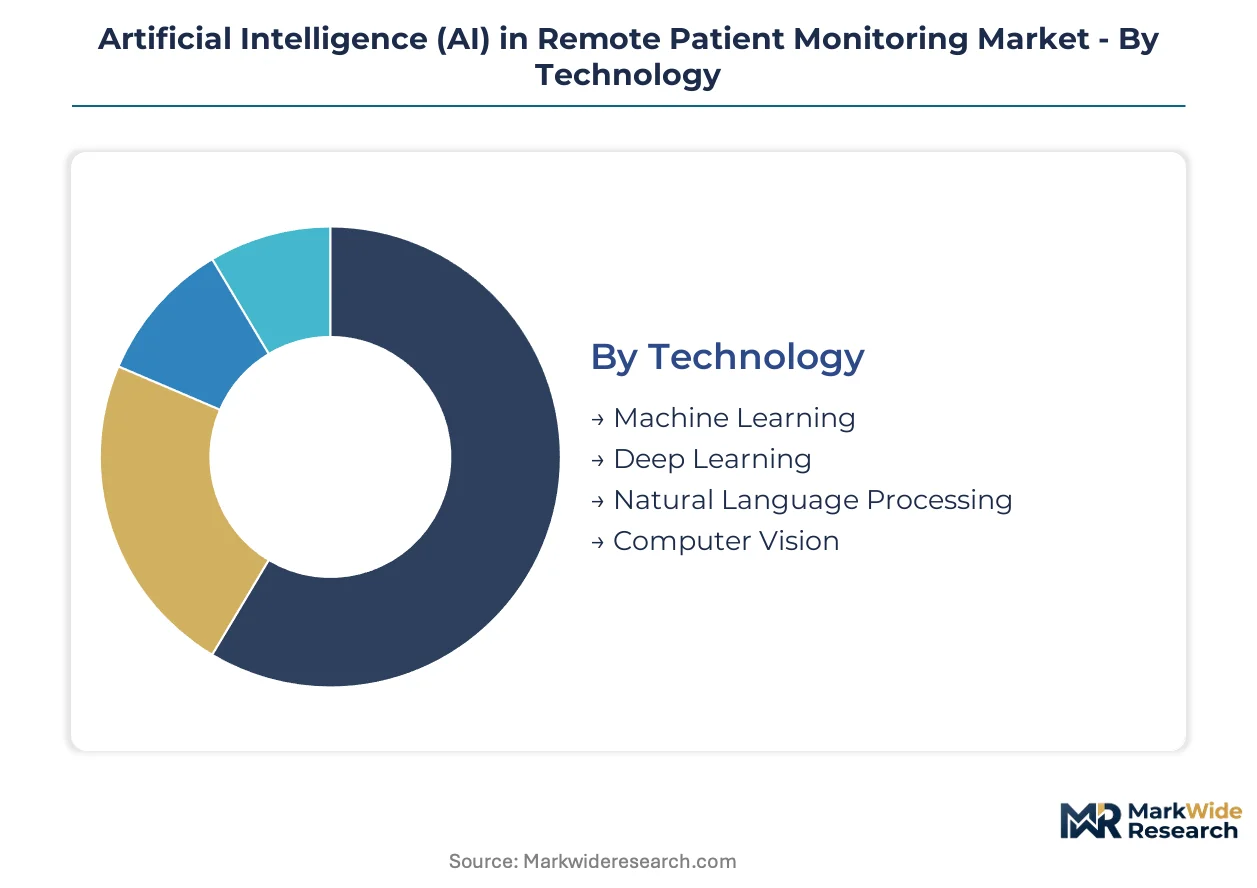
Segmentation in AI-enabled remote patient monitoring reveals how technology architecture, product form factor, and data source interact to determine deployment economics. Hospital procurement committees evaluate segments through distinct lenses: clinical validation depth for technology types, integration burden for product types, and reimbursement eligibility for end-user settings.
Technology:
Upgrade cycles in this category accelerate as health systems replace rule-based alerting with adaptive algorithms that improve through continuous learning.
- Machine Learning:Supervised learning pipelines train on labeled deterioration events from intensive care unit datasets, enabling risk stratification models that hospitals deploy at scale. Demand concentrates in United States integrated delivery networks seeking CMS-compliant predictive analytics for chronic disease management.
- Deep Learning:Multi-layer neural networks process raw electrocardiogram waveforms and photoplethysmography signals without manual feature engineering, achieving superior arrhythmia detection accuracy. Deployment concentrates in cardiology departments at academic medical centers in Boston and Cleveland pursuing same-day intervention protocols.
- Natural Language Processing:Extracts structured symptoms from unstructured patient messages and clinical notes, automating documentation workflows.
- Computer Vision:Analyzes facial video streams for micro-expression changes indicating pain or neurological events.
Volume placements concentrate in Machine Learning; the faster expansion belongs to Deep Learning.
Product Type:
Margin structures vary sharply across this category, with hardware-software bundles commanding premium pricing against commoditized connectivity layers.
- Wearable Devices:Biosensor hardware incorporating edge inference chips from NVIDIA and Qualcomm enables real-time processing without cloud dependency. Procurement at Kaiser Permanente and Mayo Clinic now mandates single-contract accountability spanning device uptime and algorithm accuracy.
- Software Platforms:Cloud-native inference engines integrate with Epic and Cerner EHR systems through HL7 FHIR pipelines, generating risk scores for clinical dashboard consumption. Health systems in Texas and Florida prioritize these platforms for chronic disease population management at scale.
- Mobile Applications:Patient-facing interfaces capturing symptom diaries and medication adherence data.
- Telehealth Solutions:Video consultation infrastructure facing commoditization pressure from platform-agnostic vendors.
Revenue concentration sits with Wearable Devices; Software Platforms are climbing the fastest as health systems consolidate vendor relationships.
End User:
Reimbursement authorization creates distinct adoption velocities across customer types, with institutional buyers moving faster than direct-to-patient channels.
- Hospitals:Enterprise deployments spanning multiple facilities require FDA 510(k) cleared algorithms and SOC 2 Type II certified cloud infrastructure. Medicare's remote therapeutic monitoring codes now cover AI-augmented physiological interpretation, accelerating CFO approval cycles.
- Home Care Agencies:Skilled nursing facilities in Texas and Florida present greenfield opportunity for predictive fall-detection systems lacking incumbent infrastructure.
- Patients:Direct-to-consumer adoption remains constrained by out-of-pocket payment requirements and limited clinical integration.
- Healthcare Providers:Individual physician practices evaluating point solutions for specific chronic conditions.
Deployment scale favors Hospitals; Home Care Agencies show the steepest expansion trajectory as post-acute reimbursement frameworks mature.
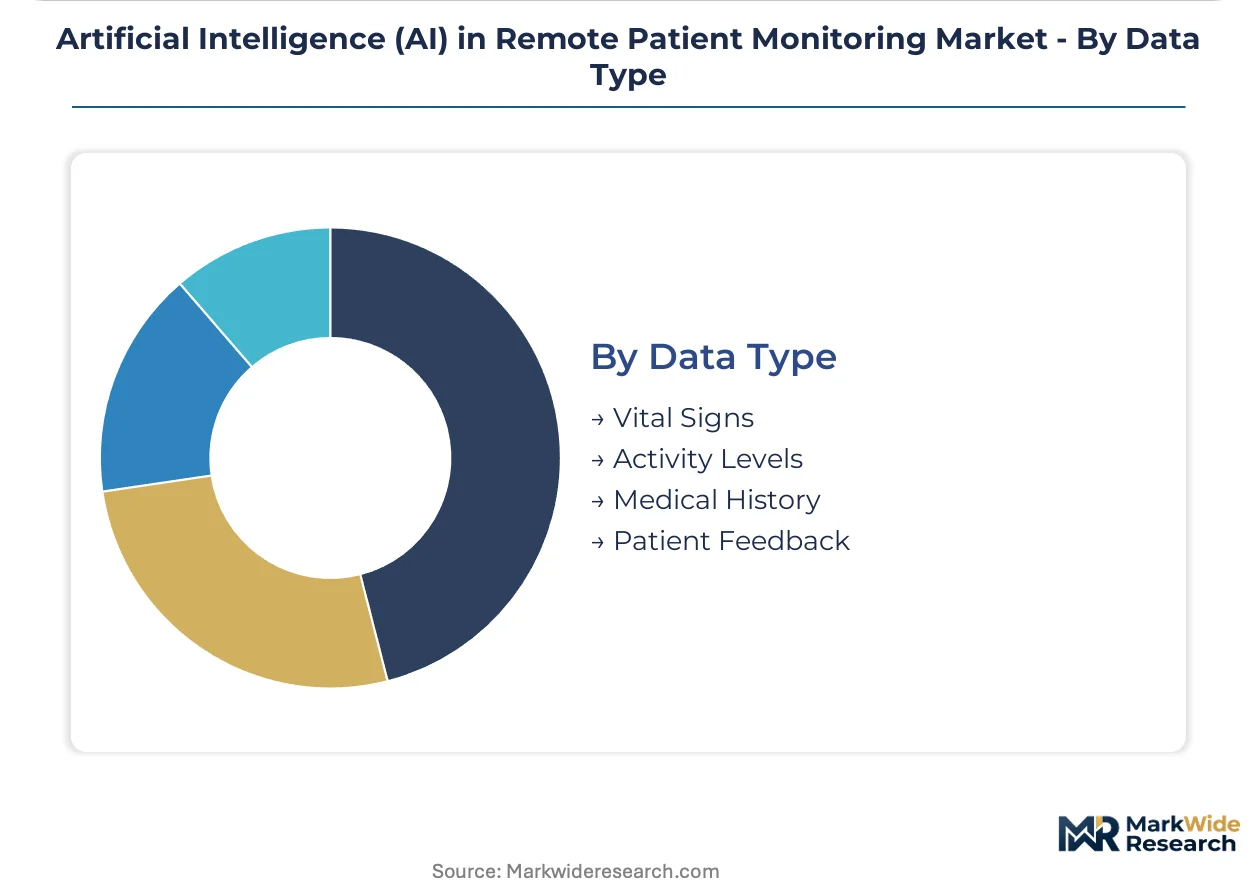
Data Type:
Sensor fusion architectures increasingly combine multiple data streams to improve prediction specificity and reduce false alert burden on clinical staff.
- Vital Signs:Continuous streams from photoplethysmography and electrocardiography sensors sampling at 250 Hz or higher, processed through edge-computing inference engines. Taiwan-based contract manufacturers supply concentrated photoplethysmography module capacity, exposing procurement to geopolitical disruption risk.
- Activity Levels:Accelerometer-derived movement signatures enabling mobility deterioration detection in elderly populations.
- Medical History:Structured EHR data providing longitudinal comorbidity context for risk scoring models.
- Patient Feedback:Subjective symptom reports captured through mobile interfaces or voice interfaces.
Processing priority goes to Vital Signs; Activity Levels are gaining share fastest as multimodal fusion applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States command the deepest procurement budgets for AI-enabled monitoring platforms, while reimbursement frameworks in Germany and Japan accelerate parallel adoption curves. Regulatory clearance velocity and integrated delivery network consolidation create divergent market maturities across national boundaries.
United States
Medicare's remote therapeutic monitoring codes now reimburse AI-augmented physiological interpretation, driving CFO approval cycles at Kaiser Permanente and Mayo Clinic. FDA software-as-a-medical-device regulations mandate locked-down data pipelines that raise competitive barriers for new entrants. Boston and Stanford academic medical centers deploy transformer-based ECG models at point of care, compressing specialist cardiology queues.
Germany
The EU MDR and AI Act impose conformity burdens on vendors seeking CE marking for predictive monitoring tools, slowing market entry but privileging prepared incumbents. Germany's national reimbursement authority evaluates clinical economic evidence for AI-augmented remote monitoring when making coverage determinations. Industrial clusters around Munich and Heidelberg concentrate health technology validation expertise.
Japan
METI and PMDA frameworks govern AI medical device approvals, with aging demographics intensifying institutional urgency for chronic disease management at scale. The country's national health insurance system evaluates remote monitoring platforms for inclusion in standard benefit packages. Tokyo and Osaka metropolitan hospitals pilot federated learning frameworks across distributed datasets.
United Kingdom
NHS England's integrated care systems consolidate vendor relationships around platforms offering both hardware and algorithmic components, displacing point-solution specialists. MHRA alignment with FDA software-as-a-medical-device precedents accelerates clearance pathways for predictive algorithms. London and Cambridge clusters concentrate digital health venture capital and regulatory consulting capacity.
China
NMPA medical AI regulations require algorithmic transparency documentation that slows release cycles but creates defensive moats for domestic vendors. The country's dual carbon goals intersect with edge-computing deployment to reduce cloud infrastructure energy intensity. Beijing and Shanghai health systems pilot multimodal sensor fusion architectures combining continuous glucose monitors with accelerometer signatures.
Artificial Intelligence (AI) in Remote Patient Monitoring Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital therapeutics and federated learning architectures. The vendor base stratifies across imaging incumbents, device-integrated platforms, and pure-play algorithm specialists. Three archetypes dominate: conglomerate health technology divisions leveraging installed base advantages; venture-backed SaMD specialists pursuing FDA breakthrough designations; and medical device manufacturers embedding cloud-based patient management layers. Competitive moves concentrate on interoperability certification racing and post-acute care channel expansion.
Within the conglomerate tier, GE Healthcare and Siemens Healthineers represent imaging and monitoring incumbents embedding AI analytics directly into clinical workflows. Among device-integrated specialists, Medtronic plc anchors its position via cloud-based patient management platforms tethered to its physiological sensor portfolio. Biofourmis occupies the digital therapeutics vector, exemplifying venture-backed SaMD specialists combining biomarker monitoring with algorithmic dosing guidance.
| Leading Market Players |
|---|
| GE Healthcare |
| Biofourmis |
| Medtronic plc |
| Current Health |
| BioIntelliSense |
| Siemens Healthineers |
| DexCom Inc |
| Vivify Health |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Edge-computing inference chip adoption from NVIDIA and Qualcomm is compressing hardware cost curves while concentrating procurement leverage among health systems demanding single-contract accountability for device-software bundles. This technology transition simultaneously lowers per-unit sensor economics and elevates vendor consolidation pressure, reshaping how pricing power distributes across the value chain.
Pricing Analysis
Volume placements concentrate in subscription-tiered SaaS contracts for cloud-native inference engines, while premium pricing attaches to wearable hardware bundles incorporating FDA-cleared algorithms and SOC 2 certified infrastructure. Price differentiation stems from certification grade—FDA 510(k) versus breakthrough designation—and integration depth with Epic and Cerner EHR systems. Pricing pressure intensifies in telehealth connectivity layers as platform-agnostic video vendors commoditize virtual consultation infrastructure. Home care agencies in Texas and Florida exhibit highest price sensitivity due to thin operating margins, whereas Kaiser Permanente and Mayo Clinic procurement committees prioritize algorithmic accuracy guarantees over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based contract manufacturers supplying photoplethysmography modules for wearable oximetry, exposing procurement to geopolitical disruption. Component sourcing draws from the United States for edge inference chips, Taiwan for biosensor modules, and Germany for precision manufacturing equipment. Raw material dependencies include semiconductor-grade silicon, medical-grade polymers, and lithium-ion cell chemistry for device power systems. Supply chain risk centers on tariff exposure affecting cross-border chip shipments. Distribution runs through integrated delivery networks consolidating vendor relationships across multiple facilities, compressing addressable channels for point-solution specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoplethysmography module concentration among three Taiwanese manufacturers creates a supply-constrained environment propping premium pricing for vendors with secured component pipelines. This bottleneck reinforces procurement urgency among health systems seeking resilient supply chains.
For Market Incumbents: Anticipate algorithm commoditization pressure from venture-backed SaMD specialists pursuing FDA breakthrough designations by deepening backward integration into edge inference chip supply and securing exclusive photoplethysmography module allocation agreements. Fortify interoperability certifications with Epic and Cerner EHR systems to maintain procurement committee preference at Kaiser Permanente and Mayo Clinic. Prioritize R&D investment in federated learning architectures that train models across distributed hospital datasets without centralizing protected health information. For New Entrants and Emerging Players: Federated learning frameworks offer a technology-first wedge for vendors lacking installed base advantages, enabling predictive model development without centralized data infrastructure that triggers HIPAA compliance burdens. Target skilled nursing facilities in Texas and Florida as the most penetrable geography, where predictive fall-detection infrastructure remains underdeployed. Pursue post-acute care channel partnerships with home health agencies seeking AI-augmented monitoring without enterprise hospital procurement complexity. For Investors and Strategic Acquirers: Re-rating potential sits with venture-backed SaMD specialists holding FDA breakthrough device designations for neurological applications, given expedited review pathways compressing time-to-revenue for seizure prediction algorithms. Long-term viability across the analysis window favors platforms combining hardware-software bundles with algorithmic transparency documentation satisfying EU AI Act conformity requirements. Monitor CMS reimbursement expansion for remote therapeutic monitoring codes as the critical signal indicating institutional buyer commitment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses time-to-revenue for neurological AI diagnostics addressing unmet clinical needs. |
| Hospital System Partnership | Single-contract accountability with Kaiser Permanente and Mayo Clinic secures multi-facility deployment scale. |
| CE Marking Pathway | EU MDR and AI Act conformity opens German reimbursement authority evaluation for predictive monitoring coverage. |
| Software Companion Development | Epic and Cerner EHR integration through HL7 FHIR pipelines embeds AI analytics directly into clinical workflows. |
| Reimbursement Strategy | Medicare remote therapeutic monitoring code alignment accelerates CFO approval cycles for platform investments. |
Study Parameters
Multi-period observation of FDA 510(k) submission volumes, CMS reimbursement code utilization, and health system procurement contract awards anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at SaMD manufacturers. Secondary validation drew from FDA software-as-a-medical-device filings, CMS Medicare claims data, hospital procurement databases, and integrated delivery network capital expenditure disclosures. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Input-output matrix framing connected algorithm deployment rates to sensor hardware shipments and cloud infrastructure capacity expansion across the projection horizon. Segmentation dimensions modeled include technology architecture, product form factor, end-user setting, and data source type, with additional granularity on interoperability certification status. CAGRs were derived from fitted growth curves against historical placement trajectories, incorporating edge computing chip shipment forecasts and chronic disease population prevalence projections as healthcare-specific demand drivers.
Several conditions sit outside the modeled scope, including specific algorithm performance benchmarks pending clinical validation, geopolitical disruption scenarios affecting Taiwanese component supply, and regulatory timeline shifts for EU AI Act implementation. Forecasts reflect documented assumptions about reimbursement expansion continuity and health system consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Patient Monitoring Software Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Fetal Heart Rate Monitoring Devices Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
IoT in Healthcare Market