
 Turner Syndrome Market | 2026-2036
Turner Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Turner Syndrome Market Intelligence
The divergence in R&D investment for novel genetic therapies versus established hormonal treatments is reorganizing the market's competitive structure. Pfizer Inc. leverages its broad pharmaceutical pipeline to address associated cardiovascular and metabolic comorbidities. Novo Nordisk A/S specializes in the development and supply of growth hormone therapies, a cornerstone of management. Ferring Pharmaceuticals competes by focusing on fertility solutions and estrogen replacement therapies for adolescent and adult patient cohorts.
Turner Syndrome is a genetic condition resulting from a complete or partial absence of an X chromosome in females, impacting physical development and causing various medical issues. The market provides therapeutic interventions to manage symptoms like short stature, ovarian failure, and congenital heart defects. Growth Hormones represent the dominant product type for pediatric patients, forming the foundation of care. Specialized Clinics and Pediatric Units serve as the primary end-user channels for initiating and monitoring these long-term treatment regimens.
Regulatory oversight from bodies such as the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) is critical for market access. These agencies' approval processes and Orphan Drug Designation policies directly influence the pipeline of new treatments for both pediatric and adult patients. Stakeholders must now focus on demonstrating long-term clinical value and securing favorable reimbursement for combination therapies that address the multifaceted nature of the syndrome.
Market Dynamics
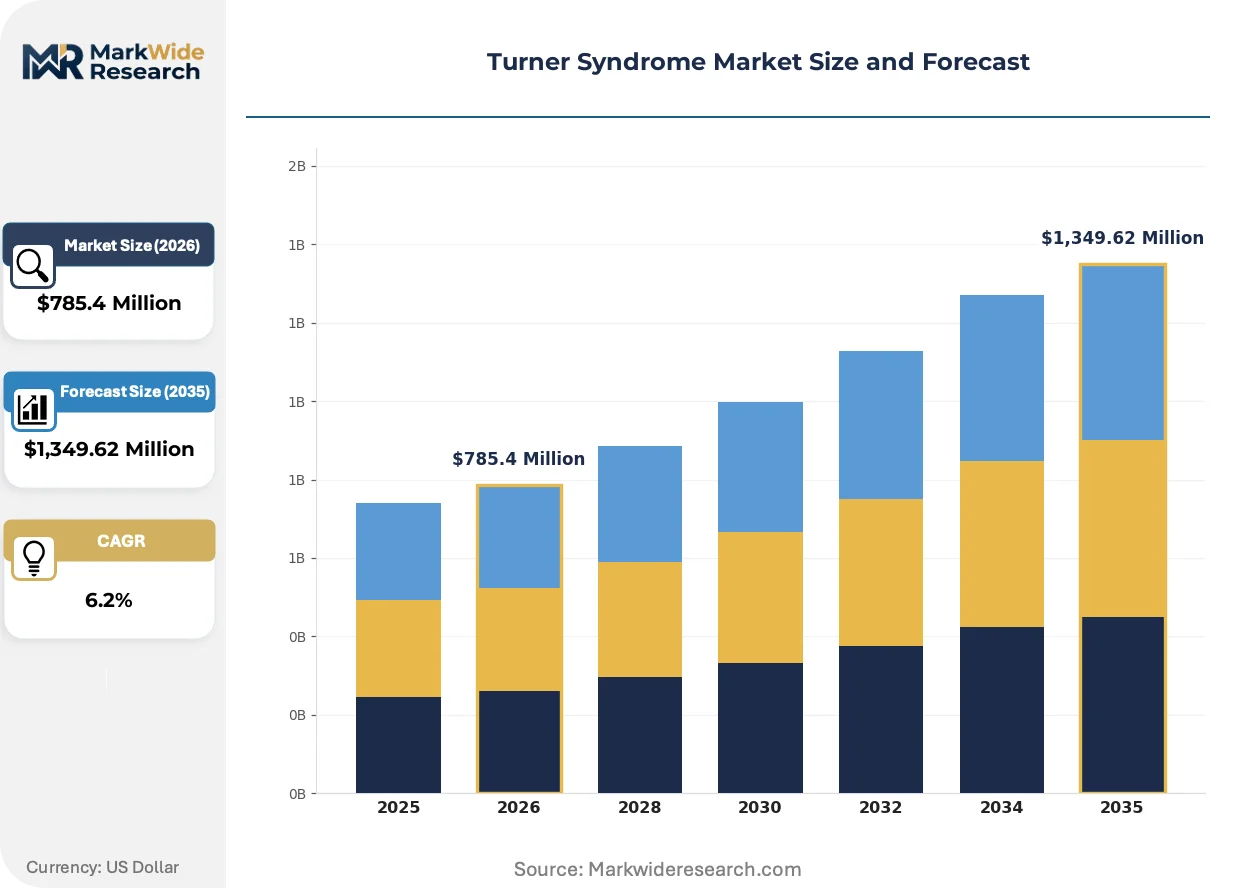
The central dynamic shaping the Turner Syndrome market is the therapeutic pivot from managing isolated symptoms, such as short stature, towards a comprehensive, lifelong care model. This shift is driven by deeper clinical understanding of the syndrome's multifaceted comorbidities, creating demand for integrated treatment protocols.
Growth Catalysts
- Regulatory Incentives:Frameworks like the FDA's Orphan Drug Designation and the EMA's similar programs are reducing development timelines and costs for novel therapies, encouraging investment in a previously niche area.
- Expanded Clinical Applications:The increasing use of established hormonal therapies to manage a wider range of associated conditions, including metabolic and cardiovascular risks in adult patients, is broadening the addressable market.
- Diagnostic Advancement:Higher rates of early diagnosis in developed nations, particularly the United States, are a direct result of improved prenatal screening technologies and greater awareness within pediatric healthcare systems.
Market Restraints
- High Treatment Cost:The substantial cost associated with long-term growth hormone regimens places a significant financial strain on patients and national healthcare budgets, restricting access in regions with limited reimbursement.
- Symptomatic Treatment Limitation:Current therapeutic options address symptoms rather than the underlying genetic cause, meaning there is no curative therapy, which caps the ultimate clinical and commercial potential of existing products.
- Substitution by Generics:The eventual patent expiration for leading growth hormone formulations introduces competition from biosimilars, which can lead to price erosion and margin pressure for originator companies.
Strategic Opportunities
- Geographic Expansion:There is a significant opportunity in improving diagnostic capabilities and establishing treatment infrastructure in large, underserved populations, particularly in countries like China and Brazil.
- Adult Patient Focus:Developing therapies specifically for the adult Turner Syndrome population, addressing long-term health issues like osteoporosis and infertility, represents an untapped area for growth.
- Technology Convergence:Integrating gene-editing technologies with advanced drug delivery systems could create a new class of therapies that offer more durable or even corrective outcomes beyond current hormonal treatments.
Industry Challenges
- Specialist Scarcity:A shortage of pediatric endocrinologists and clinical geneticists in many healthcare systems creates a bottleneck, delaying diagnosis and the initiation of appropriate long-term management plans.
- Treatment Adherence:Ensuring consistent patient compliance with complex, long-term daily injection schedules for growth hormone therapy remains a significant operational hurdle for caregivers and healthcare providers.
- Reimbursement Complexity:Obtaining favorable coverage and payment codes from public and private payers for combination therapies that address multiple symptoms simultaneously is an ongoing challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turner Syndrome Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,349.62 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Hormones, Estrogen Therapy, Cardiovascular Treatment, Fertility Solutions Application: Endocrine Management, Cardiovascular Care, Reproductive Assistance, Psychological Counseling End User: Specialized Clinics, Pediatric Units, Fertility Centers, Genetic Counseling Facilities Delivery Mode: Injectables, Oral Medication, Transdermal Patches, Assisted Reproductive Techniques |
| Companies Covered | Pfizer Inc., Novo Nordisk A/S, Eli Lilly and Company, Novartis AG, Ferring Pharmaceuticals, F. Hoffmann-La Roche Ltd, AstraZeneca, Merck KGaA, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turner Syndrome Market Strategic Shifts & Innovations
The market's focus is evolving from a pediatric-centric growth model to a more holistic approach emphasizing lifelong health management. This transition reflects a greater understanding of adult comorbidities and spurs innovation in therapies tailored to different life stages of a patient with Turner Syndrome.
Digital Health Integration
Digital health platforms and connected drug delivery devices, such as smart injection pens, provide real-time monitoring of treatment adherence and patient biometrics. Pediatric endocrinology clinics and specialized care units are adopting these systems to improve patient engagement and gather longitudinal data. This integration of digital tools with hormonal therapy is miniaturizing the feedback loop between patient behavior and clinical oversight, allowing for more timely and precise interventions.
Real-World Evidence Mandates
Emphasis from regulators like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) on real-world evidence (RWE) is altering clinical development strategies. This requires manufacturers to collect and analyze long-term data on treatment safety and effectiveness outside of traditional trial settings. The growth hormone and estrogen therapy segments are most affected, now building frameworks to demonstrate sustained clinical value to payers and health authorities.
Patient-Centric Advocacy
Patient advocacy groups are exerting greater influence on research agendas, clinical trial design, and treatment guidelines. This shift is challenging the traditional, clinician-dominated model by integrating patient-reported outcomes and quality-of-life metrics into the value assessment of therapies. This trend is particularly visible in North America and Europe, where organized patient networks collaborate directly with researchers, pharmaceutical companies, and regulatory bodies to shape care standards.
Turner Syndrome Market Segmentation
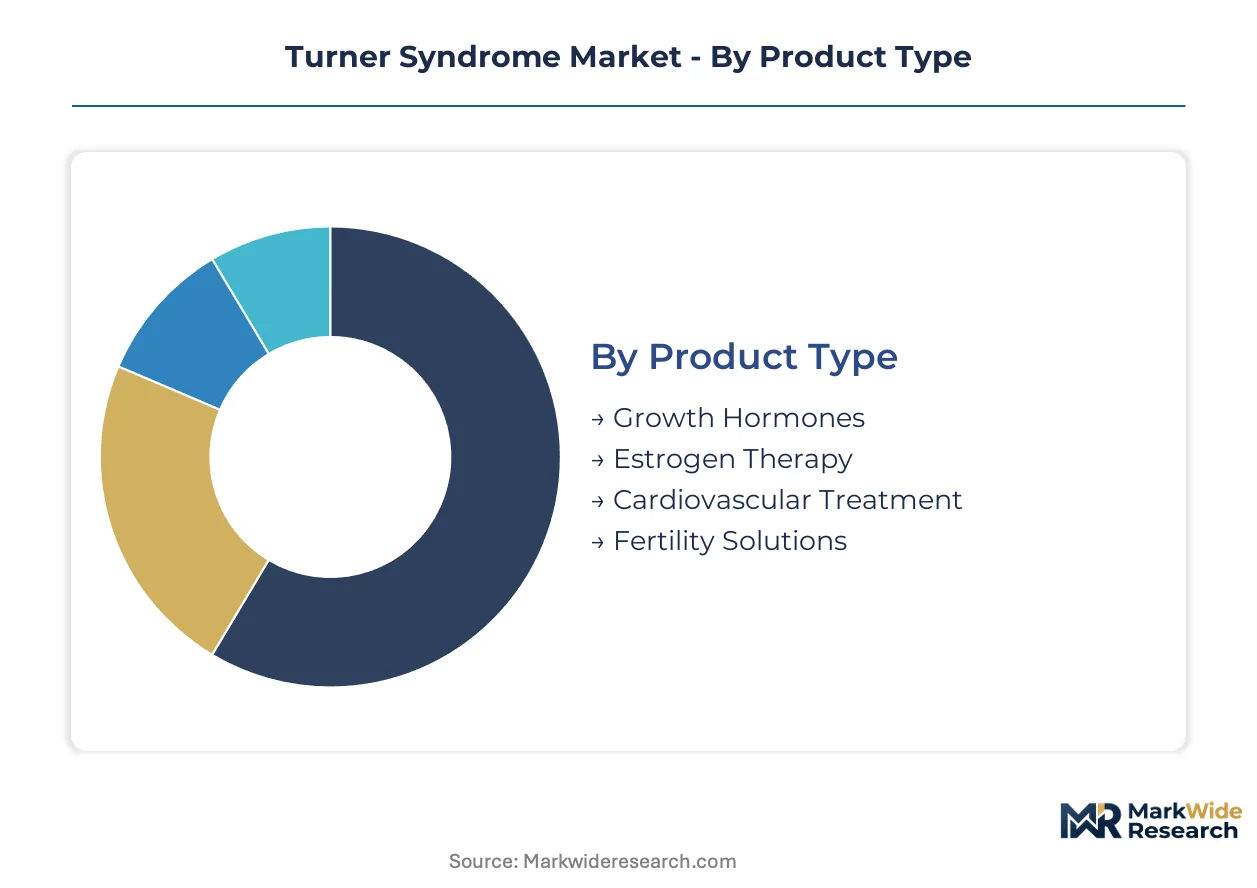
The Turner Syndrome market segmentation provides a granular view of therapeutic interventions and patient management strategies. Understanding these distinct segments helps manufacturers and healthcare providers tailor solutions to specific clinical needs and optimize resource allocation. This detailed breakdown highlights areas of established demand and emerging growth across the treatment landscape.
Product Type:
The geographic distribution of product type demand for Turner Syndrome therapies reveals distinct patterns, with established hormonal treatments dominating in mature markets like the United States and European Union member states.
- Growth Hormones:These recombinant protein therapies stimulate linear growth in pediatric patients with short stature, a common feature of Turner Syndrome. Demand concentrates heavily in developed nations where early diagnosis and long-term treatment protocols are well-established, driven by national health guidelines and robust reimbursement systems.
- Estrogen Therapy:This treatment replaces missing sex hormones, inducing puberty and maintaining bone density and cardiovascular health in adolescent and adult patients. Its usage is widespread globally, particularly in regions with advanced gynecological care, to manage ovarian failure and mitigate long-term health risks.
- Cardiovascular Treatment:These pharmaceutical interventions and surgical procedures manage congenital heart defects and other cardiovascular complications associated with the syndrome.
- Fertility Solutions:These include assisted reproductive technologies and ovum donation programs, addressing infertility challenges faced by many adult patients.
Growth Hormones commands the established base. The steepest expansion runs through Fertility Solutions.
Application:
Segmenting by application highlights the evolving clinical focus, moving from isolated symptom management towards integrated, comprehensive care protocols for individuals with Turner Syndrome.
- Endocrine Management:This application encompasses therapies targeting hormonal imbalances, primarily growth hormone deficiency and ovarian failure, to promote normal development and mitigate long-term health risks. Demand for this application is consistently high across all age groups, forming the core of Turner Syndrome treatment.
- Cardiovascular Care:This involves monitoring and treating congenital heart defects, hypertension, and other vascular anomalies, which are prevalent comorbidities in Turner Syndrome patients. Specialized cardiology units within hospitals in Germany and France regularly address these complex conditions.
- Reproductive Assistance:This application focuses on fertility preservation, in vitro fertilization, and other methods to support reproductive options for adult patients.
- Psychological Counseling:This provides essential support for patients and families, addressing emotional and developmental challenges associated with the condition.
Endocrine Management maintains the largest share of therapeutic interventions. Cardiovascular Care shows the most significant potential for future expansion.
End User:
The end-user landscape reflects the specialized nature of Turner Syndrome care, emphasizing facilities equipped for long-term patient management and multidisciplinary support.
- Specialized Clinics:These outpatient facilities, often affiliated with larger hospitals, offer multidisciplinary care, including endocrinology, cardiology, and genetics, for Turner Syndrome patients. These clinics serve as central hubs for diagnosis, treatment initiation, and ongoing monitoring across the patient's lifespan.
- Pediatric Units:These hospital departments and specialized children's hospitals focus on early diagnosis and management of Turner Syndrome in infants, children, and adolescents. Pediatric units in countries like Canada and Australia are crucial for initiating growth hormone therapy and addressing early developmental concerns.
- Fertility Centers:These specialized clinics provide reproductive services and counseling, primarily for adult women with Turner Syndrome seeking family planning options.
- Genetic Counseling Facilities:These centers offer diagnostic testing, risk assessment, and support for families navigating a Turner Syndrome diagnosis.
Specialized Clinics serve the broadest patient population. Fertility Centers are poised for rapid development.
Delivery Mode:
Delivery mode segmentation underscores the technological advancements and patient convenience considerations influencing therapeutic administration for Turner Syndrome treatments.
- Injectables:This mode primarily includes subcutaneous injections for growth hormone therapy, requiring daily or weekly administration, often self-administered by patients or caregivers. Smart injection pens and auto-injectors are improving adherence and ease of use in regions like Japan and the UK.
- Oral Medication:This category encompasses various drugs, including certain cardiovascular medications and supplements, taken by mouth. Oral formulations offer convenience and are typically used for managing co-morbidities rather than primary hormonal replacement.
- Transdermal Patches:These patches deliver estrogen through the skin, offering a convenient and sustained-release option for hormone replacement therapy.
- Assisted Reproductive Techniques:These advanced medical procedures, including in vitro fertilization, facilitate pregnancy for individuals facing infertility due to Turner Syndrome.
Injectables maintain a foundational role in treatment delivery. Assisted Reproductive Techniques are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for Turner Syndrome therapies exhibits asymmetry, with the United States maintaining higher price points due to advanced market access frameworks. Conversely, European markets often prioritize cost-containment measures, influencing reimbursement structures and product availability. This divergence shapes investment priorities and market entry strategies for pharmaceutical companies.
United States
High diagnostic rates and a robust healthcare infrastructure drive demand for growth hormone and estrogen therapies. The FDA's Orphan Drug Designation program accelerates novel therapeutic development, offering incentives for rare disease treatments. Major biotech clusters in Boston and San Francisco foster significant research and development activity.
Germany
Germany's comprehensive healthcare system supports long-term management protocols for Turner Syndrome patients, emphasizing integrated care. The European Medicines Agency (EMA) approval processes govern market access for new pharmaceutical interventions. Pharmaceutical and medical device companies in the Munich and Berlin regions actively engage in clinical trials.
Japan
Advanced medical technologies and a focus on patient adherence contribute to consistent demand for injectable growth hormone therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees the rigorous approval of new drug formulations and delivery systems. Tokyo's research hospitals and pharmaceutical companies lead in digital health integration for chronic conditions.
United Kingdom
The National Health Service (NHS) provides structured care pathways, ensuring access to established hormonal treatments for eligible patients. The Medicines and Healthcare products Regulatory Agency (MHRA) evaluates the safety and efficacy of new therapies entering the market. London's specialized pediatric endocrinology clinics are pivotal for diagnosis and ongoing patient management.
China
Expanding healthcare infrastructure and increasing awareness are improving diagnostic capabilities for Turner Syndrome in urban centers. The National Medical Products Administration (NMPA) is streamlining approval processes for essential medicines, including growth hormones. Shanghai and Beijing are emerging as key hubs for pharmaceutical research and clinical development.
Turner Syndrome Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Turner Syndrome market. The competitive structure is tiered, featuring large diversified pharmaceutical companies alongside specialized biotechnology firms and focused medical device manufacturers. Key strategic archetypes include comprehensive solution providers and niche innovators. Dominant competitive moves center on portfolio diversification to address comorbidities and significant R&D investment in novel genetic therapies.
Specialized pharmaceutical companies, such as Novo Nordisk A/S, exemplify a focus on specific therapeutic areas like growth hormone therapy. Pfizer Inc. represents the archetype of a diversified pharmaceutical giant, leveraging its broad pipeline to address associated cardiovascular and metabolic comorbidities. Ferring Pharmaceuticals occupies a position as a specialist in fertility solutions and estrogen replacement therapies, catering to adolescent and adult patient cohorts.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Novartis AG |
| Ferring Pharmaceuticals |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca |
| Merck KGaA |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Extended lead times for recombinant growth hormone production directly influence supply chain design and pricing power in the Turner Syndrome market. This structural characteristic favors vertically integrated pharmaceutical companies with established manufacturing capabilities.
Pricing Analysis
Configured-to-order pricing for advanced fertility solutions contrasts sharply with standard pricing for established hormonal therapies in the Turner Syndrome market. The dominant pricing model is a hybrid, combining value-based approaches for novel interventions with contract-based long-term offtake for foundational treatments like growth hormones. Price differentiation stems from regulatory approval status and brand premium, particularly for complex biologics. Downward pricing pressure intensifies for growth hormone therapies due to impending biosimilar competition, making national healthcare systems like the UK's NHS highly price-sensitive.
Supply Chain Analysis
Specialized biopharmaceutical manufacturing capacity underwrites the supply of recombinant growth hormones and novel genetic therapies for Turner Syndrome. Geographic supply concentration centers in the United States, Germany, and Japan, reflecting advanced biotech infrastructure. Supply chains depend on critical inputs like recombinant proteins and advanced drug delivery device components, creating single-source vulnerability for proprietary active pharmaceutical ingredients. Distribution primarily runs through direct-to-specialized clinic channels and established pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Turner Syndrome market presents a fragmentation opportunity, driven by a demand-side shift towards integrated, lifelong care models. This evolution creates distinct niches for specialized therapeutic interventions across patient age groups.
For Market Incumbents: Compound existing market leadership by diversifying product portfolios to address associated cardiovascular and metabolic comorbidities. This move mitigates the threat of biosimilar competition in the growth hormone segment and strengthens long-term patient engagement. Invest in clinical trials demonstrating the holistic benefits of combination therapies to secure favorable reimbursement from regulatory bodies like the FDA and EMA. Focus R&D on novel genetic therapies to maintain a competitive edge against emerging specialized biotechnology firms.
For New Entrants and Emerging Players: Lead with innovative gene-editing technologies or advanced drug delivery systems targeting the underlying genetic cause of Turner Syndrome. The adult patient population, particularly for long-term health issues like osteoporosis and infertility, represents a highly penetrable segment. A go-to-market angle focusing on superior patient outcomes and reduced treatment burden will resonate with specialized clinics. Leverage digital health integration to demonstrate real-world evidence and differentiate offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a specialized therapeutic platform play because of the chronic, lifelong nature of Turner Syndrome management. Acquisition targets should be niche innovators developing gene-editing solutions or companies with strong intellectual property in fertility preservation. A critical signal to watch is the successful completion of Phase 2 clinical trials for non-hormonal, disease-modifying therapies. Investment in companies capable of navigating complex regulatory pathways will yield sustained returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification into Comorbidities | Pfizer Inc. can address a wider range of patient needs, strengthening its market position against specialized firms. |
| Investment in Gene-Editing Technologies | This move could create disease-modifying therapies, shifting the treatment paradigm beyond symptomatic management. |
| Expansion of Fertility Solutions | Ferring Pharmaceuticals can capitalize on the growing demand for reproductive assistance among adult patients. |
| Digital Health Integration | This enhances patient adherence and provides valuable real-world evidence for regulatory submissions and reimbursement. |
| Geographic Market Penetration in Emerging Economies | This expands access to treatment for underserved populations, particularly in countries like China and Brazil. |
Research Approach
A standing panel of pediatric endocrinologists, clinical geneticists, pharmaceutical R&D executives, and patient advocacy leaders provided ongoing calibration for this analysis. The approach combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data sources included FDA filings, EMA submissions, ClinicalTrials.gov, and company annual reports. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market sizing.
Market outputs were consistently validated against external benchmarks and peer-reviewed literature to ensure robustness. The analytical framework modeled segmentation dimensions including product type, application, end-user, delivery mode, and regional regulatory clusters across the analysis window. Compound annual growth rates were derived through a proprietary algorithm considering historical performance and projected adoption rates. Key forecast inputs included diagnostic rates in developed nations and therapeutic pipeline advancements.
Forecasts assume regulatory continuity in US FDA and European Medicines Agency regimes; material policy shifts would require re-modeling market dynamics. The analysis reflects assumptions regarding therapeutic pipeline success and patient access initiatives, acknowledging that unforeseen breakthroughs in genetic therapies or significant changes in reimbursement policies could revise projections. Practitioners should keep alternative scenarios live as therapeutic innovations and healthcare funding models evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Rare Neurodegenerative Disease Treatment Market