
 Ambulatory Heart Monitor Market | 2026-2036
Ambulatory Heart Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Heart Monitor Market Analytics
Multi-source component procurement is consolidating as device manufacturers reduce supplier fragmentation for cardiac sensors and telemetry modules. Medtronic leverages captive manufacturing across its cardiac rhythm portfolio to sustain margin control. Abbott Laboratories anchors North American distribution through integrated health system contracts. Philips competes on cloud-based telemetry platforms that extend service revenue beyond hardware sales.
Ambulatory heart monitors are portable electrocardiographic devices that record cardiac electrical activity over extended periods, typically 24 to 48 hours for Holter systems and up to 30 days for patch-based monitors, enabling detection of intermittent arrhythmias outside clinical settings. These devices transmit data via cellular or Bluetooth connectivity to centralized monitoring centers for physician interpretation. Mobile cardiac telemetry represents the fastest-expanding product category as payers expand reimbursement for real-time arrhythmia detection over traditional event recorders. Cloud-based solutions command disproportionate R&D investment because recurring platform fees generate higher lifetime value than standalone hardware sales in the technology segment.
FDA premarket notification requirements and ISO 13485 quality management standards govern device approval and manufacturing compliance for ambulatory heart monitors in the United States. The EU Medical Device Regulation mandates clinical evidence and notified body certification for wearable cardiac devices entering European markets. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under EUDAMED as connected cardiac devices face escalating data integrity scrutiny.
Market Dynamics
Cardiology clinics are consolidating their supplier base for remote monitoring systems as reimbursement pathways stabilize, creating procurement concentration that favors integrated platform vendors over standalone hardware manufacturers.
Growth Catalysts
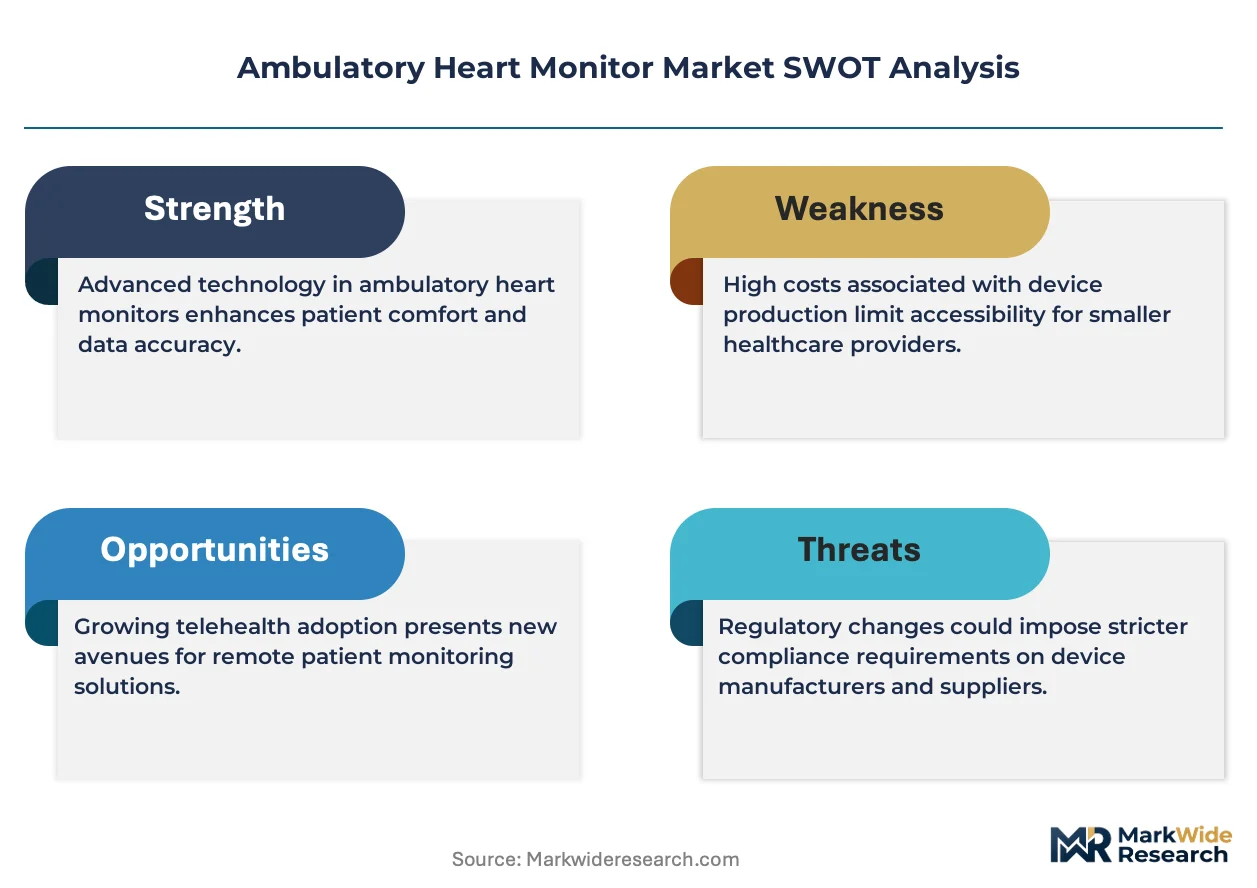
- FDA 510(k) Pathway Compression:The FDA has streamlined premarket notification reviews for wearable ECG devices, reducing clearance timelines and accelerating commercialization for patch-based monitors.
- German Cardiac Network Integration:Germany's hospital federations are embedding ambulatory monitors into integrated care contracts, creating concentrated demand pull across Bavaria and North Rhine-Westphalia.
- Mobile Cardiac Telemetry Reimbursement:US commercial payers and Medicare Advantage plans have expanded coverage codes for real-time arrhythmia detection, displacing traditional event recorders in outpatient settings.
Market Restraints
- Semiconductor Component Concentration:Telemetry modules and low-power Bluetooth chipsets face supply bottlenecks concentrated among Taiwanese foundries, creating production volatility for device assemblers.
- EU MDR Clinical Evidence Burden:The EU Medical Device Regulation mandates extended clinical follow-up for wearable cardiac devices, extending certification timelines and freezing smaller manufacturers from European markets.
- Smartwatch ECG Substitution:Consumer-grade ECG capabilities in Apple Watch and Samsung Galaxy devices are capturing low-acuity monitoring demand, compressing addressable market for prescription-grade Holter systems.
Strategic Opportunities
- India Outpatient Cardiology Expansion:India's tier-2 and tier-3 cities present underpenetrated demand as Apollo Hospitals and Max Healthcare deploy remote monitoring for post-intervention follow-up.
- AI-Enabled Arrhythmia Detection:Machine learning algorithms integrated with cloud telemetry platforms are automating preliminary ECG interpretation, reducing cardiologist review burden and enabling scale.
- Japan Super-Aging Policy Alignment:METI's healthcare robotics and remote monitoring incentives are creating procurement mandates for home-based cardiac surveillance in Japan's prefectural health systems.
Industry Challenges
- ISO 13485 Quality System Maintenance:Device manufacturers face escalating audit intensity as notified bodies apply stricter risk management documentation requirements for software-as-medical-device components.
- Cybersecurity Validation Complexity:FDA's post-market cybersecurity guidance demands continuous vulnerability monitoring and patch management, requiring dedicated engineering resources that strain mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Heart Monitor Market |
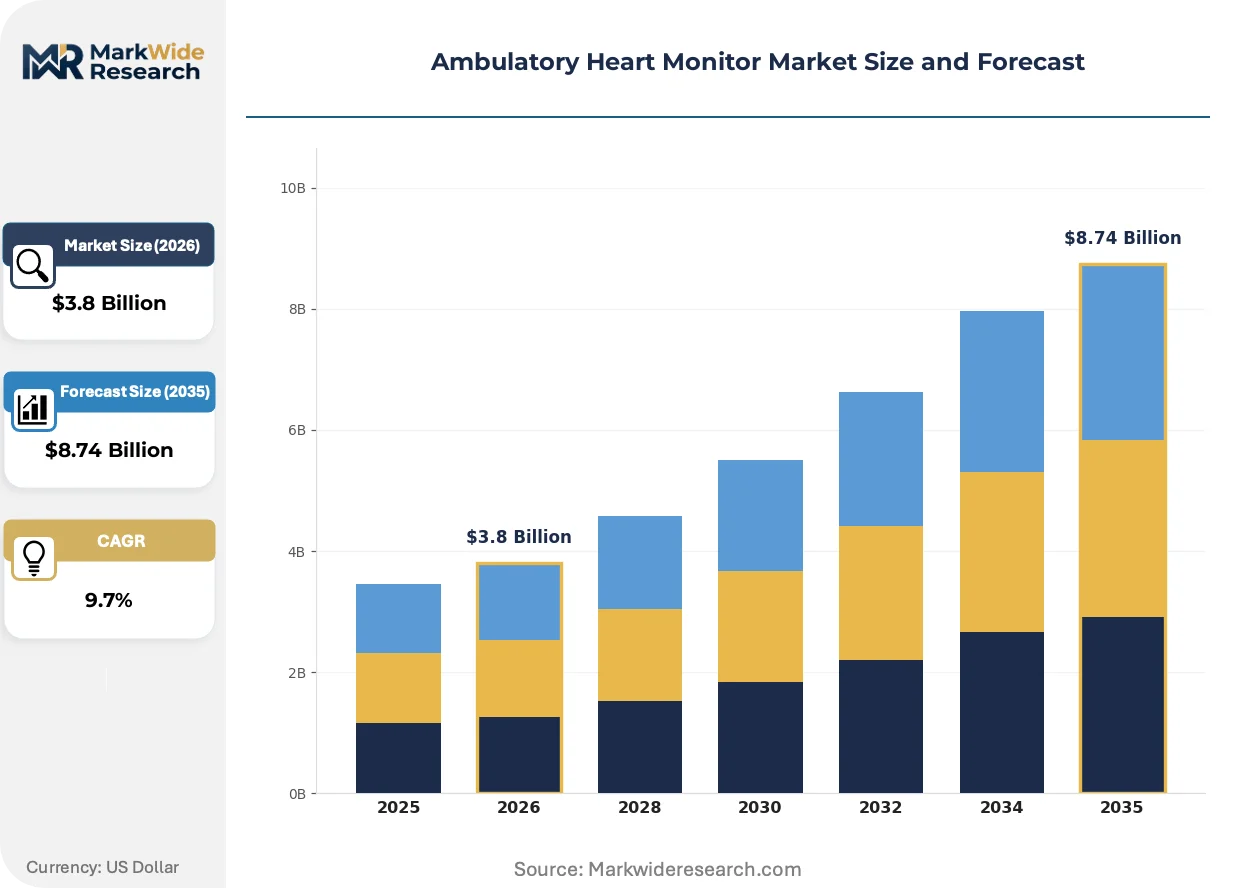
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitor, Event Recorder, Mobile Cardiac Telemetry, Wireless Monitor End User: Hospitals, Cardiology Clinics, Home Care, Research Institutions Technology: ECG Monitoring, Cloud-Based Solutions, Wearable Devices, Remote Monitoring Application: Arrhythmia Detection, Post-Operative Monitoring, Device Evaluation, Patient Management |
| Companies Covered | Abbott Laboratories, Medtronic, Boston Scientific Corporation, GE HealthCare, Koninklijke Philips, iRhythm Technologies, BioTelemetry, ZOLL Medical Corporation, NIHON KOHDEN CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Heart Monitor Market Evolving Landscape
Algorithmic interpretation and cloud-native architectures are displacing hardware-centric business models across the cardiac monitoring value chain. Platform economics now govern competitive positioning.
Artificial intelligence embedded in ECG analysis pipelines is automating beat classification and anomaly flagging before cardiologist review. Academic medical centers in the US and Germany are deploying these tools to manage telemetry volume growth without proportional specialist hiring. The technology is automating preliminary diagnostic workflows and compressing report turnaround times from hours to minutes.
The EU Medical Device Regulation's software classification rules are redefining regulatory boundaries for AI-enabled cardiac devices. Manufacturers must now demonstrate clinical validation across intended patient populations, not just algorithmic accuracy. Cloud-based telemetry platforms with embedded decision support face the steepest compliance burden, driving consolidation toward vendors with dedicated regulatory affairs infrastructure.
Hospital procurement departments are consolidating vendor relationships for cardiac monitoring into multi-year enterprise agreements. Integrated delivery networks in the US are replacing transactional device purchases with subscription models bundling hardware, software, and interpretation services. This shift is most visible in Texas and Florida health systems where HCA and Tenet have standardized on single-platform deployments.
Ambulatory Heart Monitor Market Segmentation
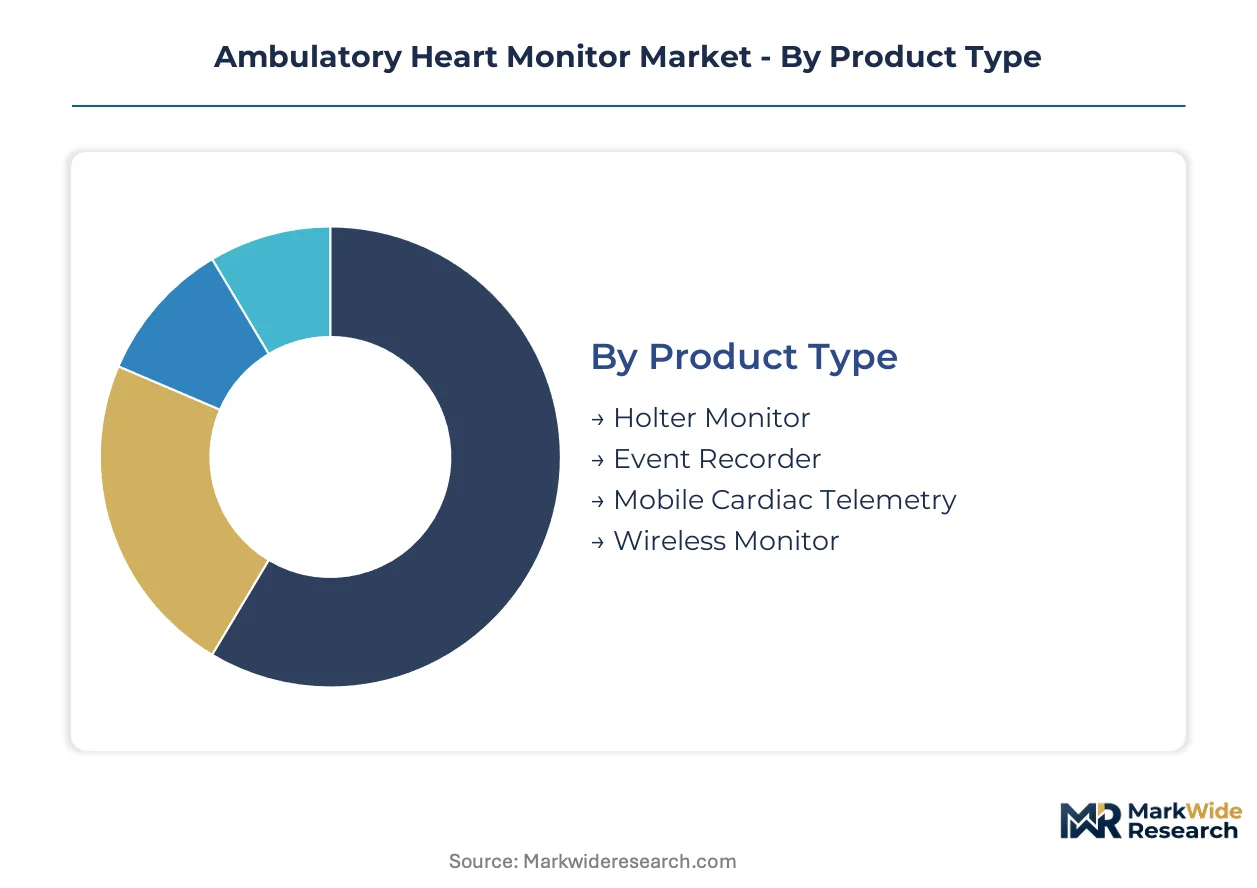
Device replacement cycles and technology refresh rates vary dramatically across ambulatory heart monitor segments. Procurement decisions increasingly hinge on interoperability with existing telemetry infrastructure rather than standalone hardware specifications.
Product Type:
Upgrade cycles range from 3-year Holter replacements to continuous patch-based telemetry refreshes, with reimbursement stability dicting replacement timing across health systems.
- Holter Monitor:Traditional wired electrode systems record 24-48 hours of continuous ECG data on portable recorders. Demand concentrates in Germany's statutory health insurance networks where established reimbursement codes support routine arrhythmia screening; supply bottlenecks in Taiwanese ASIC fabrication constrain production scaling.
- Mobile Cardiac Telemetry:Real-time cellular-transmitting devices enable immediate arrhythmia notification and intervention. US Medicare Advantage plans and commercial payers have expanded coverage for this modality, displacing event recorders in outpatient cardiology practices across Texas and Florida health systems.
- Event Recorder:Patient-activated or auto-triggered devices capture episodic cardiac events over weeks to months.
- Wireless Monitor:Bluetooth-enabled systems stream data to paired smartphones or dedicated hubs.
Volume placements concentrate in Holter systems; the faster expansion belongs to mobile cardiac telemetry.
End User:
Customer procurement sophistication spans from centralized hospital IT governance to fragmented home care distributor relationships, shaping contract structures and service bundling.
- Hospitals:Acute care facilities deploy ambulatory monitors for pre-discharge arrhythmia risk stratification and post-intervention surveillance. Integrated delivery networks in the United States negotiate enterprise-wide telemetry contracts bundling hardware, cloud platforms, and interpretation services.
- Cardiology Clinics:Outpatient specialty practices represent the fastest-expanding installation base as remote patient monitoring reimbursement stabilizes. Bavaria and North Rhine-Westphalia hospital federations embed these devices into integrated care contracts, creating concentrated demand pull.
- Home Care:Post-acute and aging-in-place settings deploy monitors for chronic disease management outside institutional walls.
- Research Institutions:Academic medical centers utilize ambulatory monitors for clinical trial endpoints and algorithm validation studies.
Cardiology clinics are gaining share fastest; hospitals retain the largest installed base by device count.
Technology:
Platform architecture choices determine regulatory pathway complexity and recurring revenue potential, with cloud-native systems commanding disproportionate R&D investment.
- Cloud-Based Solutions:Centralized telemetry platforms aggregate multi-patient data streams for remote interpretation and automated alerting. EU MDR software classification rules impose clinical validation requirements across intended patient populations, favoring vendors with dedicated regulatory affairs infrastructure.
- Remote Monitoring:Real-time data transmission to centralized monitoring centers enables immediate clinical response. FDA post-market cybersecurity guidance demands continuous vulnerability monitoring and patch management, requiring dedicated engineering resources.
- ECG Monitoring:Core electrocardiographic signal acquisition and processing remains the foundational technical layer.
- Wearable Devices:Patch-based and wrist-worn form factors prioritize patient comfort and extended wear compliance.
Revenue concentration sits with cloud-based platforms; wearable devices are climbing the fastest on patient preference tailwinds.
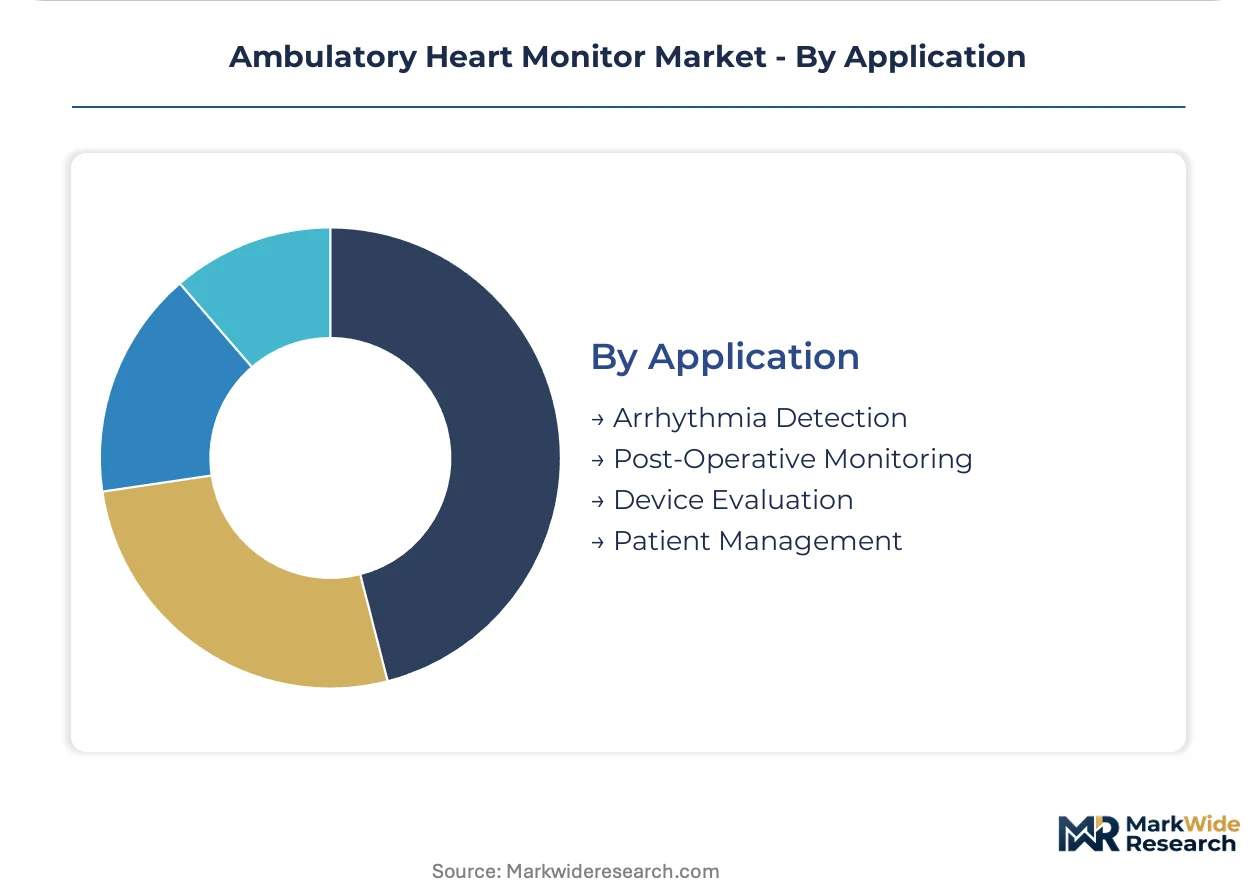
Application:
Clinical use case specificity drives sensor configuration, algorithm training, and reimbursement coding requirements across the product portfolio.
- Arrhythmia Detection:Primary diagnostic application targeting atrial fibrillation, ventricular tachycardia, and conduction abnormalities. AI-enabled beat classification algorithms embedded in cloud telemetry platforms automate preliminary ECG interpretation, reducing cardiologist review burden at US and German academic medical centers.
- Post-Operative Monitoring:Surveillance following cardiac catheterization, ablation, or device implantation. Apollo Hospitals and Max Healthcare in India deploy remote monitoring for post-intervention follow-up in tier-2 and tier-3 cities.
- Device Evaluation:Assessment of pacemaker, ICD, and CRT function through ambulatory ECG correlation.
- Patient Management:Chronic disease surveillance and medication efficacy monitoring in longitudinal care programs.
Arrhythmia detection commands the largest procedure volume; post-operative monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiology clinics in Germany are expanding procurement of remote monitoring systems faster than any other national market, while FDA clearance pathways for wearable ECG devices compress timelines in the United States. Demand concentration spans three continents with distinct reimbursement and regulatory architectures shaping adoption velocity.
United States
Medicare Advantage plans and commercial payers have expanded coverage codes for real-time arrhythmia detection, displacing traditional event recorders in outpatient settings. FDA post-market cybersecurity guidance demands continuous vulnerability monitoring and patch management for connected cardiac devices. Texas and Florida health systems led by HCA and Tenet have standardized on single-platform deployments across integrated delivery networks.
Germany
Hospital federations in Bavaria and North Rhine-Westphalia are embedding ambulatory monitors into integrated care contracts, creating concentrated demand pull across statutory health insurance networks. EU Medical Device Regulation mandates extended clinical follow-up for wearable cardiac devices, extending certification timelines. Berlin-Brandenburg clusters host regulatory affairs infrastructure serving manufacturers navigating MDR compliance.
India
Apollo Hospitals and Max Healthcare are deploying remote monitoring for post-intervention follow-up in tier-2 and tier-3 cities where outpatient cardiology infrastructure is expanding. CDSCO medical device regulations govern import and manufacturing compliance for wearable cardiac monitors. Maharashtra and Karnataka urban centers anchor private hospital chain expansion driving device procurement.
Japan
METI's healthcare robotics and remote monitoring incentives are creating procurement mandates for home-based cardiac surveillance in prefectural health systems. PMDA quality management standards apply to software-as-medical-device components in cloud telemetry platforms. Kanto region hospitals around Tokyo are piloting AI-enabled arrhythmia detection integrated with national health insurance reimbursement pathways.
United Kingdom
NHS Long Term Plan targets for cardiovascular disease prevention are accelerating ambulatory monitor deployment in community cardiology services. MHRA post-Brexit regulatory framework maintains alignment with EU MDR clinical evidence requirements for wearable devices. London and Southeast England academic medical centers are validating machine learning algorithms for automated ECG interpretation at scale.
Ambulatory Heart Monitor Market Competitive Landscape
Platform consolidation dominates the current landscape as integrated vendors absorb standalone hardware manufacturers. The vendor base stratifies across three tiers: diversified medical technology conglomerates with cardiac rhythm portfolios, pure-play remote monitoring specialists, and emerging wearable device entrants. Competitive positioning hinges on captive manufacturing control, cloud-native telemetry architecture, and enterprise health system contracting scale. M&A activity and strategic partnerships represent the dominant competitive moves reshaping market structure.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic exemplify archetypes anchored in integrated health system contracting and captive manufacturing control respectively. iRhythm Technologies occupies a position within the pure-play remote monitoring specialist tier. These three companies represent distinct strategic postures: Abbott through North American distribution integration, Medtronic through backward integration into cardiac sensor production, and iRhythm through cloud-based telemetry platform specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| GE HealthCare |
| Koninklijke Philips |
| iRhythm Technologies |
| BioTelemetry |
| ZOLL Medical Corporation |
| NIHON KOHDEN CORPORATION |
| Others |
Value Network & Pricing Analysis
Patch-based telemetry manufacturing migration toward automated surface-mount assembly lines simultaneously compresses per-unit sensor costs and concentrates production among Taiwanese and South Korean contract manufacturers with capital-intensive cleanroom capacity. This dual shift rewards scaled device vendors while squeezing mid-tier competitors unable to amortize qualification costs across sufficient volume.
Pricing Analysis
Extended warranty and cloud-platform subscription bundling separates premium-tier vendors from hardware-only competitors in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification depth, and real-time interpretation service inclusion. Cost compression in economy-tier Holter systems is intensifying because consumer-grade smartwatch ECG substitution erodes addressable volume. Hospital purchasing committees demonstrate lowest price sensitivity due to bundled enterprise contracts, while independent cardiology clinics in India negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Biomedical engineering talent scarcity in Taoyuan and Seoul metropolitan clusters constrains expansion of qualified cleanroom technicians for cardiac sensor fabrication. Component sourcing draws from Taiwan for Bluetooth low-energy chipsets, South Korea for display modules, and Malaysia for medical-grade polymer housings. Single-source vulnerability concentrates in Taiwanese foundry capacity for application-specific integrated circuits serving telemetry modules. Distribution runs through integrated delivery network procurement consortia in Texas and Florida, supplemented by regional medical device distributors serving German hospital federations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for medical-grade ASICs prop pricing power for incumbent device manufacturers with secured wafer allocations. Supply bottlenecks in Taiwanese telemetry module production insulate premium-tier vendors from price erosion.
For Market Incumbents: Cement cloud-platform subscription retention through multi-year enterprise agreements with US integrated delivery networks, offsetting margin pressure from smartwatch ECG substitution in low-acuity segments. Deepen backward integration into cardiac sensor production to secure supply continuity against Taiwanese foundry allocation constraints. Prioritize ISO 13485 quality system investments to accelerate EU MDR certification timelines and freeze smaller competitors from European market access. For New Entrants and Emerging Players: AI-enabled arrhythmia detection algorithms offer a technology-first wedge into interpretation service contracts at US academic medical centers overwhelmed by telemetry volume growth. Target India's tier-2 and tier-3 cities where Apollo Hospitals and Max Healthcare expansion outpaces established vendor coverage. Pursue CDSCO regulatory pathway alignment alongside hospital chain partnership development to bypass fragmented distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisitions by diversified medtech conglomerates seeking cloud telemetry capabilities. Five-to-ten year viability favors vendors with captive manufacturing and recurring SaaS revenue exceeding fifty percent of total mix. Watch FDA cybersecurity guidance enforcement intensity as inflection indicator for compliance cost burden and mid-cap consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Telemetry Platform Integration | Recurring SaaS revenue from HCA and Tenet enterprise contracts exceeds hardware lifetime value. |
| FDA 510(k) Cybersecurity Compliance | Continuous vulnerability monitoring mandates strain mid-cap engineering resources and accelerate consolidation. |
| EU MDR Clinical Evidence Buildout | Berlin-Brandenburg regulatory infrastructure supports notified body navigation for wearable cardiac devices. |
| AI-Enabled ECG Interpretation Deployment | Machine learning automation at German academic centers reduces cardiologist review burden and enables scale. |
| India Distribution Channel Expansion | Maharashtra and Karnataka hospital chain partnerships bypass fragmented medical device distributor networks. |
Research Methodology
Multi-period observation of FDA clearance timelines, CMS reimbursement code expansions, and EU MDR certification completion rates anchored the trend analysis, supplemented by interviews with cardiology practice administrators, hospital biomedical engineering directors, GPO contracts managers, and telemetry platform product executives. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare fee schedules, EUDAMED post-market surveillance records, and hospital procurement system contract disclosures. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocation models.
Input-output matrix modeling connected semiconductor foundry capacity utilization, telemetry module production yields, and cloud platform subscriber growth to revenue projections across the analysis window. Segmentation dimensions spanned product type, end-user facility category, technology architecture, and clinical application intensity. CAGRs derived from logistic diffusion curves fitted to reimbursement pathway maturation and technology substitution elasticities. Forecast inputs included Medicare Advantage penetration rates and German statutory health insurance integrated care contract expansion.
Several conditions sit outside the modeled scope, including unforeseen FDA cybersecurity enforcement actions, Taiwan semiconductor supply disruptions, and abrupt smartwatch ECG diagnostic accuracy improvements. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway continuity. Material deviation in Taiwanese foundry allocation priority or EU MDR audit intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Coronary Pressure Monitors Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Infusion Rate Monitoring Market
Patient Monitoring
South America Respiratory Monitoring Market