

Copper and Copper Alloy Scrap and Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Copper and Copper Alloy Scrap and Recycling Market Insights
The EU Green Deal is consolidating demand for verified recycled copper content across European manufacturing supply chains. Aurubis leverages its integrated smelter-refinery network to secure high-purity cathode output from complex scrap feeds. Glencore anchors global trading flows through its control of large-scale collection and blending operations. Wieland-Werke specializes in precision alloy production that competes on specification consistency for automotive and electrical applications.
Copper and copper alloy scrap and recycling encompasses the recovery and reprocessing of metallic copper and its alloys from end-of-life products, manufacturing residues, and construction demolition, typically yielding material with conductivity exceeding 99.9% IACS after electrolytic refining. The primary purpose is to substitute virgin mined copper with lower-embodied-energy secondary feedstock for electrical, thermal, and structural applications. Copper wire dominates scrap type volumes due to pervasive infrastructure and vehicle electrification drawdowns, while phosphor bronze commands premium pricing in precision electronics. Pyrometallurgical processing retains scale leadership for bulk complex scrap, though hydrometallurgical routes are gaining traction for lower-emission recovery of specialty alloys.
EPA hazardous waste rules, REACH substance restrictions, and China's MEE solid waste import standards collectively reshape cross-border scrap flows and domestic processing investments. The EU CSRD extends disclosure requirements to recycled content verification, pressuring midstream processors toward certified chain-of-custody systems. Stakeholders must monitor evolving border compliance regimes and decide between regional processing scale-up versus long-haul feedstock arbitrage.
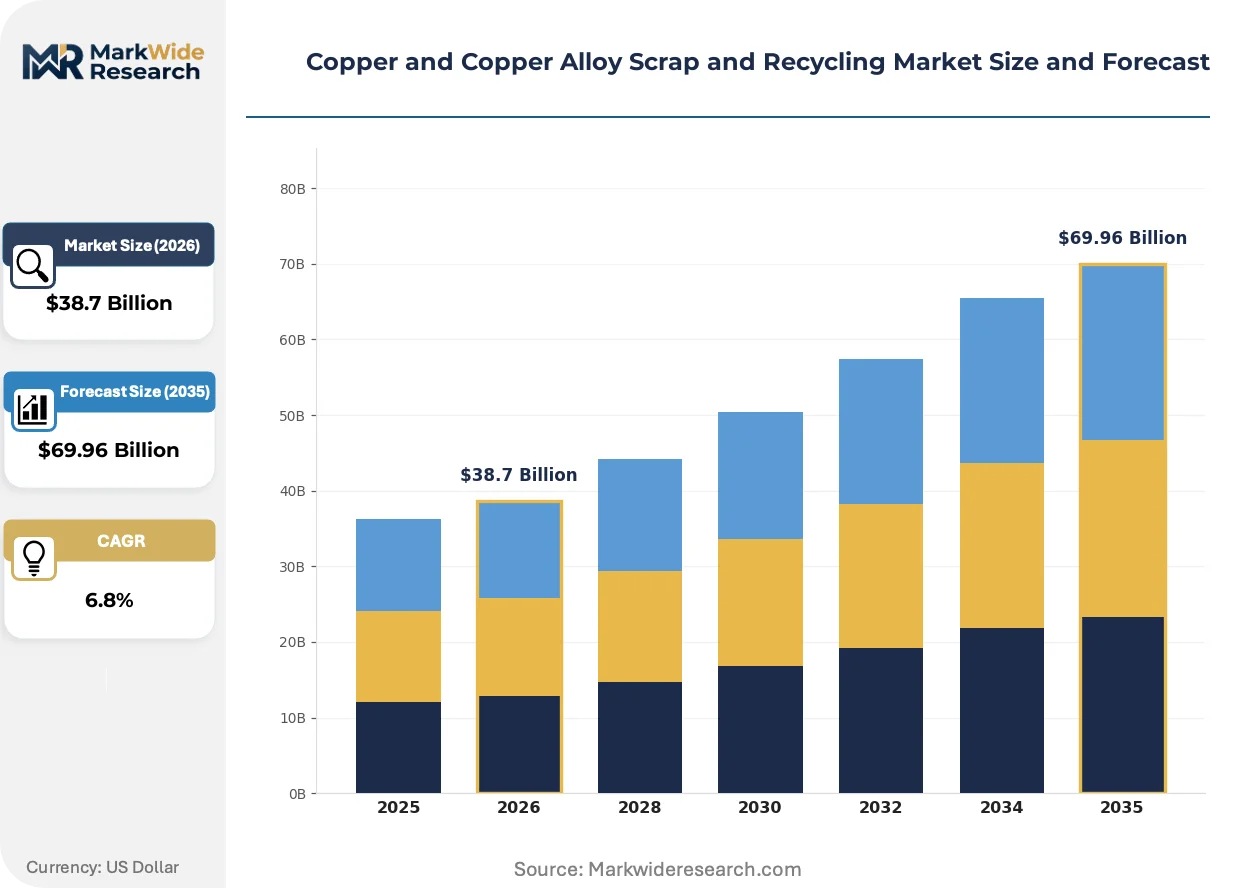
Market Dynamics
The EU Green Deal and China's dual carbon goals are forcing a wholesale reconfiguration of scrap sourcing networks, as manufacturers face binding recycled content mandates that cannot be met through spot-market purchases alone. This structural pressure is concentrating midstream processing capacity around certified supply chains with verified chain-of-custody documentation.
Growth Catalysts
- Vehicle electrification:Battery electric vehicle production in Germany and China is drawing down copper wire scrap volumes from decommissioned internal combustion fleets, creating dedicated feedstock streams for secondary smelters.
- EU CSRD disclosure rules:Corporate sustainability reporting mandates are compelling electrical equipment manufacturers to document verified recycled copper percentages, locking in long-term procurement contracts with certified processors.
- Pyrometallurgical efficiency gains:Oxygen-enriched smelting retrofits at major secondary copper facilities are expanding throughput capacity for complex mixed-alloy scrap feeds previously rejected as uneconomical.
Market Restraints
- Scrap import restrictions:China's MEE solid waste standards have eliminated cross-border arbitrage for low-grade copper scrap, forcing Southeast Asian processors to absorb regional surplus at compressed margins.
- Energy cost volatility:Natural gas and electricity price spikes in European smelting regions are eroding the cost advantage of secondary copper over primary cathode from Chilean concentrate.
- Aluminum substitution in HVAC:Heat exchanger manufacturers are specifying aluminum microchannel coils for residential air conditioning, displacing copper tube demand in a traditional scrap absorption segment.
Strategic Opportunities
- Urban mining infrastructure:Demolition waste from aging European building stock represents underexploited feedstock, with copper content in pre-1980 electrical installations exceeding modern construction by weight.
- Blockchain traceability platforms:Distributed ledger verification systems are converging with physical tagging technologies to create premium-priced certified scrap categories for automotive OEMs.
- Hydrometallurgical retrofit:Solvent extraction-electrowinning circuits adapted for scrap processing offer lower-emission recovery pathways for specialty alloys containing tin, nickel, or precious metals.
Industry Challenges
- Assay technician shortage:Rapid alloy identification through X-ray fluorescence and optical emission spectroscopy requires skilled operators, with training pipelines failing to match facility expansion timelines in the United States and Germany.
- Legacy ERP integration:Batch-level tracking systems for chain-of-custody certification must interface with decades-old inventory management platforms at mid-sized scrap processors, creating data reconciliation bottlenecks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper and Copper Alloy Scrap and Recycling Market Trends and Innovations
Processing technology and verification systems are advancing in parallel, with digital traceability tools now embedded at the point of scrap generation rather than applied downstream. This shift is compressing certification timelines and enabling real-time pricing tied to documented material provenance.
Sensor-based sorting systems employing near-infrared and X-ray transmission discrimination are converging with robotic separation arms to automate alloy classification at municipal recycling facilities. Automotive dismantlers in Germany and Japan are deploying these integrated lines to capture high-value copper fractions from shredded vehicle hulks. The structural consequence is a compression of manual sorting labor while expanding feedstock acceptance criteria for complex mixed loads.
REACH substance restrictions on lead and cadmium in electrical applications are tightening impurity tolerances for recycled copper destined for European wire rod production. Cable manufacturers must now document sub-50 ppm lead content through certified laboratory analysis, forcing scrap processors to segregate historical building wire from industrial cable categories. This regulatory friction is accelerating investment in hydrometallurgical refining circuits capable of achieving virgin-grade purity from secondary feedstock.
Long-term offtake agreements are displacing spot-market purchases as the dominant procurement model for major electrical equipment manufacturers. Tier-one automotive wiring harness suppliers in China and the United States are locking in five-to-seven-year supply contracts with fixed recycled content percentages and indexed pricing mechanisms. This behavioral shift is most visible in battery supply chain verticals, where cathode foil producers require guaranteed low-carbon copper volumes to satisfy OEM Scope 3 disclosure requirements.
Copper and Copper Alloy Scrap and Recycling Market Segmentation
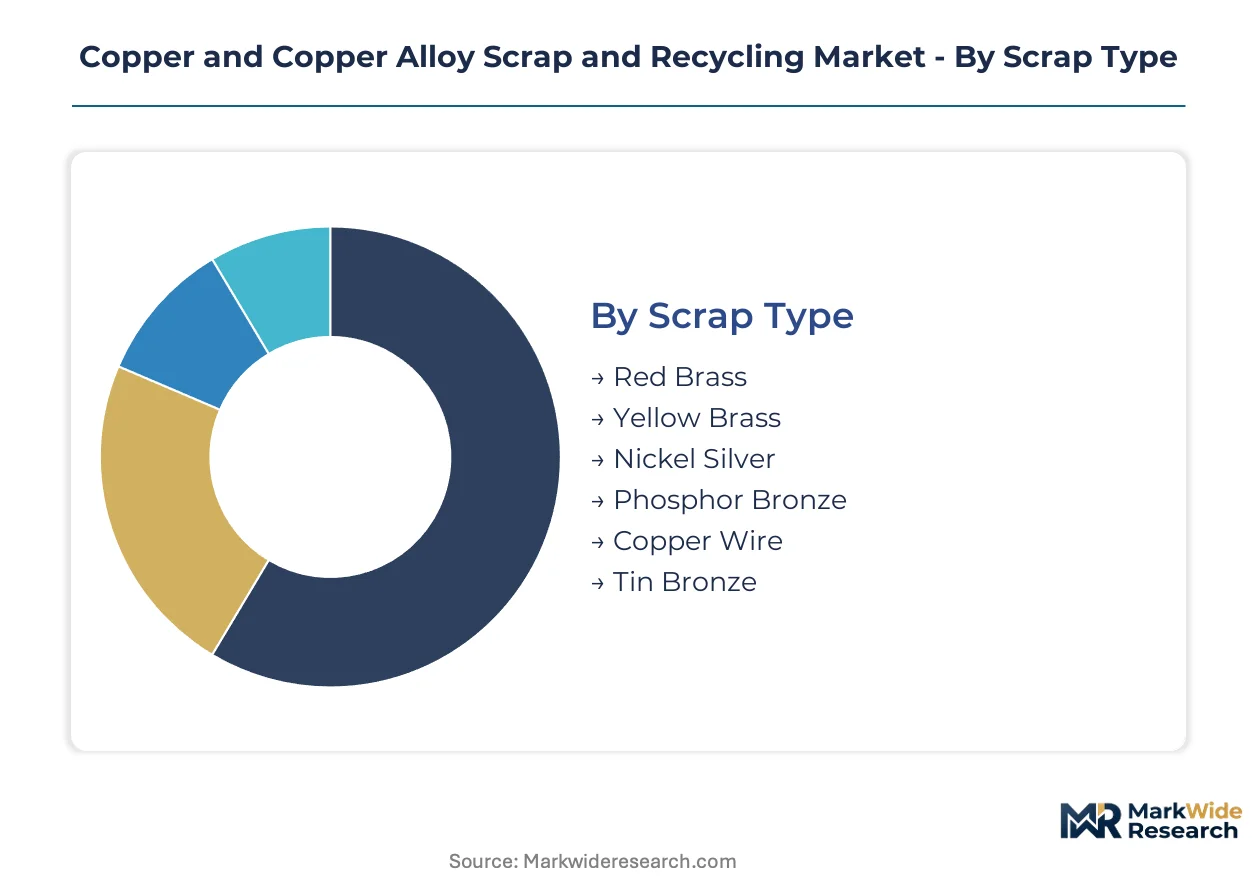
Segmentation in copper scrap and recycling reveals how material chemistry, processing economics, and collection logistics create distinct competitive arenas. Buyers prioritize conductivity specifications, impurity tolerances, and chain-of-custody documentation differently across end-use applications.
Scrap Type:
Purchasing decisions hinge on conductivity recovery rates and alloy complexity premiums.
- Copper Wire:High-purity feedstock from electrical infrastructure and vehicle harnesses yields cathode exceeding 99.9% IACS after electrolytic refining. German automotive wire harness suppliers are locking in long-term offtake agreements to secure verified low-carbon volumes for battery supply chains.
- Phosphor Bronze:Copper-tin-phosphorus alloy with superior fatigue resistance and spring characteristics commands premium pricing in precision connector applications. Electronics assemblers in Japan and South Korea specify certified phosphor bronze fractions for high-reliability telecommunications equipment.
- Red Brass:Copper-zinc-tin alloy from plumbing fixtures and valves offers consistent machinability for replacement part foundries.
- Yellow Brass:Copper-zinc alloy dominates decorative and low-stress hardware recycling volumes with established dealer pricing benchmarks.
- Nickel Silver:Copper-nickel-zinc alloy from musical instruments and marine hardware requires segregation for specialty melting campaigns.
- Tin Bronze:Bearing and bushing scrap with controlled lead content serves legacy industrial equipment remanufacturing.
Copper wire leads on scale; phosphor bronze leads on momentum.
Processing Technique:
Capital intensity and emissions profiles separate commercial viability across recovery methods.
- Pyrometallurgical:Oxygen-enriched smelting dominates bulk complex scrap processing, with retrofitted secondary facilities in Germany and China expanding throughput for mixed-alloy feeds. Natural gas price volatility in European smelting regions is compressing margins against Chilean primary cathode.
- Hydrometallurgical:Solvent extraction-electrowinning circuits achieve lower-emission recovery of specialty alloys containing tin, nickel, or precious metals. Southeast Asian processors are adopting hydrometallurgical routes to meet EU Green Deal traceability requirements for export-bound material.
- Electrolytic Refining:Final purification stage producing cathode-grade copper from fire-refined anodes.
- Mechanical Separation:Shredding and density separation for pre-concentration of metallic fractions from composite waste streams.
- Chemical Treatment:Acid leaching and precipitation for selective metal recovery from slags and residues.
- Physical Sorting:Sensor-based discrimination at municipal facilities enabling automated alloy classification.
Pyrometallurgical processing retains volume leadership; hydrometallurgical adoption is climbing the fastest.
End User Sector:
Contract structures and certification requirements vary sharply across downstream applications.
- Electrical Equipment Manufacturers:Cable and transformer producers face binding EU CSRD disclosure mandates for verified recycled content percentages, forcing migration from spot-market purchases to multi-year procurement contracts with fixed pricing mechanisms.
- Renewable Energy Installers:Photovoltaic and wind turbine contractors require guaranteed low-carbon copper volumes to satisfy OEM Scope 3 reporting obligations, creating premium-priced certified scrap categories.
- Construction Contractors:Demolition waste recovery from aging European building stock with copper-rich pre-1980 electrical installations.
- Electronics Assemblers:REACH substance restrictions on lead and cadmium drive sub-50 ppm purity requirements for connector and circuit board applications.
- Metal Fabricators:General engineering shops purchasing standardized brass and bronze ingots for non-critical components.
Electrical equipment manufacturers anchor contract volume; renewable energy installers are gaining share fastest.
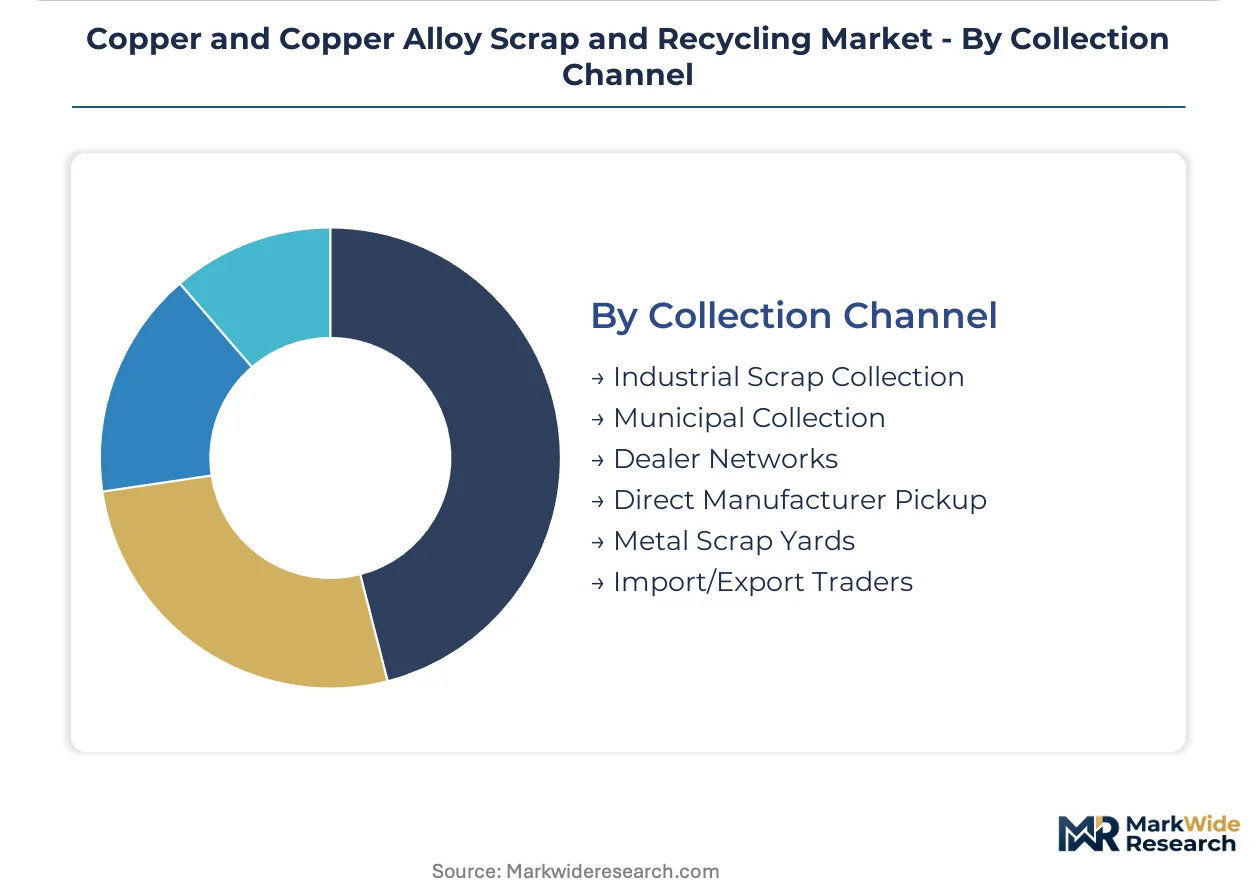
Collection Channel:
Feedstock security and logistics cost structures determine channel economics.
- Industrial Scrap Collection:Manufacturing residue streams from wire drawing, stamping, and machining operations provide predictable chemistry and volume for direct mill integration. Automotive tier-one suppliers in the United States are deploying blockchain traceability platforms at generation points to compress certification timelines.
- Dealer Networks:Independent scrap merchants aggregate dispersed flows from demolition, renovation, and equipment retirement, with pricing indexed to London Metal Exchange copper grades.
- Municipal Collection:Curbside and drop-off programs capturing consumer electronics and small appliance discards.
- Direct Manufacturer Pickup:Dedicated logistics arrangements for high-volume generators with established quality protocols.
- Metal Scrap Yards:Local processing facilities performing preliminary sorting and densification.
- Import/Export Traders:Cross-border arbitrage operations constrained by China's MEE solid waste standards elimination of low-grade copper scrap imports.
Industrial scrap collection leads on scale; dealer networks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgical engineers and assay technicians concentrate in Germany, China, and the United States, anchoring the world's most sophisticated secondary copper processing corridors.
United States
Automotive wire harness suppliers and electrical equipment manufacturers drive procurement of verified recycled copper feedstock. EPA hazardous waste rules tighten material traceability requirements for cross-border scrap movements. Texas and the industrial Midwest host expanding secondary smelting capacity serving domestic cathode demand.
Germany
Battery electric vehicle production and renewable energy installations create dedicated copper scrap absorption channels. The EU Green Deal and CSRD disclosure mandates compel manufacturers to document recycled content percentages through certified chain-of-custody systems. The Ruhr industrial corridor and Bavarian processing clusters anchor pyrometallurgical retrofit investments.
China
Vehicle electrification and grid infrastructure expansion sustain massive domestic scrap generation and consumption. MEE solid waste import standards have eliminated cross-border arbitrage for low-grade material, redirecting regional flows toward Southeast Asian processors. The Yangtze River Delta and Pearl River Delta concentrate hydrometallurgical adoption for export-bound specialty alloys.
Japan
Electronics assemblers and precision connector manufacturers specify certified phosphor bronze fractions for telecommunications equipment. METI industrial policy supports urban mining infrastructure development for end-of-life vehicle and appliance recovery. The Kansai region around Osaka maintains specialized alloy segregation capabilities for high-reliability applications.
Copper and Copper Alloy Scrap and Recycling Market Competitive Landscape
Capital-heavy integrated smelter-refinery operators compete with asset-light scrap collection and trading specialists for feedstock access and offtake relationships. The market structure concentrates around three to five major players controlling large-scale processing infrastructure, with a fragmented long tail of regional dealers and municipal collectors. Strategic archetypes include vertically integrated metals conglomerates with captive mining and recycling assets, specialized secondary copper refiners focused on complex scrap feeds, and global trading houses orchestrating cross-border arbitrage flows. Dominant competitive moves encompass oxygen-enriched smelting retrofits for throughput expansion and blockchain-enabled traceability platform deployment to secure automotive OEM contracts.
Among European-based integrated processors, Aurubis and Boliden occupy positions exemplifying the smelter-refinery archetype, while Glencore sits within the global trading and logistics tier. These entities anchor industry-wide patterns of feedstock security investments and certified supply chain development without dictating specific strategic outcomes for individual firms.
| Leading Market Players |
|---|
| Aurubis |
| Glencore |
| Boliden |
| Umicore |
| Wieland-Werke |
| Sims Metal |
| Commercial Metals Company |
| Jiangxi Copper Corporation |
| Chiho Environmental Group |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal and CSRD disclosure mandates gate qualified supply and premium-tier pricing access, as electrical equipment manufacturers must document verified recycled copper percentages through certified chain-of-custody systems to secure long-term procurement contracts.
Pricing Analysis
Certified scrap commands premium pricing over uncertified material, with three-tier pricing structure across premium, standard, and economy levels based on chain-of-custody documentation and purity grades. Price differentiation stems from EU CSRD compliance requirements and London Metal Exchange copper grade indexing. Cost compression in standard-tier material is intensifying because Southeast Asian processors absorb regional surplus at compressed margins following China's MEE import restrictions. Dealer networks exhibit highest price sensitivity, while automotive OEMs prioritize certification over cost.
Supply Chain Analysis
Dual-sourcing requirements from tier-one automotive wiring harness suppliers mandate multi-supplier qualification to mitigate single-source vulnerability in cathode foil procurement. Supply concentrates in Germany, China, and the United States, with secondary processing capacity anchored in the Ruhr corridor, Yangtze River Delta, and Texas industrial hub. Raw material dependencies include end-of-life vehicle harnesses, demolition electrical installations, and manufacturing residues from wire drawing operations. Distribution runs through integrated smelter-refinery networks and independent dealer networks indexed to commodity benchmarks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
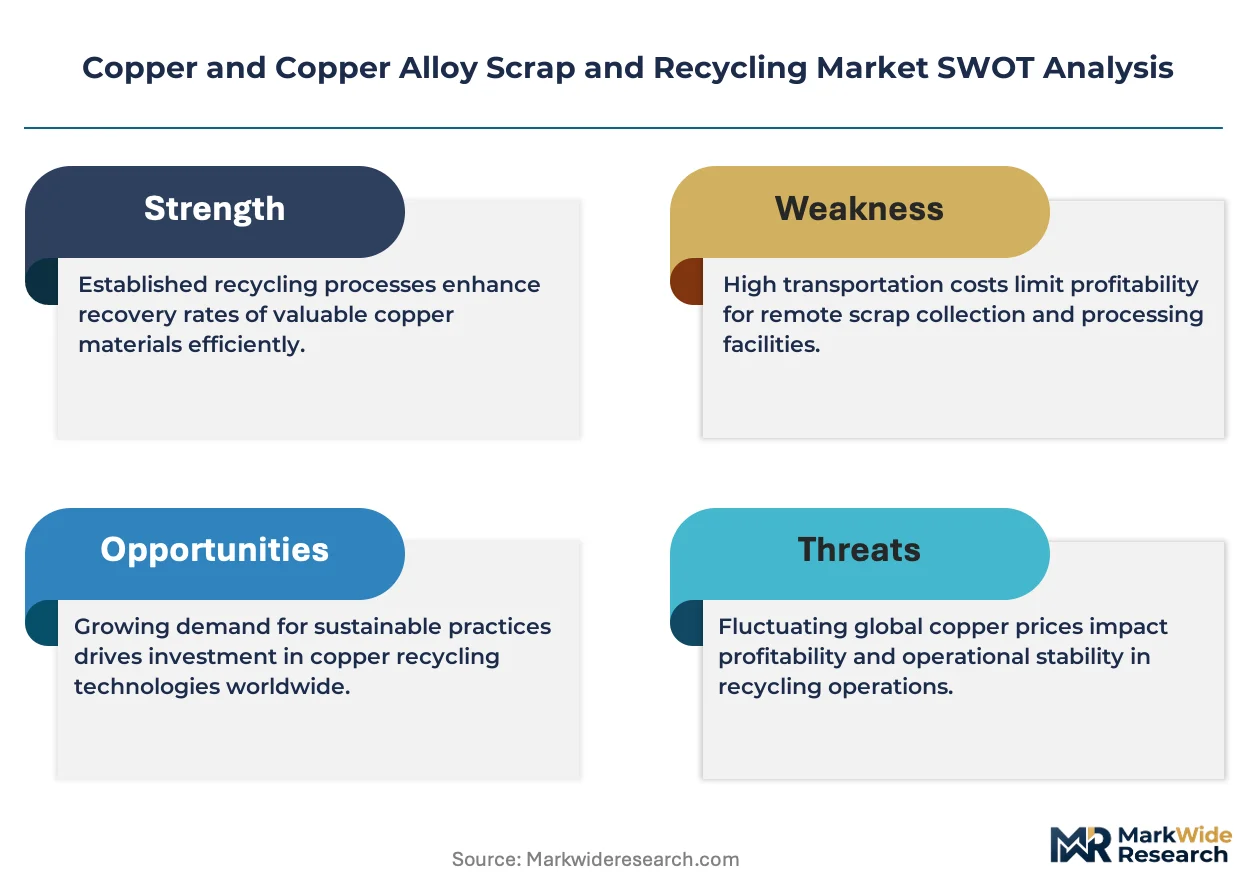
This market functions as a geographic-arbitrage play, with energy cost differentials between European smelting regions and Southeast Asian hydrometallurgical facilities creating margin relocation opportunities for processors.
For Market Incumbents: Deploy oxygen-enriched smelting retrofits to expand throughput capacity for complex mixed-alloy scrap feeds previously rejected as uneconomical. Secure feedstock through backward integration into demolition waste recovery infrastructure targeting pre-1980 European building stock with copper-rich electrical installations. Counter aluminum substitution in HVAC heat exchangers by emphasizing conductivity advantages in premium electrical applications.
For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in certified scrap categories creates entry opportunity for blockchain-enabled traceability platforms that compress certification timelines. Target municipal collection infrastructure in secondary cities lacking sensor-based sorting capabilities. Pursue white-label hydrometallurgical processing partnerships with Southeast Asian facilities seeking EU Green Deal export compliance.
For Investors and Strategic Acquirers: Roll-up economics work for regional dealer networks because fragmentation across independent scrap merchants prevents pricing power consolidation against integrated processors. Five-to-ten-year viability hinges on CSRD mandate expansion beyond electrical equipment into construction and automotive sectors. Monitor MEE regulatory relaxation signals as inflection indicator for cross-border arbitrage flow restoration.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxygen-Enriched Smelting Retrofit | Expands throughput for complex mixed-alloy feeds at German and Chinese secondary facilities. |
| Blockchain Traceability Platform Deployment | Compresses certification timelines for automotive OEM chain-of-custody requirements. |
| Urban Mining Infrastructure Buildout | Captures underexploited copper content from pre-1980 European demolition waste streams. |
| Hydrometallurgical Circuit Investment | Enables lower-emission recovery of specialty alloys containing tin, nickel, or precious metals. |
| Long-Term Offtake Agreement Structuring | Locks in five-to-seven-year supply contracts with fixed recycled content percentages. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with secondary copper refinery operators, scrap dealer network principals, automotive tier-one procurement directors, electrical equipment manufacturer sustainability leads, and assay technician training program administrators. Secondary validation drew from EPA hazardous waste filings, EU ECHA REACH substance restriction updates, China MEE solid waste import standard publications, London Metal Exchange copper grade pricing data, and SEC 10-K disclosures from integrated metals processors. Bottom-up scrap generation estimates and top-down cathode demand projections were triangulated against facility capacity announcements.
Segment-weighting approaches modeled scrap type, processing technique, end-user sector, and collection channel dimensions across the analysis window. Pyrometallurgical and hydrometallurgical route splits were calibrated against energy cost differentials and emissions compliance thresholds. CAGRs were derived from facility expansion timelines and regulatory mandate phase-in schedules. Forecast inputs included vehicle electrification scrap generation rates, EU CSRD disclosure adoption curves, and urban mining infrastructure deployment trajectories.
Caveats apply where MEE import standard revisions, European natural gas price volatility, or aluminum substitution acceleration in HVAC applications could materially shift the outlook. Deviation in EU Green Deal recycled content mandate enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.