
 Global Vanadium Market | 2026-2036
Global Vanadium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vanadium Market Outlook
Long-term offtake bundling with battery developers is repositioning procurement strategies across the value chain. Glencore leverages its trading infrastructure to secure concentrate flows from Southern African deposits. EVRAZ plc anchors its position through captive vanadium extraction tied to Russian steel operations. Australian Vanadium Limited specializes in developing integrated mine-to-battery projects targeting Western Australian resources.
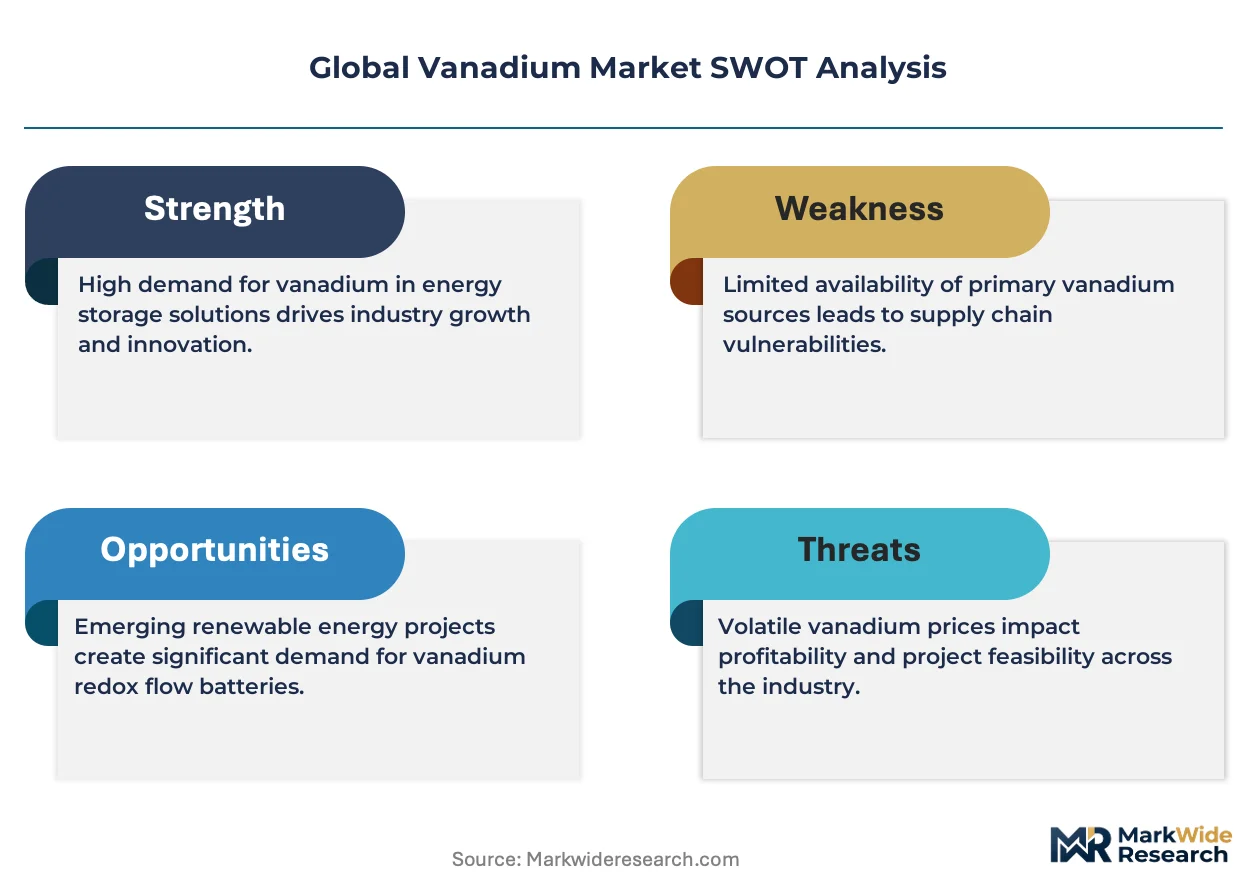
Vanadium is a transition metal with atomic number 23, occurring primarily in vanadium-titanium magnetite deposits and produced as vanadium pentoxide or ferrovanadium through pyrometallurgical and hydrometallurgical routes; its principal commercial purpose is to enhance tensile strength, fatigue resistance, and corrosion performance in steel alloys and to serve as the active material in vanadium redox flow batteries for grid-scale energy storage. Ferrovanadium dominates volume flows into construction and automotive steel production, where margin pools remain deepest due to established blast furnace integration. Vanadium pentoxide for battery manufacturing represents the fastest-growing application segment, though electrowinning capacity constraints limit near-term supply elasticity.
The EPA enforces emissions controls on U.S. ferroalloy smelters, while China's MEE implements dual carbon targets that restrict high-carbon vanadium extraction methods; REACH compliance in Europe mandates disclosure of vanadium compound toxicity in industrial applications, shaping product standards and market access conditions. Stakeholders must monitor how regulatory divergence between China's GB standards and EU chemicals policy affects cross-border material certification and offtake contract structuring.
Market Dynamics
China's dual carbon goals are forcing a structural pivot away from blast furnace-dependent vanadium extraction toward hydrometallurgical and recycling-based feedstock streams. This decarbonization mandate is compressing legacy pyrometallurgical capacity while accelerating capital deployment into battery-grade vanadium pentoxide circuits.
Growth Catalysts
- Grid-scale storage mandates:China's 14th Five-Year Plan targets 30 GW of non-lithium energy storage by 2025, directing state grid procurement toward vanadium redox flow batteries for 4-8 hour duration applications.
- High-strength rebar standards:India's Bureau of Indian Standards (BIS) has tightened seismic-grade steel specifications for infrastructure, embedding vanadium micro-alloying into national construction codes.
- Vanadium-titanium magnetite clustering:Sichuan Province's Panzhihua mining complex anchors captive feedstock supply for integrated steel-battery material production.
Market Restraints
- Feedstock concentration risk:Over 60% of primary vanadium originates from three magnetite districts—Russia's Kachkanar, South Africa's Bushveld, and China's Panzhihua—creating single-point vulnerability to export licensing or logistics disruption.
- Energy cost volatility:Ammonium salt roasting and smelting operations face margin compression from natural gas and metallurgical coke price swings, particularly affecting European electrowinning capacity.
- Titanium dioxide competition:Vanadium slag from magnetite processing competes with chloride-route TiO2 feedstock prioritization, constraining byproduct vanadium yields during pigment demand cycles.
Strategic Opportunities
- Spent catalyst recovery:Petroleum refining decommissioning in the US Gulf Coast and Rotterdam-Antwerp corridor is unlocking secondary vanadium feedstock streams from desulfurization catalyst waste.
- Long-duration storage incentives:The US Inflation Reduction Act (IRA) investment tax credit extension to 10+ hour battery technologies is repositioning vanadium redox systems against lithium-ion for grid firming contracts.
- Direct vanadium extraction:Oilfield brine processing in Alberta and Wyoming is piloting solvent extraction circuits that bypass traditional steel-slag intermediation entirely.
Industry Challenges
- Electrolyte purity certification:Battery manufacturers require 99.9%+ V2O5 with controlled sulfate and chloride thresholds, forcing smelters to retrofit hydrometallurgical refining trains with 18-24 month qualification timelines.
- Flow battery system integration:Engineering procurement construction (EPC) firms lack standardized vanadium stack assembly protocols, extending project commissioning and eroding developer returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vanadium Market |
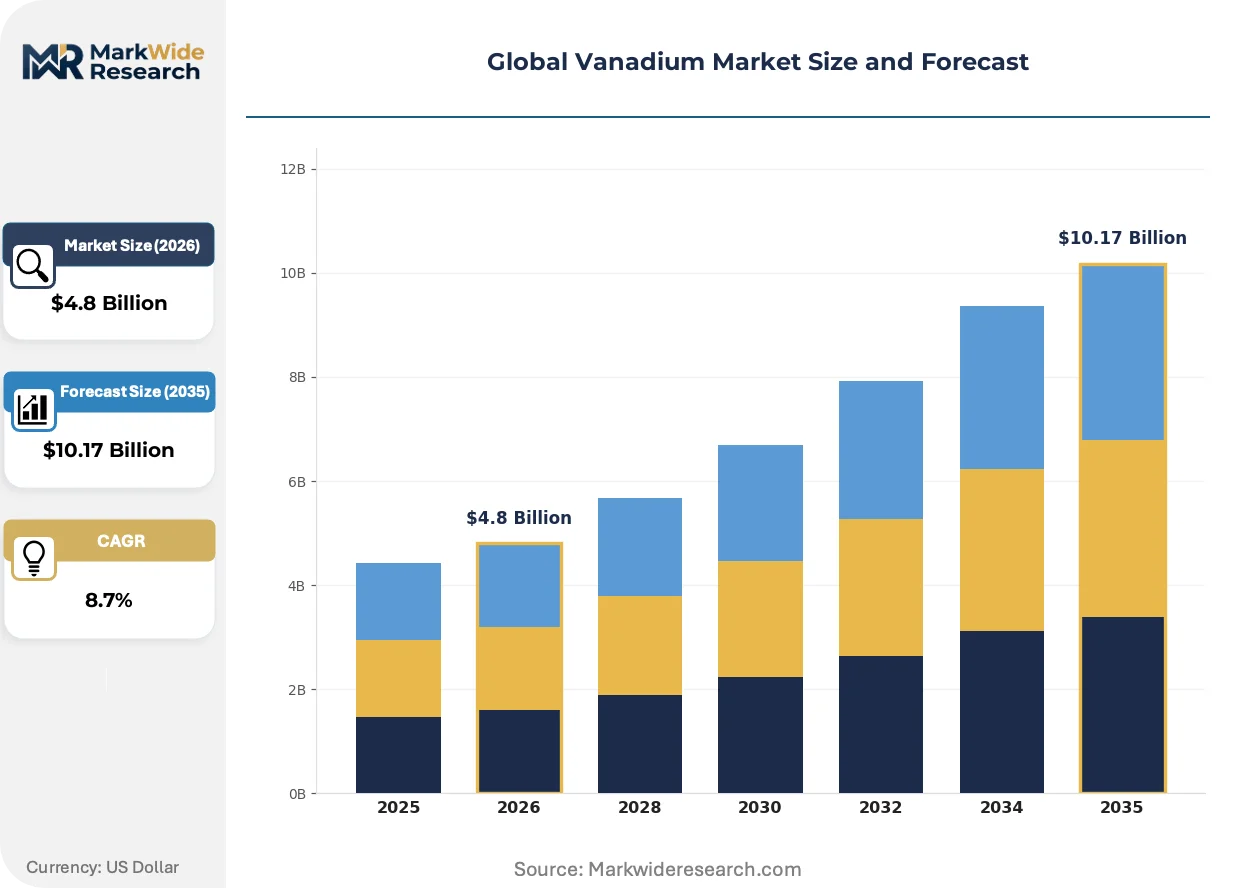
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanadium Pentoxide, Ferrovanadium, Vanadium Alloy, Vanadates End User: Aerospace, Construction, Automotive, Energy Storage Application: Steel Production, Battery Manufacturing, Aerospace Components, Chemical Production Technology: Hydrometallurgy, Pyrometallurgy, Recycling, Electrowinning |
| Companies Covered | AMG Advanced Metallurgical Group, Glencore, EVRAZ plc, Angang Steel Co. Ltd, Australian Vanadium Limited, Largo Resources Ltd, HBIS Group, VanadiumCorp Resource Inc., Bushveld Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vanadium Market Strategic Shifts
Vanadium redox flow battery commercialization is compressing the traditional steel-centric demand model while regulatory emissions frameworks reconfigure extraction economics across major producing jurisdictions.
Membrane-electrode assembly improvements are electrifying vanadium redox system economics. Gore and Asahi Kasei perfluorinated ionomer membranes now enable 20,000+ cycle durability without capacity fade. Utility-scale developers in California and Australia are deploying 200 MWh+ projects with 25-year asset life assumptions. This technology is electrifying project finance structures by eliminating replacement reserve requirements that burden lithium-ion installations.
REACH authorization requirements for vanadium pentoxide under EU chemicals policy are tightening occupational exposure documentation. ECHA's 2023 harmonized classification as a suspected carcinogen is forcing downstream users to implement closed-loop handling systems. Battery material suppliers in Finland and Germany are responding with sealed electrolyte leasing models that retain ownership and liability throughout the asset lifecycle.
Steel mills are unbundling vanadium unit pricing from long-term ferrovanadium offtake contracts. Chinese rebar producers now index vanadium micro-alloying costs to Shanghai Futures Exchange vanadium pentoxide quotes rather than fixed ferrovanadium premiums. This price transparency shift is most visible in Hebei Province, where independent mills have displaced state-owned trading company intermediation for 40% of spot purchases.
Global Vanadium Market Segmentation
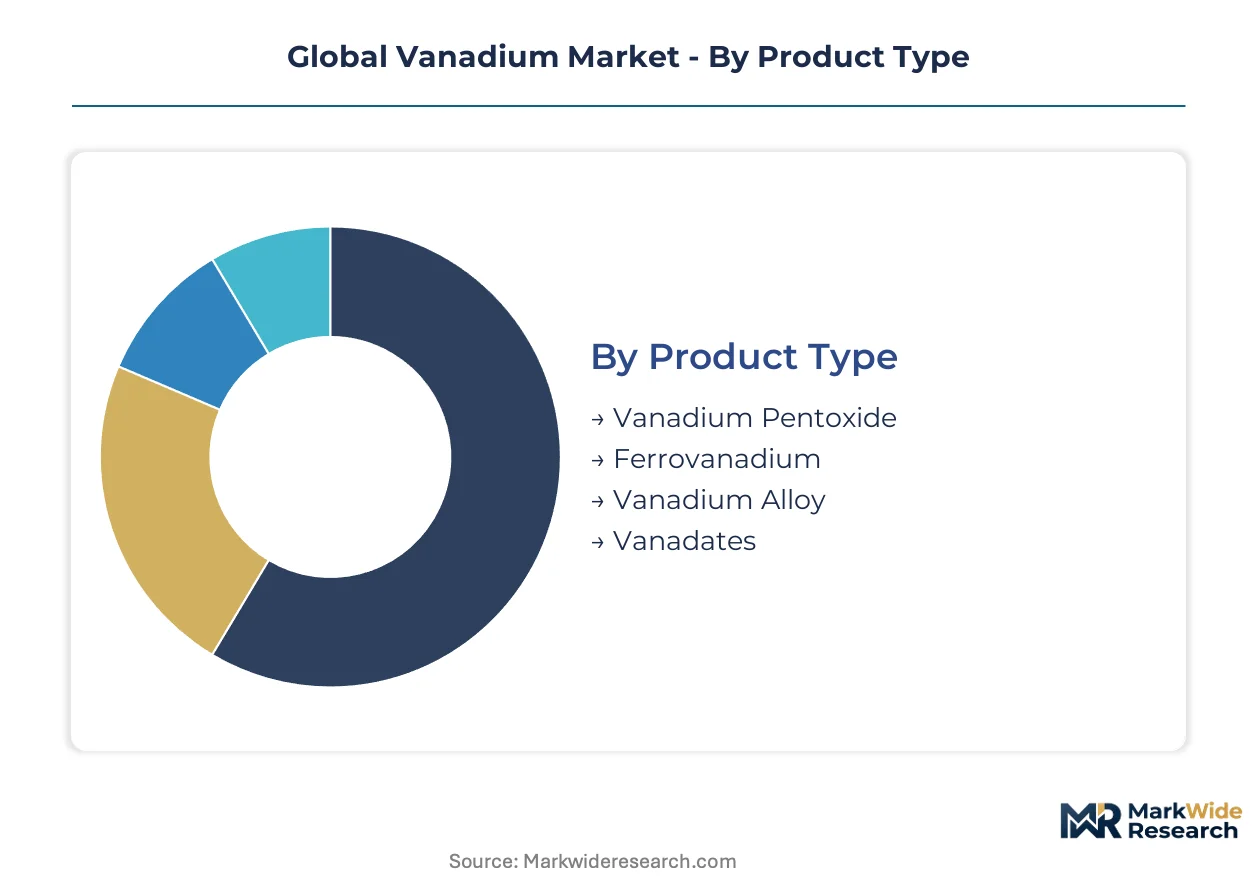
Vanadium's dual role in steel hardening and battery chemistry creates distinct certification and purity requirements across product categories. Segmentation reveals how regulatory frameworks fragment procurement strategies and margin structures.
Product Type:
Ferrovanadium carries GB standards compliance for Chinese construction steel, while battery-grade vanadium pentoxide faces REACH authorization and EPA toxic substance reporting. Vanadates and specialty alloys navigate divergent occupational exposure thresholds across major consuming jurisdictions.
- Ferrovanadium:Iron-vanadium alloy containing 35-80% vanadium by weight, produced through aluminothermic reduction of vanadium pentoxide. Demand concentrates in Hebei Province rebar mills, where BIS seismic-grade specifications and China's dual carbon goals are tightening micro-alloying intensity requirements.
- Vanadium Pentoxide:Crystalline V2O5 ranging from technical-grade (98% purity) to battery-grade (99.9%+ with sulfate/chloride controls). Electrowinning capacity in Finland and Germany is climbing fastest as ECHA carcinogen classification forces sealed electrolyte leasing models and closed-loop handling investments.
- Vanadium Alloy:Titanium-aluminum-vanadium formulations for aerospace and specialty steel applications. Russian EVRAZ and Chinese Panzhihua operations supply ingot and master alloy forms.
- Vanadates:Sodium and ammonium vanadate compounds for chemical catalysis and pigment production. Refinery desulfurization catalyst waste in the US Gulf Coast and Rotterdam-Antwerp corridor is emerging as secondary feedstock.
Ferrovanadium sits at the top of the volume ranking, with vanadium pentoxide climbing the fastest.
End User:
Construction and automotive steel producers index vanadium costs to exchange-traded pentoxide quotes, while aerospace and energy storage buyers lock in long-term offtake with purity certification requirements.
- Construction:Rebar and structural steel micro-alloying dominates tonnage flows. Indian BIS seismic standards and Chinese high-strength specifications are embedding vanadium into national building codes.
- Energy Storage:Vanadium redox flow battery developers require 25-year asset life electrolyte with 99.9%+ purity. California and Australian utility-scale projects above 200 MWh are compressing project finance structures through membrane-electrode durability improvements.
- Automotive:High-strength low-alloy steel for vehicle lightweighting. Tier-1 mills in Germany and Japan specify ferrovanadium with controlled nitrogen content for sheet formability.
- Aerospace:Titanium-6Al-4V and Ti-10V-2Fe-3Al alloys for airframe and engine components. Boeing and Airbus supply chains demand vacuum arc remelted material with full traceability documentation.
Construction commands the dominant share of procurement volume, with energy storage expanding most quickly.
Application:
Steel production and battery manufacturing split the value chain between blast furnace-integrated pyrometallurgy and hydrometallurgical electrowinning circuits with divergent energy intensity profiles.
- Steel Production:Micro-alloying for tensile strength and fatigue resistance in rebar, plate, and structural sections. Panzhihua and Kachkanar magnetite districts supply captive feedstock to integrated mills.
- Battery Manufacturing:Electrolyte preparation for vanadium redox flow systems. China's 14th Five-Year Plan 30 GW non-lithium storage target is redirecting state grid procurement toward 4-8 hour duration applications.
- Aerospace Components:Engine disks, landing gear, and airframe structures requiring specific strength-to-weight ratios. Russian and Ukrainian titanium-vanadium feedstock disruptions have accelerated Australian and Canadian alternative sourcing.
- Chemical Production:Sulfuric acid catalysts and ceramic pigments. Spent catalyst recovery from petroleum refining is unlocking secondary supply streams.
Steel production retains the highest absolute volume position, with battery manufacturing gaining share fastest.
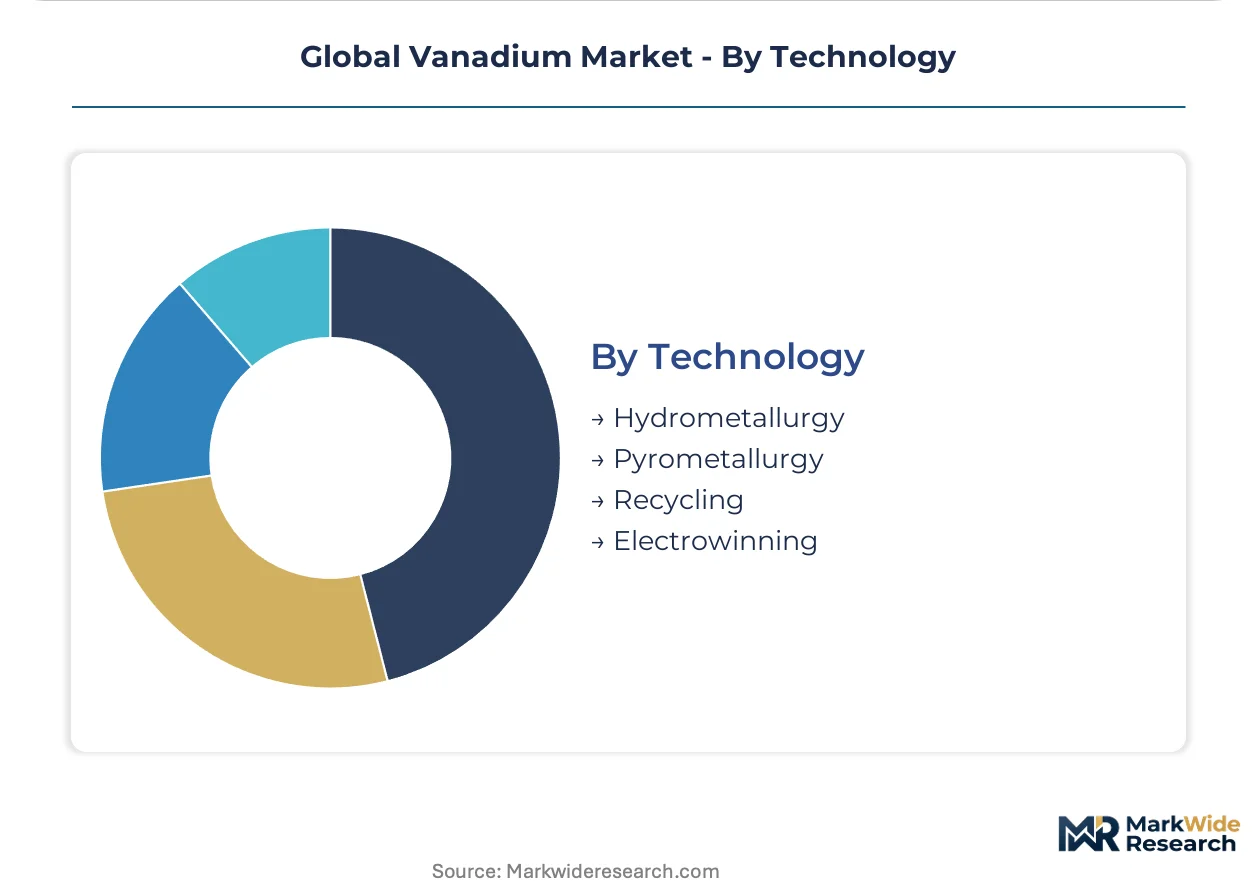
Technology:
China's dual carbon mandate is compressing legacy pyrometallurgical capacity while IRA investment tax credits accelerate US and European electrowinning deployment for battery-grade material.
- Pyrometallurgy:Roast-leach and smelting of vanadium-titanium magnetite in blast furnace-integrated operations. Panzhihua and Bushveld complexes face margin compression from metallurgical coke and natural gas price volatility.
- Hydrometallurgy:Acid leaching and solvent extraction circuits producing high-purity pentoxide. Alberta and Wyoming oilfield brine direct extraction pilots are bypassing traditional steel-slag intermediation entirely.
- Recycling:Spent catalyst and battery electrolyte recovery. US Gulf Coast refinery decommissioning and European REACH waste framework implementation are formalizing secondary feedstock qualification protocols.
- Electrowinning:Electrolytic reduction to metal or pentoxide with 99.9%+ purity. Finnish and German capacity expansions face 18-24 month qualification timelines for battery manufacturer certification.
Pyrometallurgy sits at the top of the volume ranking, with electrowinning climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vanadium extraction originated in Peruvian radium-vanadium deposits during the early 20th century, with commercial scale achieved through Colorado Plateau carnotite processing and subsequent magnetite-based production in Russia and South Africa. Geographic concentration now follows vanadium-titanium magnetite geology and steel industry integration.
China
Sichuan Province's Panzhihua complex and Hebei Province steel corridors consume the majority of domestic vanadium output for rebar micro-alloying and emerging battery feedstock. The MEE dual carbon targets restrict high-carbon extraction methods while accelerating hydrometallurgical capacity deployment. State grid procurement under the 14th Five-Year Plan redirects material flows toward vanadium redox flow battery manufacturers in Chengdu and Beijing-Tianjin-Hebei clusters.
Russia
Kachkanar's vanadium-titanium magnetite district supplies captive feedstock to integrated steel operations with byproduct pentoxide extraction. Export licensing frameworks and logistics constraints create supply vulnerability for European ferrovanadium consumers. EVRAZ plc anchors regional production through Urals-based smelting infrastructure tied to rail and construction steel output.
South Africa
Bushveld Complex magnetite deposits concentrate primary extraction capacity in Limpopo and North West provinces. Glencore leverages trading infrastructure to secure concentrate flows for export markets facing Chinese supply competition. The country's national mineral regulator monitors environmental compliance for roaster operations serving titanium dioxide and vanadium co-production circuits.
United States
Arkansas and Nevada host the remaining primary extraction capacity, with EPA emissions controls limiting ferroalloy smelter expansion. The IRA investment tax credit extension to 10+ hour battery technologies accelerates utility-scale vanadium redox project development in California and Texas. Spent catalyst recovery from Gulf Coast petroleum refining unlocks secondary feedstock streams.
Australia
Western Australian vanadium-titanium magnetite resources support integrated mine-to-battery project development targeting Asian electrolyte demand. Australian Vanadium Limited specializes in developing these captive supply chains. State-level environmental approval processes and renewable energy integration shape project economics for electrowinning capacity.
Global Vanadium Market Competitive Environment
The competitive structure tilts toward integrated mining-steel conglomerates with captive vanadium extraction. Market concentration reflects feedstock access rather than downstream specialization. Three archetypes dominate: magnetite-integrated steel producers, pure-play vanadium developers, and diversified mining-trading houses. Capacity expansion and long-term offtake bundling with battery developers constitute the primary competitive moves.
Among diversified mining-trading houses, Glencore exemplifies commodity flow control through trading infrastructure. Integrated steel operators with captive extraction include EVRAZ plc, which occupies a position tied to Russian magnetite districts. Pure-play developers such as Australian Vanadium Limited represent the mine-to-battery archetype targeting Western Australian resources for Asian battery supply chains.
| Leading Market Players |
|---|
| AMG Advanced Metallurgical Group |
| Glencore |
| EVRAZ plc |
| Angang Steel Co. Ltd |
| Australian Vanadium Limited |
| Largo Resources Ltd |
| HBIS Group |
| VanadiumCorp Resource Inc. |
| Bushveld Minerals |
| Others |
Value Chain & Pricing Dynamics
Battery-grade purity certification against technical-grade commodity benchmarks splits procurement economics into divergent contracting regimes. Chinese state grid offtake agreements index electrolyte premiums to Shanghai Futures Exchange vanadium pentoxide quotes, while European REACH compliance costs force sealed electrolyte leasing models that transfer liability upstream. This bifurcation concentrates margin capture among electrowinning specialists in Finland and Germany while compressing ferrovanadium conversion spreads in Hebei Province rebar corridors.
Pricing Analysis
Three-tier pricing structure across battery-grade, technical-grade, and ferrovanadium alloy levels anchors contract negotiations. Certification thresholds—99.9% V2O5 purity with sulfate controls versus 98% technical standards—drive price differentiation between electrolyte suppliers and steel micro-alloying buyers. Cost compression in ferrovanadium conversion is intensifying because metallurgical coke and natural gas price volatility erodes blast furnace-integrated margins. Chinese rebar mills exhibit highest price sensitivity through spot-indexed purchasing, while California utility-scale battery developers lock in long-term offtake with durability guarantees.
Supply Chain Analysis
Domestic-content mandates in China's 14th Five-Year Plan and India's PLI scheme for critical minerals are reshaping sourcing toward captive magnetite districts. Primary extraction draws from Russia's Kachkanar, South Africa's Bushveld, and China's Panzhihua complexes. Vanadium-titanium magnetite feedstock, ammonium salt roasting reagents, and perfluorinated ionomer membranes constitute critical input dependencies. Single-source vulnerability to export licensing disruptions in Russian supply channels represents the dominant structural risk. Distribution runs through Glencore's trading infrastructure for concentrate flows and integrated steel mill captive channels for ferrovanadium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's dual carbon goals and the EU Green Deal tighten emissions standards simultaneously, accelerating capital deployment into hydrometallurgical and battery-grade circuits.
For Market Incumbents: Deepen captive feedstock control through backward integration into vanadium-titanium magnetite districts and electrowinning capacity expansion in low-carbon jurisdictions. EVRAZ plc's Urals-based smelting infrastructure demonstrates how steel-integrated extraction defends against pure-play battery material entrants. Certification investment for 99.9% V2O5 purity with ECHA-compliant handling systems secures offtake from European electrolyte leasing models. For New Entrants and Emerging Players: Direct vanadium extraction from oilfield brine in Alberta and Wyoming offers a technology-first wedge that bypasses traditional steel-slag intermediation entirely. Spent catalyst recovery from US Gulf Coast petroleum refining decommissioning represents the most penetrable white-space segment, with secondary feedstock qualification protocols formalizing under EPA waste frameworks. Joint development agreements with membrane-electrode assembly suppliers accelerate stack integration capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where electrowinning capacity scarcity meets battery developer offtake bundling requirements. Long-term viability centers on mine-to-battery developers with Western Australian or North American resource bases and renewable energy-integrated refining. The signal to watch is state grid procurement allocation shifts under China's non-lithium storage mandates, which would redirect material flows from steel toward electrolyte circuits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetite Feedstock | Panzhihua and Bushveld district control secures captive supply against concentrate export restrictions. |
| Electrowinning Capacity Expansion | Finnish and German deployments target battery-grade purity with ECHA-compliant closed-loop handling. |
| Long-term Supply Agreement with Grid Developers | California and Australian utility-scale projects above 200 MWh compress project finance through durability guarantees. |
| Spent Catalyst Recovery Infrastructure | US Gulf Coast and Rotterdam-Antwerp corridor decommissioning unlocks secondary vanadium feedstock streams. |
| Membrane-Electrode Assembly Partnership | Gore and Asahi Kasei perfluorinated ionomer supply enables 20,000+ cycle durability without capacity fade. |
Study Parameters
Multiple input streams — primary interviews with vanadium smelter operations managers, battery developer procurement leads, and steel mill technical directors; secondary validation through SEC filings, customs trade data, and national mineral regulator disclosures; plus EIA energy cost databases and IEA critical minerals tracking — were reconciled through bottom-up and top-down triangulation.
Historical production and consumption patterns were cross-referenced against panel input from industry participants to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product purity grade, end-use application, extraction technology, and regional regulatory cluster. CAGRs were derived from supply-demand balance projections incorporating China's dual carbon mandate implementation pace and IRA investment tax credit eligibility for long-duration storage.
The model holds under sustained policy support for non-lithium energy storage and stable magnetite district output; deviation in export licensing regimes, membrane-electrode supply constraints, or titanium dioxide feedstock prioritization would shift trajectory. A small set of named triggers — state grid procurement allocation, ECHA authorization timelines, and oilfield brine extraction pilot results — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Oxygen-Free Copper Market
Metals
Silver-Platinum Paste Market
Metals
Iron Ore Market
Metals
Global Copper Sputtering Target Market
Metals
High Purity Tungsten Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Copper Powder Market
Metals
Copper Clad Aluminum Wire Market
Metals
Copper Foil Market
Metals
Arc Ferrite Magnet Market
Metals
Nickel Foam Market
Metals
Anodized Titanium Market
Metals
Silver Nitrate Market
Metals
Expanded Metal Foils Market
Metals
India Steel Market
Metals
Steel Ingots Market