
 Ferro Vanadium Market | 2026-2036
Ferro Vanadium Market Size, Share, and Industry Trends Forecast 2026-2036
Ferro Vanadium Market Analysis
Competitive Landscape
The capital-intensity divergence between integrated miners and merchant producers is redrawing competitive boundaries in ferro vanadium. Evraz PLC leverages captive vanadium feedstock from its Russian operations to sustain cost advantages across the alloy value chain. AMG Advanced Metallurgical Group NV differentiates through advanced reduction technologies and positions its European facilities to navigate tightening EU emissions standards. Bushveld Minerals anchors its strategy around Southern African ore bodies, competing on raw material security rather than scale.
Product Structure and Segment Dynamics
Ferro vanadium is an iron-vanadium master alloy typically containing 50–80% vanadium by weight, produced through aluminothermic reduction of vanadium pentoxide or oxide concentrates for use as a hardenability agent and grain refiner in steels. FeV 80 commands premium positioning in aerospace-grade titanium alloy applications where purity thresholds exceed standard construction grades. Steel Manufacturing absorbs the dominant volume share, while Titanium Alloys represent the fastest-expanding margin pool as aerospace OEMs qualify next-generation engine materials. The End User segmentation shows Aerospace pulling ahead of Construction in value terms, though Energy sector procurement is shifting toward long-term direct contracts to secure supply.
Regulatory Environment and Outlook
China's MIIT enforces GB standards on ferroalloy emissions intensity, while the EU F-Gas Regulation and REACH framework constrain production chemistry options for European suppliers. EPA oversight of U.S. smelter emissions shapes where new capacity can locate, and South Africa's Department of Mineral Resources and Energy influences Bushveld's licensing timelines. Stakeholders must monitor how carbon border adjustment mechanisms reshape trade flows for carbon-intensive master alloys before committing to regional expansion decisions.
Market Dynamics
Carbon border adjustment mechanisms are forcing ferro vanadium producers to reconfigure regional supply footprints before 2026 implementation deadlines reshape trade economics for carbon-intensive master alloys.
Growth Catalysts
- GB standards enforcement:China's MIIT emissions intensity mandates are accelerating furnace upgrades across Shandong and Sichuan production clusters, tightening supply quality differentials.
- Aerospace titanium qualification:Next-generation engine programs at Pratt & Whitney and Rolls-Royce are expanding FeV 80 offtake for single-crystal turbine blade alloys.
- South Korean specialty steel:POSCO and Hyundai Steel are expanding high-strength low-alloy capacity around Gwangyang, concentrating regional ferro vanadium demand.
Market Restraints
- Vanadium pentoxide concentration:Over 60% of global V2O5 supply originates from Chinese and Russian integrated steel slag operations, creating single-source vulnerability.
- Aluminothermic energy intensity:Reduction processes require 12-15 MWh per tonne FeV, exposing producers to European carbon pricing volatility under EU ETS Phase IV.
- Niobium substitution in HSLA grades:Microalloying formulations below 0.05% vanadium equivalence are displacing FeV in automotive body-in-white applications.
Strategic Opportunities
- India's PLI scheme for specialty steel:Domestic ferroalloy capacity expansion under the production-linked incentive framework offers tariff-protected offtake growth through 2030.
- Direct reduction-electric arc furnace integration:Green hydrogen-based DRI-EAF steelmaking in Sweden and Norway creates premium FeV demand for ultra-low-carbon automotive grades.
- Long-term aerospace contracting:Boeing and Airbus tier-one suppliers are negotiating 7-10 year vanadium supply agreements to secure titanium alloy feedstock against spot volatility.
Industry Challenges
- Aluminothermic furnace operator scarcity:Specialized pyrometallurgical expertise required for FeV reduction is concentrating among retiring workforces in European and North American facilities.
- REACH compliance timeline:ECHA substance evaluation deadlines for vanadium compounds are compressing registration windows for non-EU exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferro Vanadium Market |
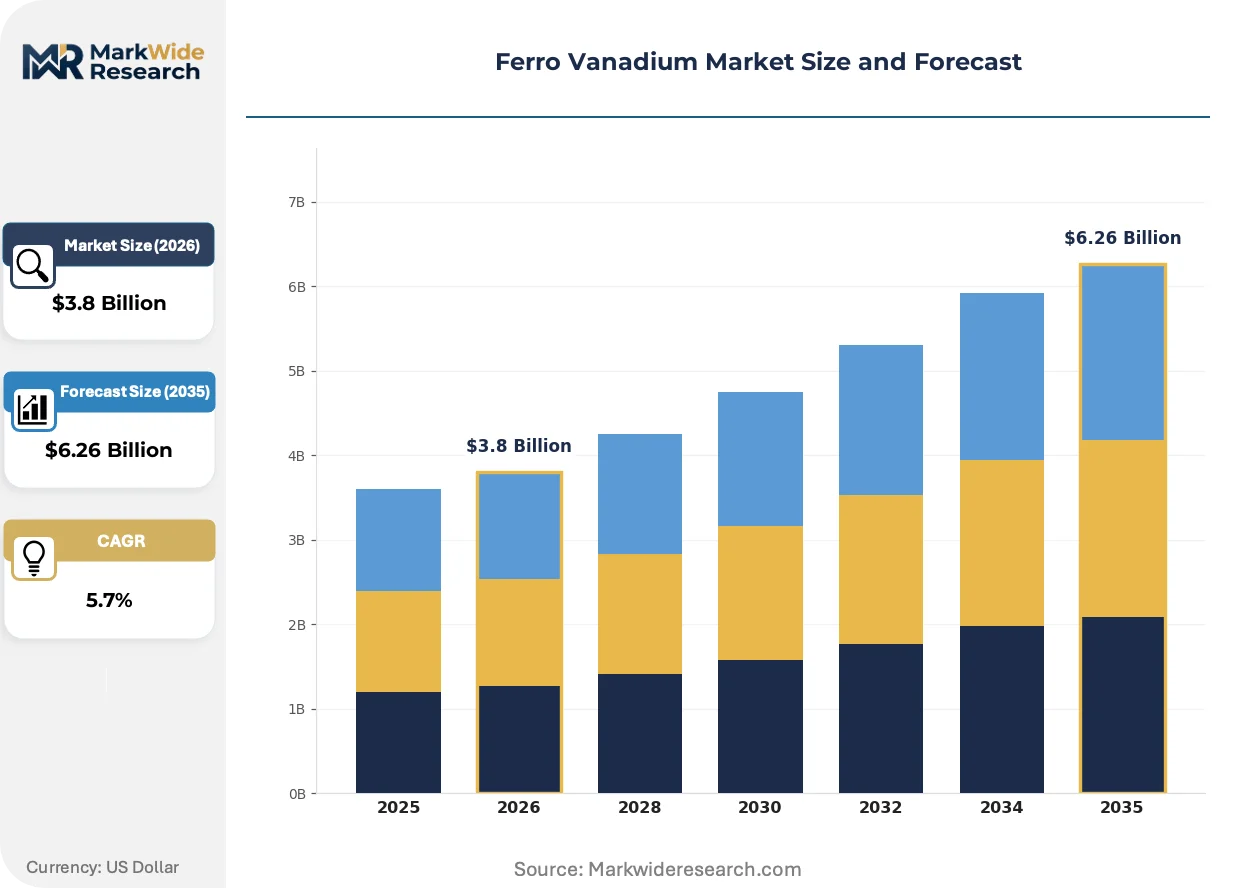
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FeV 80, FeV 50, FeV 60, FeV 70 Application: Alloy Production, Steel Manufacturing, Titanium Alloys, Aerospace Components End User: Construction, Automotive, Aerospace, Energy Distribution Channel: Direct Sales, Online Sales, Distributors, Resellers |
| Companies Covered | Evraz PLC, voestalpine AG, Glencore PLC, Treibacher Industrie AG, Ferroglobe PLC, AMG Advanced Metallurgical Group NV, Bushveld Minerals, Qinghai Salt Lake Industry Co., Ltd., Tsingshan Holding Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferro Vanadium Market Emerging Trajectories
Electrification of steelmaking and tightening emissions accounting are bifurcating ferro vanadium procurement between carbon-intensive legacy supply and certified low-carbon alternatives.
Silicothermic reduction technology is displacing conventional aluminothermic processes in pilot installations. Nippon Steel and Voestalpine are testing silicon-based reductant formulations that cut CO2 intensity by 40% per tonne FeV. This process shift is bifurcating the market between premium low-carbon grades and commodity construction specifications.
REACH authorization requirements for vanadium pentoxide are tightening raw material traceability obligations. ECHA's 2024 substance evaluation roadmap demands full supply chain disclosure for ferroalloy importers. European aerospace and medical titanium producers are responding by qualifying dual-source FeV suppliers with certified conflict-free ore documentation.
Steel mill procurement departments are consolidating ferro vanadium contracts under multi-year framework agreements. Japanese automotive OEMs through their keiretsu trading houses are displacing spot market purchases with integrated supply partnerships. This concentration is most visible in the Kansai and Chukyo industrial corridors where Toyota and Honda have centralized alloy purchasing through Itochu and Mitsui.
Ferro Vanadium Market Segmentation
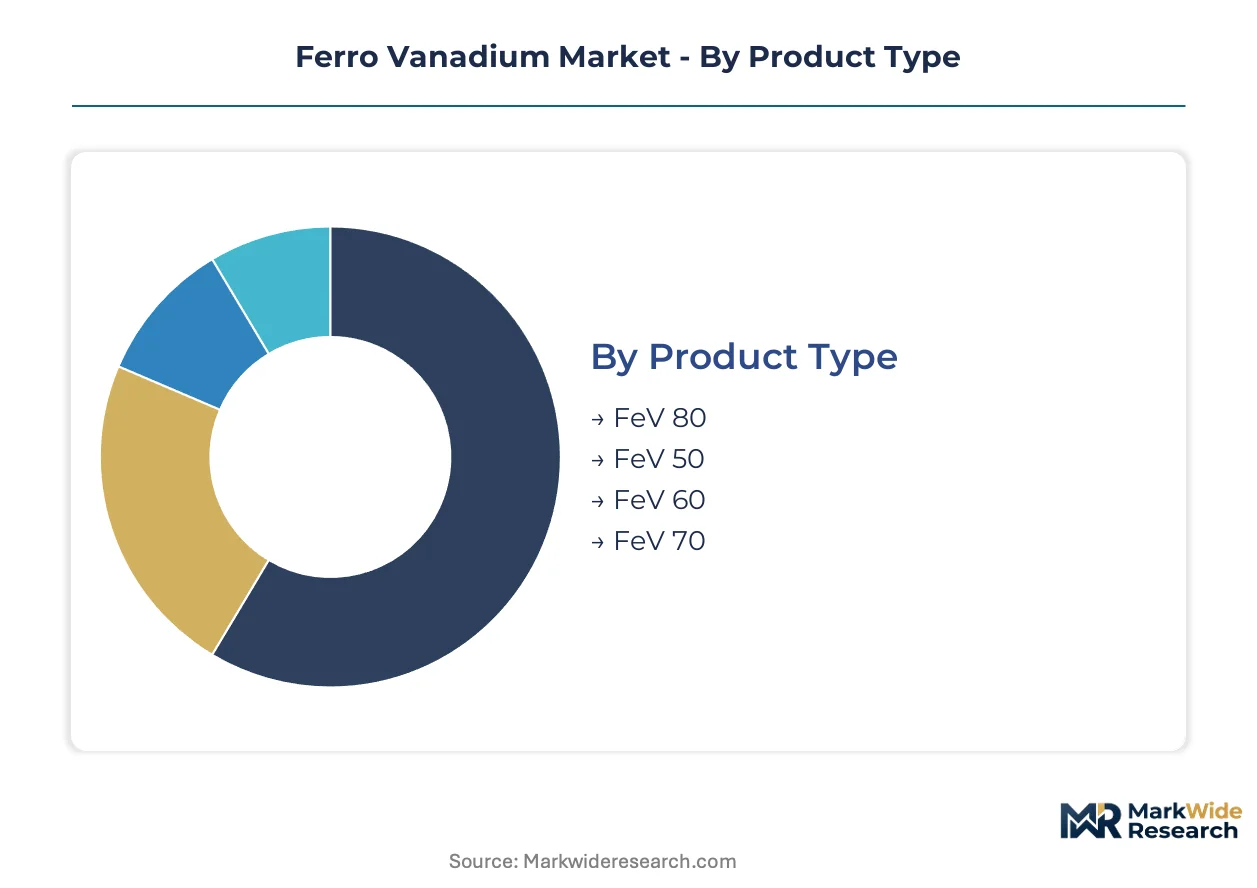
Ferro vanadium procurement patterns diverge sharply across purity grades and end-use specifications. Aerospace qualification requirements and steel mill cost optimization create fundamentally different demand profiles that reshape competitive positioning within each segment.
Product Type:
Niobium substitution pressure intensifies at lower vanadium concentrations, forcing FeV 50 and FeV 60 producers to defend specification boundaries against microalloying alternatives.
- FeV 80:Contains 78-82% vanadium by weight with stringent sulfur and phosphorus limits below 0.05%. Pratt & Whitney and Rolls-Royce turbine blade programs in Connecticut and Derby concentrate offtake for single-crystal titanium alloys where purity thresholds exclude lower grades. GB standards enforcement in China is tightening traceability documentation for aerospace-certified batches.
- FeV 50:Standard construction-grade alloy with 48-52% vanadium content serving rebar and structural beam specifications. POSCO's Gwangyang complex and Chinese integrated mills around Tangshan absorb volume for high-strength low-alloy plate production, though niobium microalloying below 0.05% vanadium equivalence is eroding share in automotive body-in-white applications.
- FeV 60:Mid-range specification bridging construction and specialty steel requirements with 58-62% vanadium content. Hyundai Steel's Dangjin facility specifies this grade for pipeline and offshore platform grades where weldability demands moderate hardenability.
- FeV 70:Higher-purity construction alloy with 68-72% vanadium serving European automotive stamping operations. Voestalpine's Linz facility qualifies this grade for hot-formed structural components requiring consistent hardenability response.
FeV 50 retains volume leadership; FeV 80 holds the steepest expansion curve.
Application:
Carbon intensity accounting is bifurcating procurement between legacy steelmaking specifications and certified low-carbon alternatives for automotive and aerospace supply chains.
- Steel Manufacturing:Dominant volume application incorporating ferro vanadium as hardenability agent and grain refiner in high-strength low-alloy grades. China's Shandong and Sichuan furnace clusters supply construction rebar and shipbuilding plate specifications, though ETS carbon pricing is reshaping European mill sourcing toward silicothermic-reduced alternatives.
- Titanium Alloys:Aerospace-grade vanadium additive for alpha-beta titanium formulations in engine discs and compressor blades. Boeing and Airbus tier-one suppliers in Wichita and Toulouse are negotiating 7-10 year supply agreements to secure FeV 80 against spot volatility.
- Alloy Production:Master alloy feedstock for specialty nickel and cobalt superalloys requiring precise vanadium addition. Carpenter Technology's Reading, Pennsylvania facility specifies certified low-carbon FeV for aerospace superalloy vacuum induction melting.
- Aerospace Components:Direct structural titanium applications including landing gear forgings and airframe fasteners. Howmet Aerospace's Cleveland operations qualify dual-source FeV suppliers with full ore traceability under ECHA's tightening substance evaluation requirements.
Steel Manufacturing absorbs the dominant volume share; Titanium Alloys are expanding most quickly.
End User:
Procurement concentration patterns vary by sector maturity, with automotive keiretsu structures displacing spot market purchases while energy sector buyers shift toward long-term direct contracting.
- Construction:Infrastructure and building steel specifications driving FeV 50 consumption through rebar and structural sections. China's dual carbon goals are tightening emissions intensity standards for construction-grade ferroalloy procurement.
- Automotive:Hot-stamped body-in-white and chassis components requiring consistent hardenability performance. Toyota and Honda through Itochu and Mitsui trading houses have centralized alloy purchasing across Kansai and Chukyo industrial corridors under multi-year framework agreements.
- Aerospace:Engine and airframe titanium alloy specifications demanding certified FeV 80 with full supply chain disclosure. ECHA's 2024 substance evaluation roadmap is compressing registration windows for non-EU exporters serving this segment.
- Energy:Pipeline and offshore platform specifications requiring weldable high-strength grades. Saudi Aramco and Equinor are shifting procurement toward long-term direct contracts to secure supply against spot market volatility.
Construction retains volume leadership; Aerospace holds the steepest expansion curve.
Distribution Channel:
Channel structure reflects customer scale and specification complexity, with large steel mills and aerospace OEMs bypassing intermediaries while smaller specialty alloy producers rely on distributor technical support.
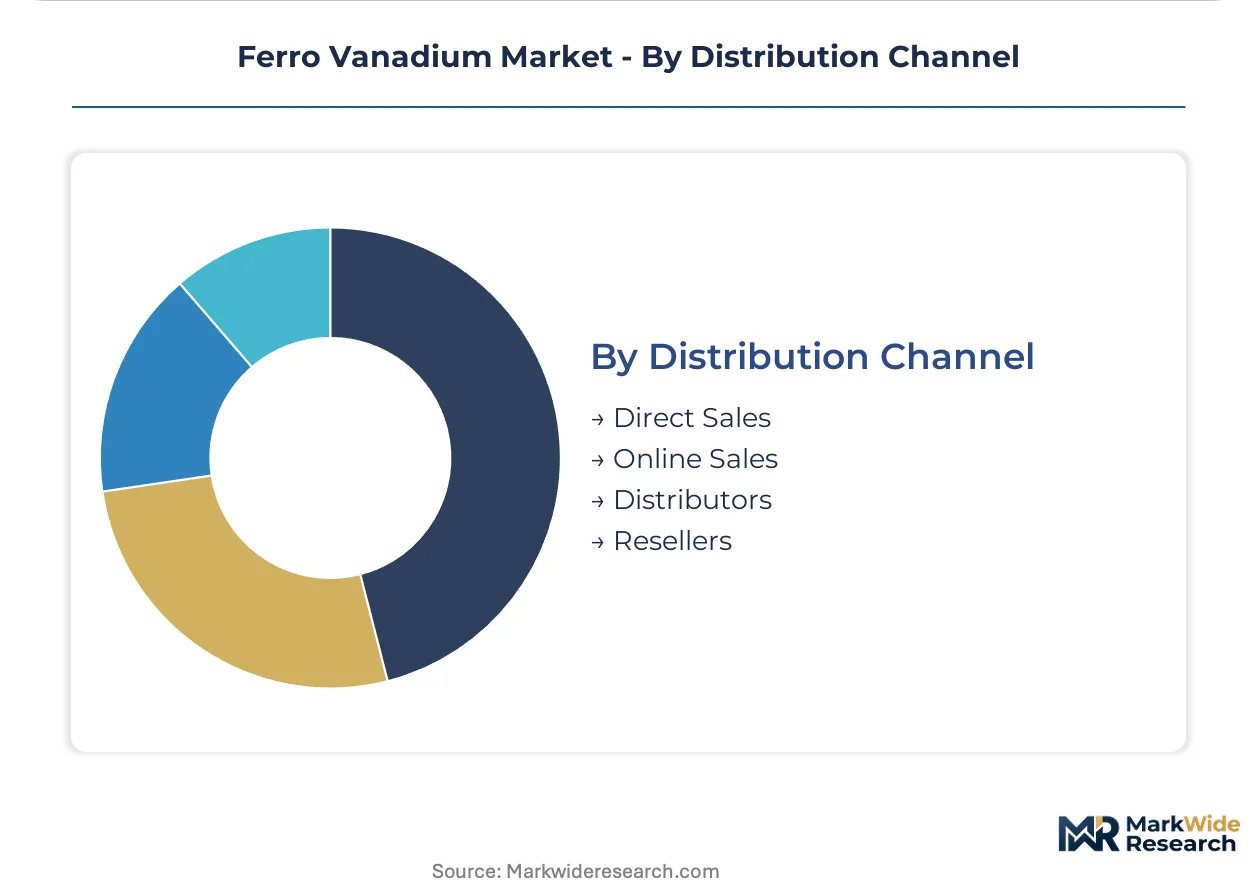
- Direct Sales:Long-term supply agreements between ferro vanadium producers and large steel mills or aerospace tier-ones. Evraz PLC leverages captive Russian feedstock to sustain cost advantages through direct contracting with European automotive stamping operations.
- Distributors:Technical intermediaries providing alloy specification guidance and inventory management for mid-size specialty steel producers. European distributors are consolidating around REACH-compliant suppliers with certified conflict-free ore documentation.
- Resellers:Spot market traders serving small-scale foundries and alloy blenders with variable demand patterns. Carbon border adjustment mechanism implementation is compressing margins for traders handling carbon-intensive legacy supply.
- Online Sales:Digital procurement platforms for standard-grade construction specifications with transparent pricing. Indian specialty steel producers under PLI scheme incentives are testing online channels for tariff-protected domestic ferroalloy sourcing.
Direct Sales retains volume leadership; Online Sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European carbon border pricing grants domestic ferro vanadium producers a structural premium over Chinese furnace clusters, while South Korean specialty steel demand concentrates procurement power in East Asian port cities. This geographic asymmetry shapes where new capacity locates and which regulatory frameworks dominate investment decisions.
China
Shandong and Sichuan furnace clusters supply construction rebar and shipbuilding plate specifications for domestic steel mills. MIIT enforces GB standards on ferroalloy emissions intensity, accelerating equipment upgrades before 2026 compliance deadlines. Tangshan integrated mills around Bohai Bay are tightening ferro vanadium quality differentials as dual carbon goals reshape raw material sourcing requirements.
South Korea
POSCO and Hyundai Steel are expanding high-strength low-alloy capacity around Gwangyang and Dangjin, concentrating regional ferro vanadium demand for automotive and offshore applications. The country's national industrial regulator enforces emissions standards aligned with EU carbon border adjustment mechanisms. Busan-Ulsan port infrastructure enables just-in-time ferroalloy delivery to specialty steel complexes.
Germany
Automotive stamping operations through Volkswagen and BMW supply chains specify FeV 70 for hot-formed structural components requiring consistent hardenability. ECHA's REACH framework and EU F-Gas Regulation constrain production chemistry options for domestic ferroalloy suppliers. North Rhine-Westphalia's Ruhr industrial corridor hosts Voestalpine's Linz-connected distribution network for premium construction grades.
United States
Pratt & Whitney's Connecticut turbine blade programs and Howmet Aerospace's Cleveland operations qualify FeV 80 suppliers with full ore traceability under tightening substance evaluation requirements. EPA oversight of smelter emissions shapes where new ferro vanadium capacity can locate domestically. The Midwest industrial belt around Detroit and Chicago concentrates automotive alloy procurement through keiretsu-style trading relationships.
South Africa
Bushveld Minerals anchors raw material security strategies around Southern African ore bodies rather than scale advantages in ferro vanadium reduction. The Department of Mineral Resources and Energy influences licensing timelines for vanadium extraction and beneficiation projects. Gauteng province's pyrometallurgical expertise supports merchant producer operations serving European aerospace qualification programs.
Ferro Vanadium Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated miners commanding feedstock security and merchant producers differentiating through reduction process sophistication. The vendor base spans three tiers: Russian and Chinese integrated steel groups with captive vanadium slag, European technology specialists with advanced furnace capabilities, and Southern African ore-body owners competing on raw material traceability. Dominant competitive moves include backward integration into vanadium pentoxide supply and geographic repositioning to escape carbon border adjustment exposure.
Within the integrated mining tier, Evraz PLC and Glencore PLC exemplify cost structures built on captive feedstock from steel slag and primary ore operations. AMG Advanced Metallurgical Group NV occupies a position among European technology specialists navigating tightening EU emissions standards through advanced metallurgical capabilities. Bushveld Minerals represents the ore-security archetype, anchoring competitive positioning around Southern African vanadium deposits rather than downstream scale.
| Leading Market Players |
|---|
| Evraz PLC |
| voestalpine AG |
| Glencore PLC |
| Treibacher Industrie AG |
| Ferroglobe PLC |
| AMG Advanced Metallurgical Group NV |
| Bushveld Minerals |
| Qinghai Salt Lake Industry Co., Ltd. |
| Tsingshan Holding Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
REACH authorization requirements for vanadium pentoxide gate both supply qualification and price differentiation simultaneously, compressing registration windows for non-EU exporters while granting certified European producers structural premiums over carbon-intensive furnace clusters.
Pricing Analysis
The customization-premium spread between aerospace-certified FeV 80 and standard construction-grade FeV 50 runs wide. Pricing stratifies across aerospace-certified, automotive-qualified, and commodity construction tiers based on purity thresholds and carbon intensity documentation. Cost compression in FeV 50 is intensifying because niobium microalloying displaces vanadium in automotive body-in-white applications. Construction steel mills exhibit the highest price sensitivity; aerospace OEMs through long-term offtake agreements show the least.
Supply Chain Analysis
China and Russia anchor global vanadium pentoxide supply through integrated steel slag operations and primary ore extraction. Ferro vanadium reduction draws from V2O5 feedstock, aluminum or silicon reductants, and high-purity iron units. Single-source vulnerability concentrates in Chinese and Russian integrated slag operations controlling over sixty percent of upstream feedstock. Distribution runs through direct long-term contracts for large mills, technical distributors for mid-size specialty producers, and spot traders for small foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Japanese automotive keiretsu and European aerospace tier-ones, with procurement centralization through trading houses and long-term framework agreements displacing spot market purchases.
For Market Incumbents: Compound captive feedstock advantages through backward integration into vanadium pentoxide supply while accelerating silicothermic furnace upgrades to escape EU carbon border adjustment exposure. Defend specification boundaries against niobium substitution in sub-0.05% vanadium equivalence microalloying grades by embedding FeV into automotive platform engineering cycles early. For New Entrants and Emerging Players: Differentiate on certified low-carbon production credentials to serve European green hydrogen-based DRI-EAF steelmaking clusters in Sweden and Norway. The most penetrable white-space sits in India's tariff-protected domestic ferroalloy capacity expansion under PLI scheme incentives. A go-to-market angle anchored to full ore traceability documentation addresses tightening ECHA substance evaluation requirements for aerospace qualification programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicothermic reduction technology deployments as European carbon pricing reshapes furnace economics. Long-term viability over a five-to-ten year window favors ore-body owners with upstream resource control over pure merchant reduction plays. The acquisition target archetype combines Southern African vanadium deposits with existing European aerospace qualification pathways. The signal to watch as inflection indicator is carbon border adjustment mechanism implementation timelines reshaping trade economics for carbon-intensive master alloys.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vanadium Pentoxide | Evraz PLC leverages captive Russian feedstock to sustain cost advantages across the alloy value chain. |
| Silicothermic Reduction Technology Deployment | Nippon Steel and Voestalpine pilot silicon-based reductant formulations cutting CO2 intensity by forty percent per tonne FeV. |
| Long-term Aerospace Supply Agreement | Boeing and Airbus tier-one suppliers negotiate seven-to-ten year vanadium supply agreements to secure titanium alloy feedstock. |
| Geographic Repositioning to Low-carbon Grids | Green hydrogen-based DRI-EAF steelmaking in Sweden and Norway creates premium FeV demand for ultra-low-carbon automotive grades. |
| Conflict-free Ore Traceability Certification | European aerospace and medical titanium producers qualify dual-source FeV suppliers with certified ore documentation under ECHA requirements. |
Methodological Framework
Operator-level perspectives from ferroalloy plant managers, steel mill procurement leads, aerospace tier-one metallurgists, and trading house alloy specialists anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, SEC filings of listed producers, and ECHA substance evaluation roadmaps. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from steel production forecasts and aerospace build rates.
Sensitivity analysis tested forecast outputs against variable inputs including carbon pricing trajectories, niobium substitution elasticity in automotive grades, and aerospace titanium alloy qualification timelines. Segmentation dimensions modeled include vanadium concentration grade, reduction process technology, end-use application, and regional regulatory cluster. CAGRs derived from historical volume trends, announced capacity expansions, and demand elasticity coefficients across steel manufacturing and titanium alloy applications.
Material uncertainties — carbon border adjustment mechanism implementation scope, REACH authorization timeline compression, and vanadium slag supply concentration risk — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and substitution technology maturation. Recalibration cycles align with material shifts in emissions standards enforcement and aerospace platform engineering decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferrochrome Market
Metals
Armour Steel Plate Market
Metals
Anodized Titanium Market
Metals
Zirconium Market
Metals
Steel Casting Market
Metals
Seamless Stainless Steel Products Market
Metals
Ore Metals Market
Metals
Galvanized Steel Market
Metals
North America and Europe Metal Powder Market
Metals
Expanded Metal Foils Market
Metals
Tungsten Metal Powder Market
Metals
Copper Clad Aluminum Wire Market
Metals
Europe Metal Service Centers Market
Metals
Stainless Steel Round Bar Market
Metals
Europe Aluminium Powder Market
Metals
Silver Powder and Flakes Market