
 Copper Clad Aluminum Wire Market | 2026-2036
Copper Clad Aluminum Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Clad Aluminum Wire Market Insights
The copper clad aluminum wire market is pivoting on a widening divergence between premium conductor grades certified for automotive and aerospace applications and commodity grades serving generic building wire. Encore Wire Corporation leverages its North American manufacturing footprint to dominate utility-scale power cable contracts. Fujikura Ltd. anchors its position through deep specialization in telecommunications-grade stranded conductors with tight impedance tolerances. Hengtong Group Co., Ltd. competes on sheer manufacturing scale, sustaining cost leadership across standard solid wire product lines.
Copper clad aluminum wire consists of an aluminum core metallurgically bonded with a copper outer layer, typically achieving 15% copper by volume while delivering conductivity approximating pure copper at roughly one-third the weight. Electroplating and cladding technologies determine bond integrity and conductivity consistency, with continuous casting gaining traction for high-volume stranded wire production. Solid wire occupies the mature volume tier in residential and commercial building applications, while stranded wire captures expanding margin pools in telecom and automotive harnesses where flexural fatigue resistance commands specification premiums. Tinned wire variants serve marine and outdoor environments where oxidation resistance shapes procurement decisions.
The US market operates under NHTSA vehicle safety standards and NEC electrical codes that govern conductor ampacity and fire resistance ratings, while China's GB standards and MIIT directives enforce material efficiency benchmarks favoring lightweight alternatives. Japan's METI energy conservation regulations and JIS standards further codify performance thresholds for power distribution applications. Stakeholders must monitor evolving automotive electrification standards and cross-border certification reciprocity as OEMs consolidate supplier bases across multiple regulatory jurisdictions.
Market Dynamics
Automotive electrification and China's dual carbon mandates are compressing specification cycles for lightweight conductors, forcing rapid recertification of copper clad aluminum grades across multiple voltage tiers and thermal classes.
Growth Catalysts
- Automotive wiring harness demand:OEMs specify copper clad aluminum for high-voltage battery interconnects to achieve mass reduction targets without sacrificing ampacity.
- GB standards on energy efficiency:China's tightening material efficiency benchmarks accelerate substitution away from pure copper in power distribution cables.
- Continuous casting technology:High-volume stranded wire production achieves tighter impedance tolerances for telecommunications-grade applications.
Market Restraints
- Copper price volatility:Raw material cost swings compress margins for cladding operations dependent on spot copper cathode purchases.
- Bond integrity limitations:Electroplating defects in low-cost grades create reliability risks in high-temperature automotive engine compartments.
- Pure copper substitution resilience:Aerospace and medical device manufacturers maintain pure copper specifications despite weight penalties.
Strategic Opportunities
- Marine tinned wire expansion:Saltwater corrosion resistance specifications open premium pricing tiers for oxidation-resistant cladding variants.
- India cable infrastructure buildout:Grid modernization programs create demand for cost-optimized conductors in rural electrification projects.
- 5G base station deployment:Telecommunications infrastructure requires high-frequency stranded conductors with precise impedance control.
Industry Challenges
- Cross-border certification reciprocity:OEM supplier consolidation demands simultaneous compliance with NHTSA, GB, and JIS testing protocols.
- Metallurgical bonding expertise scarcity:Continuous casting process engineers command premium compensation in East Asian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Clad Aluminum Wire Market |
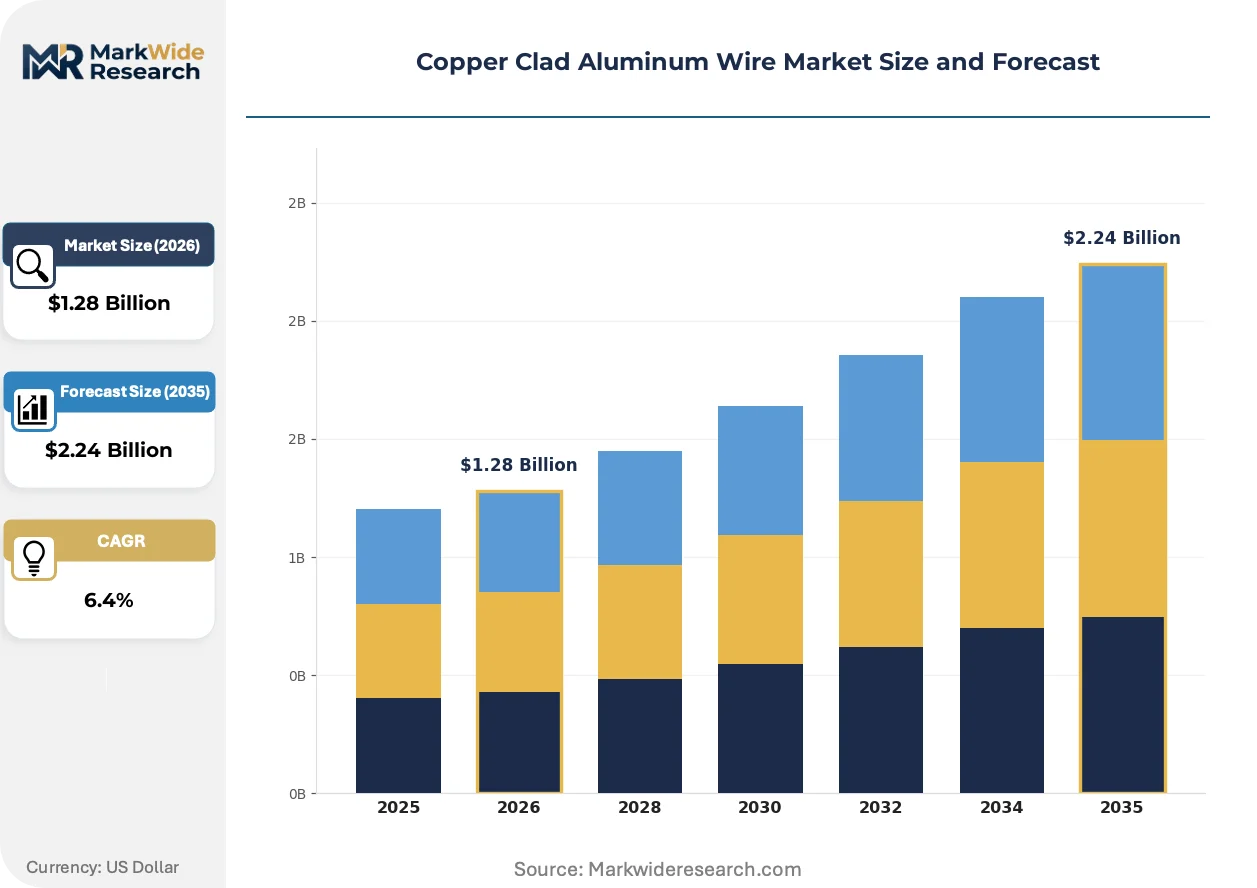
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Wire, Stranded Wire, Tinned Wire, Coated Wire Technology: Electroplating, Cladding, Continuous Casting, Ultrasonic Bonding Application: Power Transmission, Telecommunication Cabling, Electronics Manufacturing, Automotive Wiring End User: Electrical Contractors, Telecom Operators, Electronic Assemblers, Vehicle Manufacturers |
| Companies Covered | Encore Wire Corporation, Fujikura Ltd., AFL Global, General Cable Corporation, Furukawa Electric Co., Ltd., Belden Inc., Finolex Cables Ltd., Hengtong Group Co., Ltd., CommScope Holding Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Clad Aluminum Wire Market Trends and Innovations
Manufacturing process intensification and regulatory specification tightening are redefining competitive differentiation around bond integrity testing and thermal cycling performance rather than commodity conductivity metrics.
Continuous casting with in-line annealing is expanding into high-volume automotive harness production. Tier-1 suppliers in Jiangsu province adopt these lines for 800V battery platform cabling. The technology is expanding into applications previously reserved for solid-drawn pure copper conductors.
China's MIIT directives on material efficiency enforce minimum aluminum content thresholds in government-procured power cables. Provincial tender documents now disqualify pure copper bids below specified voltage classes. State Grid Corporation procurement specifications favor dual-certified GB/IEC products.
Automotive OEMs now mandate lot-level thermal cycling test reports rather than batch certificates. Harness suppliers in Zhejiang province maintain captive metallurgical laboratories for real-time bond integrity verification. This specification escalation filters down to second-tier wire producers within eighteen months.
Copper Clad Aluminum Wire Market Segmentation
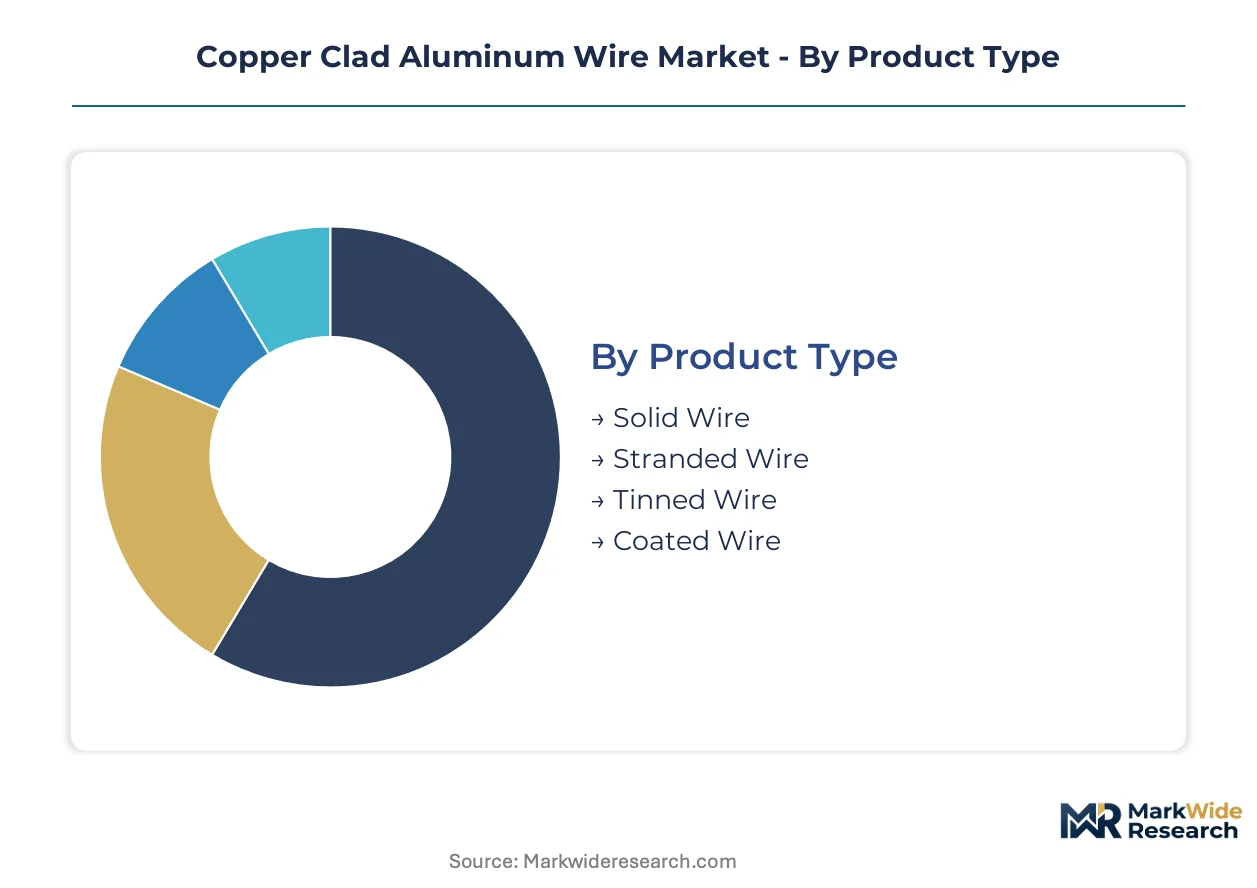
Segmentation in copper clad aluminum wire markets exposes divergent specification requirements across standalone conductor applications versus embedded component systems. Product form and bonding technology determine which segments serve discrete cable procurement versus integrated harness manufacturing.
Product Type:
Standalone conductor forms dominate bulk procurement for field installation, while coated variants embed directly into pre-assembled systems.
- Solid Wire:Single-core construction with uniform aluminum core and copper cladding serves residential and commercial building circuits. Jiangsu province cable manufacturers source solid wire for standard power distribution where installation flexibility matters less than cost efficiency.
- Stranded Wire:Multiple fine aluminum strands wrapped and copper-clad deliver superior flexural fatigue resistance. Automotive harness suppliers in Zhejiang province specify stranded construction for 800V battery interconnects where vibration tolerance commands premium positioning.
- Tinned Wire:Additional tin coating over copper cladding provides saltwater corrosion resistance for marine and coastal outdoor environments.
- Coated Wire:Polymer or enamel insulation layers enable direct embedding into motor windings and transformer coils without secondary sleeving.
Solid wire leads volumes today; stranded wire is gaining share fastest.
Technology:
Cost tiers separate laboratory-grade precision methods from high-volume production processes.
- Electroplating:Electrochemical copper deposition onto aluminum substrate achieves thin, uniform cladding layers suitable for low-frequency signal applications. Chinese commodity wire producers favor electroplating for standard building wire where bond integrity requirements remain moderate.
- Continuous Casting:Molten copper solidifies around aluminum core in continuous drawing operations, producing seamless metallurgical bonds with tight impedance tolerances. Fujikura Ltd. deploys continuous casting lines for telecommunications-grade stranded conductors serving 5G base station deployment.
- Cladding:Mechanical compression bonding of copper strip around aluminum core creates thick, durable layers for high-current power transmission.
- Ultrasonic Bonding:High-frequency vibration welding generates solid-state metallurgical joints without melting, preserving aluminum core properties for aerospace-grade specifications.
Cladding anchors volume production; continuous casting commands the steepest expansion trajectory.
Application:
Application segments stratify by margin structure, with embedded system integration capturing premium pricing over commodity infrastructure.
- Automotive Wiring:High-voltage harnesses for battery electric vehicles demand thermal cycling resistance and lot-level bond integrity verification. OEMs in Japan and Germany mandate copper clad aluminum for mass reduction targets in 800V platform architectures.
- Telecommunication Cabling:High-frequency signal transmission requires precise impedance control across stranded conductor bundles. China's 5G infrastructure buildout concentrates demand in Jiangsu and Guangdong manufacturing clusters.
- Power Transmission:Utility-scale distribution cables prioritize ampacity-to-weight ratios for long-span overhead lines.
- Electronics Manufacturing:Consumer device internal wiring favors ultra-fine gauge conductors with polymer coating for space-constrained assemblies.
Power transmission leads volumes today; automotive wiring is expanding most quickly.
End User:
Customer types separate specification authority from procurement execution across the value chain.
- Vehicle Manufacturers:Tier-1 automotive OEMs dictate material specifications through platform-level design decisions, bypassing traditional distributor channels. NHTSA safety standards and GB automotive wire standards govern their conductor certification requirements.
- Telecom Operators:State Grid Corporation and China Mobile procurement specifications favor dual-certified GB/IEC products with documented thermal cycling performance.
- Electrical Contractors:Installation firms source commodity-grade solid wire through regional distribution based on NEC ampacity compliance.
- Electronic Assemblers:Contract manufacturers procure coated wire on consignment for motor and transformer OEMs.
Electrical contractors lead volumes today; vehicle manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallurgical bonding specialists concentrate in East Asian manufacturing clusters, where continuous casting process engineers command premium compensation. Jiangsu and Zhejiang provinces anchor China's cable production capacity, while regulatory divergence across automotive electrification standards shapes cross-border procurement patterns.
China
State Grid Corporation procurement specifications favor dual-certified GB/IEC products with documented thermal cycling performance. MIIT directives on material efficiency enforce minimum aluminum content thresholds in government-procured power cables. Jiangsu province cable manufacturers source solid wire for standard power distribution where installation flexibility matters less than cost efficiency.
United States
NHTSA vehicle safety standards and NEC electrical codes govern conductor ampacity and fire resistance ratings for automotive and building applications. Utility-scale power cable contracts concentrate procurement authority with Encore Wire Corporation's North American manufacturing footprint. Texas and California manufacturing clusters serve regional distribution networks for residential and commercial building circuits.
Japan
METI energy conservation regulations and JIS standards codify performance thresholds for power distribution applications. Tier-1 automotive OEMs mandate copper clad aluminum for mass reduction targets in 800V platform architectures. Kansai and Chubu manufacturing regions specialize in telecommunications-grade stranded conductors with tight impedance tolerances.
Germany
CE marking and REACH compliance requirements shape automotive wiring harness specifications for battery electric vehicles. OEM supplier consolidation demands simultaneous compliance with NHTSA, GB, and JIS testing protocols. Bavaria and Baden-Württemberg industrial regions host harness assembly operations for European automotive platforms.
India
BIS certification and CEA grid modernization programs create demand for cost-optimized conductors in rural electrification projects. Finolex Cables Ltd. competes through regional distribution networks for NEC ampacity-compliant building wire. Maharashtra and Gujarat manufacturing clusters aggregate cable production capacity for domestic infrastructure buildout.
Copper Clad Aluminum Wire Market Competitive Landscape
Top-tier vendors anchor automotive and telecommunications certification tiers, while commodity-grade producers compete on electroplating throughput and raw material conversion efficiency. The vendor base stratifies around bond integrity testing capabilities, with continuous casting specialists commanding specification premiums over electroplating-dependent competitors. Three archetypes dominate: North American utility-scale contractors, East Asian high-volume manufacturers, and Japanese precision-stranding specialists. Capacity expansion and captive metallurgical laboratory investment represent the dominant competitive moves as OEMs mandate lot-level thermal cycling test reports.
Within the premium-tier vector, Fujikura Ltd. and Furukawa Electric Co., Ltd. exemplify telecommunications-grade specialization with tight impedance tolerance capabilities. Hengtong Group Co., Ltd. occupies a position at the scale-driven end of the market, sustaining cost leadership across standard solid wire product lines. Encore Wire Corporation represents North American manufacturing footprint advantages for utility-scale power cable contracts. These three anchors illustrate how geographic concentration, certification depth, and production technology separate competitive tiers in a market pivoting on bond integrity rather than commodity conductivity metrics.
| Leading Market Players |
|---|
| Encore Wire Corporation |
| Fujikura Ltd. |
| AFL Global |
| General Cable Corporation |
| Furukawa Electric Co., Ltd. |
| Belden Inc. |
| Finolex Cables Ltd. |
| Hengtong Group Co., Ltd. |
| CommScope Holding Company, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between automotive-lot-verified copper clad aluminum and commodity electroplated building wire manifests in parallel pricing stratification and supply chain concentration. Premium grades command specification premiums through captive metallurgical laboratories in Jiangsu province, while commodity grades compete on cathode conversion efficiency across dispersed electroplating operations.
Pricing Analysis
Unbundled conductor procurement dominates utility-scale and automotive harness contracts, while bundled certification-plus-testing packages capture premium positioning for 800V battery platform suppliers. Price differentiation separates lot-level thermal cycling documentation from batch certificates, with OEM direct contracts least sensitive to spot copper volatility and distributor-dependent electrical contractors most exposed. Cost compression in commodity electroplated grades intensifies because Chinese provincial tender documents now disqualify pure copper bids, forcing margin absorption at the cladding operation level.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and telecom operator demand, while regional distributors serve electrical contractor procurement. Raw material supply concentrates in China, Chile, and the United States for aluminum smelting and copper cathode production. Continuous casting equipment and high-purity aluminum billet feedstock constitute critical input dependencies. Single-source vulnerability sits with metallurgical bonding expertise scarcity in East Asian manufacturing clusters. Distribution runs through State Grid Corporation consolidated procurement for power transmission and Tier-1 harness assembler consignment for automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where China's MIIT material efficiency mandates accelerate substitution faster than NHTSA safety standard reciprocity permits North American adoption, creating a regulatory cost differential favoring early certification investment in GB-standard production.
For Market Incumbents: Anchor certification depth against emerging electroplating competitors from India's cable infrastructure buildout. Defend automotive harness positioning through captive metallurgical laboratory investment in Zhejiang province. Prioritize backward integration into continuous casting equipment supply to secure process engineer talent pools. For New Entrants and Emerging Players: China's GB standards on energy efficiency open a window for stranded wire specialization targeting State Grid Corporation dual-certified procurement. Penetrate the marine tinned wire segment where saltwater corrosion specifications remain underserved by incumbent commodity producers. Pursue telecom operator direct contracting for 5G base station deployment with impedance tolerance guarantees. For Investors and Strategic Acquirers: Consolidation pressure builds where electroplating-dependent commodity producers face simultaneous copper price volatility and provincial tender disqualification risks. Long-term viability favors continuous casting specialists with automotive platform certification depth. Watch for State Grid Corporation procurement specification shifts toward mandatory lot-level testing as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Metallurgical Laboratory Investment | Enables real-time bond integrity verification required by automotive OEMs in Zhejiang province. |
| Continuous Casting Capacity Expansion | Captures telecommunications-grade stranded conductor demand from China's 5G infrastructure deployment. |
| Dual GB/IEC Certification Pursuit | Qualifies suppliers for State Grid Corporation consolidated procurement specifications. |
| Marine Tinned Wire Product Line Launch | Addresses saltwater corrosion resistance specifications in coastal power distribution applications. |
| Backward Integration into Aluminum Billet Supply | Reduces exposure to high-purity feedstock price volatility from Chinese smelter concentration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged continuous casting process engineers, Tier-1 automotive harness procurement managers, State Grid Corporation tender specification officers, and telecommunications infrastructure planners. Secondary validation drew from MIIT directive filings, GB standard revision notices, NHTSA safety standard dockets, and customs trade data for copper clad aluminum wire shipments. Bottom-up production capacity modeling and top-down end-use demand estimation were cross-referenced for triangulation.
Comparable historical periods anchored the projection horizon against documented technology adoption cycles and regulatory implementation timelines. Segmentation dimensions modeled include product form, bonding technology, application vertical, and end-user procurement authority. CAGRs were derived from production capacity expansion announcements correlated with OEM platform standardization roadmaps. Forecast inputs incorporated automotive electrification mass reduction targets and China's dual carbon policy enforcement intensity.
Revisions become necessary when automotive electrification standards diverge across NHTSA, GB, and JIS jurisdictions, or when copper-aluminum price ratios shift materially. Forecasts reflect assumptions about certification reciprocity timelines and continuous casting technology diffusion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Hafnium Foil Market
Metals
7075 T6 Aluminum Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Iron Casting Market
Metals
Anodized Titanium Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
High Purity Pig Iron Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Welding Materials Market
Metals
Lanthanum Market
Metals
Ferrosilicon Market
Metals
Stainless Steel 400 Series Market
Metals
Global Precious Metal Market
Metals
Aluminum Scrap Recycling Market
Metals
Aluminum Flat-Rolled Products Market