
 Copper Powder Market | 2026-2036
Copper Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Powder Market Analysis
Chilean concentrate supply is shifting toward Asian smelters as Chinese electrolytic refiners expand cathode-to-powder conversion capacity. Kymera International leverages its North American atomization footprint to serve aerospace contractors with certified spherical grades. Mitsui Mining & Smelting Co. anchors Japanese supply through captive mine-to-powder integration. Pometon S.p.A. specializes in water-atomized irregular morphologies for European friction material producers.
Copper powder consists of finely divided metallic copper particles, typically produced through atomization, electrolysis, or chemical reduction, with particle sizes ranging from sub-ten microns to several hundred microns and purity levels often exceeding 99.5 percent depending on end-use specifications. Its primary industrial purpose centers on enabling dense, conductive structures in powder metallurgy, thermal management components, and surface coatings where wrought copper forms prove impractical. Atomized copper powder leads volume due to its suitability for additive manufacturing feedstock, while electrolytic grades command margin premiums in electronics applications demanding ultra-high purity. Sintering remains the most mature application segment, though additive manufacturing represents the fastest-expanding demand pool as machine builders qualify copper alloys for laser powder bed fusion.
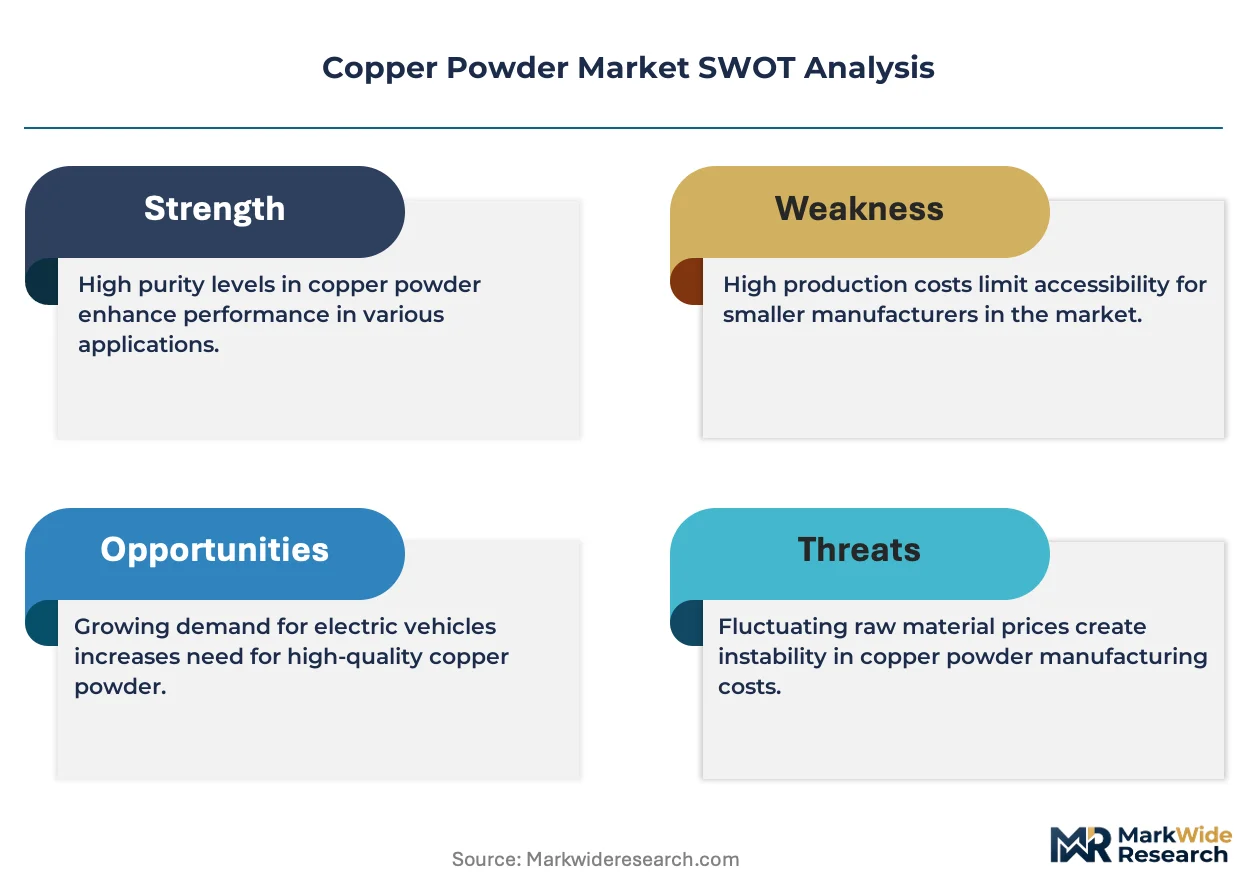
EPA air quality standards and OSHA workplace exposure limits shape North American production economics by mandating baghouse upgrades and respiratory protection protocols at atomization plants. REACH registration requirements in Europe restrict unregistered copper powder imports and compel suppliers to document substance properties through ECHA. China's MEE emissions standards for non-ferrous smelters are forcing domestic producers toward closed-loop water atomization systems that capture particulate. Stakeholders must monitor how evolving powder specifications for battery thermal interface materials reshape certification requirements across these regulatory regimes.
Market Dynamics
Electrification mandates across automotive and energy storage sectors are compressing qualification timelines for copper powder grades, forcing atomization capacity expansions ahead of traditional demand signals.
Growth Catalysts
- Automotive electrification:Battery thermal interface materials and motor windings consume electrolytic copper powder at volumes exceeding traditional sintering applications. OEMs in Germany and China are locking multi-year supply agreements.
- REACH registration:ECHA substance documentation requirements are filtering out unregistered imports across Europe, consolidating compliant suppliers into premium pricing tiers.
- Laser powder bed fusion:Machine builders are qualifying oxygen-free copper alloys for aerospace heat exchangers, creating certified feedstock demand that commands purity premiums above standard atomized grades.
Market Restraints
- Cathode price volatility:Electrolytic refiners pass LME copper swings directly to powder conversion economics, compressing margins for water-atomized product lines.
- Chilean concentrate concentration:Smelter feedstock dependence on Andean supply creates geographic vulnerability for Asian cathode-to-powder converters during port disruptions.
- Plasma atomization capex:Spherical grade production requires inert gas infrastructure that multiplies facility costs versus conventional water atomization, limiting supplier entry.
Strategic Opportunities
- Indian domestic sourcing:PLI scheme incentives for non-ferrous metal processing are attracting atomization joint ventures to serve emerging friction material and electrical component demand.
- Solid-state battery thermal management:Next-generation cell architectures require copper powder-based interface materials not yet specified in incumbent supply contracts.
- Closed-loop water systems:China's MEE emissions standards are mandating particulate capture retrofits that create technology licensing opportunities for equipment suppliers.
Industry Challenges
- Additive manufacturing metallurgist scarcity:Qualification of copper alloys for laser powder bed fusion requires specialized expertise concentrated at aerospace contractors and national labs.
- Spherical powder certification timelines:Aerospace material specifications demand eighteen-to-twenty-four-month qualification cycles that delay revenue recognition for new atomization entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Powder Market |
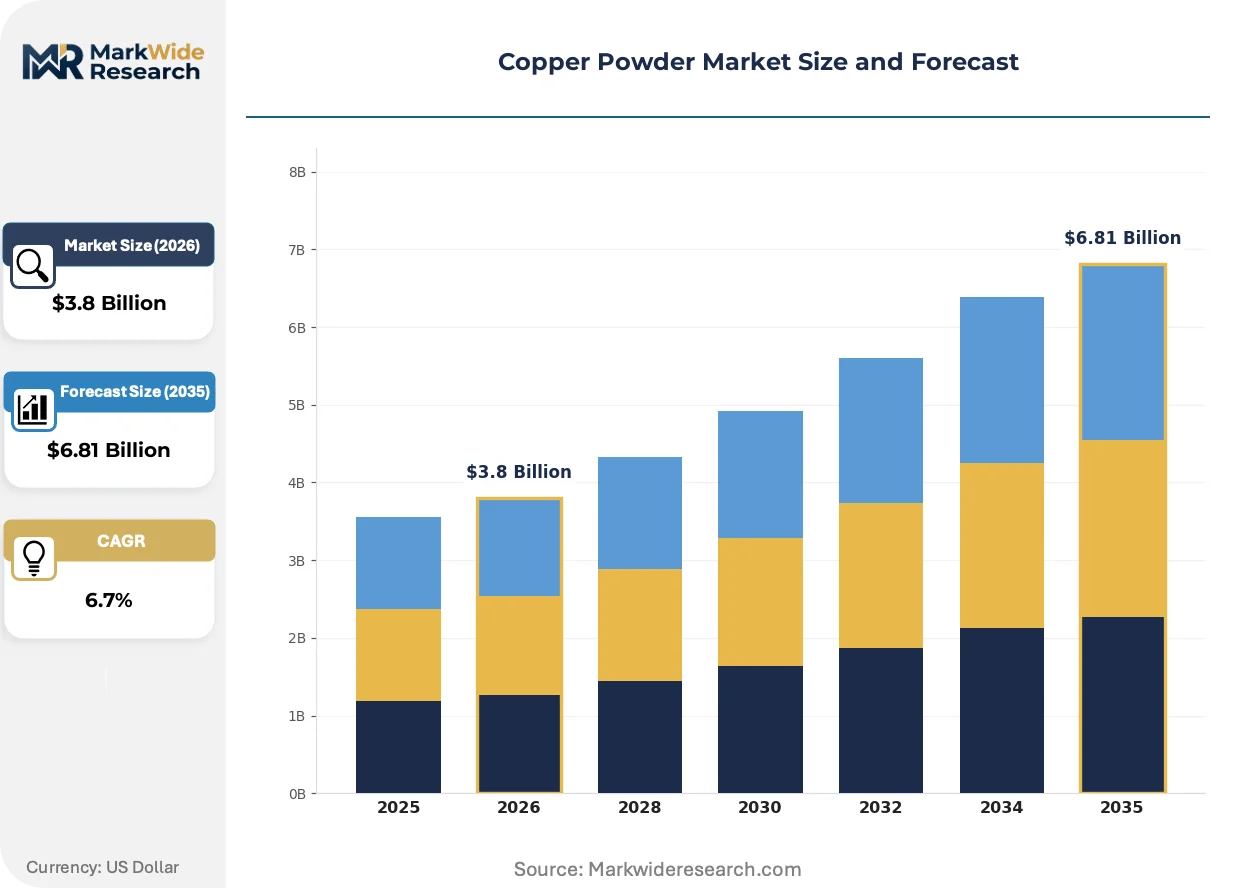
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Copper Powder, Electrolytic Copper Powder, Reduced Copper Powder, Copper Flake Application: Electrical Conductors, Additive Manufacturing, Sintering, Coatings End User: Aerospace, Electronics, Automotive, Renewable Energy Form: Powder, Granules, Pellets, Paste |
| Companies Covered | Kymera International, GGP Metalpowder AG, Mitsui Mining & Smelting Co., Carl Schlenk AG, Pometon S.p.A., Sumitomo Metal Mining Co. Ltd, Fukuda Metal Foil & Powder Co., American Chemet Corporation, Shanghai CNPC Powder Material Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Powder Market Emerging Trajectories
Process intensification and regulatory compliance automation are displacing legacy batch production economics. Suppliers are embedding real-time monitoring to preempt emissions violations and secure offtake from certified buyers.
Plasma atomization is expanding into spherical copper powder production for additive manufacturing feedstock. Aerospace heat exchanger fabricators are adopting these grades at pilot scale ahead of full production contracts. The technology is expanding into applications previously served by gas atomization, compressing acceptable oxygen content thresholds.
China's MEE emissions standards for non-ferrous smelters are mandating closed-loop water atomization systems with particulate capture rates above ninety-nine percent. Domestic producers are retrofitting facilities or facing production suspensions during inspection periods. Atomization plants in Shandong and Jiangsu provinces are prioritizing baghouse upgrades over capacity expansion.
Direct long-term contracting is displacing spot market purchases among automotive electrification suppliers. Tier-one motor manufacturers are locking three-to-five-year powder supply agreements to secure cathode conversion capacity. This pattern is most visible in Germany, where precision sintering operations anchor European offtake and resist price volatility through indexed contracts.
Copper Powder Market Segmentation
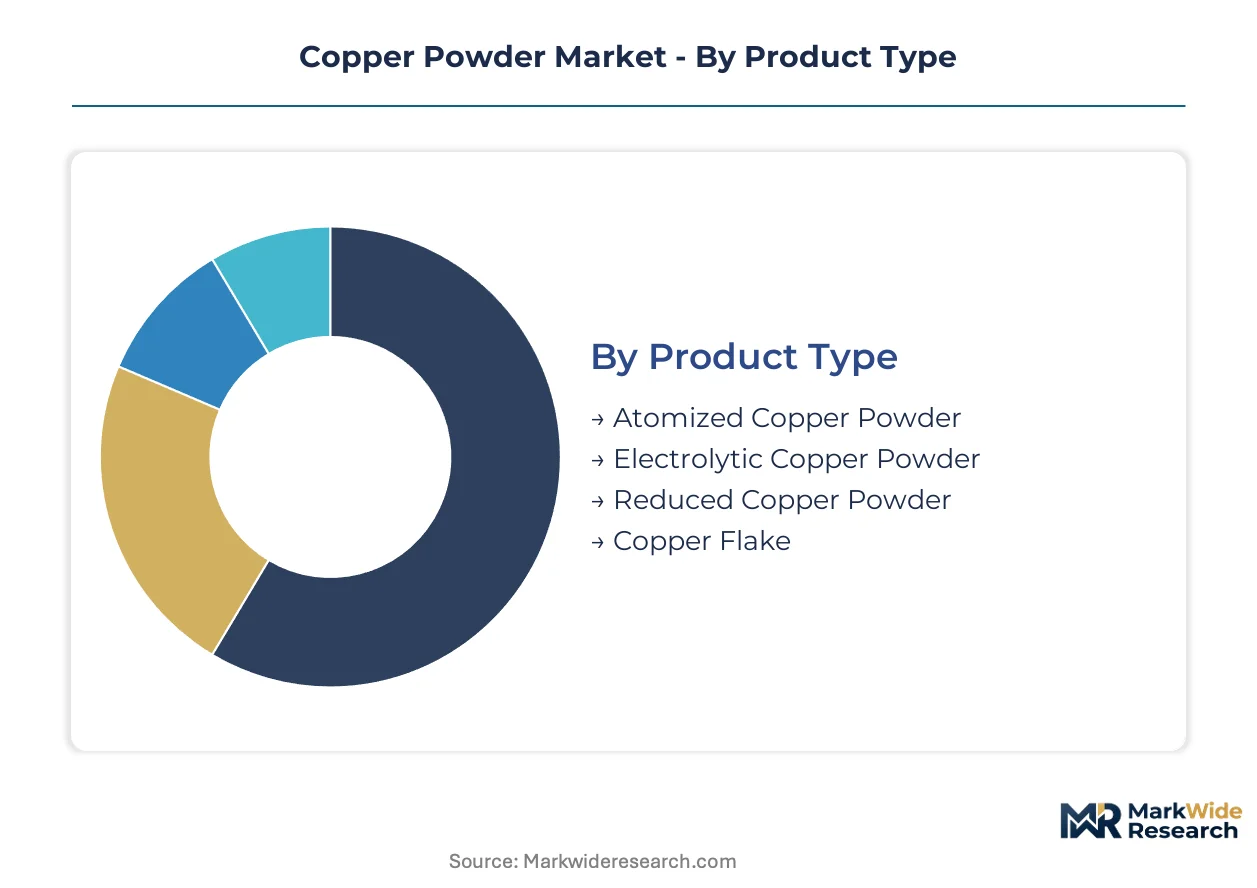
Copper powder grades diverge sharply in purity thresholds and particle morphology, forcing buyers to match atomization method against thermal conductivity requirements and regulatory certification needs. Segmentation discipline separates commodity sintering feedstock from aerospace-qualified spherical grades commanding substantial purity premiums.
Product Type:
Atomized grades dominate tonnage while electrolytic variants capture margin through ultra-high purity specifications.
- Atomized Copper Powder:Spherical particles produced through gas or water atomization of molten copper, with oxygen content typically below 0.3 percent for standard grades. Aerospace heat exchanger fabricators in Germany and the United States are locking multi-year offtake agreements for plasma-atomized spherical feedstock as laser powder bed fusion qualification accelerates.
- Electrolytic Copper Powder:Dendritic particles precipitated from copper sulfate solutions, routinely achieving 99.9 percent purity with controlled particle size distribution. Battery thermal interface material producers in China are consuming electrolytic grades at volumes that now rival traditional sintering applications, driven by electric vehicle motor winding specifications.
- Reduced Copper Powder:Oxide-reduced irregular particles offering cost advantages in friction material and chemical catalyst applications where morphology tolerance permits lower purity thresholds.
- Copper Flake:Lamellar particles manufactured through mechanical milling for conductive coatings and electromagnetic shielding applications requiring planar particle orientation.
Today's leader: Atomized Copper Powder. Tomorrow's challenger: Electrolytic Copper Powder.
Application:
Application segmentation tracks the shift from pressed-and-sintered components toward layer-wise manufactured thermal management architectures.
- Sintering:Conventional powder metallurgy processes for structural components, bearings, and electrical contacts remain the volume foundation. German automotive suppliers continue anchoring European offtake through precision sintering operations for transmission components.
- Additive Manufacturing:Laser powder bed fusion and binder jetting of copper alloys for conformal cooling channels and heat exchanger geometries. Aerospace contractors are qualifying oxygen-free copper grades eighteen-to-twenty-four months ahead of production contracts, creating certified feedstock demand pools.
- Electrical Conductors:Conductive inks, pastes, and filled polymers for printed circuit boards and flexible electronics. Japanese electronics manufacturers specify electrolytic grades with sub-ten-micron particle sizes for high-density interconnect applications.
- Coatings:Thermal spray and cold spray deposition for wear-resistant surfaces and electromagnetic interference shielding on aluminum substrates.
Sintering retains volume dominance. Additive manufacturing climbs the fastest.
End User:
End-user segmentation reveals electrification mandates compressing qualification timelines across mobility and energy storage sectors.
- Automotive:Battery thermal interface materials, motor windings, and power electronics packaging. OEMs in Germany and China are indexing long-term supply contracts to cathode conversion capacity rather than spot powder markets.
- Aerospace:Qualified spherical copper powder for heat exchangers and thermal management components. FAA certification pathways for additively manufactured flight hardware extend supplier qualification cycles.
- Electronics:Multi-layer ceramic capacitors, conductive adhesives, and semiconductor packaging materials requiring ultra-low oxygen content.
- Renewable Energy:Wind turbine slip rings, solar cell metallization pastes, and energy storage system thermal management.
Automotive anchors current demand. Aerospace represents the steepest expansion trajectory.
Form:
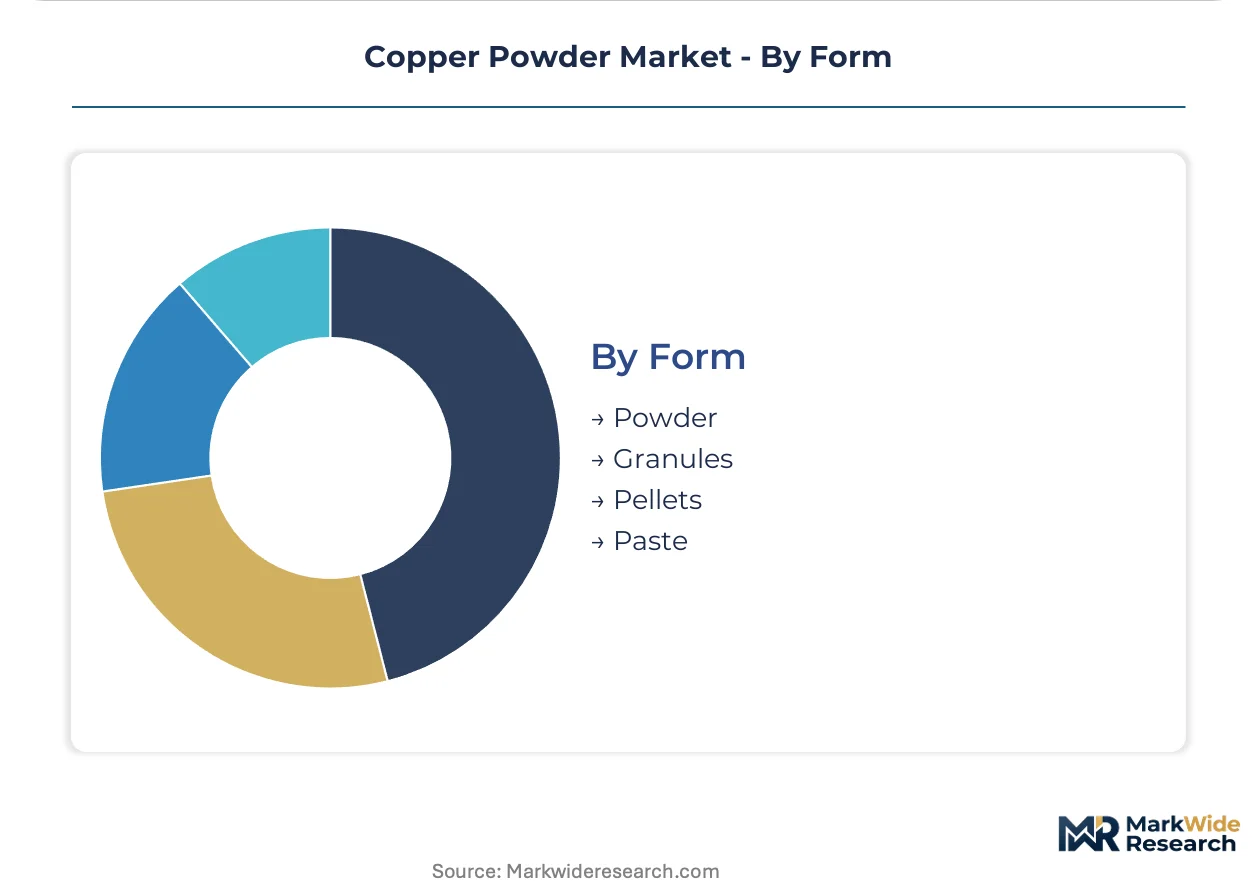
Physical form selection determines handling economics and dispersion requirements across powder metallurgy and coating processes.
- Powder:Free-flowing particulate form for additive manufacturing feedstock and powder metallurgy compaction. Atomization plants optimize particle size distribution for specific machine builder specifications.
- Paste:Copper powder dispersed in organic vehicles for screen printing and stencil deposition in electronics manufacturing. Japanese electronics clusters specify rheological properties for high-speed printing lines.
- Granules:Agglomerated particles for improved flow characteristics in thermal spray and chemical process applications.
- Pellets:Compacted preforms for direct melting or hot pressing operations in specialty alloy production.
Powder form commands current volume. Paste form gains share fastest in electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration tracks regulatory arbitrage as atomization economics shift toward jurisdictions with lower compliance costs for emissions capture and workplace exposure controls.
China
Shandong and Jiangsu provinces host the largest concentration of water-atomization capacity serving battery thermal interface material demand from CATL and BYD supply chains. MEE emissions standards mandate closed-loop particulate capture systems retrofitting older facilities. Domestic producers in these coastal clusters prioritize baghouse upgrades over greenfield expansion to maintain operating permits.
Germany
Precision sintering operations in Bavaria and Baden-Württemberg anchor European offtake for automotive transmission components and motor windings. OEMs index long-term supply agreements to cathode conversion capacity rather than spot powder markets. REACH registration requirements filter unregistered imports, consolidating compliant suppliers around ECHA-documented substance properties.
United States
EPA air quality standards and OSHA workplace exposure limits shape production economics across atomization plants serving aerospace contractors. Kymera International leverages North American atomization footprint to supply certified spherical grades for heat exchanger fabricators. California and Texas clusters concentrate thermal management component demand from satellite and defense programs.
Japan
METI industrial policy supports captive mine-to-powder integration through major smelter groups. Electronics manufacturers in the Kanto region specify electrolytic grades with sub-ten-micron particle sizes for high-density interconnect applications. Domestic supply chains resist price volatility through indexed long-term contracts with South Korean and Taiwanese cathode suppliers.
India
PLI scheme incentives for non-ferrous metal processing attract atomization joint ventures to Maharashtra and Gujarat. Emerging friction material and electrical component demand outpaces domestic supply, creating import dependence on Chinese water-atomized grades. BIS quality standards for powder metallurgy inputs remain under development, delaying qualification timelines for local producers.
Copper Powder Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certified spherical grades for additive manufacturing feedstock. The vendor base stratifies around atomization method purity thresholds, with electrolytic refiners commanding margin premiums in electronics applications. Three archetypes dominate: integrated mining-smelting-powder conglomerates, independent atomization specialists, and captive aerospace-grade producers. Competitive moves center on multi-year offtake agreements with automotive electrification suppliers and technology licensing for closed-loop water systems.
Within the integrated conglomerate tier, Mitsui Mining & Smelting Co. and Sumitomo Metal Mining Co. Ltd exemplify captive mine-to-powder supply chain control. Among independent specialists, Pometon S.p.A. occupies a position serving European friction material producers, while Kymera International anchors North American aerospace-qualified supply. These named entities represent divergent geographic and application positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Kymera International |
| GGP Metalpowder AG |
| Mitsui Mining & Smelting Co. |
| Carl Schlenk AG |
| Pometon S.p.A. |
| Sumitomo Metal Mining Co. Ltd |
| Fukuda Metal Foil & Powder Co. |
| American Chemet Corporation |
| Shanghai CNPC Powder Material Co. |
| Others |
Supply Flow & Price Mechanics
Automotive electrification procurement teams in Germany and China are mandating eighteen-to-twenty-four-month qualification cycles for spherical copper powder grades, forcing atomization capacity to concentrate around certified producers and compressing margins for unqualified entrants. This buyer-driven specification tightening creates pricing power asymmetry between REACH-registered European suppliers and spot-market dependent Asian converters.
Pricing Analysis
Direct-to-OEM contracting discounts dominate high-volume automotive electrification supply, with three-to-five-year indexed agreements replacing spot purchases for battery thermal interface materials. Price differentiation centers on oxygen content certification and laser powder bed fusion qualification status, with aerospace-grade spherical feedstock commanding substantial premiums over standard water-atomized grades. Cost compression in electrolytic conversion is intensifying because LME cathode volatility passes directly through to powder economics. Tier-one motor manufacturers exhibit lowest price sensitivity due to qualification switching costs, while friction material producers in emerging markets remain most exposed to spot price swings.
Supply Chain Analysis
FAA and EASA certification pathways for additively manufactured flight hardware gate supply chain entry, limiting qualified spherical powder sources to atomization plants with eighteen-to-twenty-four-month qualification track records. Production concentrates in China, Germany, and the United States, with Shandong and Jiangsu provinces hosting the largest water-atomization clusters serving CATL and BYD demand. Raw material feedstock draws from Chilean concentrate, Chinese cathode conversion capacity, and Japanese captive smelter output. Single-source vulnerability runs through Andean concentrate supply during port disruptions. Distribution runs through direct long-term contracting with automotive OEMs and aerospace tier-one fabricators, bypassing traditional distributor layers for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where China's MEE emissions compliance costs for closed-loop water atomization systems run substantially below equivalent EPA and OSHA infrastructure investments in North America, creating margin shelter for Shandong and Jiangsu producers serving export demand.
For Market Incumbents: Deploy captive cathode-to-powder integration to offset LME price volatility exposure in electrolytic grades. Kymera International's North American atomization footprint demonstrates how regional certification proximity to aerospace contractors defends against Asian spherical grade entrants. Capacity addition in India under PLI scheme incentives offers geographic diversification against Chinese regulatory inspection suspensions. Investment in plasma atomization infrastructure secures laser powder bed fusion qualification pipelines before automotive electrification demand fully materializes. For New Entrants and Emerging Players: Capture solid-state battery thermal management specification windows before incumbent supply contracts lock in copper powder-based interface material standards. Indian domestic friction material and electrical component demand presents the most penetrable geography, with BIS quality standards still under development and import dependence on Chinese water-atomized grades creating local supply gaps. A joint venture structure with established Indian non-ferrous processors accelerates qualification timelines versus greenfield permitting. For Investors and Strategic Acquirers: Asymmetric upside sits with independent atomization specialists possessing dormant plasma atomization capacity awaiting aerospace qualification completion. Long-term viability across the next decade hinges on positioning ahead of laser powder bed fusion copper alloy standardization in automotive thermal management. The acquisition target archetype combines water-atomization scale with pending spherical grade certification. The signal to watch is FAA publication of additively manufactured copper heat exchanger airworthiness criteria, which would collapse eighteen-to-twenty-four-month qualification cycles for prepared suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Enables laser powder bed fusion feedstock qualification for aerospace heat exchanger fabricators in Germany and the United States. |
| Backward Integration into Cathode Conversion | Mitsui Mining & Smelting Co.'s captive mine-to-powder model demonstrates margin protection against LME copper volatility. |
| Closed-Loop Water System Retrofit | China's MEE emissions standards mandate particulate capture rates above ninety-nine percent, creating technology licensing revenue for equipment suppliers. |
| Long-Term Supply Agreement with Automotive OEM | German precision sintering operations anchor European offtake through indexed contracts resisting spot market price swings. |
| Joint Venture in India Under PLI Scheme | Maharashtra and Gujarat incentives attract atomization partnerships serving emerging friction material demand with domestic supply. |
Methodological Framework
Direct dialogue with atomization plant managers, automotive Tier 1 procurement leads, aerospace materials qualification engineers, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from EPA air quality enforcement records, ECHA REACH registration databases, Chinese MEE emissions inspection reports, and SEC filings of integrated mining-smelting-powder conglomerates. Bottom-up capacity assessments across Shandong, Jiangsu, Bavaria, and Texas atomization clusters triangulated against top-down cathode conversion demand models.
Segmented projections across atomization method, purity grade, and end-use application generated volume and value estimates across the projection horizon. The analytical framework modeled product type splits between spherical and irregular morphologies, application trajectories from sintering through additive manufacturing, and end-user electrification intensity across automotive, aerospace, and electronics verticals. CAGRs derived from qualification timeline compression, regulatory compliance cost curves, and cathode-to-powder conversion capacity expansion schedules. Industry-specific inputs included laser powder bed fusion machine builder qualification pipelines and solid-state battery thermal interface material specification development.
Chilean concentrate supply disruption, Chinese smelter inspection suspension, and automotive OEM qualification cancellation are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around eighteen-to-twenty-four-month aerospace certification cycles holding constant and REACH registration requirements filtering unregistered imports. A model refresh is warranted upon material change in FAA additively manufactured copper component airworthiness criteria publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Neodymium Market
Metals
Magnesium Metal Market
Metals
Metallic Rope Cords Market
Metals
Refined Nickel Market
Metals
Metal Forging Parts Market
Metals
Steel Drums and Ibcs Market
Metals
Aluminum Hot Rolling Mill Market
Metals
High Purity Aluminium Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Industrial Silver Market
Metals
Global Steel Market
Metals
Aluminum Ingots Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Silver Powder and Flakes Market
Metals
Saudi Arabia Aluminum Market