
 Global Chemical Protective Clothing Market | 2026-2036
Global Chemical Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Protective Clothing Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is consolidating the supplier landscape by raising the bar for supply chain transparency and worker safety documentation. DuPont leverages its material science leadership in aramids and fluoropolymers to maintain a premium position. Honeywell differentiates through integrated personal protective equipment (PPE) systems that include respiratory and chemical protection. These incumbents benefit from the heightened regulatory scrutiny, which creates barriers for smaller, less compliant competitors.
Chemical protective clothing comprises garments and suits engineered from specialized materials to shield wearers from hazardous chemical and biological agents. These materials often feature multi-layer constructions, such as laminated fabrics with a barrier film, to prevent permeation by liquids and gases. Level A and Level B protection, offering the highest resistance against vapors and splashes, command significant margin premiums in the market. Within end-user segments, chemical plants and emergency services constitute the largest volume consumers due to stringent occupational safety regulations.
Worker safety standards set by bodies like the US Occupational Safety and Health Administration (OSHA) and international ISO standards directly govern product requirements. These regulations define performance criteria for material strength, seam integrity, and chemical permeation resistance, shaping market access. The critical decision for manufacturers now involves balancing the development of reusable, sustainable garments against the established market for single-use disposable suits.
Market Dynamics
The central dynamic in the chemical protective clothing market is the tension between the established dominance of single-use disposable suits and the rising demand for more sustainable, reusable garments, a shift accelerated by stringent regulations like the EU's REACH.
Growth Catalysts
- Stringent Regulations:The European Union's REACH and CSRD directives mandate higher standards for worker safety and supply chain transparency, compelling the adoption of certified, high-performance protective clothing across industries.
- Hazardous Waste Sector:Expansion in hazardous waste handling and environmental remediation services, particularly in industrialized nations, directly stimulates volume demand for suits resistant to a wide spectrum of chemicals.
- Industrialization in Asia:Rapid industrial growth and tightening occupational safety enforcement in chemical manufacturing hubs across China and India are creating significant new demand for protective apparel.
Market Restraints
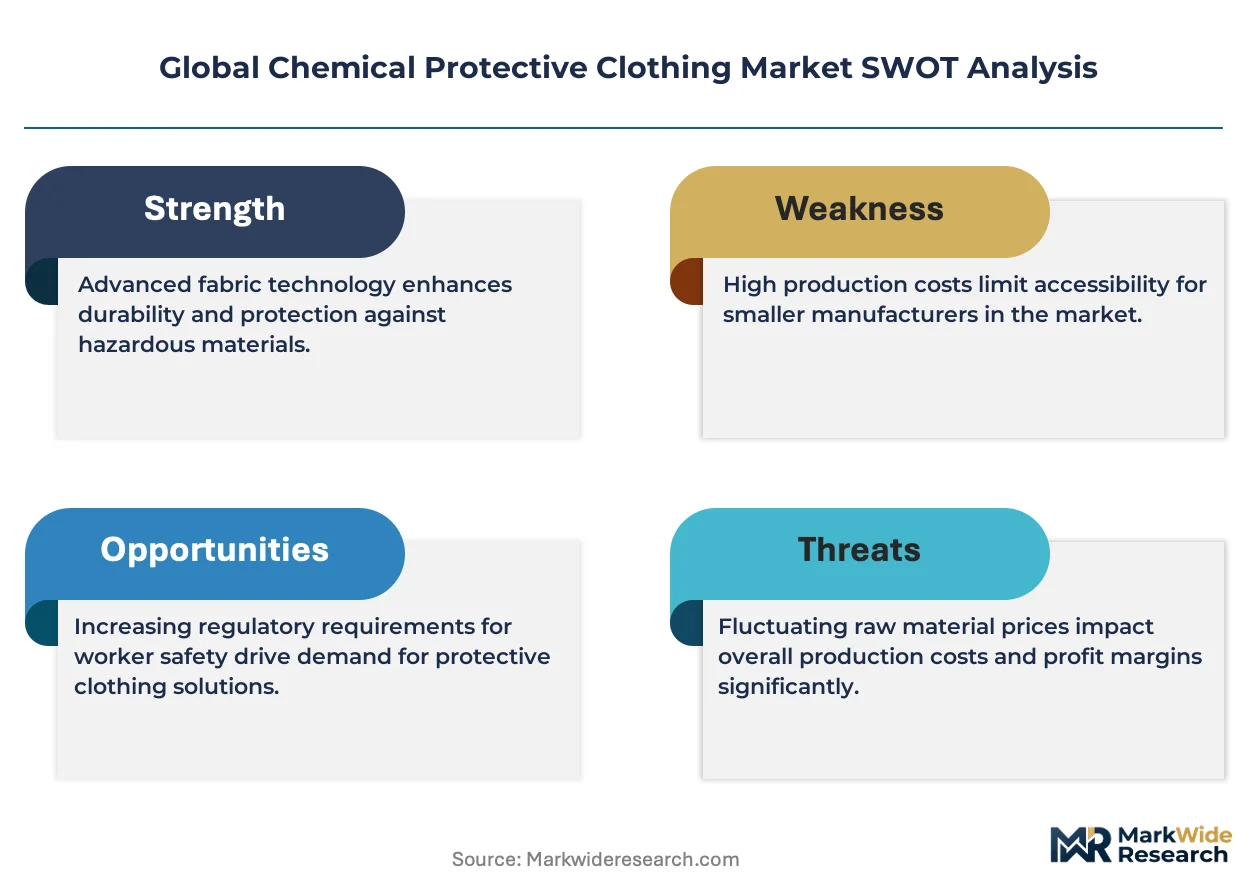
- High Material Costs:The premium cost of advanced barrier materials, including aramids and fluoropolymers, restricts the adoption of higher-level protection in cost-sensitive end-user segments and smaller enterprises.
- Performance Trade-offs:A persistent technical challenge is balancing high levels of chemical impermeability with wearer comfort, as less breathable materials can increase the risk of heat stress during strenuous tasks.
- Supply Chain Concentration:The production of critical barrier films and specialized nonwoven fabrics is concentrated among a few key material science companies, creating potential supply bottlenecks and price volatility.
Strategic Opportunities
- Smart Textiles Integration:Incorporating integrated sensors into garments to detect chemical permeation in real-time offers a significant value-add, moving from passive protection to active monitoring systems.
- Battery Manufacturing Sector:The growing battery production and recycling industry presents a new application segment, requiring protection against corrosive electrolytes and hazardous materials used in lithium-ion cells.
- Circular Economy Models:Developing closed-loop recycling programs for single-use suits or engineering more durable, multi-use garments with clear decontamination protocols addresses sustainability concerns and opens new service-based revenue streams.
Industry Challenges
- Certification Complexity:Navigating the lengthy and expensive process of obtaining product certifications from bodies like OSHA or under ISO standards for new materials creates a significant barrier to market entry and innovation.
- Contaminated Garment Disposal:The disposal of used, contaminated protective clothing, which itself is often classified as hazardous waste, poses a significant logistical and environmental challenge for end-users.
- End-User Training Gaps:Ensuring workers are properly trained in the correct donning, doffing, and decontamination procedures is a persistent operational burden that, if overlooked, can negate the effectiveness of the apparel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Protective Clothing Market |
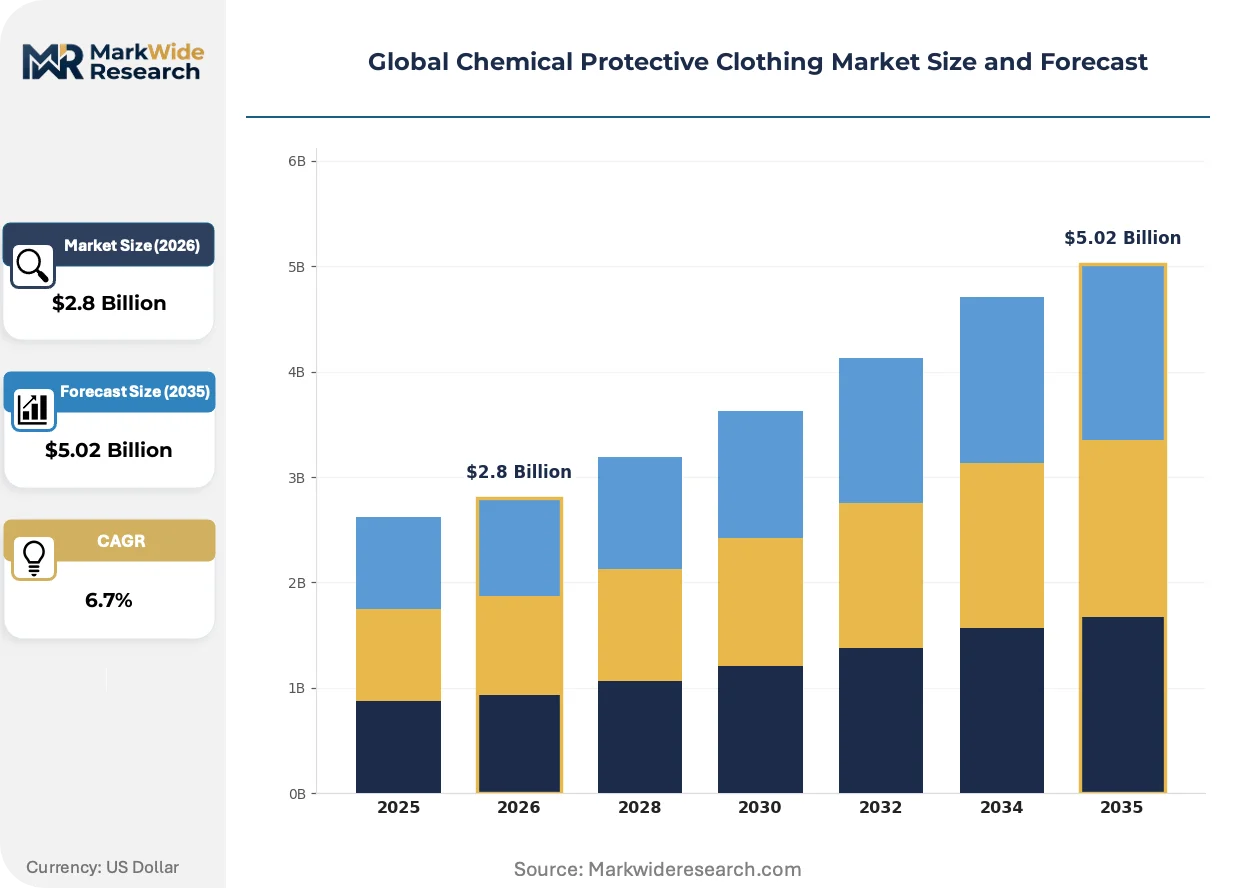
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Fabrics, Laminated Fabrics, Barrier Materials, Treated Textiles Protection Level: Level A, Level B, Level C, Level D Application: Firefighting, Hazardous Waste Handling, Laboratory Work, Agriculture End User: Chemical Plants, Construction Sites, Emergency Services, Mining Operations |
| Companies Covered | DuPont, 3M, Honeywell, Ansell, Lakeland Industries, Kimberly-Clark, MSA Safety, W. L. Gore & Associates, Sioen Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Protective Clothing Market Strategic Shifts & Innovations
Material science advancements are converging with a strong push for sustainability, altering product development priorities. This is reshaping competitive positioning as manufacturers work to balance protection, cost, and environmental impact in their product portfolios.
Bio-based polymers and recycled-content nonwovens are being developed to reduce the environmental footprint of protective suits. These materials are seeing initial adoption in less critical applications like general industrial cleaning and maintenance. This sustainable material science is expanding into more demanding segments as performance characteristics improve, challenging the dominance of traditional petroleum-based fabrics.
The US Environmental Protection Agency's (EPA) stricter enforcement of the Resource Conservation and Recovery Act (RCRA) for hazardous waste sites is elevating safety requirements. This directly increases the mandated level of protection for workers involved in site remediation and waste transportation. Consequently, demand for Level A and Level B suits is solidifying within the North American environmental services sector.
End-users are increasingly prioritizing total cost of ownership over initial purchase price, especially in high-volume consumption segments like chemical manufacturing. This shift favors reusable garments with documented lifecycles and lower per-use costs over single-use disposables. This purchasing behavior is most visible in Europe, where regulations like the CSRD encourage life-cycle analysis and waste reduction.
Global Chemical Protective Clothing Market Segmentation
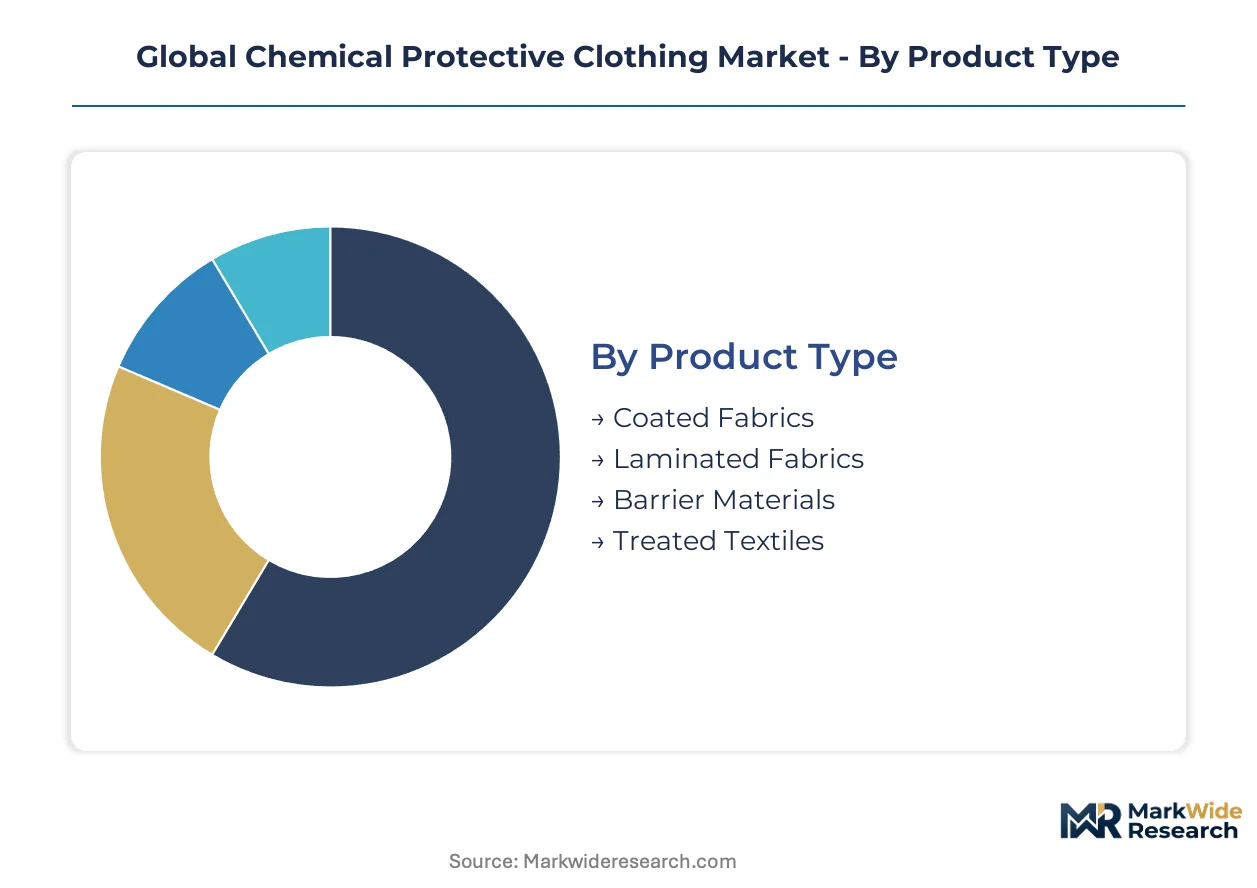
Segmentation analysis provides a granular view of the chemical protective clothing market, revealing how diverse material technologies, protection standards, and end-user demands shape product development and market dynamics. Understanding these distinct segments is essential for manufacturers to tailor offerings and for buyers to select appropriate safety solutions.
Product Type:
The product type segmentation highlights the varying upfront investment required for specialized material production, directly influencing manufacturing complexity and market entry.
- Laminated Fabrics:These materials typically feature multiple layers, often combining a substrate with a barrier film to prevent chemical permeation. Demand for laminated fabrics is concentrating in European chemical manufacturing, driven by strict CSRD requirements for documented worker safety.
- Barrier Materials:These specialized films and nonwovens offer high resistance against hazardous liquids and gases, forming the critical protective layer in advanced suits. The growing battery manufacturing sector in Asia requires robust barrier materials to protect against corrosive electrolytes.
- Coated Fabrics:These fabrics have a polymer layer applied to their surface, enhancing resistance to splashes and abrasions.
- Treated Textiles:Chemical treatments are applied to conventional textiles to impart flame retardancy or water repellency.
Laminated Fabrics absorb the bulk of installed capacity for high-performance suits; Barrier Materials are expanding most quickly due to new application demands.
Protection Level:
This segment delineates product offerings by their inherent protective capabilities, directly correlating with material sophistication and associated margin premiums.
- Level A:These fully encapsulated, gas-tight suits provide the highest level of protection against hazardous vapors, gases, mists, and particulate matter. Demand for Level A suits is solidifying within the North American environmental services sector, driven by stricter EPA enforcement.
- Level B:These non-gas-tight suits offer high protection against liquid splashes but require a separate breathing apparatus, often used in situations with less vapor hazard. Chemical plants and emergency services constitute the largest volume consumers of Level B protection due to stringent occupational safety regulations.
- Level C:This level provides protection against airborne contaminants and liquid splashes but offers less permeation resistance.
- Level D:This basic work uniform offers minimal protection, typically used for nuisance contamination or as a splash guard.
The highest protection levels, Level A and Level B, see sustained adoption in critical applications; Level C and D suits fulfill routine industrial safety requirements.
Application:
Application segmentation reveals distinct operational environments that shape specific performance requirements and procurement patterns for protective apparel.
- Hazardous Waste Handling:This application involves protecting workers from a wide spectrum of toxic chemicals during collection, transport, and disposal of dangerous materials. Expansion in hazardous waste handling services, particularly in industrialized nations, directly stimulates demand for chemical protective clothing.
- Laboratory Work:Scientists and technicians require protection from chemical splashes and fumes during research, development, and quality control processes. Stringent occupational safety regulations in pharmaceutical and chemical research facilities mandate certified protective garments.
- Firefighting:Firefighters require specialized gear that protects against heat, flames, and chemical exposure during emergency responses.
- Agriculture:Workers use protective clothing against pesticides, herbicides, and other agricultural chemicals during spraying and handling operations.
Applications like Hazardous Waste Handling are heavily influenced by environmental regulations; Laboratory Work demands consistent adherence to safety protocols.
End User:
End-user segmentation reflects the varying scales of consumption and the regulatory intensity governing worker safety across different industrial sectors.
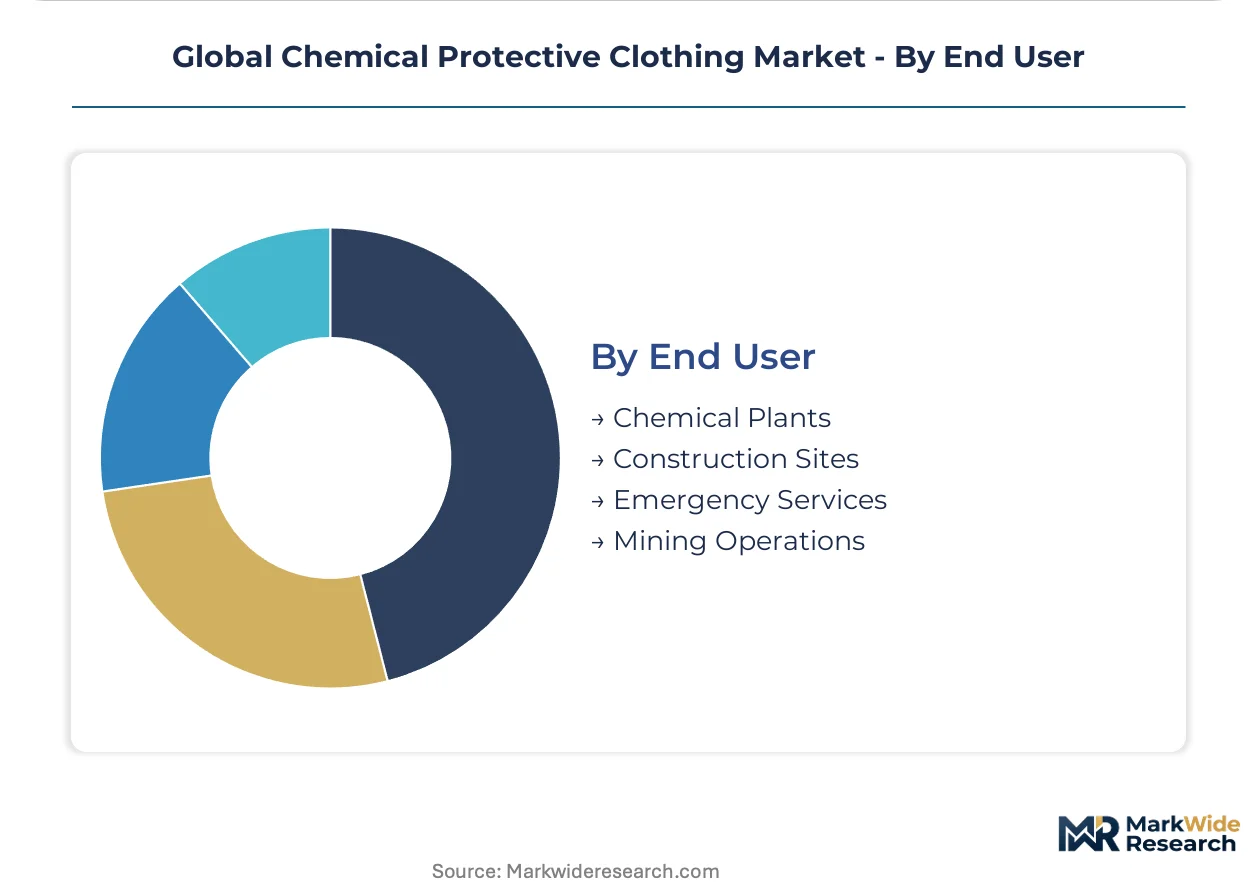
- Chemical Plants:These facilities require extensive protective clothing for workers handling corrosive, toxic, and reactive chemicals during production and maintenance. Chemical plants constitute the largest volume consumers due to stringent occupational safety regulations and continuous exposure risks.
- Emergency Services:First responders, including hazmat teams and paramedics, depend on protective suits for immediate intervention in chemical spills, biological incidents, and other hazardous scenarios. These services demand reliable, high-performance gear for critical, unpredictable environments.
- Construction Sites:Workers on construction sites may require chemical protective clothing for tasks involving hazardous materials like asbestos, lead, or certain solvents.
- Mining Operations:Miners need protection from dust, chemicals used in extraction, and potential exposure to hazardous substances present in geological formations.
End-users like Chemical Plants are increasingly prioritizing total cost of ownership and reusable solutions; Construction Sites and Mining Operations represent diverse protection needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones across Asia, such as those in China and India, are driving regional demand for chemical protective clothing through concentrated industrial development and export-oriented manufacturing. These zones attract significant foreign investment in chemical production, necessitating advanced worker safety measures. This industrial expansion creates specific regional demand patterns for high-performance protective garments.
United States
Demand for chemical protective clothing in the United States stems from robust industrial activity and stringent occupational safety enforcement. The US Occupational Safety and Health Administration (OSHA) mandates specific personal protective equipment for hazardous environments. Industrial clusters in Texas and Louisiana, known for petrochemical refining, consistently require high volumes of Level A and Level B suits.
Germany
Germany's chemical protective clothing market is shaped by its advanced manufacturing sector and the European Union's stringent environmental and worker safety regulations. The EU's REACH regulation directly impacts material selection and product compliance. Chemical manufacturing centers along the Rhine River, including Ludwigshafen and Leverkusen, are significant consumers of specialized protective apparel.
China
China's chemical protective clothing market is expanding due to rapid industrialization and tightening enforcement of occupational safety standards. The country's national GB standards are increasingly aligning with international performance criteria. Major chemical production bases in Jiangsu and Zhejiang provinces are driving substantial demand for both disposable and reusable protective suits.
India
India's market for chemical protective clothing is growing, propelled by its expanding pharmaceutical and chemical manufacturing sectors. The country's national industrial safety guidelines are becoming more rigorously applied across various industries. Chemical processing zones in Gujarat and Maharashtra represent significant consumption hubs for protective garments.
Japan
Japan's chemical protective clothing market emphasizes advanced material science and high-quality product performance, driven by a mature industrial base. Japanese Industrial Standards (JIS) define critical performance requirements for protective apparel. The highly specialized chemical industries in regions like Kansai and Kanto prioritize high-barrier protective solutions.
Global Chemical Protective Clothing Market Key Industry Players
North American and European producers anchor one tier, focusing on premium materials and integrated safety systems; Asian manufacturers hold another, emphasizing cost-effectiveness and scalability for diverse industrial applications. The market structure exhibits a tiered consolidation, where large incumbents leverage material science expertise and brand recognition. Strategic archetypes include diversified safety equipment manufacturers, specialized material science companies, and regional fabricators. Competitive moves often involve strategic partnerships for new material development and geographic expansion into emerging industrial hubs.
Within the diversified safety equipment tier, DuPont and Honeywell exemplify companies with broad product portfolios, spanning materials to integrated PPE solutions. DuPont leverages its extensive research in aramids and fluoropolymers, maintaining a premium position through specialized material offerings. Honeywell differentiates through comprehensive personal protective equipment systems, integrating respiratory and chemical protection for diverse industrial applications. Sioen Industries, a European-based textile innovator, occupies a position focused on technical textiles and coated fabrics, emphasizing durability and multi-use capabilities in its protective clothing lines.
| Leading Market Players |
|---|
| DuPont |
| 3M |
| Honeywell |
| Ansell |
| Lakeland Industries |
| Kimberly-Clark |
| MSA Safety |
| W. L. Gore & Associates |
| Sioen Industries |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists often shape the supply behavior and pricing discipline in the chemical protective clothing market. Their investment strategies directly influence material availability and cost structures.
Pricing Analysis
Premium for short lead times on specialized barrier materials reflects urgent demand in critical applications. The dominant pricing model is per-unit transactional for disposables and contract-based for reusable garments, often tied to certification levels like Level A and Level B. Price differentiation stems from material science advancements in aramids and fluoropolymers, alongside geographic delivery costs. Pricing softness emerges from the rising demand for reusable, sustainable garments in cost-sensitive segments. Smaller enterprises exhibit higher price sensitivity compared to chemical plants and emergency services.
Supply Chain Analysis
Specialized industrial distributors and direct sales channels manage the flow of chemical protective clothing to diverse end-users. Geographic supply concentration for finished goods centers on manufacturing hubs in China and India, while critical barrier films and specialized nonwoven fabrics originate from key material science companies in Europe and North America. The supply chain relies on advanced barrier materials like aramids and fluoropolymers. Single-source vulnerability from concentrated production of these critical inputs poses a significant structural risk. Large volume consumers often engage in direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently engaged in a vertical-integration race, as players pursue control over either advanced material science or closed-loop decontamination services for reusable garments.
For Market Incumbents:Deepen material science leadership in aramids and fluoropolymers to counter emerging bio-based alternatives and maintain premium positioning. Invest in advanced certification processes, such as ISO standards, to create barriers for smaller, less compliant competitors. Acquire specialized decontamination service providers to capture value from the shift towards reusable garments. Expand integrated PPE systems that combine respiratory and chemical protection, leveraging existing brand recognition.
For New Entrants and Emerging Players:Industrial safety consultants represent a strategic entry point for new players targeting niche applications. Focus on developing smart textiles with integrated chemical permeation sensors for active monitoring, creating significant value. Target the rapidly expanding battery manufacturing sector in Asia with specialized barrier materials for corrosive electrolytes. Partner with regional fabricators to offer cost-effective, certified solutions for routine industrial safety needs.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertically integrated mid-caps with strong material science IP in Europe, positioning them for long-term growth. The shift towards reusable garments and circular economy models ensures sustained demand over the next decade. Seek companies with established closed-loop recycling programs or advanced decontamination protocols. A critical signal to watch is the approval of new bio-based polymer certifications for Level A or B protection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding manufacturing capabilities in China supports regional industrial growth and tightening safety enforcement. |
| Green Manufacturing Transition | Developing bio-based polymers and recycled-content nonwovens addresses stringent EU sustainability regulations. |
| Long-term Supply Agreement | Securing access to advanced barrier films mitigates supply chain concentration risks from key material science companies. |
| Joint Venture | Partnering for smart textile development integrates real-time chemical permeation detection for active protection. |
| Acquisition of Specialist Firm | Acquiring decontamination service providers enables closed-loop recycling models for reusable chemical protective clothing. |
Research Approach
Document review covered industry association reports, regulatory filings from OSHA and REACH, and trade publications, complemented by interviews with chemical plant managers, procurement leads, R&D directors, and industrial safety officers. This approach combined primary insights with secondary validation through customs data and material science journals. Both bottom-up market sizing and top-down validation ensured data integrity.
Volume and value projections emerged from a robust analytical framework, modeling market dynamics across the analysis window. The framework segmented demand by product type, protection level, application, end-user, and regional regulatory intensity. Compound Annual Growth Rates were derived from historical trends and expert projections. Key forecast inputs included advanced material cost fluctuations and occupational safety regulation enforcement changes.
Caveats apply where global trade policies, material science breakthroughs, or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect assumptions documented during research phases. Practitioners should monitor these triggers for early signals of market reorientation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Lead Encapsulants Market
Chemicals & Materials
Construction Repair and Rehabilitation Chemicals Market
Chemicals & Materials
Global Stainless Steel Forgings Market
Chemicals & Materials
Silane Coupling Agents Market
Chemicals & Materials
Diphenylamine (DPA) Market
Chemicals & Materials
Global Quinine Sulphate Market
Chemicals & Materials
Single-Ply Membranes Market
Chemicals & Materials
Polyurethane Catalysts Market
Chemicals & Materials
Benzophenone (Oxybenzone) Market
Chemicals & Materials
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Chemicals & Materials
Methyl Undecylenate Market
Chemicals & Materials
South America Engineering Plastics Market
Chemicals & Materials
Oxalate Hydrogenation Catalyst Market
Chemicals & Materials
Global Butt Weld Fittings Market
Chemicals & Materials
Metal Injection Molding (MIM) Parts Market
Chemicals & Materials
In-Mold Coatings Market