
 Low-Carbon Concrete Shrinkage-Reduction Additives Market | 2026-2036
Low-Carbon Concrete Shrinkage-Reduction Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Carbon Concrete Shrinkage-Reduction Additives Market Insights
Modular additive dosing systems is decoupling shrinkage-reduction chemistry from traditional ready-mix plant configurations, letting buyers customize performance per pour rather than accepting standardized blends. Sika leverages its European formulation network to supply project-specific additive kits across multiple jurisdictions. Master Builders Solutions anchors its position through deep integration with precast concrete producers seeking consistent low-carbon performance. Mapei competes by specializing in silane-based technologies that reduce drying shrinkage without compromising compressive strength targets.
Low-carbon concrete shrinkage-reduction additives are chemical admixtures formulated with bio-based or recycled-content carriers that limit autogenous and drying shrinkage in cementitious matrices, typically dosed at 0.5 to 2.0 percent by weight of cementitious material to maintain dimensional stability during curing and service life. Their primary industrial purpose is enabling wider deployment of supplementary cementitious materials and alternative binders that inherently increase shrinkage risk while meeting structural performance specifications. Liquid additives currently occupy the largest volume position due to ease of metering and compatibility with automated batching systems, though nano-enhanced formulations represent the fastest-expanding category as producers pursue dual shrinkage and permeability control. Among formulation technologies, polycarboxylate ether chemistry dominates new product development pipelines because its molecular architecture permits precise tuning of water-reduction and shrinkage-mitigation ratios.
EMA's construction product regulations and the EU Green Deal's embodied carbon thresholds are tightening market access for additive suppliers without verified environmental product declarations. REACH compliance requirements for novel nano-materials are extending development timelines and testing burdens for innovative formulations. France's national low-carbon building strategy and Germany's federal sustainable construction guidelines are creating divergent certification pathways that stakeholders must navigate. Buyers and suppliers should monitor how emerging carbon accounting standards for concrete additives reshape procurement criteria and technical specifications.
Market Dynamics
The EU Green Deal's carbon border adjustments and green public procurement rules are compressing product certification timelines while fragmenting national compliance pathways across member states. This regulatory pressure is forcing additive suppliers to restructure formulation networks and documentation systems ahead of 2030 embodied carbon thresholds.
Growth Catalysts
- France's national low-carbon building strategy:Public works mandates now require verified environmental product declarations for concrete admixtures, creating pull-through demand for certified shrinkage-reduction formulations in government infrastructure contracts.
- Precast concrete producers:These manufacturers are integrating shrinkage-control chemistry directly into quality assurance protocols to maintain dimensional tolerances when substituting Portland cement with calcined clay and fly ash blends.
- Modular dosing systems:Automated batching equipment is decoupling additive delivery from fixed ready-mix plant configurations, letting project engineers customize performance per pour rather than accepting standardized blends.
Market Restraints
- REACH compliance timelines:Novel nano-material formulations face extended safety testing and registration burdens at ECHA, stretching development cycles and elevating R&D costs for innovative carriers.
- Bio-based carrier supply concentration:Agricultural feedstock availability for plant-derived polyols concentrates in specific climatic zones, exposing formulators to harvest volatility and price swings.
- Performance trade-offs with SCM-heavy mixes:Supplementary cementitious materials inherently elevate autogenous shrinkage risk, requiring higher additive loadings that compress margin structures for producers.
Strategic Opportunities
- Germany's federal sustainable construction guidelines:Divergent certification pathways from French standards create arbitrage potential for suppliers mastering multi-jurisdictional documentation.
- Silane-based nano-enhanced formulations:Convergence of permeability control and shrinkage mitigation in single-admixture systems opens premium positioning for dual-function chemistry.
- Project-specific additive kits:Direct-to-contractor distribution models bypass traditional ready-mix intermediary channels, capturing margin and capturing specification influence earlier in the value chain.
Industry Challenges
- Carbon accounting skill gaps:Formulation chemists lack training in lifecycle assessment methodologies required for environmental product declaration verification under EN 15804.
- Legacy batching system incompatibility:Automated dosing infrastructure at older ready-mix plants cannot meter nano-enhanced additives with sufficient precision, forcing capital reinvestment or exclusion from premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Carbon Concrete Shrinkage-Reduction Additives Market |
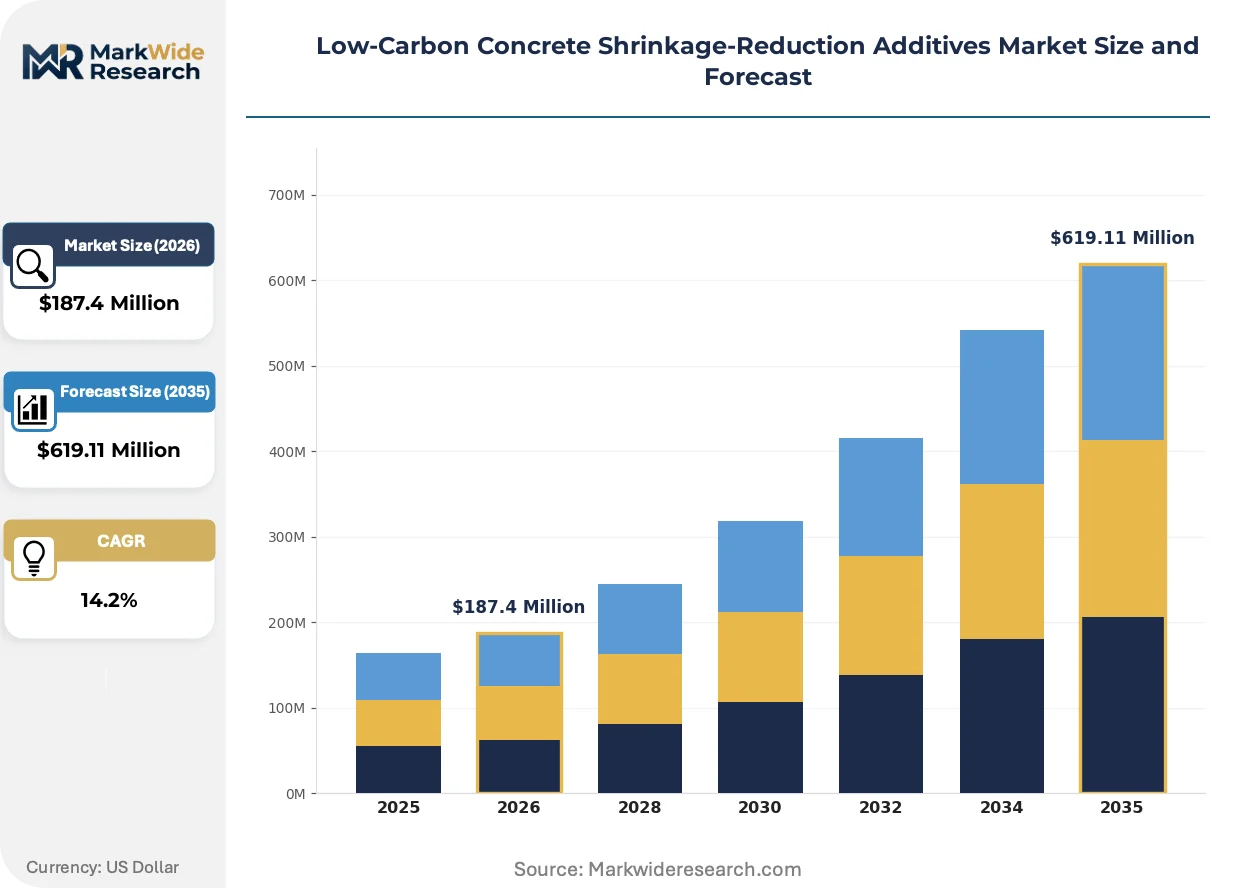
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Additives, Powder Additives, Polymer-Based Additives, Fiber-Reinforced Additives, Nano-Enhanced Additives Application: Precast Concrete, Ready-Mix Concrete, Shotcrete, Bridge Construction, Tunnel Lining End User Industry: Infrastructure Development, Commercial Construction, Residential Projects, Marine Engineering, Transportation Facilities Formulation Technology: Polycarboxylate Ether, Silane-Based, Silicone-Based, Acrylic-Based, Lignosulfonate-Based |
| Companies Covered | Sika, Saint-Gobain Construction Chemicals, Master Builders Solutions, Mapei, Fosroc, CEMEX, Holcim, GCP Applied Technologies, Euclid Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Carbon Concrete Shrinkage-Reduction Additives Market Trends and Innovations
Polycarboxylate ether molecular architecture is enabling precise tuning of water-reduction and shrinkage-mitigation ratios, compressing the performance gap between conventional and low-carbon concrete matrices. This chemistry shift is reshaping competitive positioning around formulation customization rather than commodity supply.
Modular additive dosing systems is modularizing shrinkage-reduction chemistry from traditional ready-mix plant configurations. Infrastructure contractors in the Netherlands are deploying these systems on major bridge and tunnel projects to customize performance per pour. This decoupling is compressing specification power toward end-users and away from centralized batching operations.
REACH compliance requirements for novel nano-materials are extending development timelines and elevating testing burdens at ECHA. Formulators must submit expanded toxicological dossiers before commercializing innovative carriers. German and French producers are responding by pre-qualifying substances through early engagement with the agency's substance evaluation processes.
Specification influence is migrating upstream from ready-mix suppliers to project engineers and public procurement officers. Direct engagement models are displacing traditional distribution through concrete producers in Dutch and Belgian infrastructure markets. This channel compression is most visible in Rotterdam's port expansion and Antwerp's flood defense programs, where additive selection now sits with design consultants rather than batch plant operators.
Low-Carbon Concrete Shrinkage-Reduction Additives Market Segmentation
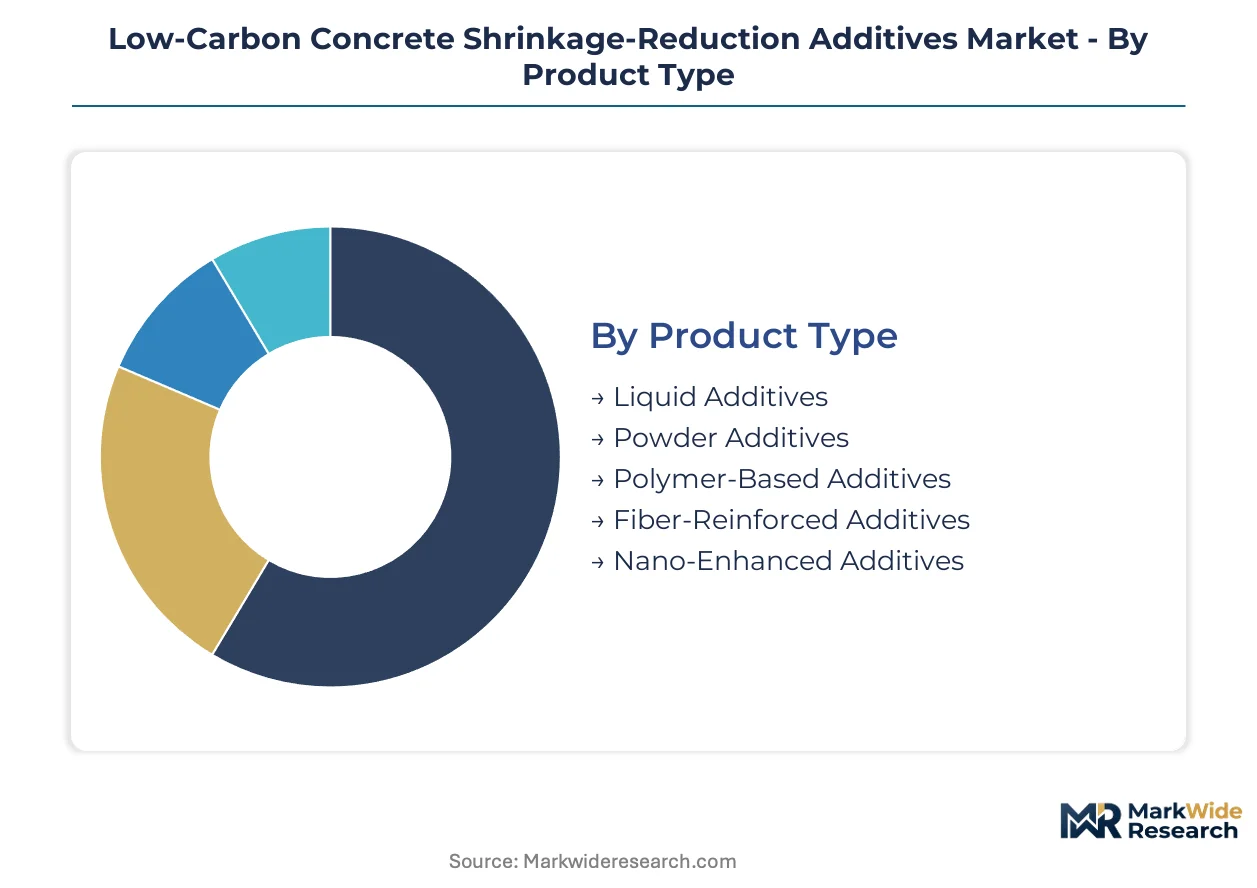
Segmentation in this market tracks how performance requirements, dosing infrastructure, and carbon accounting protocols reshape procurement patterns across additive categories. Buyers select formulations based on compatibility with automated batching systems, SCM substitution ratios, and certification documentation needs.
Product Type:
The customization-vs-standardization spectrum runs from commodity liquids with universal metering compatibility to nano-enhanced systems demanding precision infrastructure and technical support.
- Liquid Additives:Aqueous solutions with 20-40% active solids content dominate volume due to seamless integration with existing ready-mix plant automation. Demand concentrates in Dutch and German infrastructure projects where rapid dispensing and consistent dispersion prove critical for large-scale pours with tight dimensional tolerances.
- Nano-Enhanced Additives:Colloidal suspensions of silica or calcium carbonate nanoparticles deliver dual shrinkage and permeability control through pore refinement. French precast producers are adopting these formulations fastest, driven by public procurement mandates for extended service life in marine and tunnel environments.
- Powder Additives:Spray-dried polycarboxylate polymers suit remote construction sites lacking liquid storage infrastructure.
- Polymer-Based Additives:Synthetic latex emulsions reduce plastic shrinkage through film-forming mechanisms.
- Fiber-Reinforced Additives:Microsynthetic fibers blended with shrinkage-reducing chemistry address crack control in thin-section elements.
Leading the category by volume: Liquid Additives. Growing fastest: Nano-Enhanced Additives.
Application:
Cost tier segmentation separates capital-intensive precast manufacturing from project-specific ready-mix and specialized repair applications.
- Precast Concrete:Factory-controlled curing environments enable precise additive optimization for standardized elements like bridge girders and tunnel segments. German and Dutch producers integrate shrinkage control into quality assurance protocols to maintain dimensional stability when replacing Portland cement with calcined clay blends.
- Ready-Mix Concrete:Variable site conditions and pour-specific requirements drive demand for adjustable dosing systems. Belgian contractors on Antwerp flood defense programs specify additive loadings per structural element rather than accepting plant-standard blends.
- Shotcrete:Accelerated setting demands compatibility with alkali-free accelerators in tunnel lining applications.
- Bridge Construction:Segmental construction and post-tensioning require controlled shrinkage for alignment precision.
- Tunnel Lining:Waterproofing integration prioritizes permeability reduction alongside dimensional stability.
Highest value concentration: Precast Concrete. Steepest expansion trajectory: Ready-Mix Concrete with modular dosing.
End User Industry:
Customer type segmentation distinguishes public infrastructure with mandatory EPD requirements from private construction with performance-based procurement.
- Infrastructure Development:Government agencies in France, Germany, and the Netherlands mandate verified environmental product declarations for concrete admixtures in public works. Rotterdam's port expansion and Belgian rail tunnel programs specify shrinkage-reduction chemistry at the design consultant stage.
- Commercial Construction:Developer-driven projects prioritize speed-to-market and cost control over extended durability specifications.
- Residential Projects:Single-family and multi-family construction show limited penetration due to thin margin structures and specification fragmentation.
- Marine Engineering:Salt exposure and freeze-thaw cycling demand combined shrinkage and chloride resistance.
- Transportation Facilities:Airports and rail stations require joint-free slabs with tight flatness tolerances.
Dominant procurement volume: Infrastructure Development. Gaining share fastest: Marine Engineering with dual-function requirements.
Formulation Technology:
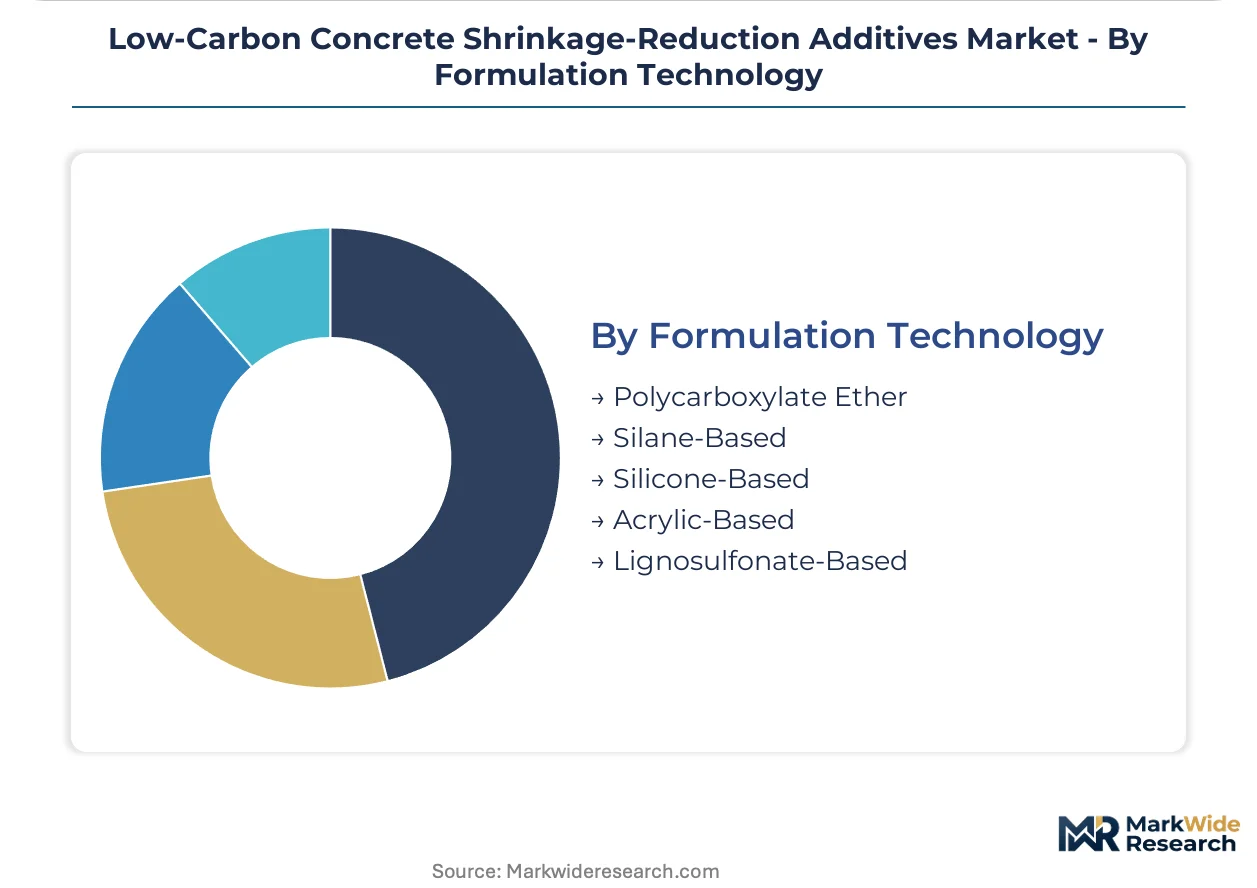
Maturity segmentation separates established polycarboxylate chemistry from emerging silane-based systems with premium positioning potential.
- Polycarboxylate Ether:Comb-shaped copolymers with adjustable side-chain density dominate new product pipelines. Molecular architecture permits independent tuning of water-reduction and shrinkage-mitigation ratios, enabling formulators to match SCM-heavy mix designs without strength compromise.
- Silane-Based:Organosilane compounds react with cement hydration products to reduce capillary porosity and drying shrinkage simultaneously. Mapei's specialization in this chemistry targets French and German producers seeking single-admixture solutions for premium structural applications.
- Silicone-Based:Polydimethylsiloxane emulsions provide hydrophobicity alongside moderate shrinkage reduction.
- Acrylic-Based:Polyacrylate esters offer cost-competitive shrinkage control with limited water reduction.
- Lignosulfonate-Based:Bio-derived polymers from pulp processing face supply volatility from agricultural feedstock concentration.
Technology leadership by deployment: Polycarboxylate Ether. Climbing the fastest: Silane-Based with dual-function convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity concentrates in northwestern Europe while consumption spreads across infrastructure corridors in Germany, France, and the Netherlands. The EU Green Deal's carbon border adjustments and divergent national building codes are fragmenting compliance pathways. Procurement power is shifting toward public agencies mandating verified environmental product declarations.
Germany
Federal sustainable construction guidelines under the BNB system require lifecycle-assessed concrete admixtures in federal buildings. The country's national building code now mandates lower-carbon concrete for public works exceeding specific volume thresholds. Industrial demand clusters in North Rhine-Westphalia's precast manufacturing belt around Düsseldorf and Cologne, where producers integrate shrinkage control into quality assurance protocols for calcined clay blends.
France
Public procurement rules under the national low-carbon building strategy require environmental product declarations for concrete admixtures in government contracts. ANSM construction product regulations align with EMA standards for chemical safety documentation. The Île-de-France region anchors demand through Grand Paris Express tunnel segments and Olympic infrastructure, where design consultants specify additive loadings at the engineering stage rather than batch plant level.
Netherlands
Rotterdam's port expansion and Antwerp flood defense programs are compressing specification influence toward design consultants. Dutch infrastructure agencies mandate embodied carbon thresholds that elevate demand for certified shrinkage-reduction chemistry. Modular dosing systems deployment concentrates in the Randstad corridor, letting contractors customize performance per pour on bridge and tunnel projects.
Belgium
Flemish regional building codes incorporate EU Green Deal carbon accounting standards for concrete specifications. The country's construction product regulator enforces CE marking with supplemental environmental declaration requirements. Antwerp's ring road tunnels and Brussels metro extensions represent high-volume applications where dual-function additives address both shrinkage control and permeability reduction.
United Kingdom
BSI construction standards are converging with EU environmental product declaration methodologies post-Brexit. The UK's building safety regulator is tightening documentation requirements for structural concrete admixtures. Infrastructure demand concentrates in London's Thames Tideway and HS2 rail programs, where project-specific additive kits bypass traditional ready-mix distribution channels.
Low-Carbon Concrete Shrinkage-Reduction Additives Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with formulation networks spanning multiple jurisdictions. European producers dominate through deep integration with precast and ready-mix channels. Three archetypes define positioning: multinational admixture specialists with modular dosing capabilities, cement majors backward-integrating into additive supply, and regional silane-technology specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms pre-position for 2030 embodied carbon thresholds.
Among diversified chemical specialists, Sika and Master Builders Solutions exemplify the multinational formulation network archetype. Mapei occupies a position within the technology-specialist tier through its silane-based chemistry focus. These three companies anchor the competitive landscape by representing distinct strategic approaches: Sika through project-specific additive kit distribution, Master Builders Solutions through precast producer integration, and Mapei through dual-function permeability-shrinkage convergence.
| Leading Market Players |
|---|
| Sika |
| Saint-Gobain Construction Chemicals |
| Master Builders Solutions |
| Mapei |
| Fosroc |
| CEMEX |
| Holcim |
| GCP Applied Technologies |
| Euclid Chemical |
| Others |
Pricing and Supply Chain Analysis
France's mandatory environmental product declarations for public works concrete admixtures are forcing formulation suppliers to absorb certification costs while maintaining competitive positioning, compressing margin structures and reshaping procurement toward verified supply partnerships.
Pricing Analysis
Margin tightening in nano-enhanced additive tiers reflects REACH compliance burdens and precision dosing infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates silane-based dual-function formulations from commodity polycarboxylate liquids and basic lignosulfonate carriers. Price differentiation hinges on EPD verification grade and SCM substitution compatibility. Ready-mix contractors show highest price sensitivity due to thin bid margins, while precast producers accept premium positioning for batch-to-batch consistency.
Supply Chain Analysis
Bio-based polyol feedstock supply rests on agricultural harvests concentrated in France, Germany, and the Netherlands, exposing formulators to seasonal volatility and price swings. Polycarboxylate ether precursors draw from German and Belgian petrochemical complexes, while nano-silica suspensions hinge on Italian and Spanish specialty chemical production. Single-source vulnerability concentrates around plant-derived carriers from specific climatic zones. Distribution runs through ready-mix plant networks and direct-to-contractor additive kit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarboxylate ether molecular architecture is displacing legacy lignosulfonate and acrylic chemistries, compressing the performance gap between conventional and SCM-heavy concrete matrices while elevating formulation customization requirements.
For Market Incumbents: Deepen backward integration into bio-based carrier supply to insulate margin structures from agricultural feedstock volatility. Expand EPD pre-certification capacity across German and French jurisdictions ahead of divergent national building code implementations. Anchor position through captive supply of nano-enhanced formulations for precast quality assurance protocols. For New Entrants and Emerging Players: Enter via modular dosing system partnerships with Dutch and Belgian infrastructure contractors, bypassing entrenched ready-mix distribution channels. Target marine engineering applications in Rotterdam and Antwerp where dual-function permeability-shrinkage specifications remain underpenetrated. Lead with silane-based chemistry differentiation against commodity polycarboxylate incumbents. For Investors and Strategic Acquirers: The window for entry favors regional silane-technology specialists with REACH pre-qualified substance dossiers and established French precast channel relationships. Long-term viability hinges on 2030 embodied carbon threshold positioning and multi-jurisdictional certification mastery. Watch for ECHA substance evaluation outcomes on novel nano-carriers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Qualification Investment | Early ECHA engagement compresses development timelines for nano-enhanced formulations ahead of commercialization windows. |
| Modular Dosing System Deployment | Direct contractor relationships in Rotterdam and Antwerp bypass traditional ready-mix intermediary control. |
| EPD Certification Network Expansion | Multi-jurisdictional documentation mastery captures arbitrage between French and German building code pathways. |
| Bio-Based Carrier Supply Integration | Upstream control over plant-derived polyols insulates margin structures from harvest volatility in northwestern Europe. |
| Silane Chemistry R&D Partnership | Dual-function permeability-shrinkage convergence opens premium positioning in marine and tunnel environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving formulation chemists, precast quality assurance directors, infrastructure procurement officers, and ready-mix plant managers. ECHA substance evaluation databases, EU Green Deal implementation reports, and national building code amendments provided regulatory trajectory validation. Bottom-up additive consumption estimates triangulated against top-down concrete production forecasts.
Granularity-level modeling tracked formulation technology, application segment, and end-user industry dimensions across the projection horizon, with regional splits calibrated to national low-carbon building strategy implementation timelines. CAGRs derived from SCM substitution elasticity curves and embodied carbon threshold compliance cost trajectories. Forecast inputs incorporated modular dosing system deployment rates and EPD verification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory acceleration or agricultural feedstock supply disruption scenarios. Assumptions reflect current EU Green Deal carbon border adjustment mechanisms and REACH implementation trajectories. A small set of named triggers—nano-material safety evaluation outcomes, bio-based carrier harvest volatility, and divergent national certification pathway convergence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Polyols and Sorbitols Products Market
Additives
Global Synthetic Tackifier Market
Additives
Feed Additives Market
Additives
Silicone Additives Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Lubricant Additives Market
Additives
Rheological Additives Market
Additives
North America Potassium Nitrate Market
Additives
North America Fuel Additives Market
Additives
Cetane Improver Additives Market
Additives
Inhibited Propylene Glycol Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Refinery Fuel Additives Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
China Sodium Reduction Ingredient Market
Additives
Packaging Coating Additives Market