
 Higher Olefins Market | 2026-2036
Higher Olefins Market Size, Share, and Industry Trends Forecast 2026-2036
Higher Olefins Market Outlook
The capital-intensity divergence between integrated petrochemical giants and standalone oligomer specialists is unwinding competitive stability in higher olefins. ExxonMobil Chemical leverages captive ethylene supply to anchor cost positions across Gulf Coast production corridors. Sasol competes through Fischer-Tropsch-derived 1-Octene streams that differentiate its product slate from conventional ethylene oligomerization. INEOS Oligomers specializes in European supply chains with dedicated logistics infrastructure serving polymerization customers.
Higher olefins comprise C6 to C10 linear alpha-olefins produced through ethylene oligomerization or Fischer-Tropsch synthesis, with carbon chain length determining compatibility with metallocene catalysts and final polymer properties. These molecules function primarily as comonomers in polyethylene production, where precise incorporation controls density, tensile strength, and optical clarity in finished resins. 1-Hexene dominates volume demand as the standard comonomer for linear low-density polyethylene, while 1-Octene commands premium positioning in high-performance flexible packaging grades. Detergent applications represent a mature outlet with stable offtake but thinner margin pools relative to polymerization. Plasticizers and lubricants occupy specialized niches where Idemitsu Kosan and regional blenders navigate formulation-specific requirements.
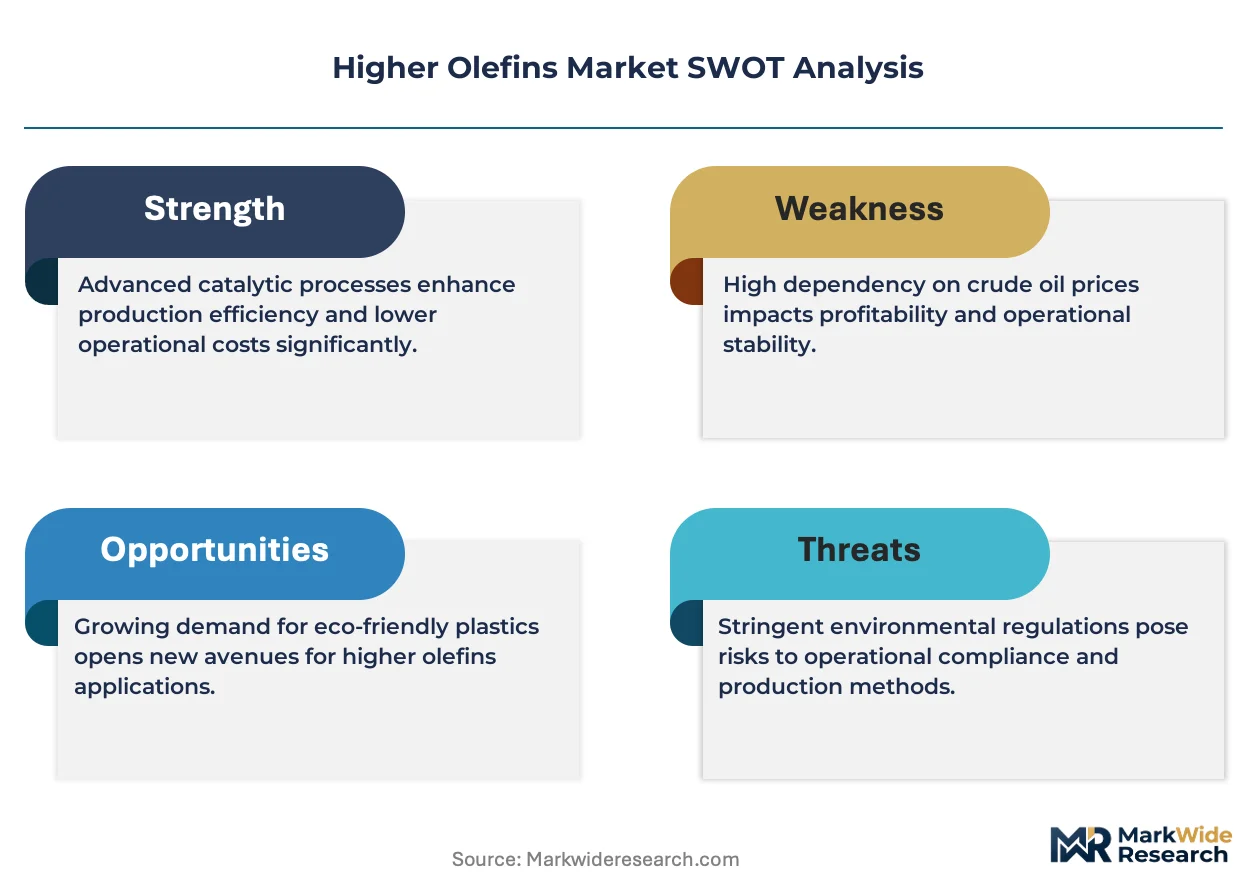
EPA oversight of chemical manufacturing emissions shapes US plant permitting and operating cost structures, while REACH registration obligations in Europe constrain market entry for non-compliant producers. China's MEE enforces increasingly stringent environmental assessments for new ethylene derivative capacity, affecting project timelines for domestic higher olefins expansion. Stakeholders must monitor feedstock cost volatility and regulatory divergence across jurisdictions when evaluating capital allocation for oligomerization assets.
Market Dynamics
Ethylene feedstock cost volatility and metallocene catalyst compatibility requirements are compressing margins for standalone oligomer producers while rewarding integrated operators with captive ethylene supply. The divergence between Gulf Coast ethane advantage and European naphtha-based economics is restructuring competitive positioning across C6-C10 product slates.
Growth Catalysts
- Flexible packaging demand:Converter specifications for high-clarity linear low-density polyethylene are expanding 1-Octene incorporation rates in premium film grades.
- EU Green Deal chemical standards:REACH registration obligations for sustainable feedstocks are accelerating bio-based alpha-olefin development pathways.
- Fischer-Tropsch synthesis:Gas-to-liquids technology is diversifying 1-Octene supply sources beyond conventional ethylene oligomerization routes.
Market Restraints
- Ethylene price volatility:Naphtha-cracker economics in Europe expose standalone oligomer units to margin compression during crude oil spikes.
- Supply concentration risk:Gulf Coast ethane advantage concentrates C6-C8 production capacity in Texas-Louisiana corridors, creating hurricane exposure.
- Metallocene catalyst limitations:Narrow comonomer incorporation windows restrict 1-Hexene substitution by longer-chain alpha-olefins in certain polymer grades.
Strategic Opportunities
- India polymerization capacity:Reliance Industries and domestic converters are expanding metallocene polyethylene lines, creating import substitution potential for C6-C8 supply.
- Biodegradable detergent formulations:C10-C14 linear alpha-olefin sulfonates are capturing share from petrochemical-derived surfactants under EU chemical sustainability mandates.
- Digital supply chain platforms:Blockchain-enabled feedstock traceability is emerging as a procurement differentiator for REACH-compliant polymerization customers.
Industry Challenges
- Process control engineering talent:Ethylene oligomerization unit optimization requires scarce expertise in selective catalyst systems and reactor temperature management.
- MEE environmental assessment timelines:China's Ministry of Ecology and Environment permitting delays are extending project commissioning schedules for new derivative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Higher Olefins Market |
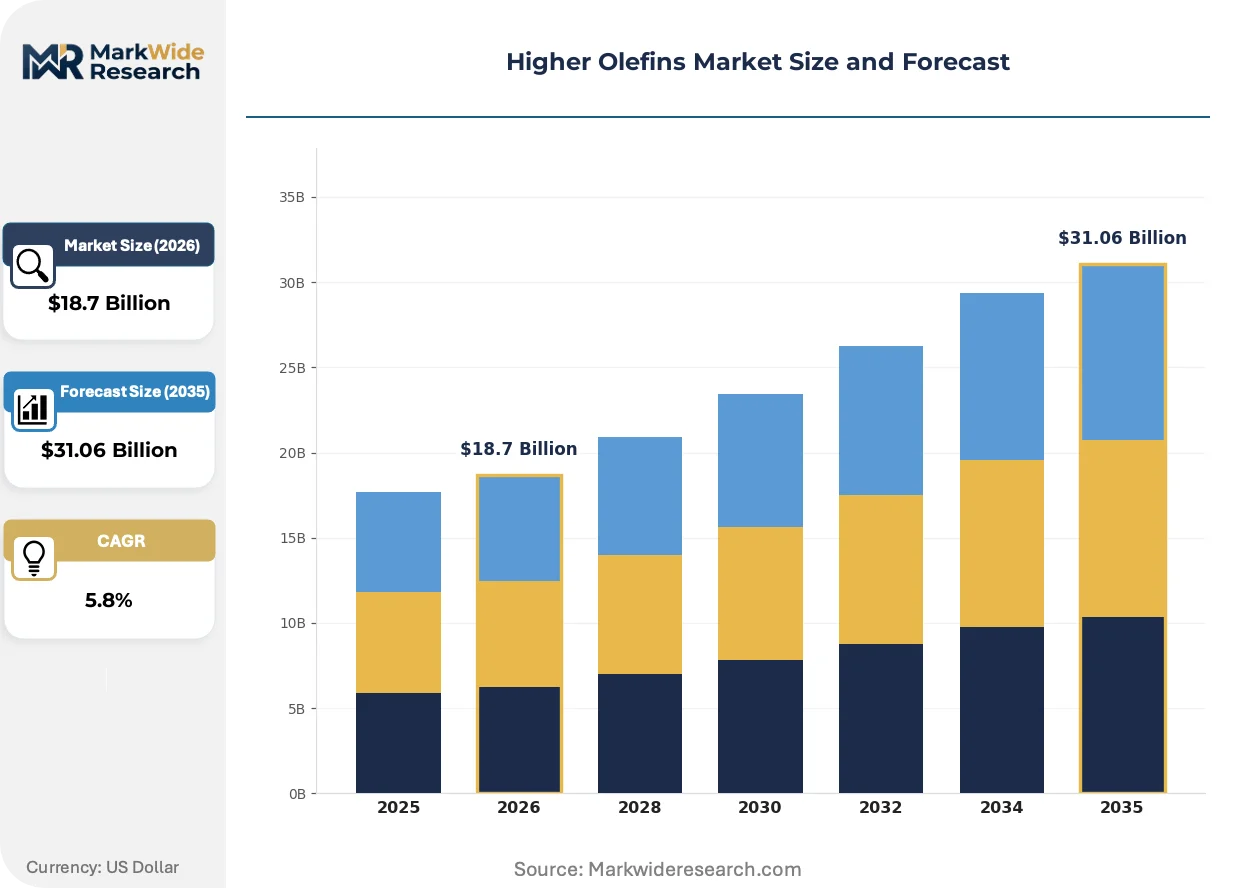
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1-Octene, 1-Hexene, 1-Butene, 1-Decene Application: Plasticizers, Detergents, Lubricants, Polymerization End User: Packaging, Automotive, Cosmetics, Construction Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Chevron Phillips Chemical Company, ExxonMobil Chemical, Royal Dutch Shell, INEOS Oligomers, Sasol, SABIC, Qatar Chemical Company, Idemitsu Kosan Co., Ltd., Honeywell International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Higher Olefins Market Strategic Shifts
Metallocene polyethylene formulation requirements are driving precision in comonomer selection, while regulatory pressure on chemical manufacturing emissions is forcing process technology upgrades across production corridors.
Advanced selective oligomerization catalysts are fragmenting the traditional trade-off between 1-Hexene yield and 1-Octene selectivity. Polymerization customers in flexible packaging are adopting these systems to tailor density-stiffness profiles without blending multiple comonomer streams. The technology is fragmenting established supply relationships by enabling smaller crackers to produce polymer-grade C6-C8 volumes previously requiring world-scale units.
EPA emissions standards for ethylene manufacturing are tightening volatile organic compound limits at US Gulf Coast facilities. The industrial consequence is accelerated capital deployment in closed-loop reactor designs and vapor recovery systems. Polymerization customers sourcing from Texas-Louisiana corridors are prioritizing suppliers with demonstrated compliance to avoid feedstock disruption risk.
Converter procurement teams are consolidating alpha-olefin purchasing through long-term offtake agreements rather than spot market exposure. This behavior compresses trading liquidity in C6-C8 markets while rewarding integrated producers with balance sheet capacity to underwrite decade-long contracts. The shift is most visible in China where downstream polyethylene capacity expansion has outpaced domestic oligomerization investment.
Higher Olefins Market Segmentation
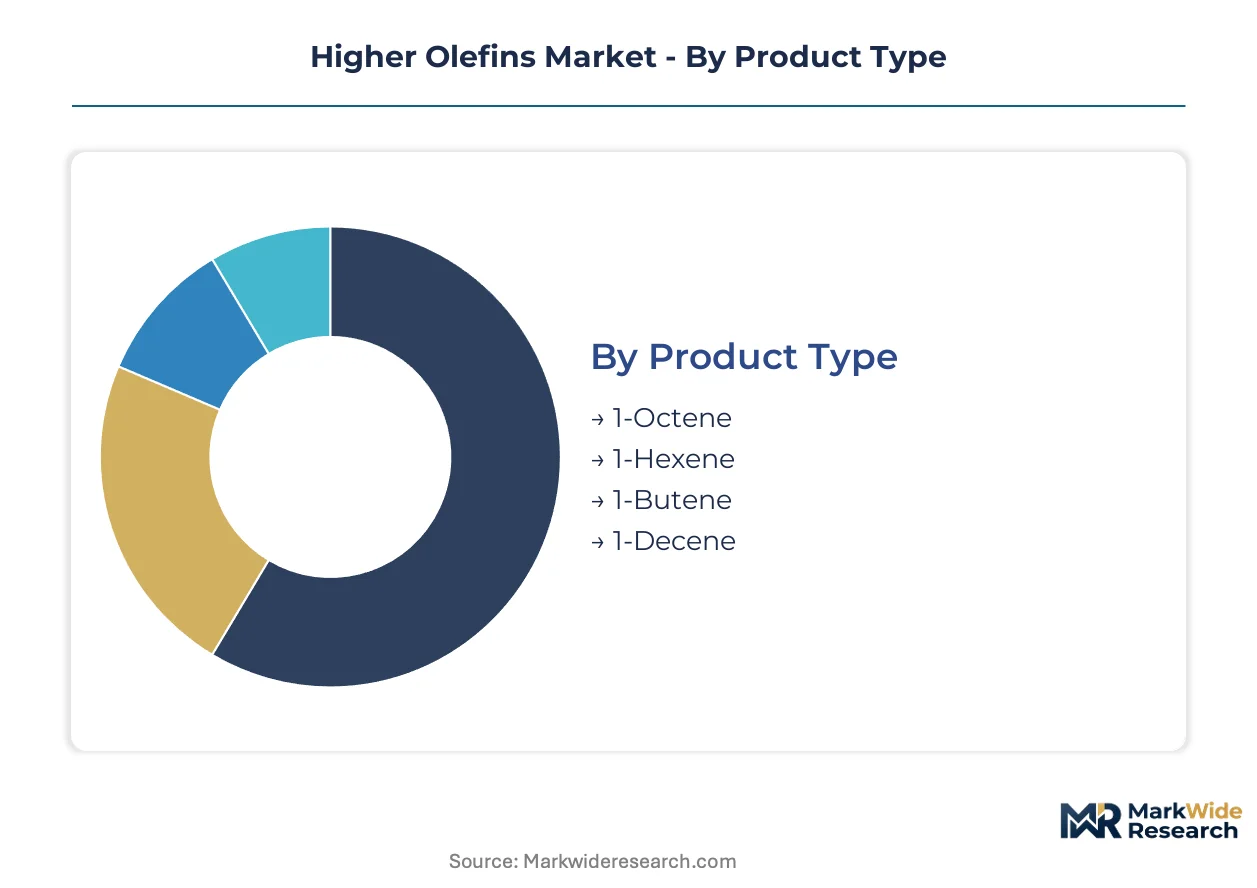
Segmentation in higher olefins reveals how carbon chain length and application specificity fragment pricing power across the value chain. Distinct technical requirements for metallocene catalyst compatibility and end-use performance create divergent margin pools that reward precise positioning.
Product Type:
Substitution pressure intensifies as polymerization customers optimize comonomer blends against density-stiffness specifications and catalyst system constraints.
- 1-Octene:The C8 linear alpha-olefin delivers superior tensile strength and optical clarity in flexible packaging grades. Premium film converters in China are expanding incorporation rates for high-clarity linear low-density polyethylene, though Fischer-Tropsch supply diversification is compressing historical premiums.
- 1-Hexene:Standard comonomer for linear low-density polyethylene production dominates volume flows through its compatibility with conventional metallocene systems. Gulf Coast ethane advantage anchors cost-competitive supply for polymerization customers seeking density control without optical-grade specifications.
- 1-Butene:Shorter-chain C4 molecule serves high-density polyethylene modification and polybutene-1 specialty resins where lower comonomer incorporation suffices.
- 1-Decene:C10 alpha-olefin supplies lubricant base stocks and detergent intermediates through selective oligomerization or wax cracking routes.
1-Hexene retains volume leadership; 1-Octene holds the steepest expansion curve.
Application:
Margin tiering separates polymerization demand from functional additive markets based on specification stringency and contract duration.
- Polymerization:Comonomer incorporation into polyethylene consumes the majority of C6-C8 volumes, with metallocene catalyst compatibility requirements dictating purity specifications. Flexible packaging converters in Asia-Pacific drive specification escalation for high-performance film grades.
- Detergents:Linear alpha-olefin sulfonate production for biodegradable surfactant formulations is gaining share under EU chemical sustainability mandates, particularly for C10-C14 chain lengths.
- Plasticizers:Polymer flexibility modification for wire insulation and flooring compounds represents stable offtake with thinner margin pools relative to polymerization.
- Lubricants:Synthetic base stock formulation for automotive and industrial applications requires specialized C10+ fractions with narrow viscosity index specifications.
Polymerization commands the premium tier; detergent applications are climbing fastest on regulatory tailwinds.
End User:
Customer concentration patterns concentrate procurement leverage among large-scale polyethylene producers while fragmenting demand across specialty compounders.
- Packaging:Flexible film and rigid container manufacturers dominate comonomer consumption, with converter consolidation strengthening long-term offtake negotiation positions.
- Automotive:Under-the-hood plastics and fuel system components require specialized polyethylene grades with precise thermal stability profiles.
- Cosmetics:Personal care formulation houses source C12-C14 fractions for emollient and surfactant applications with stringent purity certifications.
- Construction:Pipe and geomembrane producers specify higher-density polyethylene modifications with controlled comonomer distribution for durability.
Packaging anchors procurement volumes; automotive specifications are tightening fastest on performance requirements.
Distribution Channel:
Supply chain configuration reflects the tension between just-in-time polymerization plant feedstock security and working capital efficiency for smaller volume customers.
- Direct Sales:Integrated producers and large standalone oligomer units serve major polyethylene manufacturers through dedicated pipeline and railcar arrangements with decade-long contract structures.
- Distributors:Regional chemical distributors stock C6-C10 volumes for mid-tier compounders and specialty formulators requiring smaller batch flexibility.
- E-commerce:Digital procurement platforms are emerging for spot market transparency and REACH-compliant feedstock traceability documentation.
- Retail:Packaged laboratory and pilot-scale quantities reach research institutions and specialty blenders through industrial chemical retailers.
Direct sales retain volume concentration; e-commerce channels are expanding most quickly on transparency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China absorb volumes with limited price elasticity as downstream polymer capacity expansion outpaces domestic supply, while European converters face margin compression from naphtha-based feedstock economics that amplify cost sensitivity.
United States
Shale-derived ethane advantage anchors cost-competitive C6-C8 production for polymerization customers along Gulf Coast corridors. EPA emissions standards for volatile organic compounds are tightening at Texas-Louisiana facilities, accelerating capital deployment in closed-loop reactor designs. Houston-Beaumont-Port Arthur industrial clusters concentrate world-scale oligomerization capacity serving flexible packaging converters.
China
Downstream polyethylene capacity expansion in Zhejiang and Jiangsu provinces absorbs significant 1-Hexene and 1-Octene imports despite domestic production growth. MEE environmental assessment timelines are extending project commissioning schedules for new ethylene derivative investments. Ningbo-Zhoushan petrochemical zones are emerging as integrated production hubs with dedicated logistics infrastructure.
Germany
REACH registration obligations constrain market entry for non-compliant producers while driving bio-based alpha-olefin development pathways. EU Green Deal chemical standards are tightening specifications for sustainable feedstocks in polymerization applications. Ludwigshafen-Cologne chemical corridor maintains specialized supply chains for metallocene polyethylene producers.
Saudi Arabia
Gas-to-liquids technology diversification is expanding 1-Octene supply sources beyond conventional ethylene oligomerization routes for regional polymerization demand. SABIC and downstream partners are integrating Fischer-Tropsch-derived streams into specialty chemical value chains. Jubail Industrial City anchors production clusters with dedicated export infrastructure serving Asian markets.
Japan
Specialty lubricant and detergent formulations sustain demand for C10+ fractions with narrow viscosity index specifications. METI industrial standards are guiding formulation-specific requirements for synthetic base stocks and biodegradable surfactants. Chiba-Kashima petrochemical complexes maintain precision production capabilities for high-purity alpha-olefin grades.
Higher Olefins Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the value chain. Integrated petrochemical giants with captive ethylene supply command margin resilience against feedstock volatility, while standalone oligomer specialists compete through product slate differentiation and regional logistics advantages. Three archetypes dominate: Gulf Coast ethane-advantaged integrators, Fischer-Tropsch technology specialists, and European logistics-focused regional suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure long-term offtake agreements with polymerization customers.
Within the integrated petrochemical tier, ExxonMobil Chemical and Chevron Phillips Chemical Company represent archetypes of Gulf Coast ethane advantage, while Sasol occupies a distinctive position through Fischer-Tropsch-derived product streams. INEOS Oligomers exemplifies the European regional specialist model with dedicated infrastructure serving polymerization customers. These three companies anchor competitive positioning across technology, feedstock, and geography vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company |
| ExxonMobil Chemical |
| Royal Dutch Shell |
| INEOS Oligomers |
| Sasol |
| SABIC |
| Qatar Chemical Company |
| Idemitsu Kosan Co., Ltd. |
| Honeywell International Inc |
| Others |
Value Chain & Pricing Dynamics
REACH registration obligations gate both supply qualification and price differentiation simultaneously, as polymerization customers demand documented compliance for premium contract tiers while non-registered producers face exclusion from EU value chains entirely. This regulatory filter stratifies pricing power between integrated operators with dedicated compliance infrastructure and marginal suppliers competing on spot-market transparency.
Pricing Analysis
Long-term offtake agreements with embedded service provisions drive lifetime value beyond base chemical delivery, as polymerization customers prioritize feedstock security over spot-market savings. Contract structures stratify across premium polymer-grade specifications, standard metallocene-compatible volumes, and economy detergent-grade outlets based on purity certification and catalyst compatibility testing. Pricing pressure stems from Fischer-Tropsch supply diversification compressing historical 1-Octene premiums. Standalone oligomer producers exhibit highest price sensitivity due to ethylene feedstock cost volatility, while integrated operators with captive ethylene supply demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory cycles for C6-C8 alpha-olefins run tight against polymerization plant feedstock security requirements, with Gulf Coast ethane-advantaged producers holding 3-5 day pipeline delivery windows versus 4-6 week maritime lead times for Asian imports. Supply concentrates in the United States, China, and Saudi Arabia as primary production corridors. Raw material dependencies center on ethylene monomer from steam crackers, natural gas liquids fractionation, and Fischer-Tropsch synthesis streams. Single-source vulnerability emerges from hurricane exposure across Texas-Louisiana production clusters. Distribution runs through dedicated pipeline and railcar arrangements for major polyethylene manufacturers, with regional distributors serving mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical support for metallocene catalyst optimization and REACH compliance documentation expands faster than commodity chemical sales. Recurring revenue layers including catalyst compatibility testing and regulatory file maintenance now anchor customer retention.
For Market Incumbents: Secure captive ethylene supply through backward integration or long-term feedstock agreements to defend margin position against naphtha-based standalone competitors. Add selective oligomerization capacity in Ningbo-Zhoushan corridors to capture China polymerization demand growth. Invest in closed-loop reactor engineering talent to maintain EPA compliance leadership as emissions standards tighten.
For New Entrants and Emerging Players: Differentiate on bio-based alpha-olefin pathways certified under EU Green Deal chemical standards, targeting detergent and surfactant formulators with C10-C14 sustainable fractions. Penetrate India's import substitution gap as Reliance Industries expands metallocene polyethylene lines. Pursue blockchain-enabled feedstock traceability platforms as procurement differentiator for REACH-compliant customers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified petrochemical parents seeking to monetize non-core oligomerization assets with stranded logistics infrastructure. Five-to-ten year viability hinges on feedstock cost position and regulatory compliance capability rather than scale alone. Monitor MEE environmental assessment timeline extensions as inflection indicator for China capacity addition delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive feedstock from Gulf Coast ethane crackers anchors cost resilience against naphtha volatility. |
| Green Manufacturing Transition | Bio-based alpha-olefin pathways unlock premium positioning under EU Green Deal chemical standards. |
| Long-term Supply Agreement | Decade-long offtake contracts with Chinese polymerization customers compress trading liquidity rewards. |
| Capacity Expansion | Selective oligomerization unit additions in Ningbo-Zhoushan corridors capture downstream polyethylene growth. |
| Joint Venture | Fischer-Tropsch technology partnerships with SABIC diversify 1-Octene sources beyond conventional routes. |
Study Parameters
Initial hypotheses were tested against primary input from oligomerization plant managers, polyethylene procurement leads at major converters, Fischer-Tropsch technology specialists, and REACH regulatory consultants, then refined against secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up capacity modeling triangulated against top-down demand aggregation across polymerization, detergent, and lubricant applications.
Variance decomposition separated volume drivers from price trajectory components across the projection horizon. Segmentation dimensions modeled include carbon chain length tier, end-use application, metallocene catalyst compatibility grade, and regional production hub classification. CAGRs derived from historical trajectory analysis adjusted for capacity addition schedules and regulatory timeline risks. Forecast inputs incorporated ethylene feedstock cost scenario modeling and MEE permitting delay probability distributions.
The analysis sits within stated boundaries; outcomes outside sustained shale gas economics or accelerated EU chemical sustainability mandates would require recalibration. Forecasts reflect documented assumptions about catalyst technology diffusion and cracker feedstock slates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Squalane Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Esters Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Global Wax Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Aminoethylethanolamine Market