
 Polyphenylene Sulfide Market | 2026-2036
Polyphenylene Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylene Sulfide Market Analysis
The EU F-Gas Regulation is hardening fluoropolymer substitution mandates across European HVAC and automotive cooling systems, pushing OEMs toward high-heat thermoplastics. Solvay leverages its integrated sulfur chemistry chain to sustain cost-competitive virgin and recycled PPS resin output. DIC Corporation anchors Japanese supply security through captive para-dichlorobenzene production and compounding expertise. Toray Industries differentiates via carbon fiber-reinforced PPS hybrid materials targeting aerospace bracket applications.
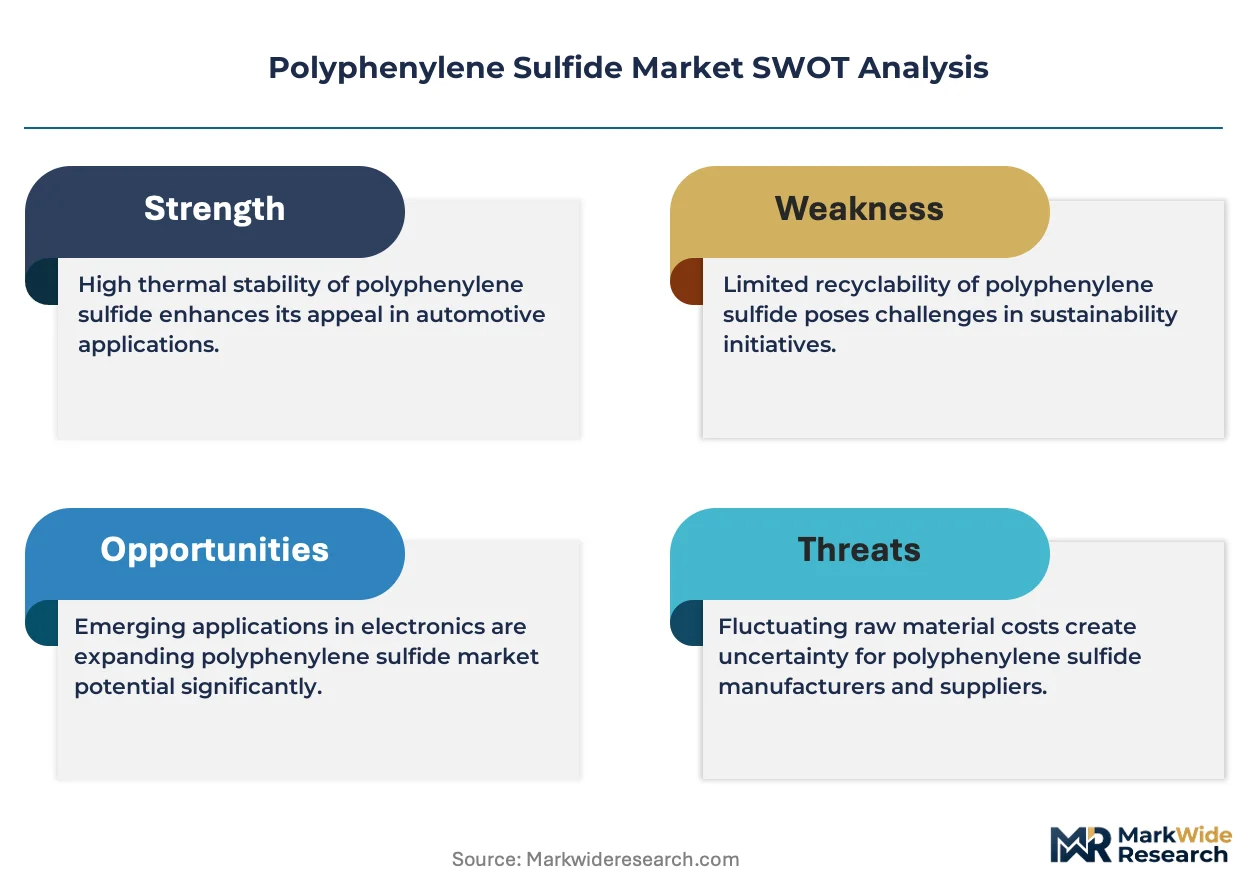
Polyphenylene sulfide is a semi-crystalline aromatic polymer with a melting point near 285°C, synthesized through nucleophilic substitution of para-dichlorobenzene with sodium sulfide in polar aprotic solvents, valued for dimensional stability in aggressive chemical and thermal environments. Reinforced grades dominate volume given their stiffness-to-weight ratios in automotive pump housings and electronic connectors, while compound formulations tailored for EMI shielding capture expanding margin pools in 5G infrastructure. Blended PPS alloys with polyetherimide or liquid crystal polymer occupy niche high-frequency electronic substrates where dielectric performance commands premium positioning.
The EPA administers TSCA Section 5 premanufacture notifications for new PPS chemistries entering US commerce, while REACH obliges ECHA-registered suppliers to document substance volumes and hazard profiles across European downstream formulations. China's MEE enforces GB standards for volatile organic compound emissions at polymer synthesis facilities, shaping capital allocation toward closed-loop process upgrades. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in major jurisdictions, as these directly determine PPS substitution economics in sealing and coating end uses.
Market Dynamics
Automotive electrification is restructuring PPS resin demand around thermal management modules and high-voltage connector systems, forcing compounders to recalibrate flame-retardant formulations and melt-flow specifications for battery platform integration.
Growth Catalysts
- EU F-Gas Regulation:Fluoropolymer substitution mandates in HVAC and automotive cooling systems are redirecting OEM specifications toward high-heat thermoplastics with comparable chemical resistance profiles.
- 5G infrastructure deployment:EMI shielding-grade PPS compounds are capturing specification wins in base station housings and fiber-optic connector assemblies across East Asian manufacturing clusters.
- China:Domestic EV battery housing production is accelerating modified PPS consumption as local compounders expand capacity for power electronics encapsulation.
Market Restraints
- Para-dichlorobenzene feedstock concentration:Asian suppliers dominate upstream chlorobenzene chemistry, exposing European and North American compounders to freight-adjusted cost volatility and supply timing risk.
- REACH compliance burden:ECHA-registered suppliers face escalating documentation requirements for substance volumes and hazard profiles across downstream formulations, compressing margin on specialty grades.
- Polyetheretherketone substitution:PEEK resins are displacing PPS in select aerospace bracket applications where higher continuous service temperatures justify premium material positioning.
Strategic Opportunities
- India:BIS certification pathways for engineering thermoplastics remain underdeveloped, creating first-mover positioning for compounders establishing localized compounding and technical service infrastructure.
- Closed-loop recycling:Pyrolysis-based PPS reclamation from automotive shredder residue is converging with OEM circularity commitments under EU Green Deal sourcing protocols.
- Carbon fiber hybridization:Aerospace tier suppliers are qualifying continuous fiber-reinforced PPS tapes for primary structural brackets, opening margin pools beyond conventional injection molding grades.
Industry Challenges
- Specialized polymer processing expertise:Mold flow simulation for crystallization kinetics in thin-wall connector geometries requires scarce technical talent, constraining tier-two compounders from automotive qualification programs.
- UL 94 V-0 flame retardancy certification:Extended testing timelines for halogen-free PPS formulations are delaying new grade introductions by 12-18 months versus legacy brominated alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylene Sulfide Market |
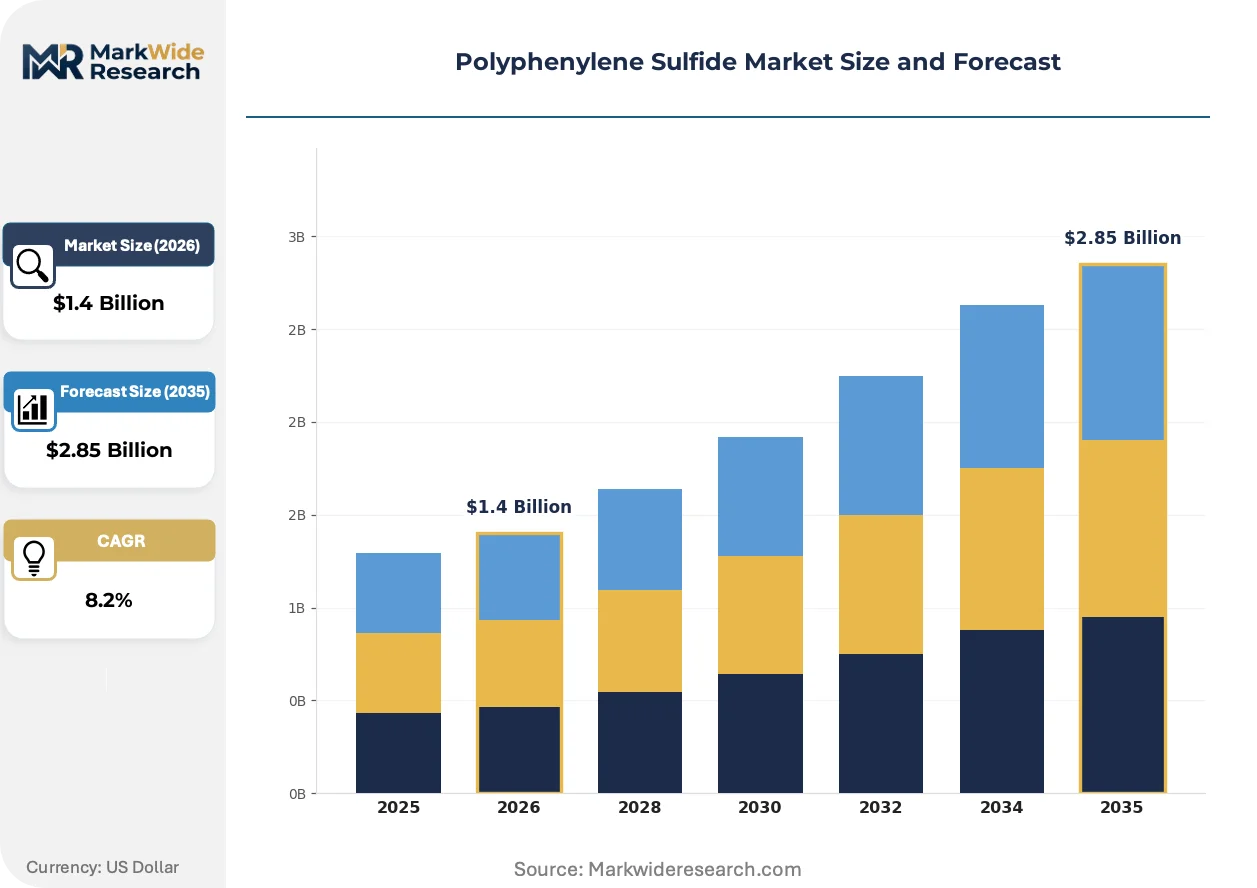
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Reinforced, Compound, Blended End User: Automotive, Electronics, Aerospace, Industrial Application: Insulation, Filtration, Coatings, Sealing Form: Granules, Sheets, Films, Powders |
| Companies Covered | Solvay, DIC Corporation, Lion Idemitsu Composites, Polyplastics Co. Ltd., Toray Industries, Tosoh Corporation, Celanese Corporation, Kureha Corporation, TEIJIN Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylene Sulfide Market Emerging Trajectories
Material science convergence is redefining competitive positioning across the PPS value chain, with hybridization strategies and regulatory chemistry shifts commanding disproportionate R&D allocation.
Long-fiber thermoplastic PPS composites are overtaking short-fiber injection grades in automotive front-end modules, with German tier suppliers accelerating adoption for crash-resistant battery tray structures; this displacement is compressing commodity compounder margins while rewarding upstream fiber integration capabilities.
REACH authorization requirements for persistent organic pollutants are tightening impurity thresholds in sulfur-based polymerization catalysts, forcing European resin producers to retrofit purification trains; automotive under-the-hood specifications are tightening correspondingly, with OEMs demanding batch-level contaminant documentation.
Direct compounder-to-OEM technical partnerships are displacing traditional distributor channels in North American EV supply chains, with battery platform engineers embedding material scientists at resin specification stages; this pattern is most pronounced in Michigan and California manufacturing corridors where platform consolidation concentrates procurement decision-making.
Polyphenylene Sulfide Market Segmentation
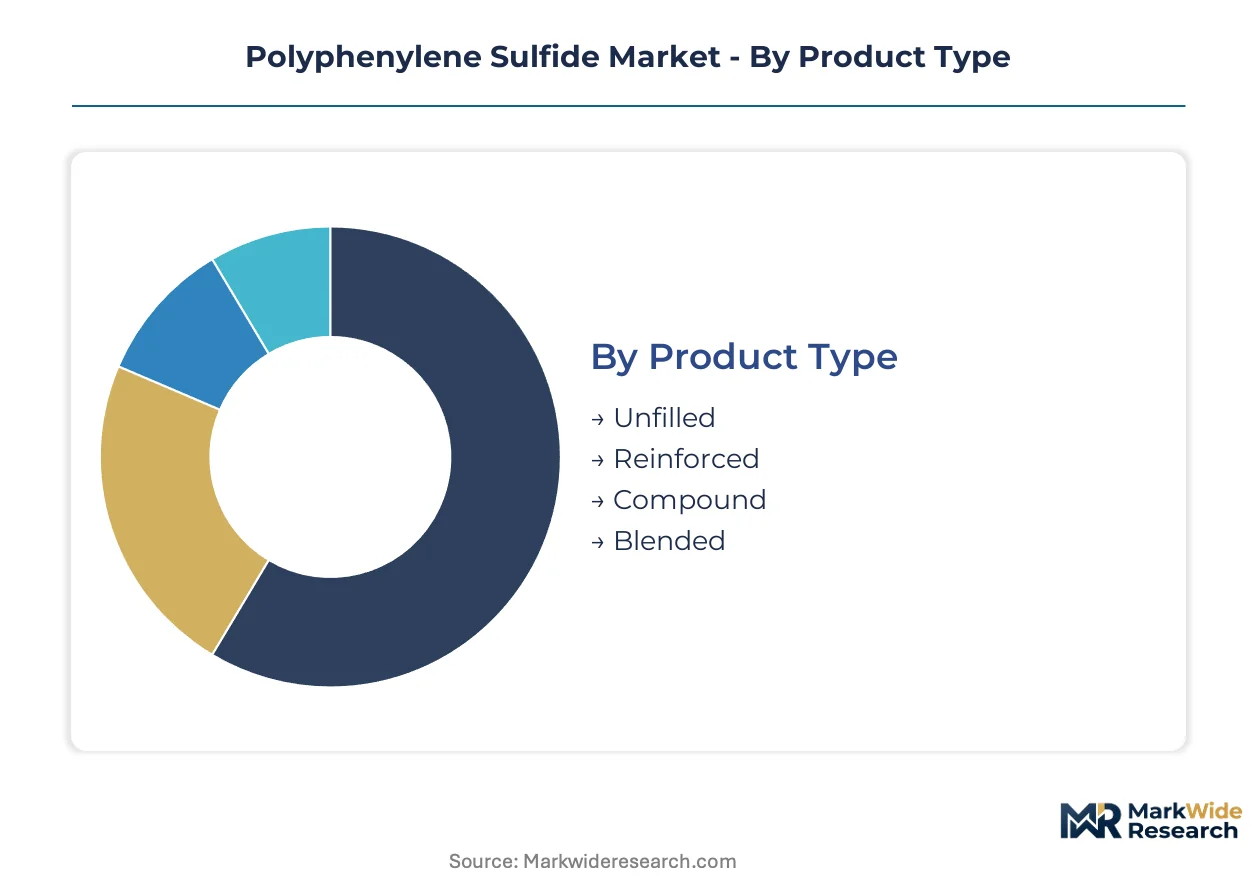
PPS resin specifications diverge sharply across end-use thermal and mechanical load requirements. Compounders must align melt-flow indices, fiber loading ratios, and flame-retardant packages to each segment's qualification protocols.
Product Type:
Reinforced grades demand the heaviest capital commitment for twin-screw compounding lines and long-fiber impregnation equipment.
- Reinforced:Glass fiber or carbon fiber loadings between 30-60% deliver stiffness-to-weight ratios critical for automotive pump housings and electronic connectors. Demand concentrates in German and Japanese automotive tier supply chains where OEMs mandate batch-level mechanical property documentation. REACH authorization thresholds for catalyst impurities are tightening qualification timelines.
- Compound:Tailored formulations incorporating mineral fillers, lubricants, and stabilizers target specific processing windows for injection molders. Chinese domestic compounders are expanding modified PPS output for local EV battery housings and power electronics encapsulation under MEE GB standards enforcement.
- Unfilled:Virgin resin grades serve specialized extrusion and compression molding applications requiring maximum chemical purity.
- Blended:Alloys with polyetherimide or liquid crystal polymer occupy high-frequency electronic substrates where dielectric performance commands premium positioning.
Reinforced grades absorb the bulk of installed capacity; compound formulations are expanding most quickly.
End User:
Automotive procurement volumes dominate resin allocation, though electronics qualification cycles generate higher margin per kilogram.
- Automotive:Under-the-hood connectors, thermal management modules, and high-voltage battery components drive specification. EU F-Gas Regulation substitution mandates are redirecting HVAC and cooling system designs toward PPS from fluoropolymers. OEMs in Stuttgart, Munich, and Wolfsburg manufacturing clusters embed material scientists at platform specification stages.
- Electronics:EMI shielding-grade compounds capture base station housing and fiber-optic connector assemblies across East Asian manufacturing corridors. UL 94 V-0 halogen-free certification timelines extend 12-18 months versus legacy brominated alternatives, compressing new grade introduction velocity.
- Aerospace:Continuous carbon fiber-reinforced PPS tapes are qualifying for primary structural brackets, opening margin pools beyond conventional injection molding grades.
- Industrial:Pump housings, valve components, and filtration systems exploit chemical resistance in aggressive process environments.
Automotive offtake commands the largest volume share; aerospace applications are climbing the fastest.
Application:
Insulation and sealing applications split between commodity pricing and specialty premium tiers based on thermal class ratings.
- Insulation:Wire and cable jacketing, motor slot liners, and transformer components leverage PPS dielectric stability across continuous service temperatures. 5G infrastructure deployment is accelerating specification wins in high-frequency substrate applications.
- Sealing:Gaskets, O-rings, and packings for chemical processing equipment substitute for fluoroelastomers where per- and polyfluoroalkyl substance restrictions tighten. EPA TSCA Section 5 premanufacture notifications govern new chemistries entering US commerce.
- Filtration:Non-woven and membrane structures for liquid and gas separation in corrosive environments.
- Coatings:Powder and liquid formulations for corrosion protection on chemical processing equipment.
Insulation applications hold the broadest installed base; sealing grades are gaining share fastest.
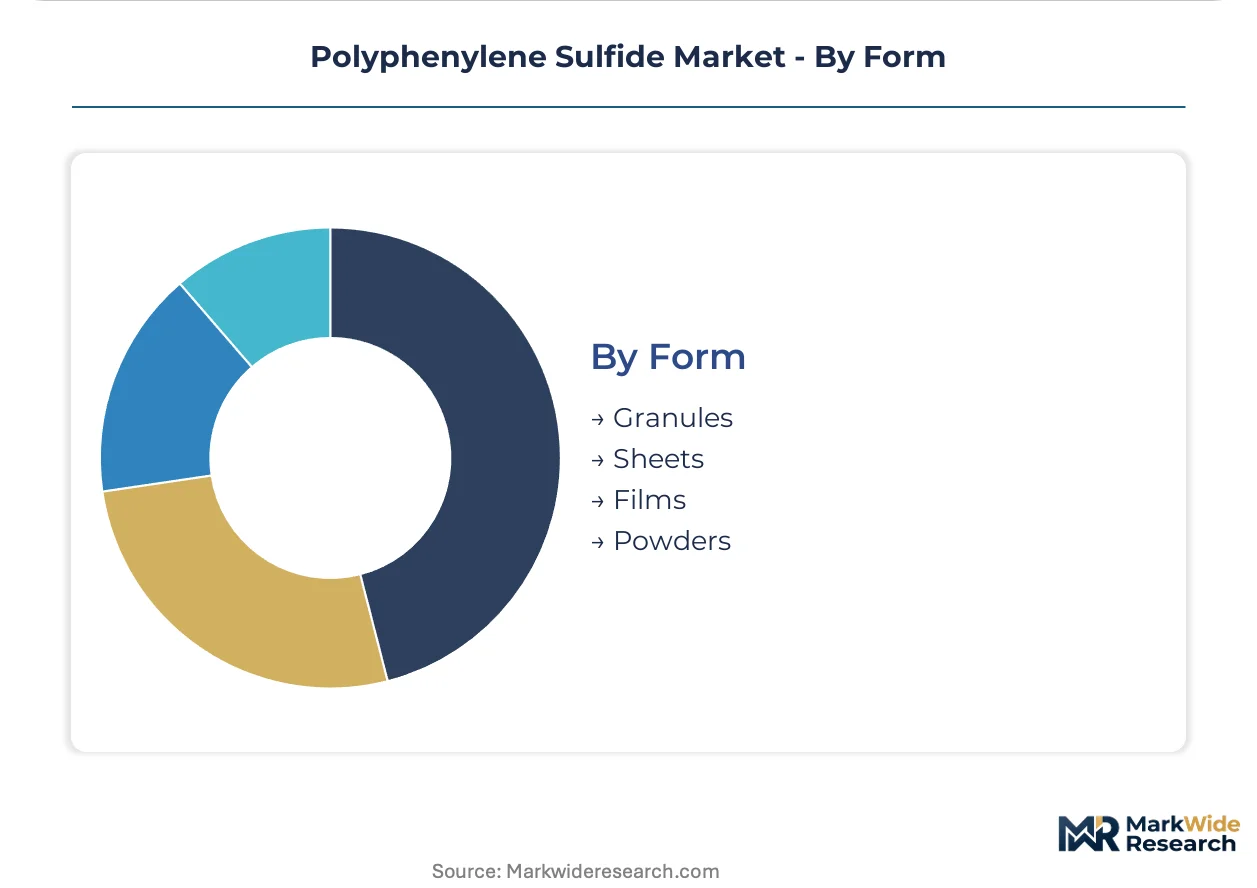
Form:
Granule production scales most efficiently, while film extrusion requires specialized die and orientation equipment.
- Granules:Standard injection molding feedstock with tailored melt-flow indices for thin-wall connector geometries. Mold flow simulation for crystallization kinetics requires scarce technical talent, constraining tier-two compounders from automotive qualification programs.
- Films:Biaxially oriented and cast structures for flexible circuit substrates and capacitor dielectrics. Toray Industries differentiates via carbon fiber-reinforced PPS hybrid materials targeting aerospace bracket applications.
- Sheets:Compression molding and thermoforming feedstock for chemical equipment linings and semiconductor process hardware.
- Powders:Coating applications and selective laser sintering additive manufacturing feedstock.
Granules represent the dominant form factor; films follow the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wolfsburg anchors European PPS procurement intensity as Volkswagen Group's battery platform consolidation concentrates resin specification decisions in Lower Saxony manufacturing corridors.
China
Yangtze River Delta EV battery housing production accelerates modified PPS consumption as domestic compounders expand compounding capacity for power electronics encapsulation. MEE enforces GB standards for volatile organic compound emissions at polymer synthesis facilities, redirecting capital toward closed-loop process upgrades. Shenzhen and Suzhou manufacturing clusters concentrate the fastest capacity buildout for local automotive tier supply.
United States
Michigan and California manufacturing corridors concentrate direct compounder-to-OEM technical partnerships as battery platform engineers embed material scientists at resin specification stages. EPA administers TSCA Section 5 premanufacture notifications for new PPS chemistries entering US commerce, extending qualification timelines for modified grades. Detroit-area automotive thermal management module production drives reinforced resin offtake.
Germany
Stuttgart, Munich, and Wolfsburg automotive clusters embed material scientists at platform specification stages for under-the-hood connector and thermal management applications. EU F-Gas Regulation hardens fluoropolymer substitution mandates across HVAC and automotive cooling systems, redirecting OEM specifications toward high-heat thermoplastics. REACH authorization requirements tighten impurity thresholds in sulfur-based polymerization catalysts, forcing resin producers to retrofit purification trains.
Japan
Kansai and Chubu industrial corridors anchor captive para-dichlorobenzene production and compounding expertise for supply security. METI oversees industrial chemical safety protocols shaping batch-level contaminant documentation requirements. Nagoya-area aerospace tier suppliers qualify continuous fiber-reinforced PPS tapes for primary structural bracket applications.
India
Maharashtra and Gujarat manufacturing zones present first-mover positioning for compounders establishing localized compounding infrastructure. BIS certification pathways for engineering thermoplastics remain underdeveloped, creating technical service differentiation opportunities. Mumbai-Pune industrial corridor automotive electronics manufacturing drives EMI shielding-grade compound interest.
Polyphenylene Sulfide Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive sulfur chemistry chains and specialized compounders with fiber integration capabilities. Market concentration remains moderate as Asian producers dominate upstream para-dichlorobenzene supply while European and North American players differentiate through modified grades and technical service. Three archetypes define positioning: integrated resin producers controlling polymerization assets, independent compounders blending tailored formulations, and hybrid material specialists developing carbon fiber-reinforced tapes. Capacity expansion and direct OEM technical partnerships constitute the dominant competitive moves reshaping channel relationships.
Among integrated chemical producers, Solvay exemplifies the archetype leveraging sulfur chemistry integration for cost-competitive virgin and recycled resin output. DIC Corporation occupies a position within the supply-secured tier through captive feedstock production and compounding expertise. Toray Industries sits within the advanced materials specialization vector, representing positioning around carbon fiber-reinforced hybrid materials for aerospace bracket applications.
| Leading Market Players |
|---|
| Solvay |
| DIC Corporation |
| Lion Idemitsu Composites |
| Polyplastics Co. Ltd. |
| Toray Industries |
| Tosoh Corporation |
| Celanese Corporation |
| Kureha Corporation |
| TEIJIN Limited |
| Others |
Supply Flow & Price Mechanics
Specialized polymer processing engineers in Germany's Stuttgart manufacturing corridor command compensation premiums that compress tier-two compounder margins while widening spreads between automotive-qualified and general-purpose PPS grades. REACH compliance documentation costs and captive sulfur chemistry integration determine which suppliers capture pricing power across reinforced resin tiers.
Pricing Analysis
Automotive OEM uptime guarantees anchor value-based pricing for thermal management module grades, with compounders capturing premiums tied to batch-level mechanical property documentation and zero-defect supply commitments. Pricing stratifies across UL 94 V-0 halogen-free certified, legacy brominated, and uncertified economy tiers based on flame-retardant package complexity and qualification timeline investment. Cost compression in standard reinforced grades is intensifying because Chinese domestic compounders are expanding modified PPS output for local EV battery housings. Tier-one automotive suppliers demonstrate lowest price sensitivity given platform consolidation and embedded material scientist relationships, while industrial pump housing buyers negotiate aggressively on volume contracts.
Supply Chain Analysis
Polymerization chemist and mold flow simulation specialist availability constrains capacity expansion in Michigan and Wolfsburg manufacturing corridors where automotive qualification programs concentrate demand. Supply concentrates in China, Japan, and Germany, with Asian suppliers dominating upstream para-dichlorobenzene chemistry through captive chlorobenzene production. European and North American compounders draw from sodium sulfide and polar aprotic solvent inputs subject to freight-adjusted cost volatility. Single-source vulnerability runs through Japanese para-dichlorobenzene producers given Kansai industrial corridor concentration. Distribution runs through direct compounder-to-OEM technical partnerships displacing traditional distributor channels in North American EV supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH authorization requirements and UL 94 V-0 halogen-free certification timelines force capital-constrained compounders toward exit or acquisition.
For Market Incumbents: Lock in sulfur chemistry integration through backward integration into sodium sulfide production or long-term offtake agreements with para-dichlorobenzene suppliers, insulating margin from Asian feedstock volatility. Capture channel control by embedding technical service teams at Volkswagen Group and other OEM platform specification stages in Wolfsburg, Stuttgart, and Munich manufacturing clusters before battery platform consolidation hardens supplier lists.
For New Entrants and Emerging Players: Automotive tier-two suppliers in India's Maharashtra and Gujarat manufacturing zones present partnership opportunities given underdeveloped BIS certification pathways and localized compounding infrastructure gaps. Target EMI shielding-grade compound formulations for 5G base station housing applications where East Asian manufacturing clusters accelerate specification wins and qualification timelines remain more penetrable than automotive grades.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid material specialists developing carbon fiber-reinforced PPS tapes given aerospace tier supplier qualification momentum for primary structural bracket applications. Long-term viability favors compounders with demonstrated automotive platform wins and captive feedstock arrangements over pure-play resin distributors. Signal to watch: OEM circularity commitment acceleration under EU Green Deal protocols driving pyrolysis-based reclamation infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Sulfide | Solvay leverages captive sulfur chemistry to sustain cost-competitive virgin and recycled resin output against Asian feedstock volatility. |
| Long-term Supply Agreement with OEMs | Direct compounder-to-OEM technical partnerships in Michigan and California corridors embed material scientists at resin specification stages. |
| Green Manufacturing Transition | Closed-loop process upgrades under MEE GB standards enforcement redirect Chinese capital toward volatile organic compound emission controls. |
| Joint Venture for Carbon Fiber Hybridization | Aerospace tier suppliers in Nagoya qualify continuous fiber-reinforced PPS tapes for primary structural bracket margin pools. |
| Capacity Expansion in India | First-mover compounders establishing Maharashtra and Gujarat technical service infrastructure capture BIS certification pathway development. |
Methodological Framework
Document review covered customs and trade data, SEC 10-K filings, and ACC/Cefic chemical industry reports, complemented by interviews with polymerization plant managers, automotive Tier 1 procurement leads, distribution channel partners, and technical R&D directors. Primary fieldwork across the Yangtze River Delta, Kansai industrial corridor, and Michigan manufacturing zones validated secondary data on capacity buildout and qualification timelines. Bottom-up resin consumption estimates by end-use application triangulated against top-down polymerization capacity assessments.
Historical volume trajectories cross-referenced against expert panel input on automotive electrification and 5G infrastructure deployment shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, fiber loading specification, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery platform content-per-vehicle assumptions and fluoropolymer substitution rates under EU F-Gas Regulation mandates.
Several conditions sit outside the modeled scope, including abrupt per- and polyfluoroalkyl substance restriction tightening, para-dichlorobenzene feedstock supply disruptions, and automotive OEM platform consolidation reversals. Forecasts reflect assumptions on REACH authorization timeline stability and halogen-free certification pathway development. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Green Polyols Market