
 Conditioning Polymers Market | 2026-2036
Conditioning Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Conditioning Polymers Market Analytics
Buyer concentration among personal care multinationals is realigning procurement leverage toward formulators with global scale. BASF leverages its integrated silicone-polymer platform to serve tier-one cosmetics houses across multiple continents. Dow Chemical sustains volume leadership through backward integration into ethylene oxide feedstocks. Solvay anchors specialty positions in polyamide conditioning agents for premium hair care lines.
Conditioning polymers are film-forming or substantiative macromolecules, typically cationic or amphiphilic in charge profile, that deposit on keratinous or cellulosic substrates to reduce friction and improve tactile properties; molecular weights generally range from 10,000 to 2,000,000 Daltons depending on deposition kinetics required. Silicone variants occupy the largest value share due to their unmatched spreadability and sensory profile in rinse-off applications. Polyacrylate segments are gaining fastest in leave-on skin care as formulators seek non-occlusive hydration films. Liquid forms dominate formulation flexibility, though powder grades command margin premiums in solid shampoo and anhydrous balm formats.
REACH registration requirements in Europe and FDA cosmetic ingredient reviews in the United States are elevating toxicological dossier costs for new polymer introductions. China's SAMR now mandates safety assessment filings for imported cosmetic raw materials, adding a third compliance layer for multinational suppliers. Stakeholders must monitor evolving polymer microplastic restrictions under the EU Green Deal, as cationic conditioning agents face scrutiny for aquatic persistence profiles.
Market Dynamics
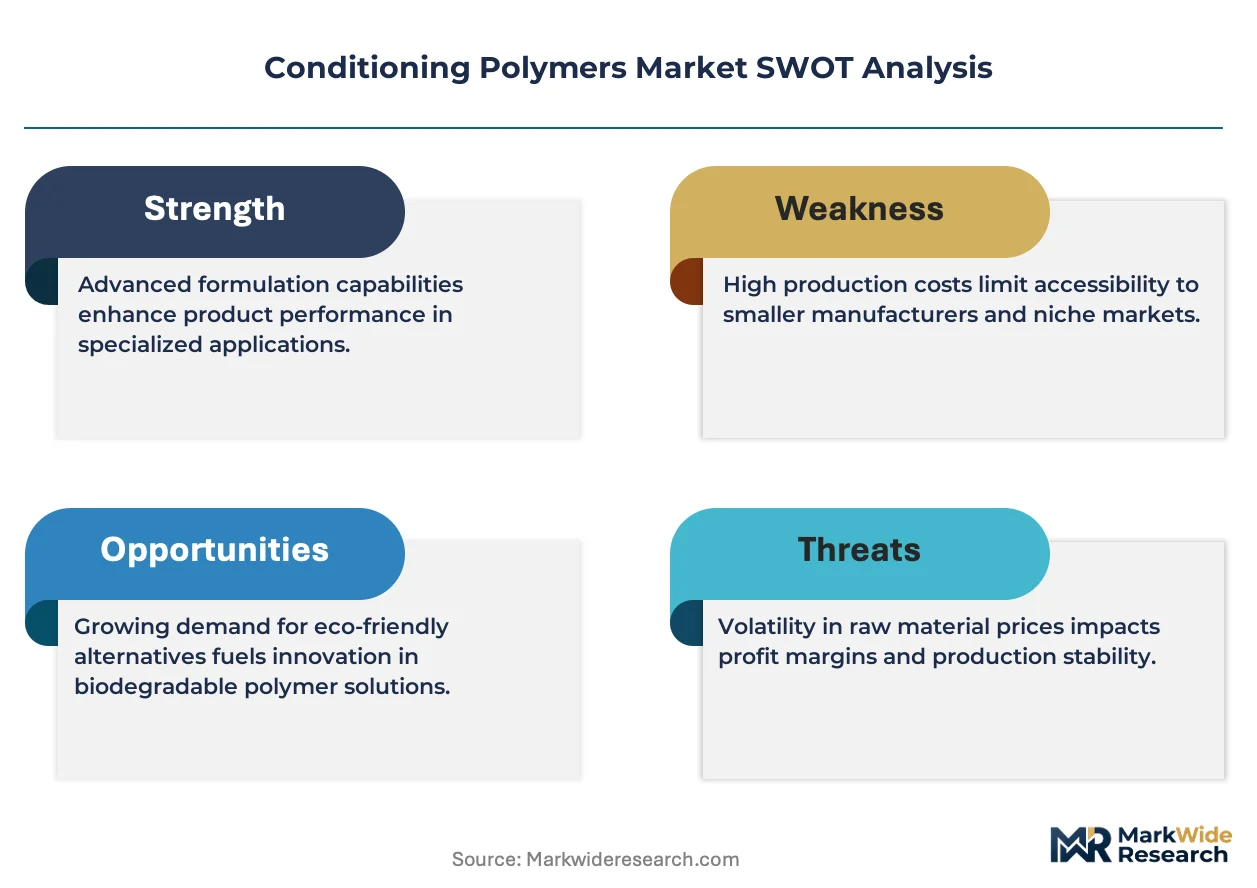
Personal care formulators are consolidating conditioning polymer procurement around suppliers with multi-continent regulatory dossiers, compressing vendor lists as REACH, FDA, and SAMR compliance costs escalate.
Growth Catalysts
- Biodegradable cationic polymers:ECHA's microplastic restrictions under the EU Green Deal are accelerating formulator migration toward bio-based conditioning agents with improved aquatic degradation profiles.
- China's domestic cosmetic manufacturing:Local brands scaling production in Shanghai and Guangzhou are demanding localized polymer supply chains to reduce import dependency and customs clearance friction.
- Leave-on skin care expansion:Polyacrylate variants are capturing formulation share as consumers prioritize non-occlusive hydration films in facial serums and moisturizers.
Market Restraints
- Ethylene oxide feedstock volatility:Dow Chemical's backward integration into ethylene oxide provides insulation, but mid-tier suppliers face margin compression from petrochemical price swings.
- Aquatic toxicity documentation:ECHA's REACH registration requirements for cationic polymers demand extensive ecotoxicological testing, extending new product introduction timelines by 18-24 months.
- Silicone substitution pressure:Clean beauty positioning is driving formulators toward bio-based alternatives, threatening volume share for dimethicone and amodimethicone variants.
Strategic Opportunities
- Solid format cosmetics:Powder-grade conditioning polymers command margin premiums in anhydrous shampoo bars and balm formats as waterless beauty gains traction in Germany and France.
- India's personal care manufacturing:PLI scheme incentives for domestic cosmetic production are creating localized polymer demand as multinational brands establish contract manufacturing in Maharashtra and Gujarat.
- SAMR regulatory harmonization:China's safety assessment filing requirements for imported raw materials favor suppliers with existing toxicological dossiers, creating barrier-to-entry advantages for established players.
Industry Challenges
- Cross-regulatory dossier management:Maintaining concurrent compliance with REACH, FDA cosmetic ingredient reviews, and SAMR filings requires dedicated regulatory affairs functions with polymer-specific toxicology expertise.
- Legacy formulation integration:Substituting conventional silicones with bio-based conditioning agents demands reformulation of established hair care lines without compromising sensory performance benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conditioning Polymers Market |
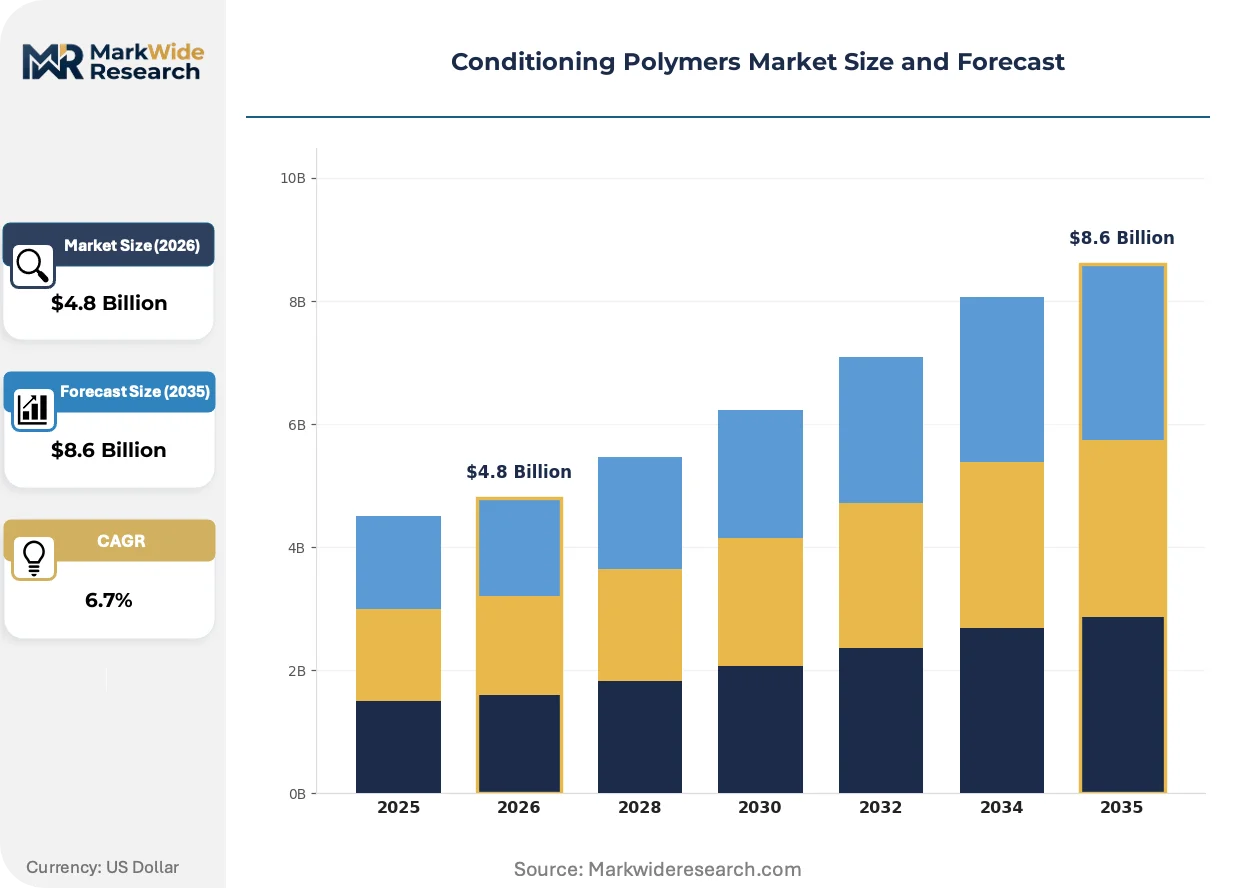
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyethylene Glycol, Polyacrylate, Polyamides Application: Personal Care, Household Products, Industrial Applications, Textile Treatment End Use Industry: Cosmetics, Food & Beverage, Automotive, Construction Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | BASF, Dow Chemical, Solvay, Evonik, Lubrizol, AkzoNobel, Ashland, Lonza, Nalco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conditioning Polymers Market Evolving Landscape
Conditioning polymer innovation is pivoting toward regulatory-compliant biodegradability while formulation science advances deposition control through molecular architecture engineering.
Amphiphilic block copolymers with tunable cationic charge density are consolidating technical preference among premium hair care formulators. BASF's integrated silicone-polymer platform demonstrates this trajectory, as tier-one cosmetics houses specify polymers with precise molecular weight distributions between 50,000 and 500,000 Daltons for optimized keratin substrate adhesion. The technology is consolidating R&D investment away from conventional homopolymer conditioning agents toward architecturally complex macromolecules with substantivity control.
ECHA's evolving microplastic restrictions under the EU Green Deal are reshaping polymer registration strategies across the personal care value chain. Cationic conditioning agents face heightened scrutiny for aquatic persistence, forcing suppliers to generate biodegradation data under OECD 301B protocols before market authorization. European formulators are responding by pre-qualifying bio-based alternatives in rinse-off applications, anticipating regulatory expansion to leave-on products.
Direct-to-consumer beauty brands are compressing raw material qualification cycles, demanding conditioning polymer samples with pre-assembled regulatory packages. Contract manufacturers in China's Pearl River Delta are bypassing traditional distributor networks, building direct supplier relationships to accelerate formulation turnaround. This pattern is most pronounced in Guangdong province, where domestic cosmetic brands iterate product launches quarterly rather than seasonally.
Conditioning Polymers Market Segmentation
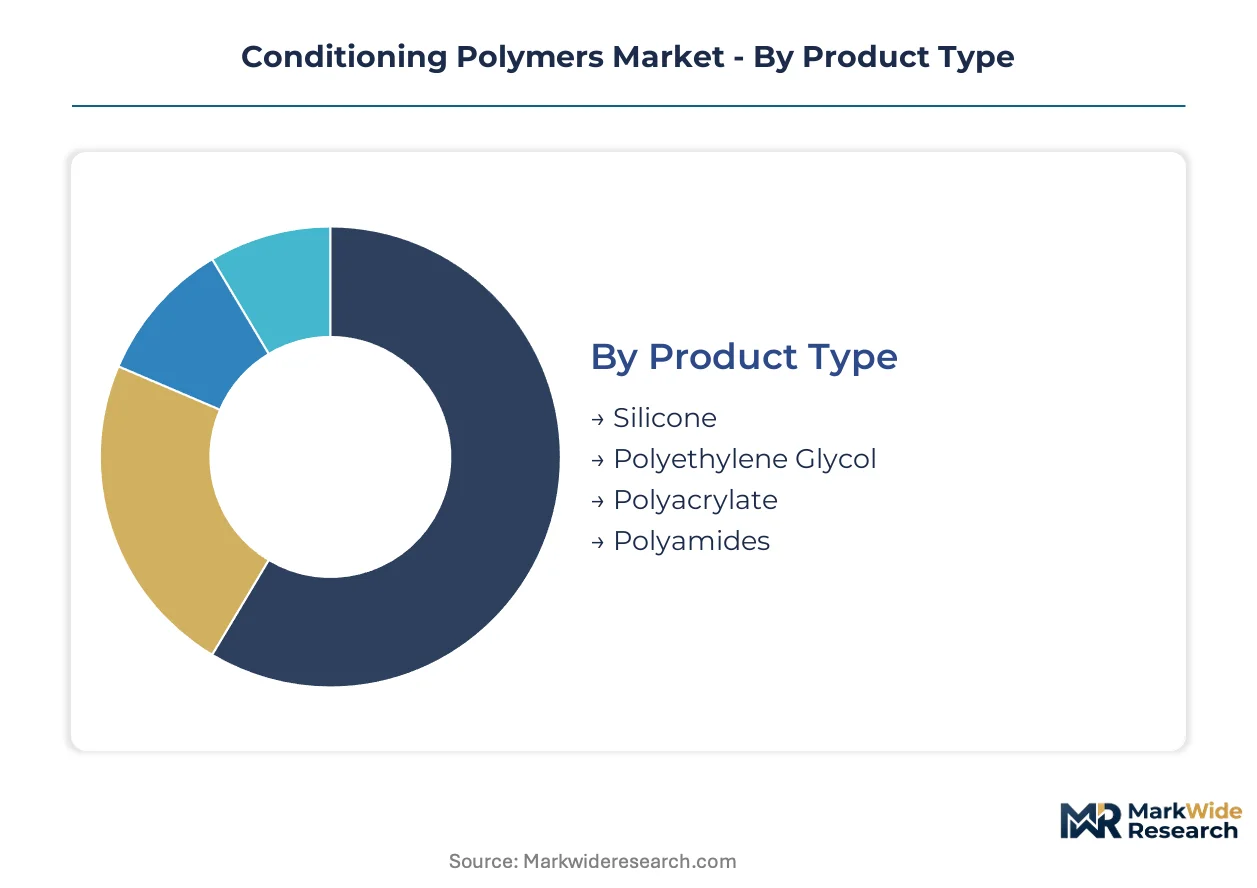
Formulators select conditioning polymers based on deposition kinetics, regulatory dossier availability, and sensory performance requirements. Segmentation reveals how procurement priorities diverge across rinse-off versus leave-on applications, premium versus mass-market positioning, and established versus emerging manufacturing geographies.
Product Type:
Buyers differentiate primarily by spreadability requirements and clean beauty positioning, with sensory benchmarks and biodegradability credentials driving specification choices.
- Silicone:Dimethicone and amodimethicone variants deliver unmatched spreadability and sensory profile in rinse-off hair care. ECHA's microplastic restrictions under the EU Green Deal are forcing European formulators toward bio-based alternatives, compressing volume outlook despite technical superiority.
- Polyacrylate:Non-occlusive film-forming properties position these polymers for leave-on facial serums and moisturizers where hydration without heaviness is specified. China's domestic cosmetic brands in Shanghai and Guangzhou are scaling polyacrylate procurement for localized skin care manufacturing.
- Polyethylene Glycol:Water-soluble conditioning agents with tunable molecular weights for viscosity control in shampoo formulations.
- Polyamides:Specialty cationic variants for premium hair care lines requiring substantivity control and thermal protection.
Volume sits with Silicone; growth tilts toward Polyacrylate.
Application:
Application selection tracks formulation complexity, with personal care commanding the most stringent purity documentation and household products tolerating broader specification ranges.
- Personal Care:Hair and skin formulations demand cationic or amphiphilic polymers with molecular weights between 10,000 and 2,000,000 Daltons for controlled deposition kinetics. REACH registration costs and FDA cosmetic ingredient reviews are elevating supplier qualification barriers, consolidating procurement around multinationals with multi-continent dossiers.
- Household Products:Fabric softeners and surface cleaners utilize conditioning polymers for anti-static and lubricity benefits with reduced toxicological documentation requirements compared to cosmetic applications.
- Industrial Applications:Metalworking fluids and coatings incorporate conditioning polymers for friction reduction and substrate protection.
- Textile Treatment:Fiber lubrication and anti-snag finishes in apparel manufacturing.
Procurement complexity concentrates in Personal Care; formulation expansion is accelerating fastest in Household Products.
End Use Industry:
End use selection reflects margin structure, with cosmetics tolerating premium pricing for sensory differentiation and automotive prioritizing cost-efficient functional performance.
- Cosmetics:Hair care, skin care, and color cosmetic formulations specify conditioning polymers with film-forming or substantiative properties for tactile enhancement. China's SAMR safety assessment filing requirements for imported raw materials are favoring established suppliers with existing toxicological dossiers.
- Food & Beverage:Limited conditioning polymer use in processing equipment lubrication and packaging surface treatments.
- Automotive:Interior trim conditioning and leather treatment applications.
- Construction:Additive applications in sealants and coatings for substrate adhesion.
Specification intensity peaks in Cosmetics; volume scale is largest in Automotive.
Form:
Form selection balances formulation flexibility against handling economics, with liquid forms dominating continuous manufacturing and powder grades capturing solid format premiums.
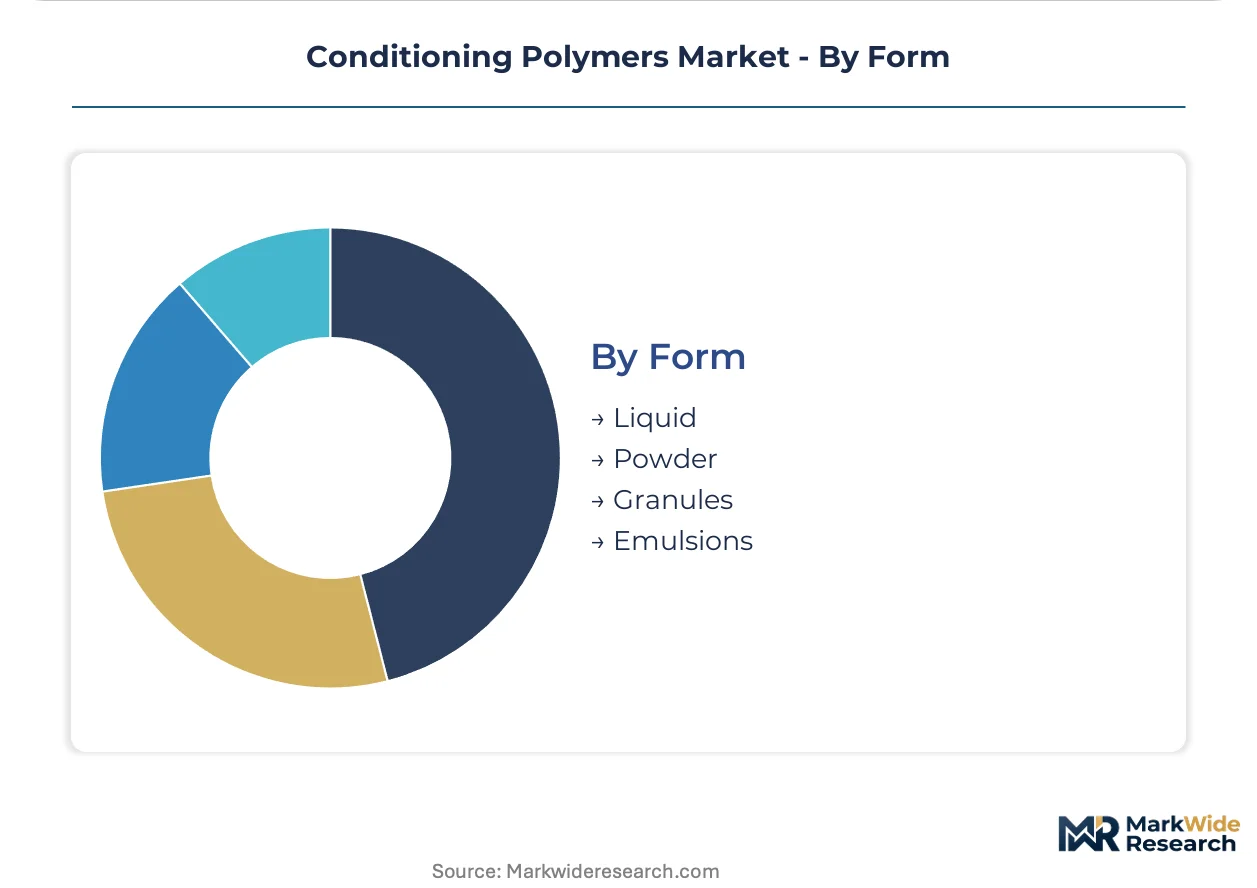
- Liquid:Aqueous and anhydrous liquid polymers dominate formulation flexibility for conventional shampoo, conditioner, and lotion manufacturing. Dow Chemical's backward integration into ethylene oxide feedstocks supports volume leadership in liquid polyethylene glycol derivatives.
- Powder:Anhydrous grades command margin premiums in solid shampoo bars and balm formats as waterless beauty gains traction in Germany and France. Powder conditioning polymers require specialized dispersion equipment but eliminate preservative requirements and reduce shipping weights.
- Granules:Intermediate handling form for industrial-scale compounding operations.
- Emulsions:Pre-dispersed polymer systems for simplified formulation incorporation.
Liquid holds manufacturing scale; Powder captures the steepest expansion trajectory in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal care formulators in China now drive the largest absolute volume expansion for conditioning polymers, while regulatory divergence across the United States, Germany, and India is fragmenting supplier qualification requirements.
China
Domestic cosmetic brands in Shanghai and Guangzhou are scaling manufacturing capacity for hair care and skin care lines, creating localized demand for polyacrylate and silicone conditioning polymers. SAMR mandates safety assessment filings for all imported cosmetic raw materials, elevating documentation burdens for foreign suppliers. The Pearl River Delta contract manufacturing cluster now iterates product launches quarterly, compressing polymer sample qualification cycles.
United States
Personal care multinationals headquartered in New Jersey and California are consolidating procurement around suppliers with pre-assembled FDA cosmetic ingredient dossiers. The EPA monitors aquatic toxicity profiles for cationic polymers discharged in rinse-off applications, though federal pre-market approval remains less stringent than REACH. Midwest manufacturing hubs near Dow Chemical's ethylene oxide feedstock operations maintain cost advantages in liquid polymer production.
Germany
Premium hair care formulators in Hamburg and Düsseldorf specify polyamide conditioning agents with substantivity control for thermal protection applications. ECHA's REACH registration requirements demand extensive ecotoxicological testing under OECD 301B protocols for biodegradation claims. The EU Green Deal's microplastic restrictions are accelerating migration toward bio-based alternatives in rinse-off formulations.
India
Contract manufacturers in Maharashtra and Gujarat are expanding conditioning polymer procurement as multinational brands establish production under the PLI scheme for domestic cosmetic manufacturing. CDSCO oversees cosmetic ingredient safety through the Drugs and Cosmetics Act, though enforcement intensity lags European standards. Mumbai-based formulators are qualifying powder-grade polymers for solid shampoo bar exports to Germany and France.
Japan
Specialty hair care brands in Osaka and Tokyo prioritize conditioning polymers with precise molecular weight distributions between 50,000 and 500,000 Daltons for keratin substrate adhesion. METI's chemical substance management frameworks align with REACH principles, creating dual-compliance pathways for suppliers already registered in Europe. Kansai region formulators are integrating amphiphilic block copolymers into premium leave-on treatments.
Conditioning Polymers Market Competitive Landscape
German producers anchor one tier; American specialists hold feedstock-integrated positions. The vendor base stratifies across three tiers: multinational chemical conglomerates with multi-continent regulatory dossiers, mid-cap regional suppliers serving domestic formulators, and niche bio-based polymer developers. Strategic moves concentrate on backward integration into ethylene oxide feedstocks and portfolio diversification toward biodegradable cationic variants.
Within the multinational tier, BASF leverages its integrated silicone-polymer platform, Dow Chemical sustains volume leadership through captive ethylene oxide supply, and Solvay anchors specialty positions in polyamide conditioning agents. These three exemplify divergent archetypes: BASF represents the full-spectrum platform player, Dow Chemical occupies the feedstock-integrated commodity position, and Solvay sits within the premium specialty segment. Their collective presence compresses vendor lists as procurement consolidation accelerates.
| Leading Market Players |
|---|
| BASF |
| Dow Chemical |
| Solvay |
| Evonik |
| Lubrizol |
| AkzoNobel |
| Ashland |
| Lonza |
| Nalco |
| Others |
Value Network & Pricing Analysis
Ethylene oxide feedstock costs transmit directly from Dow Chemical's captive Gulf Coast production through liquid polyethylene glycol derivatives to mid-tier formulators, compressing margins for non-integrated suppliers while reinforcing tier-one pricing power.
Pricing Analysis
Volume leadership concentrates in liquid silicone and polyethylene glycol grades where Dow Chemical's backward integration anchors economy-tier pricing, while powder-grade polyamides from Solvay capture premium positioning in solid shampoo formats. Price differentiation rests on REACH dossier completeness and biodegradability certification under OECD 301B protocols. Pricing pressure intensifies in silicone variants as ECHA microplastic restrictions force European formulators toward bio-based alternatives. Mass-market personal care brands exhibit highest price sensitivity; premium cosmetics houses tolerate substantial premiums for substantivity-controlled polyamides.
Supply Chain Analysis
Freight cost differentials between anhydrous powder shipments from Germany and aqueous liquid bulk from the US Gulf Coast influence formulator procurement geography, particularly for Pearl River Delta manufacturers iterating quarterly launches. Supply concentrates in the United States, Germany, and China, with ethylene oxide derivatives feeding from Texas petrochemical complexes and specialty polyamides originating in Belgian and German production hubs. Raw material dependencies center on ethylene oxide, silicone monomers, and bio-based cationic feedstocks. Single-source vulnerability persists for OECD 301B-certified biodegradable variants. Distribution runs through direct supplier relationships with Guangdong contract manufacturers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration capacity constraints prop pricing power for dossier-complete suppliers, as new polymer introductions face 18-24 month toxicological testing timelines that freeze competitive entry.
For Market Incumbents: Anticipate silicone substitution pressure from clean beauty positioning by accelerating bio-based cationic polymer R&D and pre-qualifying alternatives under ECHA's evolving microplastic framework. Defend margin structure through captive ethylene oxide supply or specialty polyamide differentiation, while monitoring SAMR filing backlogs that could delay Chinese market access for competitors. For New Entrants and Emerging Players: The premium-economy price gap in powder-grade conditioning polymers for waterless beauty formats offers white-space entry, particularly for anhydrous shampoo bar suppliers serving German and French formulators. Target India's PLI-subsidized contract manufacturing cluster in Maharashtra and Gujarat with localized production partnerships. Pursue direct qualification with Guangdong contract manufacturers bypassing distributor markups. For Investors and Strategic Acquirers: BASF's integrated silicone-polymer platform expansion announcements are the leading indicator that multi-continent regulatory dossiers are consolidating competitive moats. Five-to-ten year viability favors suppliers with concurrent REACH, FDA, and SAMR compliance infrastructure. Target acquisition candidates with existing OECD 301B biodegradation data packages. Monitor ECHA restriction timeline acceleration as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow Chemical's captive feedstock supply insulates margin compression from petrochemical volatility. |
| Biodegradable Cationic Polymer Development | ECHA's microplastic restrictions under the EU Green Deal force formulation migration toward OECD 301B-certified alternatives. |
| SAMR Dossier Pre-Assembly | China's safety assessment filing requirements favor established suppliers with existing toxicological packages. |
| Powder-Grade Capacity Expansion | Anhydrous polymer production for solid shampoo bars captures waterless beauty premiums in Germany and France. |
| Direct Supplier Relationships with Guangdong CMOS | Pearl River Delta contract manufacturers now iterate quarterly launches, compressing traditional distributor cycles. |
Research Methodology
Independent corroboration across formulator procurement leads, regulatory affairs directors at multinational chemical suppliers, and ECHA registration consultants underwrites the qualitative findings in this study. Primary interviews with personal care R&D directors, supply chain managers at Shanghai and Guangzhou cosmetic brands, and technical sales leads at conditioning polymer distributors were validated against secondary sources including REACH registration databases, FDA cosmetic ingredient filings, SAMR safety assessment records, and customs trade data for ethylene oxide derivatives. Bottom-up polymer volume estimates triangulate against top-down personal care formulation consumption models.
Comparable-period anchoring to historical REACH registration timelines and silicone substitution patterns structured the projection framework across the analysis window. Segmentation modeling incorporated product type, application, form, and regional regulatory cluster dimensions. CAGRs derive from ethylene oxide feedstock cost trajectories, ECHA restriction implementation schedules, and China domestic cosmetic manufacturing capacity buildouts.
Inputs from ECHA pre-registration databases and SAMR filing disclosures were available through the study window; gaps in real-time biodegradation test data under OECD 301B protocols introduce uncertainty bands around bio-based polymer adoption timelines. Forecasts reflect assumptions regarding regulatory enforcement intensity and feedstock cost stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polyol Esters Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Nonchlorinated Polyolefins Market