
 Global Liquid Crystal Polymer (LCP) Market | 2026-2036
Global Liquid Crystal Polymer (LCP) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Crystal Polymer (LCP) Market Foresight
The direct-to-manufacturer supply channel is narrowing as resin producers bypass distributors to serve electronics fabricators with customized LCP grades. Toray Industries leverages its integrated polymerization and film extrusion capabilities to lock in high-frequency connector contracts. Celanese Corporation anchors North American supply through captive compounding assets in South Carolina. Sumitomo Chemical Co., Ltd. competes on ultra-low dielectric constant formulations for millimeter-wave antenna substrates.
Liquid crystal polymer is a wholly aromatic thermoplastic exhibiting ordered mesophase structure, melt viscosity typically below 10,000 poise, and thermal stability exceeding 300°C, engineered primarily for precision-molded electrical components and high-frequency signal transmission. Resin dominates volume throughput because injection molding of connector housings consumes the bulk of industry tonnage. Film is the fastest-expanding product category as flexible printed circuit substrates for foldable smartphones absorb new capacity. Powder segments occupy niche additive applications where melt-blending with fluoropolymers creates specialty composites.
FDA regulates LCP grades intended for medical device housings and surgical instrument handles, while REACH restricts certain aromatic amine precursors in European-sourced resins. Japan's METI enforces JIS standards on flame-retardant classifications for telecommunications-grade compounds. China's GB standards and NMPA oversight on medical applications are converging toward stricter migration testing protocols. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape energy-intensive polymerization economics.
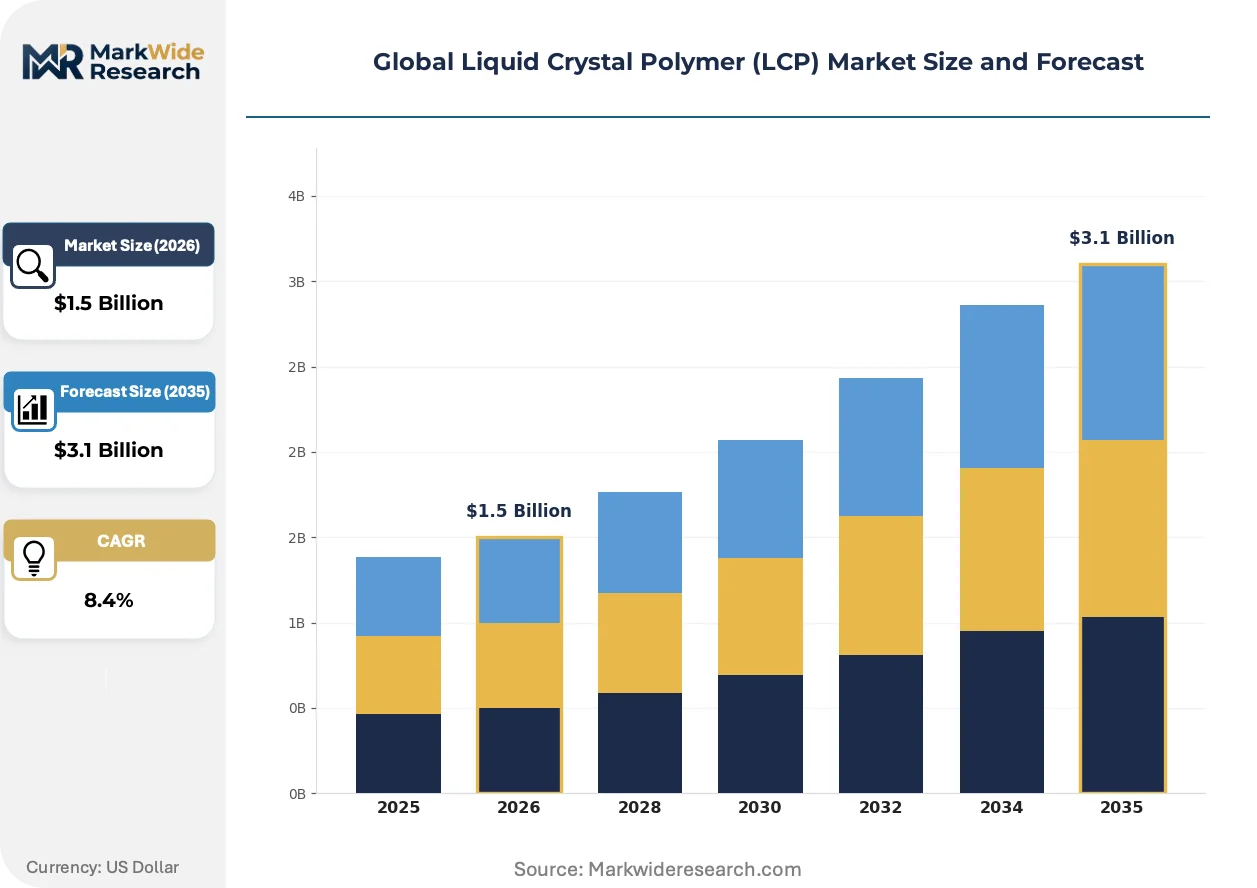
Market Dynamics
5G infrastructure deployment is compressing connector development cycles, forcing resin suppliers to co-develop customized LCP grades directly with telecommunications equipment fabricators in South Korea and Taiwan.
Growth Catalysts
- Millimeter-wave antenna substrates:Foldable smartphone manufacturers in Taiwan are absorbing new film-grade capacity for flexible printed circuit substrates. This end-use vertical is pulling formulation innovation toward ultra-low dielectric constant specifications.
- REACH aromatic amine restrictions:European resin producers are reformulating polymerization pathways to eliminate restricted precursors, creating first-mover advantage for compliant grades in medical device housings.
- East Asian electronics clusters:Concentrated injection molding capacity in South Korea and Taiwan consumes the bulk of industry tonnage, locking in volume commitments from resin producers.
Market Restraints
- Monomer supply concentration:Aromatic diacid and hydroxybenzoic acid feedstocks concentrate among Japanese and Chinese chemical intermediates suppliers, exposing compounders to input volatility.
- High melt-processing temperatures:LCP's thermal stability exceeding 300°C demands specialized injection molding equipment with hardened screw and barrel configurations, elevating capital barriers for new entrants.
- Fluoropolymer substitution:PTFE and PFA compounds compete for high-frequency signal transmission applications where dielectric performance tolerates slightly higher loss tangents.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for telecom and mobile device production are attracting connector fabricators seeking localized resin supply.
- Medical device migration testing:China's NMPA and GB standards convergence toward stricter protocols creates premium positioning for compliant LCP grades in surgical instrument handles.
- Dual carbon policy alignment:Beijing's energy-intensive industry restrictions are accelerating polymerization process efficiency investments that reduce unit carbon intensity.
Industry Challenges
- Specialized rheology expertise:Formulating LCP grades with melt viscosity below 10,000 poise while maintaining mesophase order requires polymer scientists with scarce aromatic thermoplastic experience.
- Multi-regulatory certification timelines:Simultaneous FDA, REACH, and METI JIS compliance for telecommunications-grade compounds extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Crystal Polymer (LCP) Market |
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $3.1 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Fiber, Resin, Composite, Powder Application: Consumer Electronics, Aerospace Components, Automotive Components, Industrial Machinery, Telecommunications Equipment Technology: Injection Molding, Extrusion, Lamination, Coating, 3D Printing End User Industry: Electronic Manufacturers, Aerospace Fabricators, Vehicle Assemblers, Heavy Equipment Makers, Communication Providers |
| Companies Covered | Toray Industries, Inc., Kuraray Co., Ltd., Celanese Corporation, Ueno Fine Chemicals Industry, Ltd., RTP Company, Polyplastics Co., Ltd., Solvay S.A., Mitsubishi Chemical Group, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Crystal Polymer (LCP) Market Shifts & Advancements
Material science convergence and direct manufacturer engagement are eroding traditional distribution layers while regulatory fragmentation across medical and telecom verticals is multiplying formulation complexity.
Multi-layer LCP film laminates is hybridizing with copper-clad substrate architectures to enable finer pitch flexible circuits. South Korean smartphone OEMs are qualifying these structures for foldable hinge interconnects at accelerated 12-month cycles. This hybridizing technology is compressing incumbent polyimide film margins in high-frequency applications.
China's GB standards on flame-retardant classifications are tightening halogen-free requirements for telecommunications-grade compounds. Compounders must reformulate phosphorus-based synergist packages to maintain V-0 ratings without brominated additives. Medical device segments in China face the steepest recertification burden as NMPA aligns with EU MDR migration testing protocols.
Direct resin-to-fabricator contracting is displacing distributor-mediated procurement in high-volume connector applications. Electronics manufacturing services in Taiwan and South Korea are consolidating purchase authority and demanding lot-to-lot viscosity consistency guarantees. This channel compression is most visible in millimeter-wave antenna substrate programs where formulation co-development locks in multi-year supply agreements.
Global Liquid Crystal Polymer (LCP) Market Segmentation
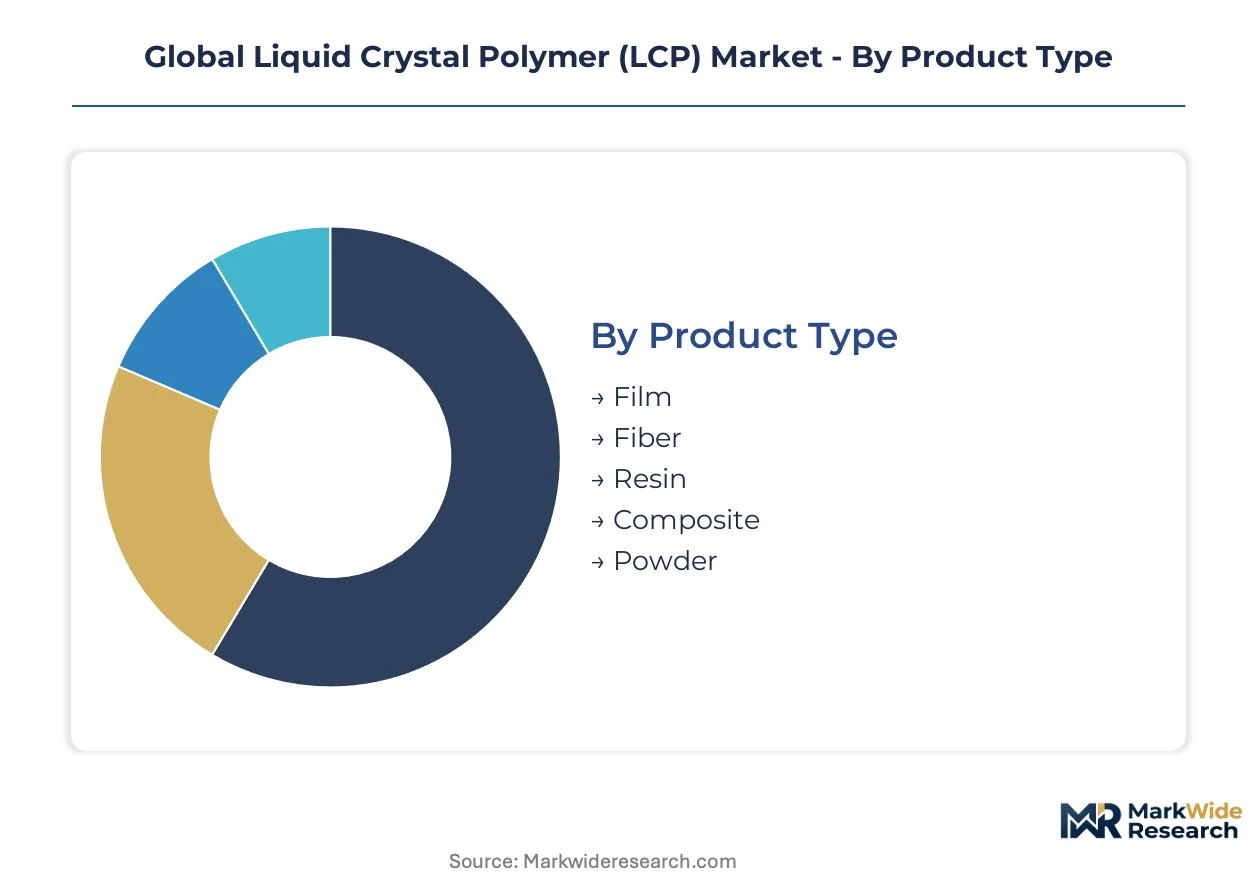
LCP procurement patterns diverge sharply across product forms and processing routes. Technical service intensity varies by segment, with resin grades demanding the most intensive co-development support while powder additives require minimal field engineering.
Product Type:
After-sales service intensity peaks with resin grades requiring viscosity calibration and mold-flow optimization at customer sites, while film and fiber segments demand less ongoing technical support.
- Resin:Injection-molding grades dominate industry tonnage with melt viscosity engineered below 10,000 poise for precision connector housings. South Korean electronics manufacturing services consume the bulk of volume through direct mill contracts that lock in lot-to-lot consistency guarantees. Resin holds the largest share; momentum sits with film.
- Film:Multi-layer laminates hybridize with copper-clad substrates for flexible printed circuit applications. Taiwan-based foldable smartphone OEMs are qualifying these structures for hinge interconnects at compressed 12-month development cycles, pulling formulation innovation toward ultra-low dielectric constant specifications.
- Fiber:High-tenacity filaments serve aerospace cable reinforcement and industrial belting where thermal stability exceeds 300°C. Japanese suppliers anchor capacity for aircraft harness applications.
- Composite:Melt-blended LCP-fluoropolymer compounds occupy niche additive applications requiring combined chemical resistance and dimensional stability. Medical device fabricators in Germany specify these for surgical instrument handles facing REACH aromatic amine compliance.
- Powder:Fine-ground grades enable compression molding of thick-walled electrical insulators and sintered filter media. Chinese compounders source powder for specialty composite blending with minimal technical service overhead.
Resin commands volume leadership through connector housing applications; film is expanding most quickly via smartphone substrate adoption.
Application:
Cost tier stratification separates high-specification telecommunications grades from commodity industrial machinery compounds, with aerospace and automotive occupying intermediate premium positions.
- Telecommunications Equipment:Millimeter-wave antenna substrates and high-frequency connectors demand ultra-low dielectric constant formulations. 5G infrastructure deployment in South Korea and Taiwan is compressing resin supplier development cycles to 12-month qualification timelines.
- Consumer Electronics:Foldable smartphone flexible circuits and laptop hinge components absorb expanding film-grade capacity. Japanese OEMs specify halogen-free V-0 rated compounds under METI JIS flame-retardant standards.
- Automotive Components:Under-hood sensors and electric vehicle charging inlets require thermal cycling resistance above 150°C continuous service. German vehicle assemblers specify REACH-compliant grades for sensor housings.
- Aerospace Components:Aircraft interior brackets and avionics enclosures leverage LCP's flame-smoke-toxicity profile. FAA certification timelines extend 18-24 months for new grade qualifications.
- Industrial Machinery:Pump seals and valve components exploit chemical resistance to hydrocarbons and acids. Chinese heavy equipment makers drive volume through standardized injection-molded geometries with minimal formulation customization.
Telecommunications equipment generates the steepest margin premiums; consumer electronics delivers the fastest volume expansion.
Technology:
Processing method selection correlates directly with part geometry complexity and production scale, with injection molding and extrusion commanding the installed equipment base.
- Injection Molding:Precision connector housings and miniature electronic components dominate throughput. Hardened screw and barrel configurations handling 300°C+ melt temperatures elevate capital barriers for new entrants.
- Extrusion:Film and fiber production lines in Japan and Taiwan supply flexible circuit substrates and high-tenacity filaments. Continuous processing enables scale economies that compression molding cannot match.
- Lamination:Multi-layer copper-clad substrate architectures enable finer pitch flexible circuits. South Korean smartphone OEMs qualify these for foldable hinge interconnects.
- Coating:Thin-film deposition on metal substrates creates hermetic barriers for sensor protection. Medical device applications in China face NMPA migration testing protocol convergence with EU MDR standards.
- 3D Printing:Fused filament fabrication of prototype electrical housings and custom jigs remains experimental. Powder bed fusion struggles with LCP's ordered mesophase structure and anisotropic shrinkage.
Injection molding anchors production volume; lamination is gaining share fastest through flexible circuit hybridization.
End User Industry:
Customer concentration patterns split between consolidated electronics manufacturing services and fragmented industrial equipment fabricators, dictating contract structure and pricing leverage.
- Electronic Manufacturers:Taiwan and South Korea-based manufacturing services consolidate purchase authority for connector and substrate applications. Direct resin-to-fabricator contracting is displacing distributor-mediated procurement in high-volume programs.
- Communication Providers:5G network equipment vendors in South Korea co-develop customized LCP grades with resin suppliers for base station antenna modules. Multi-year supply agreements lock in formulation exclusivity.
- Aerospace Fabricators:Tier-1 aircraft interior suppliers in Germany and France specify REACH and EASA-compliant grades for cabin electronics. Certification burden limits supplier switching.
- Vehicle Assemblers:Electric vehicle platforms in Germany and China integrate LCP sensors and charging components. Dual carbon goals in Beijing accelerate polymerization process efficiency investments.
- Heavy Equipment Makers:Chinese and Indian construction machinery producers specify standard-grade compounds for hydraulic sensor housings. India's PLI scheme incentives are attracting localized connector fabrication.
Electronic manufacturers command the largest procurement volumes; communication providers are consolidating supply relationships fastest through co-development partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals are accelerating polymerization process efficiency investments while India's PLI scheme attracts connector fabricators seeking localized resin supply. Japan's METI enforces stringent JIS flame-retardant standards that reshape formulation requirements for telecommunications-grade compounds. South Korea and Taiwan anchor electronics manufacturing demand through concentrated injection molding capacity.
China
Electric vehicle platforms and 5G base station deployments absorb expanding resin volumes for sensor housings and antenna modules. GB standards on halogen-free flame-retardant classifications tighten compound specifications under NMPA oversight. Yangtze River Delta chemical clusters in Shanghai and Jiangsu province host polymerization assets serving domestic connector fabricators.
Japan
High-tenacity fiber production for aircraft harness applications and ultra-low dielectric constant film development for millimeter-wave substrates drive specialty grade demand. METI enforces JIS C 3005 flame-retardant classifications that eliminate brominated additives from telecommunications compounds. Kanto region chemical producers in Tokyo and Kanagawa prefecture supply precision-molding resins to domestic electronics OEMs.
South Korea
Foldable smartphone OEMs qualify multi-layer LCP film laminates for hinge interconnects at compressed development cycles. MFDS alignment with EU MDR migration testing protocols elevates certification burdens for medical device grades. Seoul Capital Area manufacturing services consolidate procurement authority through direct mill contracts locking in viscosity consistency guarantees.
Taiwan
Electronics manufacturing services consume bulk resin volumes for high-frequency connector housings and flexible printed circuit substrates. REACH aromatic amine restrictions reshape import compliance requirements for European-sourced medical device grades. Hsinchu Science Park and Tainan technology corridors concentrate injection molding capacity serving global telecom equipment vendors.
United States
Aerospace fabricators specify FAA-certified grades for aircraft interior brackets and avionics enclosures with extended qualification timelines. FDA regulates LCP grades intended for medical device housings and surgical instrument handles. South Carolina compounding assets anchor North American supply chains for automotive sensor and electric vehicle charging component applications.
Global Liquid Crystal Polymer (LCP) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated polymerization-to-compounding capabilities that lock in high-frequency connector contracts. Japanese and North American chemical conglomerates dominate resin production while specialized compounders occupy niche formulation tiers. Three archetypes define competitive positioning: integrated resin-film extruders, captive compounding specialists, and regional custom compounders. Capacity expansion and direct manufacturer engagement represent the dominant competitive moves as distributors face displacement.
Within the integrated chemical conglomerate tier, Toray Industries, Celanese Corporation, and Sumitomo Chemical Co., Ltd. exemplify backward control over polymerization and downstream processing. These entities occupy positions where captive supply of aromatic diacid feedstocks and in-house film extrusion capabilities create formulation exclusivity in millimeter-wave substrate programs. RTP Company represents the specialized compounding archetype, sitting within a tier that serves medical device and industrial machinery segments requiring customized viscosity grades. Polyplastics Co., Ltd. anchors the Asia-Pacific regional supply vector, reflecting concentration patterns among Japanese resin producers with established electronics manufacturing relationships.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Kuraray Co., Ltd. |
| Celanese Corporation |
| Ueno Fine Chemicals Industry, Ltd. |
| RTP Company |
| Polyplastics Co., Ltd. |
| Solvay S.A. |
| Mitsubishi Chemical Group |
| Sumitomo Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta polymerization clusters in Shanghai and Jiangsu province concentrate aromatic diacid feedstock processing, translating upstream capacity control into downstream pricing leverage for telecommunications-grade resin suppliers serving South Korean connector fabricators.
Pricing Analysis
Certification level (FDA/REACH/METI JIS-grade) creates the primary spread between premium telecommunications compounds and standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects lot-to-lot viscosity consistency guarantees demanded by Taiwan electronics manufacturing services. Cost compression in standard-grade resin is intensifying because Chinese heavy equipment makers consolidate procurement around undifferentiated injection-molding compounds. Medical device fabricators in Germany exhibit least price sensitivity due to REACH aromatic amine compliance requirements and extended recertification timelines.
Supply Chain Analysis
Foxconn and Pegatron manufacturing services in Taiwan hold concentrated flexible printed circuit substrate capacity, locking in multi-year resin supply agreements through direct mill contracts. Feedstock supply draws from Japanese aromatic diacid producers and Chinese hydroxybenzoic acid intermediates suppliers, creating single-source vulnerability around monomer inputs. Distribution runs through direct resin-to-fabricator channels that displace traditional distributor layers in high-volume connector applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
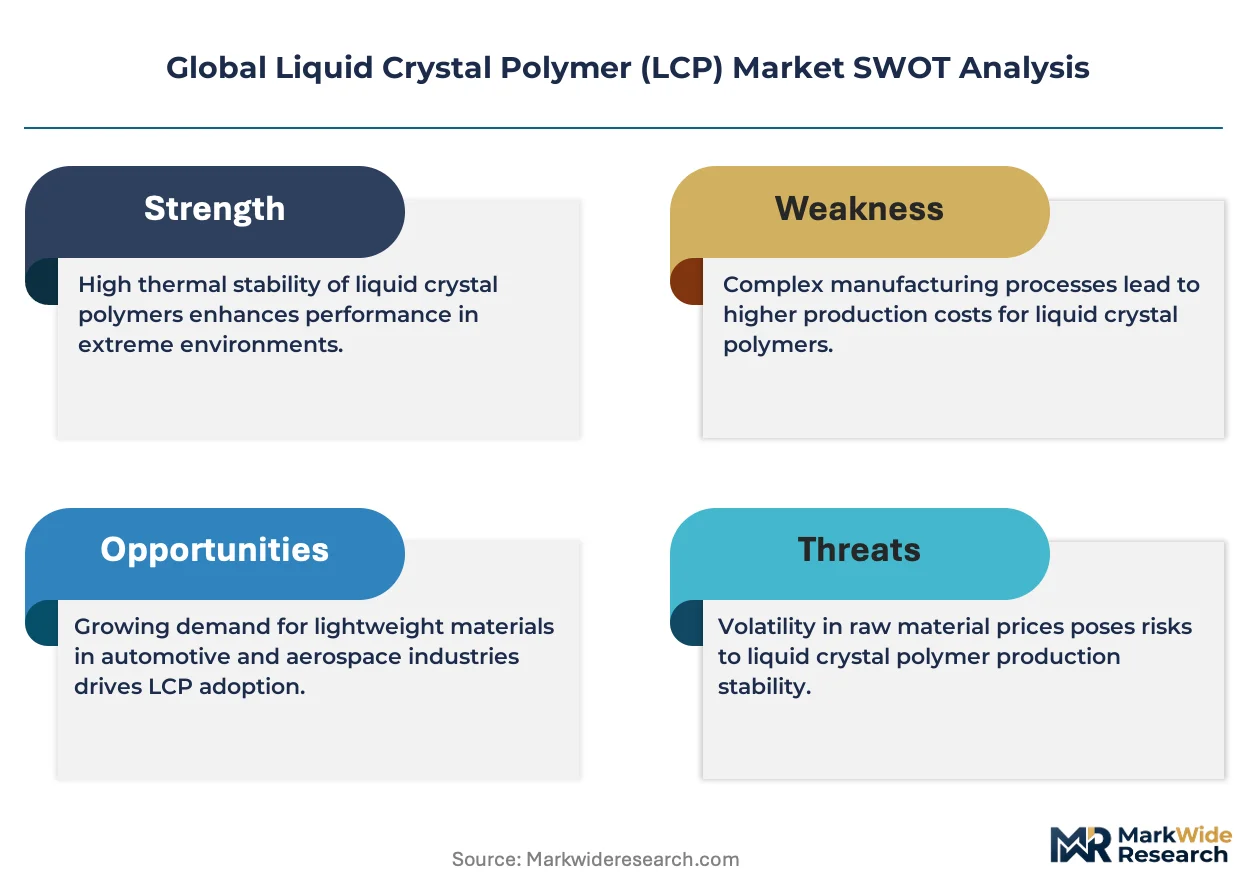
Fluoropolymer substitution in high-frequency signal transmission threatens incumbent positioning, forcing aromatic thermoplastic suppliers to defend formulation exclusivity through dielectric performance differentiation.
For Market Incumbents: Build formulation co-development moats through captive polymerization assets and locked-in viscosity calibration services at customer sites. Anchor backward integration into aromatic diacid feedstocks to secure input cost control against Japanese and Chinese monomer concentration. Defend against PTFE and PFA substitution by accelerating ultra-low dielectric constant R&D for millimeter-wave antenna substrates. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing corridors represent the most penetrable entry point for localized resin supply to emerging connector fabricators. Medical device migration testing compliance in China under converging NMPA-EU MDR protocols offers premium positioning for specialty compounders with aromatic amine-free formulations. Go-to-market leverage rests on technical service partnerships with regional injection molding equipment distributors. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because direct manufacturer engagement is compressing distributor-mediated procurement and concentrating margin capture with integrated resin-film extruders. Target compounders with captive polymerization assets and established electronics manufacturing relationships in East Asian clusters. Monitor 5G infrastructure deployment cadence in South Korea and Taiwan as volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Diacid Feedstocks | Captive monomer supply insulates Japanese and Chinese compounders from input volatility and secures cost position. |
| Multi-layer Film Lamination Capacity Expansion | South Korean smartphone OEMs qualify hybrid copper-clad substrates for foldable hinge interconnects at compressed cycles. |
| REACH Aromatic Amine Compliance Reformulation | European resin producers gain first-mover advantage in medical device housings through polymerization pathway redesign. |
| Direct Mill Contracting with Electronics Manufacturing Services | Taiwan and South Korea procurement consolidation demands lot-to-lot viscosity consistency guarantees. |
| Dual Carbon Process Efficiency Investment | Beijing's energy-intensive industry restrictions accelerate polymerization unit carbon intensity reduction. |
Research Methodology
Cross-validation between polymerization plant manager interviews and customs/trade data anchors the qualitative findings on feedstock concentration patterns. Primary fieldwork with technical R&D directors at resin compounders, procurement leads at South Korean connector fabricators, and distribution channel partners in East Asian electronics clusters combined with secondary validation through SEC 10-K filings, Cefic chemical industry reports, and METI JIS standard documentation. Bottom-up tonnage estimates triangulate against top-down value projections.
Calibration against historical grade-level pricing and regional production hub capacity utilization informs the analytical framework across the analysis window. Segmentation dimensions modeled include product form (resin, film, fiber, powder), application vertical (telecommunications equipment, consumer electronics, automotive components, aerospace, industrial machinery), and end-use industry procurement concentration. CAGRs derive from elasticity-adjusted demand projections incorporating 5G infrastructure deployment intensity and foldable smartphone substrate adoption curves.
Practitioners should monitor fluoropolymer substitution rates in high-frequency applications and REACH aromatic amine restriction enforcement timelines for early signals of forecast revision. Assumptions reflect current regulatory trajectories and electronics manufacturing cluster expansion plans. Quarterly review of millimeter-wave antenna substrate qualification cycles and dual carbon policy implementation in Beijing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Circular Polymers Market