
 Global Linear Alpha Olefins Market | 2026-2036
Global Linear Alpha Olefins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Alpha Olefins Market Foresight
A shift from single-source ethylene feedstock contracts toward multi-source arrangements is repositioning procurement strategy across the value chain. Chevron Phillips Chemical leverages captive Gulf Coast ethylene supply to sustain cost-advantaged 1-hexene output. Sasol anchors its position through Fischer-Tropsch integration in South Africa, while INEOS Oligomers competes via European oligomerization scale and flexible product slates.
Linear alpha olefins are unbranched hydrocarbons with terminal double bonds, typically produced through ethylene oligomerization or Fischer-Tropsch synthesis, serving primarily as comonomers for polyethylene density control and as intermediates for surfactants and lubricants. 1-Hexene and 1-Octene dominate volume flows into polyethylene production, where margin pools concentrate with metallocene catalyst compatibility and tight purity specifications. Synthetic detergents and surfactants represent the fastest-growing application vector, as C10-C14 fractions gain formulation share in concentrated liquid and powder products across Asian and European consumer markets.
The EPA regulates volatile organic compound emissions from olefin production facilities in the United States, while REACH and the EU Green Deal constrain carbon intensity disclosures and chemical hazard classifications for European imports. China's MEE enforces dual carbon goals that tighten energy efficiency benchmarks for ethylene oligomerization capacity additions. Stakeholders must monitor feedstock cost divergence between naphtha and ethane routes, as this spread determines regional competitiveness and capital allocation for new alpha olefin trains.
Market Dynamics
Ethylene oligomerization technology advances are compressing conversion costs and redistributing margin pools toward producers with integrated feedstock positions, forcing asset-light competitors to renegotiate long-term offtake terms or exit higher carbon number grades.
Growth Catalysts
- REACH biodegradability mandates:European detergent formulators are substituting branched surfactants with linear C10-C14 alpha olefins to meet the EU Green Deal's chemical hazard classification thresholds, tightening purity specifications across the supply chain.
- Metallocene catalyst diffusion:Polyethylene producers in South Korea and Saudi Arabia are expanding 1-hexene and 1-octene consumption to manufacture differentiated LLDPE grades for flexible packaging applications.
- Fischer-Tropsch integration:South African and Qatari producers leverage stranded gas assets to supply wax-range olefins for synthetic lubricant base stocks, capturing premium pricing in industrial fluid formulations.
Market Restraints
- Ethane-naphtha cost divergence:Gulf Coast ethane advantage versus European and Asian naphtha crackers creates persistent margin compression for non-integrated oligomerization units in Rotterdam and Singapore.
- Supply concentration in 1-octene:Four producers control over seventy percent of high-purity 1-octene capacity, exposing downstream polyethylene compounders to allocation risk during unplanned outages.
- EPA VOC emission ceilings:Olefin production facilities in Texas and Louisiana face tightening volatile organic compound permits that limit debottlenecking projects without carbon capture retrofits.
Strategic Opportunities
- India's PLI scheme for chemicals:Domestic polyethylene capacity additions under the Production Linked Incentive framework will require captive 1-butene and 1-hexene supply currently met through imports.
- Convergence of bio-ethylene and oligomerization:Brazilian sugarcane-derived ethanol-to-ethylene routes are expanding into alpha olefin production for certified renewable surfactant formulations targeting European consumer goods multinationals.
- Direct-to-compounder digital platforms:Specialty chemical distributors are building e-procurement portals that bypass traditional merchant intermediaries for C6-C10 grades in North American automotive polymer compounds.
Industry Challenges
- Process control engineering scarcity:Ethylene oligomerization units require specialized expertise in high-pressure reactor management and selective catalyst recovery systems that few technical training programs currently address.
- Metallocene patent thickets:Licensing negotiations with catalyst technology holders are extending project timelines for new polyethylene trains, delaying synchronized alpha olefin offtake agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Alpha Olefins Market |
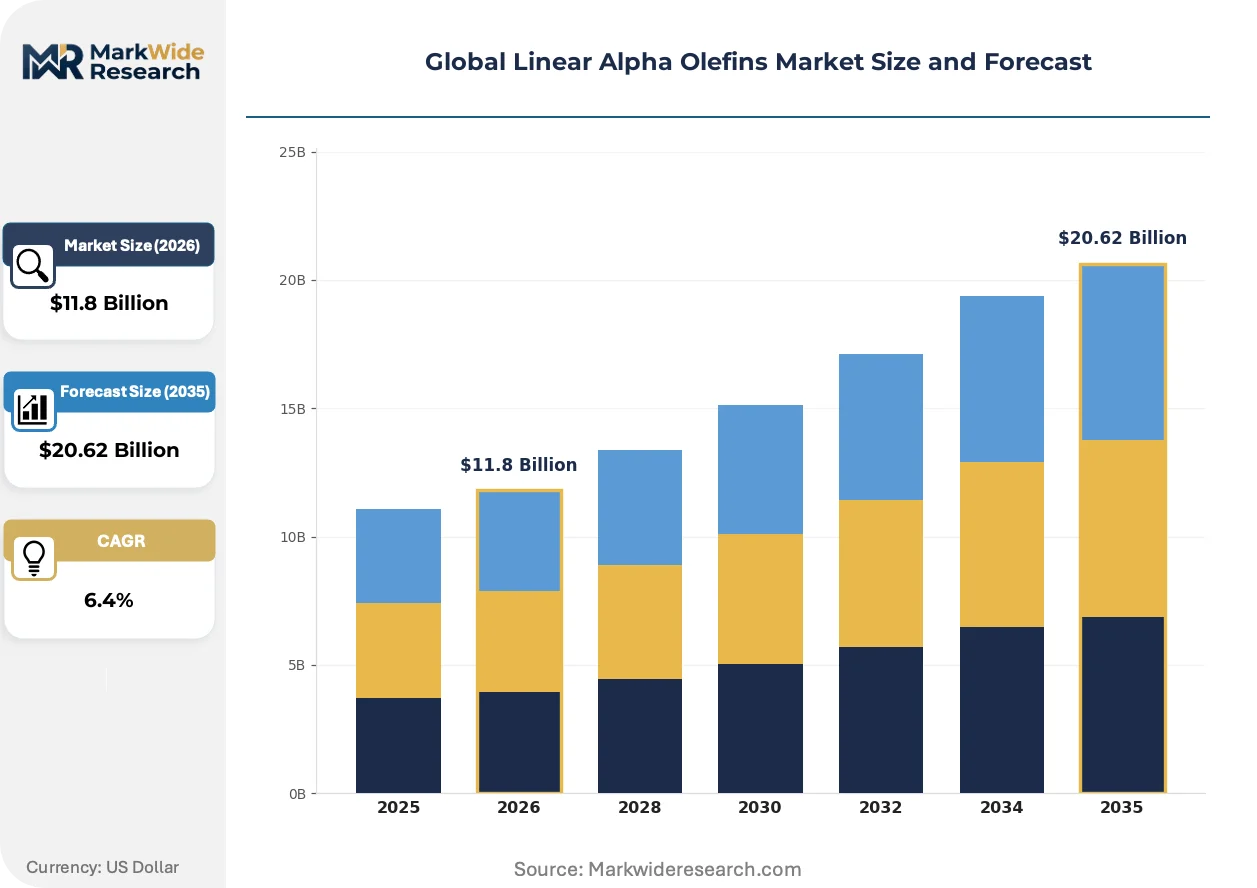
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1-Hexene, 1-Octene, 1-Decene, 1-Dodecene, 1-Tetradecene, 1-Hexadecene Technology: Ethylene Oligomerization, Fischer-Tropsch Synthesis, Shell Higher Olefin Process, Ethylene Thermal Cracking, Catalytic Process, Metathesis Application: Polyethylene Production, Synthetic Detergents, Plasticizers, Rubber Chemicals, Lubricants, Surfactants End User Industry: Polymer Manufacturers, Specialty Chemicals Producers, Lubricant Suppliers, Detergent Makers, Rubber Processors, Coating Companies |
| Companies Covered | ExxonMobil Chemical, Sasol, Chevron Phillips Chemical, Mitsubishi Chemical, Qatar Chemical Company, Shell Chemicals, SABIC, Evonik Industries, INEOS Oligomers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Alpha Olefins Market Shifts & Advancements
Digital process control and molecular sieve separation technologies are tightening product slate flexibility, enabling producers to pivot between carbon number distributions in response to real-time polyethylene comonomer differentials rather than running fixed product mixes.
Advanced membrane separation systems for 1-hexene purification are expanding into metallocene-grade specification markets previously served by energy-intensive extractive distillation. South Korean and Thai polyethylene compounders are adopting these units to secure lower-carbon-intensity comonomer certificates for export shipments to European converters. The technology is expanding into smaller-scale modular installations that reduce minimum efficient scale thresholds for regional producers.
China's MEE dual carbon enforcement is tightening energy efficiency benchmarks for new ethylene oligomerization capacity, requiring heat integration designs that recover reaction exotherm for downstream separation duties. Domestic engineering firms are retrofitting existing trains with organic Rankine cycle power recovery systems to avoid production caps. The policy is accelerating consolidation among independent olefin merchants in Shandong and Jiangsu provinces unable to fund compliance upgrades.
Polyethylene producers are consolidating comonomer procurement under single-source framework contracts with volume-flexibility clauses, displacing spot market purchases that dominated the 2015-2020 period. This concentration of buying power is compressing merchant alpha olefin margins in the C6-C8 range. The shift is most visible among Southeast Asian integrated petrochemical complexes seeking supply security amid ethylene feedstock volatility.
Global Linear Alpha Olefins Market Segmentation
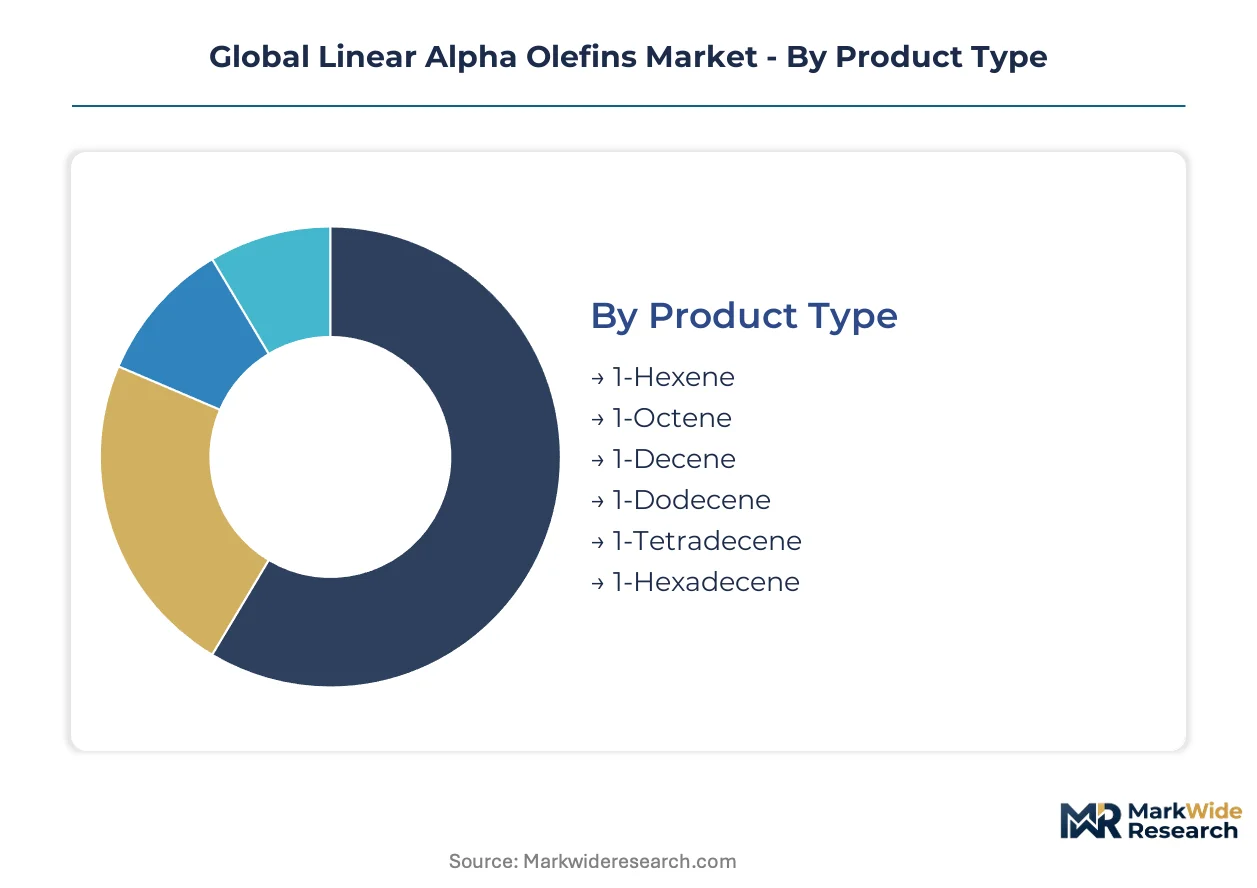
Linear alpha olefin producers configure asset slates around carbon number selectivity and feedstock integration economics. Segmentation reveals where margin pools concentrate and which technology routes face displacement pressure from regulatory tightening on carbon intensity disclosures.
Product Type:
Supply concentration in C6 and C8 grades has compressed merchant margins and elevated purity premiums for metallocene-compatible specifications.
- 1-Hexene:The lightest commercially significant comonomer, 1-hexene enables linear low-density polyethylene with density reduction to 0.918 g/cm³. Demand concentrates with South Korean and Saudi Arabian polyethylene compounders expanding flexible packaging capacity for food-contact applications.
- 1-Octene:Four producers control dominant shares of high-purity 1-octene, creating allocation vulnerability for downstream compounders during unplanned outages. The grade commands the steepest purity premiums for metallocene catalyst systems requiring sub-50 ppm impurity thresholds.
- 1-Decene:Intermediate carbon number serving surfactant and synthetic lubricant base stock formulations with growing traction in European REACH-compliant detergent applications.
- 1-Dodecene:Primary feedstock for biodegradable surfactant production under EU Green Deal chemical hazard classifications.
- 1-Tetradecene:Wax-range olefin capturing premium pricing in industrial lubricant formulations from Qatari Fischer-Tropsch integration.
- 1-Hexadecene:Heavy fraction supplying specialty lubricant and coating additive markets with limited merchant availability outside integrated Fischer-Tropsch operations.
Today's leader: 1-Hexene. Tomorrow's challenger: 1-Octene.
Technology:
Cost tier differentiation separates integrated feedstock holders from merchant operators exposed to ethylene price volatility.
- Ethylene Oligomerization:Dominant commercial route employing homogeneous or heterogeneous catalyst systems to chain-growth ethylene into even-numbered alpha olefins. Gulf Coast producers leverage captive ethane-to-ethylene integration to sustain cost advantage over naphtha-crack competitors in Rotterdam and Singapore.
- Fischer-Tropsch Synthesis:Sasol and Qatari operators exploit stranded gas assets to produce broad-spectrum olefin slates including odd and even carbon numbers unavailable from ethylene routes. The technology captures wax-range premiums for synthetic lubricant base stocks.
- Shell Higher Olefin Process:Proprietary oligomerization technology yielding internal olefin byproducts requiring secondary isomerization for alpha olefin recovery.
- Ethylene Thermal Cracking:Legacy high-temperature pyrolysis route with elevated energy intensity facing displacement from catalytic alternatives.
- Catalytic Process:Emerging selective oligomerization variants targeting improved 1-hexene and 1-octene selectivity through modified zirconium or nickel catalyst systems.
- Metathesis:Displacement route converting internal olefins to terminal positions, gaining niche application in bio-ethylene derived feedstock processing.
Integrated ethylene oligomerization commands current margin pools. Fischer-Tropsch expansion is climbing the fastest.
Application:
Application mix determines exposure to polyethylene cycle volatility versus surfactant defensive demand.
- Polyethylene Production:Comonomer consumption for density control in LLDPE and HDPE grades absorbs the majority of 1-hexene and 1-octene volume. Metallocene catalyst diffusion in South Korea and Saudi Arabia is expanding specification tightening for ultra-low density packaging films.
- Synthetic Detergents:C10-C14 fractions are gaining formulation share in concentrated liquid and powder products across Asian and European consumer markets. REACH biodegradability mandates are redirecting demand from branched surfactants toward linear alpha olefin derivatives.
- Plasticizers:Internal olefin derivatives serving PVC flexibility modification with pressure from phthalate regulatory restrictions in multiple jurisdictions.
- Rubber Chemicals:C6-C8 olefins in synthetic rubber polymerization and vulcanization accelerator production.
- Lubricants:Polyalphaolefin base stock synthesis from 1-decene and heavier fractions targeting industrial and automotive fluid formulations.
- Surfactants:Ethoxylated and sulfonated derivatives for institutional and consumer cleaning applications with accelerating European substitution mandates.
Polyethylene comonomer demand anchors volume. Synthetic detergent formulations are expanding most quickly.
End User Industry:
Customer concentration in integrated polymer producers is consolidating procurement leverage and compressing merchant alpha olefin margins.
- Polymer Manufacturers:Integrated polyethylene compounders in Saudi Arabia, South Korea, and the United States are consolidating comonomer procurement under single-source framework contracts with volume-flexibility clauses, displacing spot market purchases that dominated earlier periods.
- Specialty Chemicals Producers:Surfactant and lubricant additive formulators requiring C10-C16 fractions with tight bromine index specifications for European export certification.
- Lubricant Suppliers:Synthetic base stock blenders sourcing 1-decene and heavier grades from Fischer-Tropsch integrated producers for industrial fluid formulations.
- Detergent Makers:Consumer goods multinationals reformulating European product lines to meet EU Green Deal chemical hazard classification thresholds through linear surfactant substitution.
- Rubber Processors:Synthetic rubber manufacturers consuming C6-C8 olefins in solution polymerization processes with stable but slower growth trajectories.
- Coating Companies:Niche consumers of C12-C16 fractions for paint and coating additive applications with limited volume scale.
Polymer manufacturers dominate procurement volume. Specialty chemicals producers are gaining pricing power fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage on carbon intensity disclosures is redirecting alpha olefin investment toward jurisdictions with lower compliance costs and stranded gas feedstock advantages. Producers are relocating capacity to exploit these gaps.
United States
Gulf Coast ethane crackers supply captive feedstock to oligomerization units serving polyethylene compounders in Texas and Louisiana. The EPA enforces tightening VOC emission permits that constrain debottlenecking without carbon capture retrofits. Houston Ship Channel concentration hosts integrated producers leveraging cost-advantaged ethane against naphtha-based competitors.
Saudi Arabia
SABIC and joint-venture partners expand 1-hexene and 1-octene output for domestic LLDPE capacity and Asian export markets. The national chemicals regulator aligns product specifications with REACH-equivalent biodegradability thresholds for European-bound surfactant derivatives. Jubail Industrial City clusters ethylene and alpha olefin production with direct pipeline connectivity to Red Sea export terminals.
China
Shandong and Jiangsu provinces consolidate independent olefin merchants unable to fund MEE dual carbon compliance upgrades. The ministry enforces energy efficiency benchmarks requiring heat integration and organic Rankine cycle retrofits on new oligomerization trains. Yangtze River Delta polyethylene producers are consolidating comonomer procurement under single-source framework contracts with volume-flexibility clauses.
Germany
REACH biodegradability mandates redirect detergent formulation demand toward linear C10-C14 grades from merchant suppliers. ECHA chemical hazard classifications constrain branched surfactant imports, tightening purity specifications across the supply chain. Ludwigshafen and Marl industrial complexes anchor European oligomerization capacity with pipeline distribution to Benelux converters.
South Africa
Sasol's Fischer-Tropsch integration exploits domestic coal and stranded gas assets to supply wax-range olefins for synthetic lubricant base stocks. The national petroleum regulator monitors carbon intensity disclosures for export certification to EU markets. Secunda and Sasolburg complexes concentrate odd and even carbon number production unavailable from ethylene routes.
Global Linear Alpha Olefins Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-ethylene and renewable certification vectors. The market consolidates around integrated feedstock holders with captive ethylene or stranded gas positions, compressing margins for merchant operators exposed to spot price volatility. Three archetypes dominate: Gulf Coast ethane-integrated oligomerizers, Fischer-Tropsch gas-to-liquids operators, and European scale players with flexible product slates. Competitive moves concentrate on backward integration into ethylene supply and selective capacity expansion in high-purity C6-C8 grades.
Among ethane-integrated specialists, Chevron Phillips Chemical and ExxonMobil Chemical exemplify the Gulf Coast archetype with captive feedstock positions. Sasol occupies a distinctive position as the leading Fischer-Tropsch integrated producer leveraging coal and gas conversion economics outside conventional ethylene value chains. These three anchors illustrate how feedstock access determines competitive tier placement and margin sustainability.
| Leading Market Players |
|---|
| ExxonMobil Chemical |
| Sasol |
| Chevron Phillips Chemical |
| Mitsubishi Chemical |
| Qatar Chemical Company |
| Shell Chemicals |
| SABIC |
| Evonik Industries |
| INEOS Oligomers |
| Others |
Supply & Pricing Matrix
Ethylene feedstock costs cascade through oligomerization trains into three-tier pricing structure across premium, standard, and economy levels, with Gulf Coast ethane-integrated producers capturing margin advantage over Rotterdam naphtha crackers facing persistent cost divergence.
Pricing Analysis
Input-cost pass-through from ethane-naphtha spreads compresses margins for merchant operators while rewarding integrated producers with captive supply. Price differentiation hinges on metallocene-grade purity thresholds and REACH-compliant certification tiers for European surfactant exports. Pricing pressure stems from polyethylene compounders consolidating procurement under single-source framework contracts with volume-flexibility clauses. Merchant buyers in Southeast Asia exhibit highest price sensitivity, while Fischer-Tropsch integrated producers serving synthetic lubricant base stocks command lowest elasticity.
Supply Chain Analysis
Direct-to-compounder channels handle hyperscale polyethylene producer demand, bypassing traditional merchant intermediaries for C6-C8 grades. Supply concentrates in the United States, Saudi Arabia, and South Africa, with feedstock drawn from Gulf Coast ethane crackers, Jubail Industrial City ethylene integration, and Sasol's Fischer-Tropsch complexes. Raw material dependencies center on ethylene monomer, catalyst systems, and hydrogen for selective hydrogenation. Single-source vulnerability persists in high-purity 1-octene, where four producers control dominant capacity shares. Distribution runs through pipeline networks to integrated polymer complexes and specialty chemical distributors for surfactant formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU REACH biodegradability mandates redirecting detergent formulation demand toward linear C10-C14 grades and tightening purity specifications across derivative supply chains.
For Market Incumbents: Anticipate margin compression from bio-ethylene derived alpha olefins targeting European consumer goods multinationals by securing backward integration into stranded gas assets or ethane supply. Prioritize capacity additions in high-purity 1-octene to defend against allocation risk during unplanned outages, while investing in organic Rankine cycle retrofits to meet China's MEE dual carbon enforcement thresholds.
For New Entrants and Emerging Players: EU REACH in Europe opens a window for certified renewable surfactant formulations through Brazilian sugarcane-derived ethanol-to-ethylene routes, exploiting white-space in biodegradable C12-C14 grades. India's PLI scheme for chemicals presents captive comonomer supply opportunity as domestic polyethylene capacity expands. Target direct-to-compounder digital platforms for C6-C10 automotive polymer compounds in North America.
For Investors and Strategic Acquirers: Consolidation pressure builds where independent olefin merchants in Shandong and Jiangsu provinces face MEE compliance funding gaps. Long-term viability favors Fischer-Tropsch integrated operators with wax-range premium capture and odd-carbon-number slate flexibility. Watch for ethane-naphtha cost divergence persistence as inflection indicator for regional competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive Gulf Coast ethane access sustains cost-advantaged 1-hexene output against naphtha competitors. |
| Green Manufacturing Transition | Bio-ethylene oligomerization routes unlock renewable certification for European surfactant export markets. |
| Capacity Expansion in High-Purity Grades | Metallocene-compatible 1-octene additions address allocation vulnerability among downstream compounders. |
| Long-term Supply Agreement | Single-source framework contracts with volume-flexibility clauses secure polyethylene comonomer offtake. |
| Joint Venture | Fischer-Tropsch partnerships exploit Qatari stranded gas assets for wax-range synthetic lubricant base stocks. |
Research Methodology
Direct dialogue with plant managers, procurement leads at downstream polyethylene OEMs, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and regulatory disclosure databases. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation across the analysis window.
Bottom-up modeling of ethylene oligomerization train economics and Fischer-Tropsch integration costs anchored volume projections, while top-down macro drivers tested scenario boundaries across the projection horizon. Segmentation dimensions included carbon number selectivity, technology route, application mix, and regional production hub. CAGRs derived from iterative reconciliation of supply-side capacity additions with demand-side polyethylene comonomer and surfactant formulation trajectories. Industry-specific inputs incorporated catalyst yield improvements and regulatory compliance cost curves.
Revisions become necessary when ethane-naphtha cost spreads invert, REACH enforcement intensifies beyond baseline assumptions, or MEE dual carbon thresholds accelerate. Forecasts reflect documented assumptions on feedstock availability, catalyst performance, and trade flow configurations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
FT Wax Market