
 Asia-Pacific Flooring Resins Market | 2026-2036
Asia-Pacific Flooring Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flooring Resins Market Insights
Multi-source procurement for specialty isocyanates and epoxy hardeners is realigning supply strategies across the Asia-Pacific Flooring Resins Market. Kansai Paint Co Ltd leverages its Osaka-based R&D campus to sustain formulation leadership in low-VOC polyurethane systems for Japanese automotive plants. Sika AG anchors its regional position through captive production of cementitious screed additives in Thailand, while Akzo Nobel N.V. competes via water-based technology licensing to Southeast Asian distributors.
Asia-Pacific flooring resins comprise thermosetting polymer systems—typically polyurethane with NCO/OH ratios between 1.0 and 1.1, or bisphenol-A epoxy with amine hardeners—applied as protective, decorative, or chemically resistant coatings to concrete substrates in commercial and industrial buildings. Epoxy formulations dominate institutional and heavy industrial applications where chemical resistance and compressive strength above 80 MPa prove essential, while polyurethane leads residential and light commercial segments where flexibility and UV stability matter more. Water-based technology is displacing solvent-based systems fastest in China and Japan as MEE air-quality enforcement tightens, though 100% solid systems capture premium margin pools in pharmaceutical cleanrooms and electronics manufacturing where zero-VOC performance commands specification.
Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS K 6800 standards for flooring material emissions, while China's Ministry of Ecology and Environment (MEE) limits VOC content in architectural coatings under GB 18582. India's BIS certification for epoxy and polyurethane floor coatings creates market-access friction for uncertified imports. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for manufacturing infrastructure reshape resin specification criteria and local-content requirements across the region.
Market Dynamics
China's dual carbon goals are compressing specification timelines for water-based polyurethane and epoxy systems across industrial construction projects, forcing reformulation investments ahead of MEE enforcement waves.
Growth Catalysts
- MEE VOC Limits:China's Ministry of Ecology and Environment restrictions on solvent-based architectural coatings are redirecting specification toward water-based polyurethane and 100% solid epoxy systems in electronics manufacturing facilities.
- India PLI Manufacturing Push:Production-linked incentive schemes for automotive and electronics sectors are accelerating coated floor installations across the Mumbai-Delhi industrial corridor.
- Cold-Chain Infrastructure:Southeast Asian logistics warehouse construction is specifying polyurethane flooring systems with thermal shock resistance for refrigerated storage operations.
Market Restraints
- Specialty Isocyanate Concentration:Supply of MDI and TDI precursors concentrates among Northeast Asian producers, creating input cost volatility for polyurethane formulators.
- BIS Certification Friction:India's Bureau of Indian Standards certification requirements for epoxy and polyurethane floor coatings delay market access for uncertified imports.
- Cementitious Screed Substitution:Lower-cost cementitious flooring systems capture budget-constrained institutional projects where chemical resistance requirements are moderate.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Underpenetrated northern industrial zones around Bac Ninh and Hai Phong offer specification growth as Samsung and Apple suppliers expand production facilities.
- UV-Cured Polyurethane Convergence:Combination of UV curing technology with aliphatic polyurethane chemistry enables rapid-installation systems for operational manufacturing environments.
- Japan JIS K 6800 Alignment:METI emission standards for flooring materials create premium positioning for low-VOC systems in healthcare and pharmaceutical cleanroom applications.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists capable of balancing NCO/OH ratios in moisture-cured polyurethane systems complicates R&D scaling across Southeast Asian operations.
- Substrate Preparation Certification:Concrete moisture testing and surface profile compliance requirements under SSPC and ICRI standards extend project timelines and subcontractor qualification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flooring Resins Market |
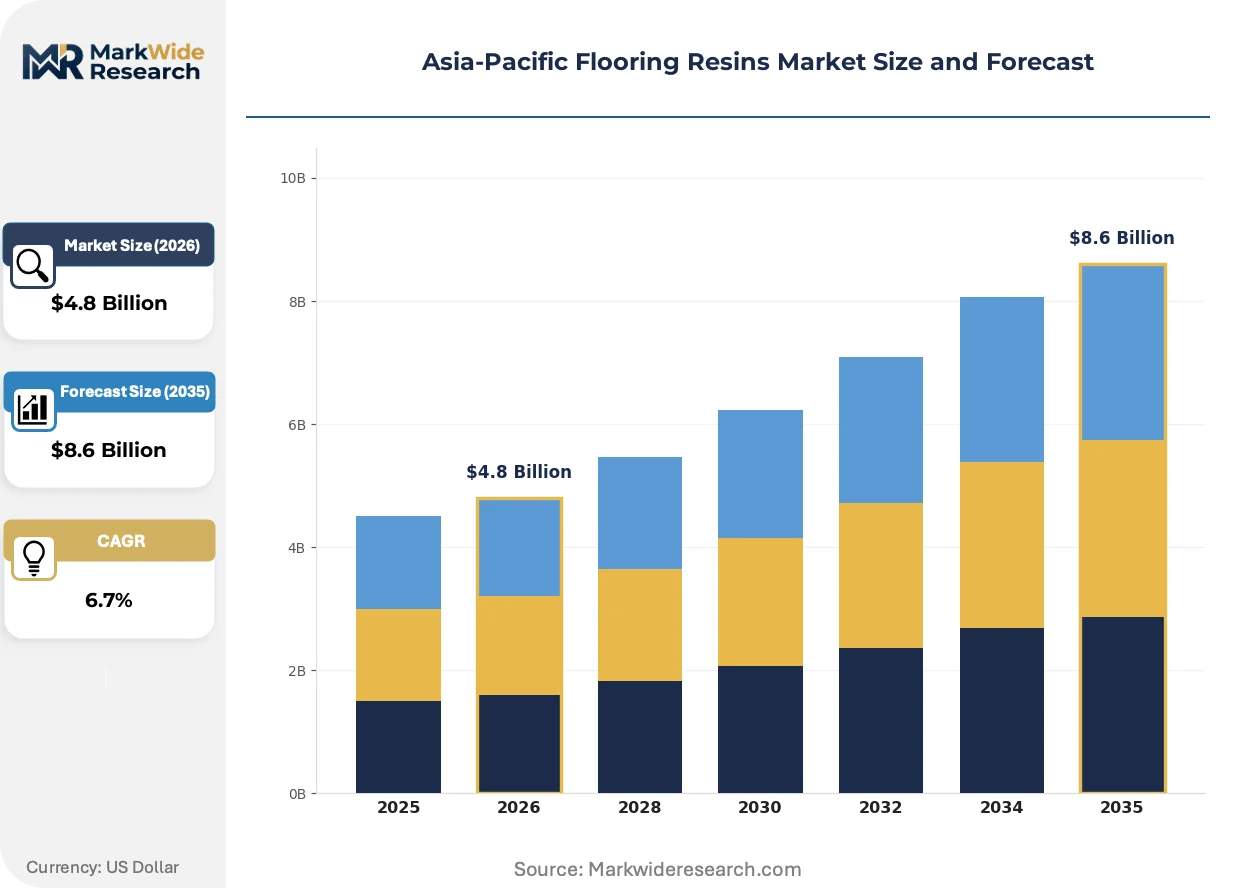
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Polyester Application: Residential, Commercial, Industrial, Institutional Technology: Water-based, Solvent-based, 100% Solid, UV-cured End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | PPG Industries Inc, Kansai Paint Co Ltd, Sika AG, KCC Corporation, Allnex GMBH, The Sherwin-Williams Company, Nippon Paint Holdings Co., Ltd., RPM International Inc., Akzo Nobel N.V., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flooring Resins Market Trends and Innovations
Specification automation and regulatory compression are redefining how resin systems are selected, with digital tools and emission standards converging to accelerate technology turnover across the Asia-Pacific region.
Self-leveling epoxy screed technology with integrated moisture-tolerant primers is automating substrate preparation workflows for industrial flooring contractors. Japanese automotive plants in Toyota City and Yokohama are specifying these systems to compress installation schedules during production line shutdown windows. The technology is automating quality assurance steps previously requiring manual testing protocols, reducing specification risk for facility engineers.
China's GB 18582 standard revisions under MEE authority are tightening VOC content ceilings for architectural coatings applied in commercial buildings. Formulators must recertify product lines or exit the construction specification channel entirely. Water-based polyurethane systems with aliphatic topcoats are capturing premium positioning in Shanghai and Shenzhen commercial developments where air-quality compliance documentation is mandatory.
Asset owner procurement teams are consolidating flooring specification decisions at regional headquarters rather than project sites, compressing distributor influence and technical sales cycles. Southeast Asian general contractors are losing autonomy to specify lower-margin alternatives as multinational logistics operators standardize on pre-approved material lists. This concentration is most visible in Singapore and Johor Bahru cold-storage developments where tenant requirements override local contractor preferences.
Asia-Pacific Flooring Resins Market Segmentation
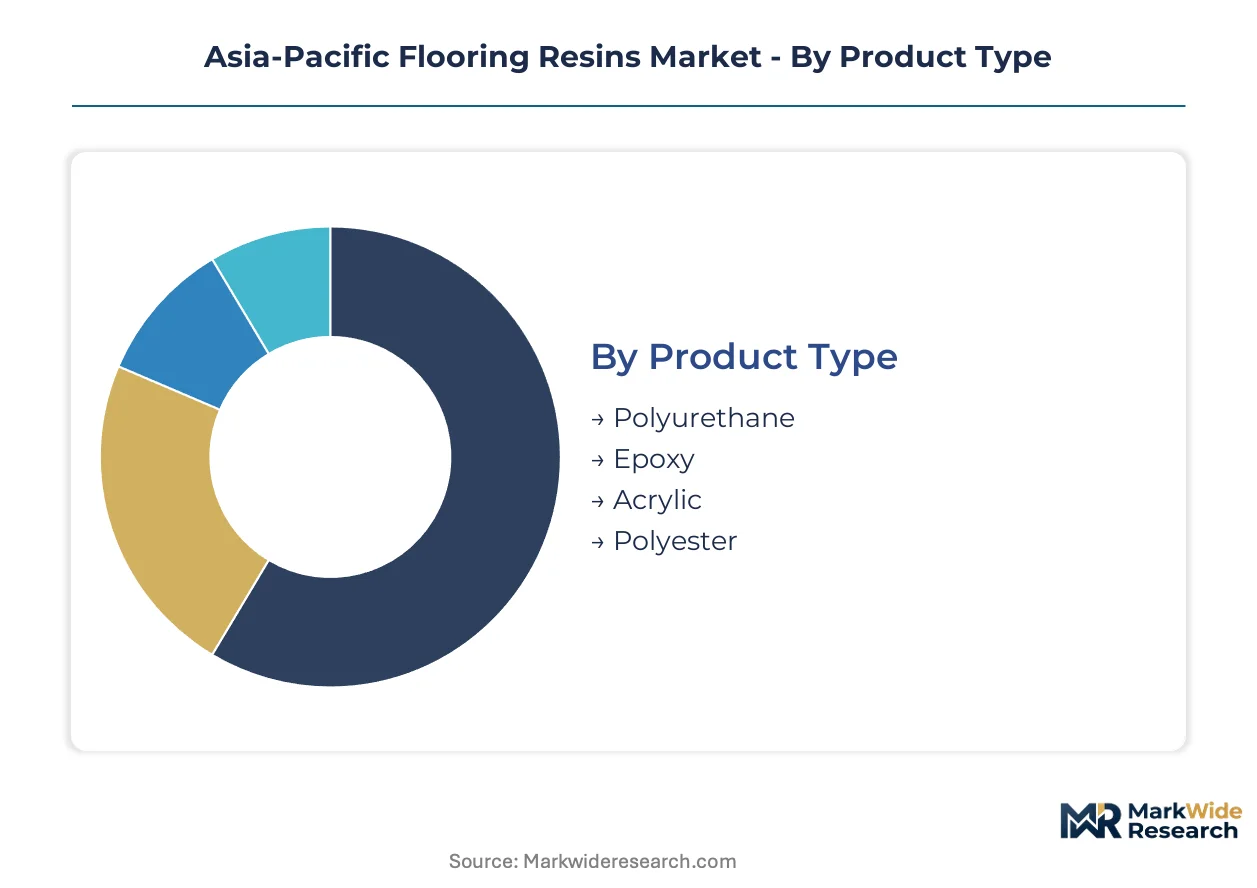
Segmentation in the Asia-Pacific Flooring Resins Market reveals how specification decisions split across performance requirements, regulatory compliance tiers, and installation constraints. Buyers prioritize chemical resistance in pharmaceutical cleanrooms, UV stability in automotive plants, and rapid curing in operational manufacturing environments.
Product Type:
Performance specifications and substrate compatibility drive resin selection across industrial, commercial, and residential construction channels.
- Polyurethane:Aliphatic and aromatic urethane systems formulated with NCO/OH ratios between 1.0 and 1.1 deliver flexibility and abrasion resistance. Demand concentrates in Japanese automotive assembly plants around Toyota City and Yokohama, where METI emission standards under JIS K 6800 mandate low-VOC formulations for cleanroom flooring.
- Epoxy:Bisphenol-A resins cured with amine hardeners achieve compressive strength above 80 MPa and chemical resistance essential for heavy industrial applications. China's electronics manufacturing facilities in Shenzhen and Shanghai specify these systems under MEE VOC enforcement waves, with water-based and 100% solid variants displacing solvent-based alternatives.
- Acrylic:Thermoplastic emulsion systems offering rapid drying and decorative finish options for light commercial environments.
- Polyester:Unsaturated resin formulations with styrene monomers for specialized chemical containment and secondary containment applications.
Volume sits with Epoxy; growth tilts toward Polyurethane.
Application:
End-use environment dictates the trade-off between installation speed, durability, and lifecycle cost in specification decisions.
- Industrial:Heavy-traffic manufacturing floors requiring chemical resistance, thermal shock tolerance, and mechanical load-bearing capacity. Southeast Asian cold-storage warehouses specify polyurethane systems with thermal cycling resistance for refrigerated logistics operations in Singapore and Johor Bahru.
- Commercial:Retail, office, and hospitality spaces where aesthetic finish and rapid return-to-service compress installation schedules. Water-based polyurethane with aliphatic topcoats captures specification in Shanghai and Shenzhen commercial developments where GB 18582 compliance documentation is mandatory.
- Residential:Decorative and protective coatings for concrete substrates in private homes and multi-unit housing.
- Institutional:Healthcare, education, and government facilities balancing durability requirements against constrained capital budgets.
Industrial commands the largest installed base; commercial applications are climbing the fastest.
Technology:
Regulatory compression and project timeline constraints are restructuring technology adoption curves across the region.
- Water-based:Aqueous dispersions of polyurethane and epoxy resins with VOC content below MEE limits for architectural coatings. China's dual carbon goals and GB 18582 standard revisions force reformulation investments ahead of enforcement waves, redirecting specification in electronics manufacturing and commercial construction.
- 100% Solid:Zero-VOC systems applied at high film thickness for pharmaceutical cleanrooms and electronics manufacturing where emission performance commands premium positioning.
- Solvent-based:Traditional formulations facing specification decline as MEE air-quality enforcement tightens in China and Japan.
- UV-cured:Aliphatic polyurethane systems enabling rapid installation in operational manufacturing environments without extended shutdown windows.
Water-based systems hold the broadest specification base; 100% Solid technology is gaining share fastest in premium segments.
End User:
Procurement authority concentration is reshaping channel relationships and technical sales approaches.
- Contractors:Application specialists controlling substrate preparation, installation quality, and final acceptance. Southeast Asian general contractors face eroded autonomy as multinational logistics operators consolidate specification decisions at regional headquarters, standardizing on pre-approved material lists for cold-storage developments.
- Manufacturers:Automotive and electronics producers with in-house facilities engineering teams defining performance specifications. India's PLI scheme for manufacturing infrastructure accelerates coated floor installations across the Mumbai-Delhi industrial corridor for automotive and electronics plants.
- Distributors:Regional stocking intermediaries facing compressed influence as asset owners centralize procurement decisions.
- Retailers:Consumer-facing channels for residential and light commercial DIY applications.
Contractors manage the highest project volume; manufacturers drive the steepest expansion trajectory in specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty isocyanate production clusters in Northeast Asia anchor polyurethane formulation supply across the region. Epoxy hardener manufacturing concentrates in coastal China and South Korea, creating feedstock proximity advantages for flooring resin compounders serving industrial construction corridors.
China
Electronics manufacturing facilities in Shenzhen and Shanghai drive specification of water-based epoxy and 100% solid polyurethane systems. MEE enforcement of GB 18582 VOC limits is forcing reformulation investments ahead of compliance deadlines. The Yangtze River Delta industrial belt hosts the densest concentration of coated floor installations for semiconductor cleanrooms.
Japan
Automotive assembly plants around Toyota City and Yokohama specify low-VOC polyurethane flooring under METI JIS K 6800 emission standards. METI regulations mandate flooring material testing for healthcare and pharmaceutical applications. The Kansai region around Osaka anchors formulation R&D for moisture-cured systems serving precision manufacturing environments.
India
Production-linked incentive schemes for automotive and electronics sectors accelerate coated floor demand across the Mumbai-Delhi industrial corridor. BIS certification requirements for epoxy and polyurethane floor coatings create market-access friction for uncertified imports. Gujarat and Maharashtra host the fastest-expanding automotive manufacturing clusters specifying high-performance resin systems.
South Korea
Electronics manufacturing complexes in Gyeonggi Province and the Seoul Capital Area drive epoxy flooring specification for semiconductor fabrication facilities. National emission standards align with corporate sustainability targets for manufacturing infrastructure. The Busan-Ulsan industrial zone anchors petrochemical feedstock supply for regional resin formulators.
Vietnam
Samsung and Apple supplier expansions in Bac Ninh and Hai Phong industrial zones generate underpenetrated specification opportunities for polyurethane flooring systems. Logistics warehouse construction in northern provinces specifies thermal-shock-resistant coatings for cold-storage operations. The Hai Phong port corridor concentrates foreign manufacturing investment requiring high-performance industrial flooring.
Asia-Pacific Flooring Resins Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach. The vendor base splits between consolidated multinational coating groups and specialized flooring system providers with captive additive production. Three archetypes dominate: integrated coating conglomerates with construction chemicals divisions, regional resin specialists with localized formulation capabilities, and construction chemical pure-plays with captive screed additive manufacturing. Competitive moves concentrate on technology licensing partnerships and backward integration into isocyanate and epoxy hardener supply.
Among Japanese coating groups, Kansai Paint Co Ltd and Nippon Paint Holdings Co., Ltd. exemplify the integrated conglomerate archetype with formulation leadership in low-emission systems. Swiss construction chemical specialist Sika AG anchors the pure-play segment through regional manufacturing of cementitious screed additives. Dutch coatings group Akzo Nobel N.V. represents the technology-licensing model for water-based systems across Southeast Asian distribution channels.
| Leading Market Players |
|---|
| PPG Industries Inc |
| Kansai Paint Co Ltd |
| Sika AG |
| KCC Corporation |
| Allnex GMBH |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Akzo Nobel N.V. |
| Others |
Pricing and Supply Chain Analysis
Multinational logistics operators consolidating specification decisions at regional headquarters extract volume-based discounts that compress distributor margins and force formulators toward project-based pricing with embedded technical service.
Pricing Analysis
Warranty and installation service bundling separates premium polyurethane systems from unbundled commodity epoxy alternatives in competitive tenders. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and VOC compliance tier under MEE and METI standards. Cost compression in water-based formulations is intensifying because reformulation investments ahead of enforcement waves concentrate R&D spending. Budget-constrained institutional buyers exhibit highest price sensitivity, while pharmaceutical cleanroom operators prioritize zero-VOC performance over unit cost.
Supply Chain Analysis
Direct-to-manufacturer channels handle specification for automotive and electronics OEMs with captive facilities engineering teams. Feedstock supply concentrates in China, South Korea, and Japan, where MDI and TDI isocyanate production clusters anchor polyurethane formulation. Epoxy hardener manufacturing draws from bisphenol-A supply chains tethered to coastal Chinese petrochemical complexes. Single-source vulnerability in specialty amine hardeners exposes formulators to input cost volatility. Distribution runs through regional stocking intermediaries serving general contractors in Southeast Asian construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific flooring resins function as a cost-of-compliance market where MEE VOC enforcement under GB 18582 erects formulation recertification barriers that favor incumbents with captive R&D infrastructure.
For Market Incumbents: Lock in specification authority by embedding moisture-tolerant primer technology into self-leveling epoxy screed systems for Japanese automotive shutdown windows. Deepen backward integration into aliphatic isocyanate supply to offset MDI price volatility from Northeast Asian producers. Prioritize BIS certification investment ahead of India's PLI manufacturing acceleration across the Mumbai-Delhi corridor.
For New Entrants and Emerging Players: Launch via technology licensing partnerships with Southeast Asian distributors to bypass captive distribution networks controlled by Sika and Akzo Nobel. Target Vietnam's underpenetrated Bac Ninh and Hai Phong electronics manufacturing zones where Samsung supplier expansions outpace local formulation capacity. Lead with UV-cured polyurethane systems that compress installation schedules for operational manufacturing environments.
For Investors and Strategic Acquirers: The window for entry favors regional resin specialists with localized formulation capabilities and existing METI or BIS certification portfolios. Long-term viability hinges on water-based technology transition completion ahead of regulatory enforcement waves. Watch MEE air-quality inspection intensity in the Yangtze River Delta as the inflection signal for specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | Captive MDI sourcing insulates formulators from Northeast Asian producer pricing volatility. |
| Water-Based Technology Licensing | Akzo Nobel's Southeast Asian distributor partnerships demonstrate scalable low-VOC market entry. |
| BIS Certification Investment | Indian PLI scheme acceleration creates first-mover advantage in automotive flooring specification. |
| UV-Cured System Development | Rapid-installation aliphatic polyurethane captures premium positioning in operational manufacturing environments. |
| Cementitious Screed Additive Manufacturing | Sika's Thailand captive production anchors regional supply for substrate preparation workflows. |
Research Methodology
Independent corroboration across plant managers at Japanese automotive facilities, procurement leads at Chinese electronics OEMs, distribution channel partners in Southeast Asia, and technical R&D directors at regional formulators underwrites the qualitative findings. Secondary validation draws from MEE enforcement bulletins, METI JIS K 6800 testing protocols, BIS certification registries, and customs trade data for isocyanate and epoxy hardener flows. Bottom-up project pipeline assessment and top-down construction spending allocation triangulate volume estimates.
Historical reference periods spanning pre-pandemic baseline through regulatory enforcement acceleration anchor the forecast window. The analytical framework models resin demand across product type, application environment, technology tier, and end-user procurement authority. CAGRs derive from segment-level growth rate synthesis applied to base-year value allocations. Key inputs include MEE inspection intensity projections, PLI scheme disbursement schedules, and cold-storage warehouse construction permits in Singapore and Johor Bahru.
Regulatory enforcement delay, specialty isocyanate supply disruption, and cementitious flooring substitution acceleration are the dominant revision risks. Forecasts reflect assumptions about MEE compliance timeline adherence and PLI manufacturing incentive uptake velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Polyurethane (PU) Foam Market