
 North Sea Offshore Helicopter Services Market | 2026-2036
North Sea Offshore Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Offshore Helicopter Services Market Analytics
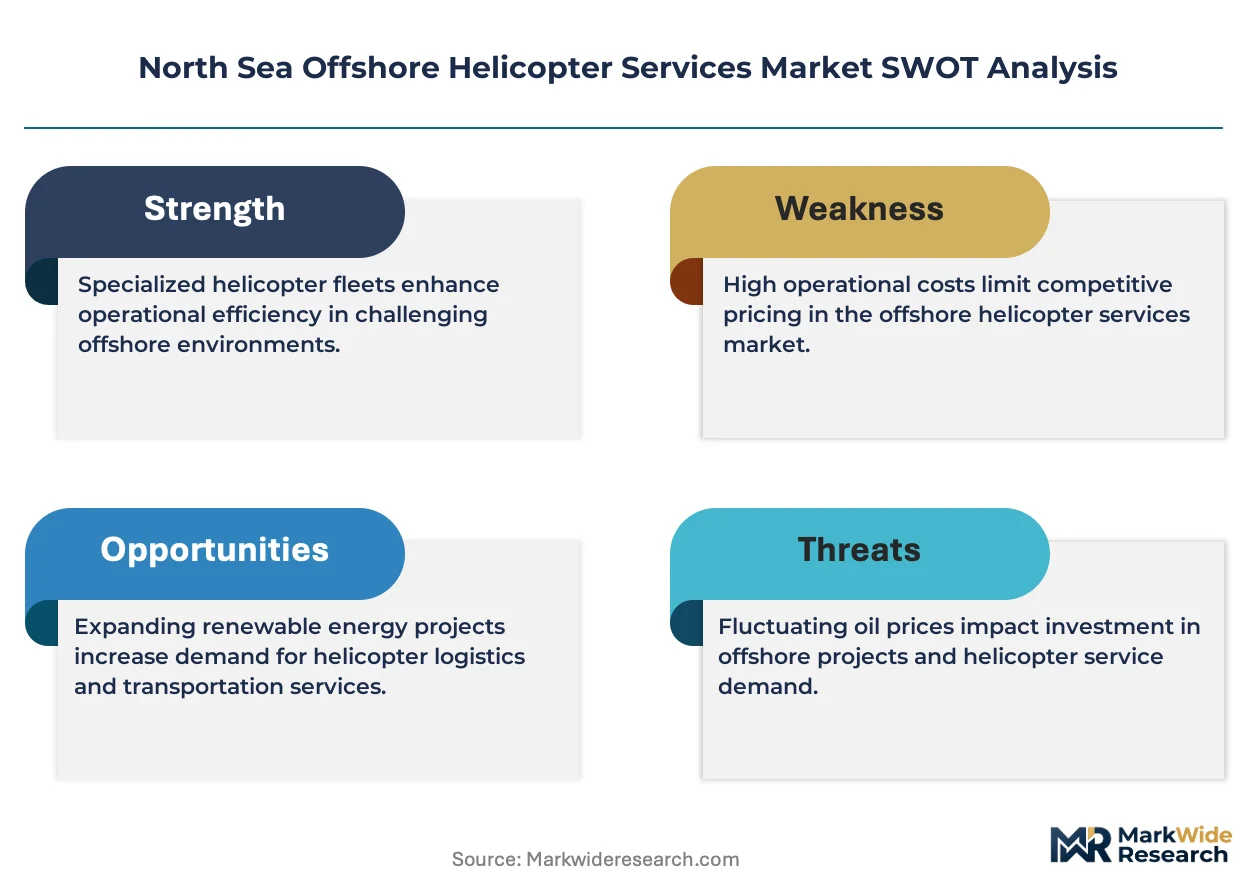
Power-by-the-hour leasing arrangements and asset-light fleet management is reconfiguring competitive entry barriers for mid-sized operators. Bristow Group Inc. leverages its integrated training and maintenance infrastructure to sustain contract renewals with supermajor oil producers. CHC Helicopter anchors its position through long-term crew-transport agreements covering Danish and Norwegian sectors. WIKING Helikopter Service GmbH specializes in emergency medical services, differentiating through SAR-certified night-flight capabilities.
North Sea offshore helicopter services encompass rotorcraft operations supporting energy infrastructure personnel and cargo movement across marine environments, typically employing twin-engine helicopters rated for instrument flight rules and equipped with automatic flotation systems. These operations function as critical logistics arteries connecting onshore bases to fixed and floating offshore platforms operating beyond conventional vessel range. Personnel transfer services dominate contracted revenue volumes, reflecting the persistent need for daily crew rotations across hundreds of active installations. Heavy lift helicopters represent the fastest-growing aircraft category, driven by turbine transport demands at offshore wind construction sites. Scheduled services maintain the most stable margin pools through multi-year framework agreements with oil and gas majors.
The European Union Aviation Safety Agency mandates instrument flight rules and offshore approach minima that directly shape fleet composition and pilot certification requirements. Norway's Civil Aviation Authority enforces additional health and safety standards through its offshore helicopter regulations, influencing equipment specifications for operators serving Norwegian continental shelf installations. The UK's Civil Aviation Authority maintains comparable oversight through its CAP 1145 framework governing offshore public transport operations. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and assess their implications for fleet renewal timelines and alternative fuel certification pathways.
Market Dynamics
The EU Green Deal's emissions standards are compressing fleet renewal timelines across North Sea operators, forcing capital deployment toward alternative fuel certification pathways and hybrid-electric rotorcraft platforms before conventional airframe depreciation cycles conclude.
Growth Catalysts
- EU Green Deal mandates:Binding emissions targets for offshore transport services are accelerating operator investment in fuel-efficient twin-engine platforms and sustainable aviation fuel infrastructure.
- Offshore wind construction:Turbine installation crews at Danish and German North Sea sites require heavy-lift helicopter capacity that legacy offshore oil fleets cannot economically supply.
- Norwegian continental shelf activity:Sustained exploration drilling and platform maintenance rotations generate contracted daily crew transport volumes exceeding other North Sea jurisdictions.
Market Restraints
- Airframe supply concentration:Twin-engine offshore-certified helicopter production concentrates with Airbus Helicopters and Leonardo, creating delivery backlogs extending 18-24 months for IFR-equipped H175 and AW139 variants.
- Pilot certification scarcity:EASA's instrument flight rules and offshore approach minima require specialized training syllabi that European flight schools cannot scale to match fleet expansion rates.
- Jet-A fuel price volatility:Helicopter operators lack fuel hedging instruments at contract tenors matching their multi-year framework agreements with oil majors.
Strategic Opportunities
- Danish offshore wind zones:Anholt and Kriegers Flak construction phases lack dedicated heavy-lift helicopter infrastructure, creating first-mover positioning for operators with SAR-certified night-flight capabilities.
- Power-by-the-hour leasing:Asset-light fleet management models allow mid-sized operators to access newer-generation airframes without balance-sheet capitalization requirements.
- Sustainable aviation fuel blending:EU ReFuelEU Aviation mandates create offtake certainty for SAF producers, enabling operators to secure long-term supply contracts at stabilized premiums over conventional jet fuel.
Industry Challenges
- Automatic flotation system recertification:EASA offshore public transport mandates require periodic airworthiness demonstrations that ground aircraft during peak seasonal demand windows.
- Maintenance technician pipeline:Composite rotor blade repair and avionics integration skills concentrate with OEM-authorized facilities, constraining in-house maintenance scaling for independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Offshore Helicopter Services Market |
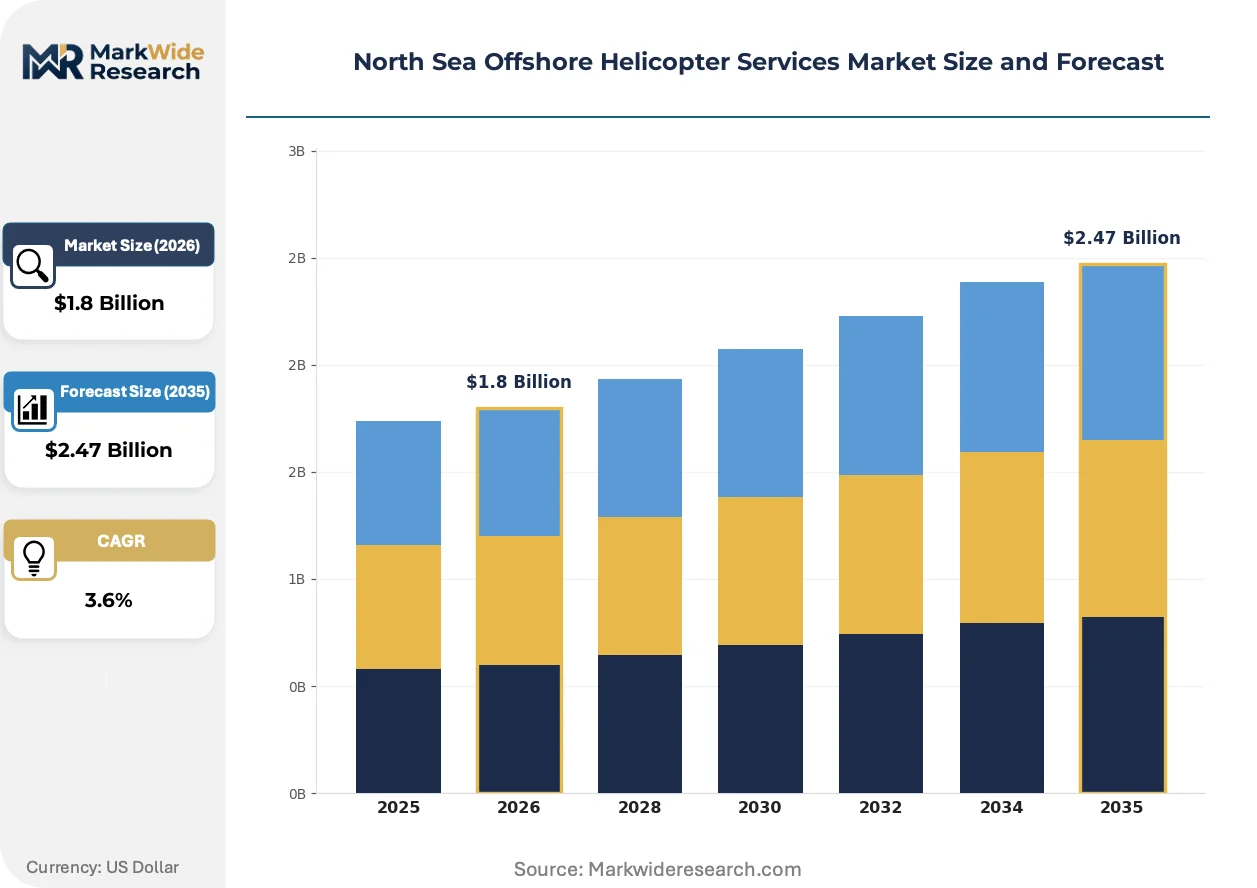
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.47 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Emergency Medical Services, Personnel Transfer, Cargo Transport End User: Oil & Gas Companies, Renewable Energy Operators, Engineering Firms, Government Agencies Aircraft Type: Light Helicopters, Medium Helicopters, Heavy Lift Helicopters, Specialized Aircraft Operational Model: Scheduled Services, Ad-Hoc Services, Charter Services, Contracted Operations |
| Companies Covered | NHV Group, WIKING Helikopter Service GmbH, Bristow Group Inc., Heli Holland, NSEG, CHC Helicopter, HeliService International GmbH, DRF Luftrettung, Babcock International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Offshore Helicopter Services Market Evolving Landscape
Technology migration and regulatory compression are reconfiguring competitive positioning across North Sea helicopter services, with operational capabilities separating contract winners from framework agreement casualties.
Hybrid-electric propulsion architectures are migrating from experimental demonstrators to commercial certification pathways, with Airbus Helicopters' CityAirbus NextGen and Leonardo's AW09 platforms targeting offshore mission profiles. Offshore wind developers in German and Dutch sectors are piloting these configurations for crew transport at turbine construction sites. The technology is migrating from technology validation to operational deployment, compressing the service-life economics of conventional turbine-powered fleets.
EU Green Deal emissions standards are mandating fleet-average carbon intensity reductions for offshore public transport operators serving installations under member-state jurisdiction. Norway's Civil Aviation Authority has enacted supplementary offshore helicopter regulations requiring operators to document fuel efficiency metrics in contract bidding processes. Danish and Norwegian sectors exhibit the most aggressive compliance timelines, with framework agreement renewals now incorporating sustainability performance clauses.
Buyer consolidation among supermajor oil producers is concentrating procurement leverage with fewer decision-makers managing multi-field helicopter service contracts. Integrated energy companies in the UK and Norwegian North Sea are unbundling crew transport from emergency response services, creating discrete contract vehicles that favor specialized operators over full-service incumbents. This pattern is most visible in Norwegian continental shelf operations, where Equinor and Aker BP have separated scheduled personnel transfer from search-and-reserve standby requirements.
North Sea Offshore Helicopter Services Market Segmentation
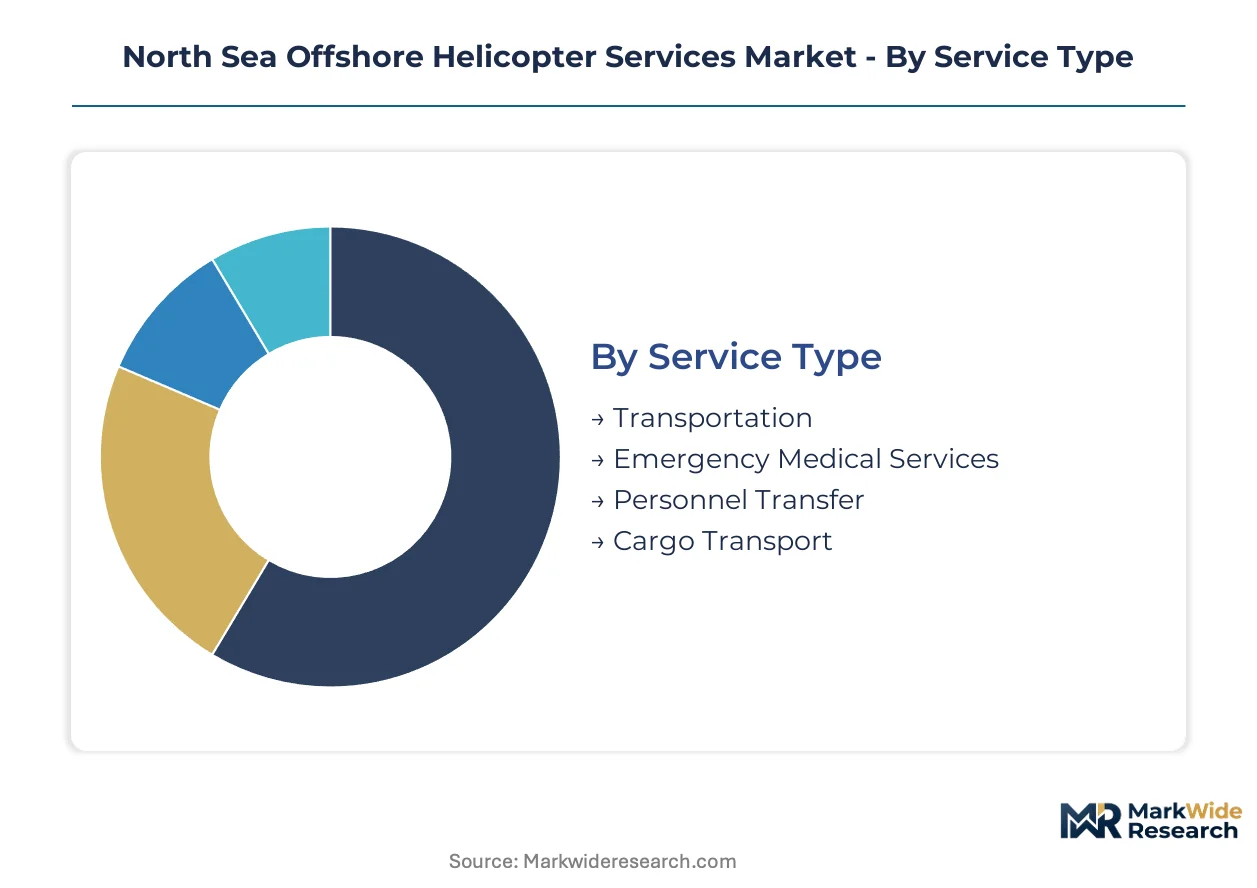
North Sea offshore helicopter operators structure service portfolios around mission-criticality and asset utilization economics. Segmentation reveals how contract tenors, aircraft specifications, and buyer procurement patterns fragment revenue pools across distinct operational categories.
Service Type:
Cost tier differentiation separates scheduled crew rotations from premium emergency response missions requiring dedicated standby aircraft.
- Transportation:Scheduled passenger movements between onshore bases and fixed offshore platforms dominate contracted flight hours. Norwegian continental shelf installations generate the densest route networks, with daily rotations to hundreds of active facilities driving fleet utilization rates.
- Personnel Transfer:Twin-engine IFR-certified helicopters equipped with automatic flotation systems execute crew changeovers under EASA offshore public transport mandates. Danish and German offshore wind construction sites are expanding demand for this service category as turbine installation phases accelerate.
- Emergency Medical Services:SAR-certified night-flight capabilities with dedicated medical equipment configurations.
- Cargo Transport:External sling loads and internal cabin freight for platform resupply missions.
Personnel transfer commands the established base. The steepest expansion runs through emergency medical services as regulatory frameworks mandate dedicated standby coverage.
End User:
Application-driven procurement patterns separate multi-year framework agreements from spot-market charter demand.
- Oil & Gas Companies:Supermajor producers in UK and Norwegian sectors negotiate integrated crew transport contracts spanning multiple field developments. Equinor and Aker BP have unbundled scheduled personnel transfer from search-and-rescue standby requirements, creating discrete contract vehicles.
- Renewable Energy Operators:Offshore wind developers at Anholt and Kriegers Flak lack dedicated heavy-lift helicopter infrastructure. Turbine installation crews require rotorcraft capacity that legacy offshore oil fleets cannot economically supply.
- Engineering Firms:Construction and maintenance contractors with project-based helicopter requirements.
- Government Agencies:Coast guard and maritime safety organizations procuring SAR coverage.
Oil and gas companies anchor contract volumes. Renewable energy operators are climbing the fastest as offshore wind construction phases multiply across Danish and German North Sea zones.
Aircraft Type:
Payload capacity and range specifications determine fleet composition against mission profiles and regulatory minima.
- Heavy Lift Helicopters:External load capacity exceeding 4,000kg for turbine component transport at wind farm construction sites. EU Green Deal emissions standards are compressing fleet renewal timelines, forcing capital deployment toward hybrid-electric platforms before conventional airframe depreciation cycles conclude.
- Medium Helicopters:Twin-engine IFR-rated airframes such as H175 and AW139 variants dominate personnel transfer missions. Airbus Helicopters and Leonardo production backlogs extend 18-24 months for offshore-certified configurations.
- Light Helicopters:Single-engine platforms restricted to coastal shuttle routes below offshore approach minima.
- Specialized Aircraft:SAR-equipped configurations with extended range fuel systems and rescue hoists.
Medium helicopters maintain the dominant installed base. Heavy lift helicopters are gaining share fastest as offshore wind construction scales beyond vessel-accessible sites.
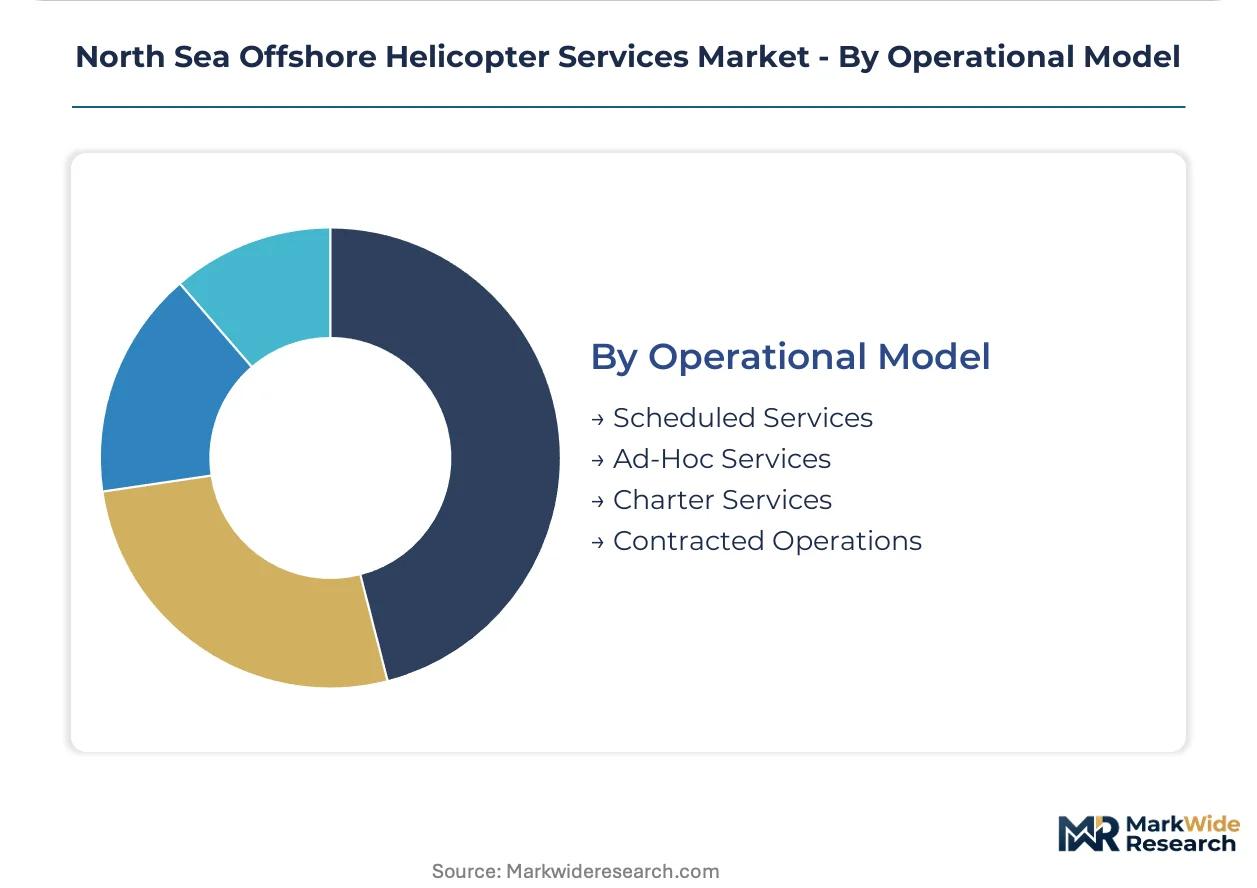
Operational Model:
Contract structure determines margin stability and capital commitment intensity across the revenue mix.
- Scheduled Services:Multi-year framework agreements with oil majors generate the most stable margin pools through guaranteed minimum flight hour commitments. Norway's Civil Aviation Authority fuel efficiency documentation requirements now embed sustainability performance clauses in renewal negotiations.
- Contracted Operations:Dedicated aircraft and crew assignments for single-buyer exclusive use.
- Charter Services:Power-by-the-hour leasing arrangements enable asset-light fleet management for mid-sized operators accessing newer-generation airframes.
- Ad-Hoc Services:Spot-market demand responding to unplanned maintenance or emergency requirements.
Scheduled services lock in the recurring revenue base. Contracted operations are expanding most quickly as buyer consolidation concentrates procurement leverage with fewer decision-makers managing multi-field service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore helicopter services trade flows through a tightly integrated corridor where Norwegian export capacity supplies Danish and German wind construction zones, while UK and Dutch operators maintain cross-border crew rotation networks serving overlapping continental shelf installations.
Norway
Equinor and Aker BP sustain the densest contracted flight hour volumes across hundreds of active platform installations. The Norwegian Civil Aviation Authority enforces supplementary offshore helicopter regulations requiring fuel efficiency documentation in contract bidding processes. Stavanger anchors the primary operational cluster, with helicopter bases at Sola Airport and Bergen Flesland processing daily crew rotations to North Sea oil and gas facilities.
United Kingdom
Supermajor producers negotiate integrated multi-field crew transport agreements spanning UK continental shelf developments. The UK Civil Aviation Authority maintains oversight through its CAP 1145 framework governing offshore public transport operations. Aberdeen serves as the dominant logistics hub, with heliport infrastructure connecting onshore bases to platforms operating beyond vessel-accessible ranges.
Denmark
Anholt and Kriegers Flak offshore wind zones generate heavy-lift helicopter demand for turbine installation crews that legacy oil fleets cannot economically supply. EU Green Deal emissions standards compress fleet renewal timelines for operators serving Danish installations. Esbjerg hosts the primary service infrastructure, with operators positioning SAR-certified night-flight capabilities to capture construction-phase contracts.
Germany
North Sea wind farm developers in German sectors pilot hybrid-electric rotorcraft configurations for crew transport at turbine construction sites. EU ReFuelEU Aviation mandates create offtake certainty for sustainable aviation fuel producers serving German offshore zones. Cuxhaven and Wilhelmshaven concentrate helicopter support infrastructure for wind construction logistics.
Netherlands
Cross-border crew rotation networks connect Dutch offshore installations to Belgian and German operational bases. EASA instrument flight rules and offshore approach minima shape fleet composition for operators serving Dutch North Sea platforms. Den Helder maintains dedicated helicopter infrastructure supporting oil, gas, and emerging wind energy logistics requirements.
North Sea Offshore Helicopter Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in maintenance and avionics subsystems. The North Sea market structures around a consolidated top tier managing multi-year framework agreements with supermajor producers, while mid-sized operators compete through asset-light power-by-the-hour leasing models. Two strategic archetypes dominate: integrated full-service operators with captive training and maintenance infrastructure, and specialized emergency response providers with SAR-certified night-flight capabilities. Competitive moves concentrate on portfolio diversification into offshore wind segments and geographic expansion through contracted operations in Danish and German zones.
Among integrated service providers, Bristow Group Inc. and CHC Helicopter occupy positions exemplifying the full-service archetype with multi-jurisdiction coverage across Norwegian and UK sectors. WIKING Helikopter Service GmbH represents the specialized emergency response tier, anchoring differentiation through SAR-certified capabilities. These three entities illustrate how competitive positioning separates framework agreement incumbents from spot-market challengers in a market where buyer consolidation concentrates procurement leverage with fewer oil major decision-makers.
| Leading Market Players |
|---|
| NHV Group |
| WIKING Helikopter Service GmbH |
| Bristow Group Inc. |
| Heli Holland |
| NSEG |
| CHC Helicopter |
| HeliService International GmbH |
| DRF Luftrettung |
| Babcock International |
| Others |
Value Network & Pricing Analysis
Stavanger's helicopter base concentration at Sola Airport and Bergen Flesland channels fleet capacity toward Norwegian continental shelf contracts, concentrating pricing power with operators holding captive maintenance infrastructure and multi-year framework agreements with Equinor and Aker BP.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across scheduled crew transport services, with three-tier pricing structure across premium, standard, and economy levels separating SAR-certified night-flight capabilities from daytime personnel rotations. Price differentiation rests on certification grade and volume scale, with EU Green Deal fuel efficiency documentation requirements compressing margins on older airframes. Cost compression in the medium helicopter tier is intensifying because Airbus Helicopters and Leonardo production backlogs extend delivery timelines. Renewable energy operators exhibit highest price sensitivity due to project-based procurement, while supermajor oil producers demonstrate lowest sensitivity through guaranteed minimum flight hour commitments.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union jurisdictions dominates supply chain risk for cross-border crew rotation networks serving overlapping continental shelf installations. Manufacturing concentrates in France, Italy, and Germany for twin-engine IFR-rated airframes, with avionics integration and composite rotor blade repair feeding from OEM-authorized facilities. The supply chain hinges on specialized pilot certification syllabi that European flight schools cannot scale to match fleet expansion rates. Distribution runs through Stavanger, Aberdeen, and Esbjerg as primary logistics hubs connecting onshore bases to offshore installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North Sea offshore helicopter services market functions as a defensive-moat industry where regulatory entrenchment through EASA instrument flight rules and offshore approach minima creates substantial switching costs for buyers locked into multi-year framework agreements.
For Market Incumbents: Insulate contract renewal positions by deepening captive training and maintenance infrastructure investments at Stavanger and Aberdeen bases, while accelerating hybrid-electric rotorcraft certification to preempt EU Green Deal compliance deadlines. Threat substitution from power-by-the-hour leasing models demands countermeasures through exclusive long-term crew transport agreements with supermajor producers. Vertical integration into SAR-certified night-flight capabilities represents the priority lever for portfolio diversification. For New Entrants and Emerging Players: Build out asset-light fleet management operations targeting Danish offshore wind zones at Anholt and Kriegers Flak, where turbine installation crews lack dedicated heavy-lift helicopter infrastructure. The most penetrable segment lies in emergency medical services unbundled from integrated operators serving Norwegian continental shelf installations. Go-to-market execution should emphasize SAR-certified capabilities as a differentiated entry credential. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized emergency response providers with regulatory-certified capabilities over capital-intensive full-service operators facing compressed fleet renewal timelines. Long-term viability hinges on operators securing sustainable aviation fuel supply contracts under EU ReFuelEU Aviation mandates. Acquisition target archetypes include mid-sized operators with power-by-the-hour leasing infrastructure. The signal to watch is framework agreement renewal patterns incorporating sustainability performance clauses as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Certification | Airbus Helicopters' CityAirbus NextGen and Leonardo's AW09 platforms target offshore wind crew transport missions. |
| Sustainable Aviation Fuel Supply Contracting | EU ReFuelEU Aviation mandates create offtake certainty enabling long-term supply agreements at stabilized premiums. |
| SAR-Certified Night-Flight Capability Expansion | Danish offshore wind construction phases lack dedicated infrastructure, creating first-mover positioning opportunities. |
| Power-by-the-Hour Leasing Infrastructure | Asset-light models allow mid-sized operators to access newer-generation airframes without balance-sheet capitalization. |
| Multi-Field Framework Agreement Consolidation | Buyer concentration with Equinor and Aker BP rewards operators with integrated training and maintenance infrastructure. |
Research Methodology
A standing panel of helicopter fleet managers, offshore logistics coordinators, EASA certification specialists, and oil major procurement directors provided ongoing calibration across primary interviews combined with secondary validation from EASA regulatory filings, UK Civil Aviation Authority CAP 1145 documentation, Norwegian offshore helicopter regulations, EU Green Deal implementation directives, and customs trade data. Bottom-up and top-down triangulation cross-checked operator flight hour reports against supermajor contract disclosures.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including service type, end user archetype, aircraft payload capacity, and operational model structure. CAGRs were derived from contracted flight hour trajectories, fleet renewal timelines, and offshore wind construction phase schedules. Industry-specific forecast inputs incorporated EU ReFuelEU Aviation mandate compliance trajectories and EASA automatic flotation system recertification cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light power-by-the-hour entrants or accelerated hybrid-electric certification by OEMs would shift outcomes. Forecasts reflect assumptions regarding oil major capital expenditure continuity and offshore wind construction timeline execution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Air Crane Helicopter Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Hang Glider Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Flying Taxi Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Flying Motorbikes Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Global Aerial Firefighting Market