
 South America Rotor Blade Market | 2026-2036
South America Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
South America Rotor Blade Market Analytics
Aftermarket service revenue is reshaping margin distribution across the South America rotor blade value chain. TPI Composites SA leverages its manufacturing footprint to capture recurring refurbishment contracts from aging Brazilian wind farms. Siemens Gamesa Renewable Energy SA anchors its regional position through integrated blade repair networks spanning multiple operating sites. Vestas Wind Systems A/S competes by extending its service agreements into predictive maintenance capabilities that reduce turbine downtime.
South America rotor blades are aerodynamic structures typically exceeding 50 meters in length, constructed from fiberglass-reinforced epoxy composites with carbon fiber spar caps, designed to convert kinetic wind energy into rotational mechanical power for electricity generation. Horizontal axis configurations dominate installed capacity across the region due to proven efficiency in the consistent trade winds of Brazil's Northeast corridor. Carbon fiber material adoption is accelerating as manufacturers pursue longer blades that improve capacity factors without exceeding transport weight limits on regional road networks. Specialty blade designs for low-wind-speed sites represent an emerging segment where margins concentrate as developers target previously marginal territories in Argentina and Uruguay.
INMETRO certification requirements and Brazil's ANEEL grid connection standards shape blade design specifications and testing protocols for equipment entering the national market. Argentina's national energy regulator enforces local content mandates that influence manufacturing location decisions and supplier qualification processes. Uruguay's energy ministry maintains technical standards aligned with IEC 61400 series for wind turbine structural integrity. Stakeholders must monitor evolving certification reciprocity agreements between Mercosur members to anticipate supply chain reconfigurations that could alter competitive access across national boundaries.
Market Dynamics
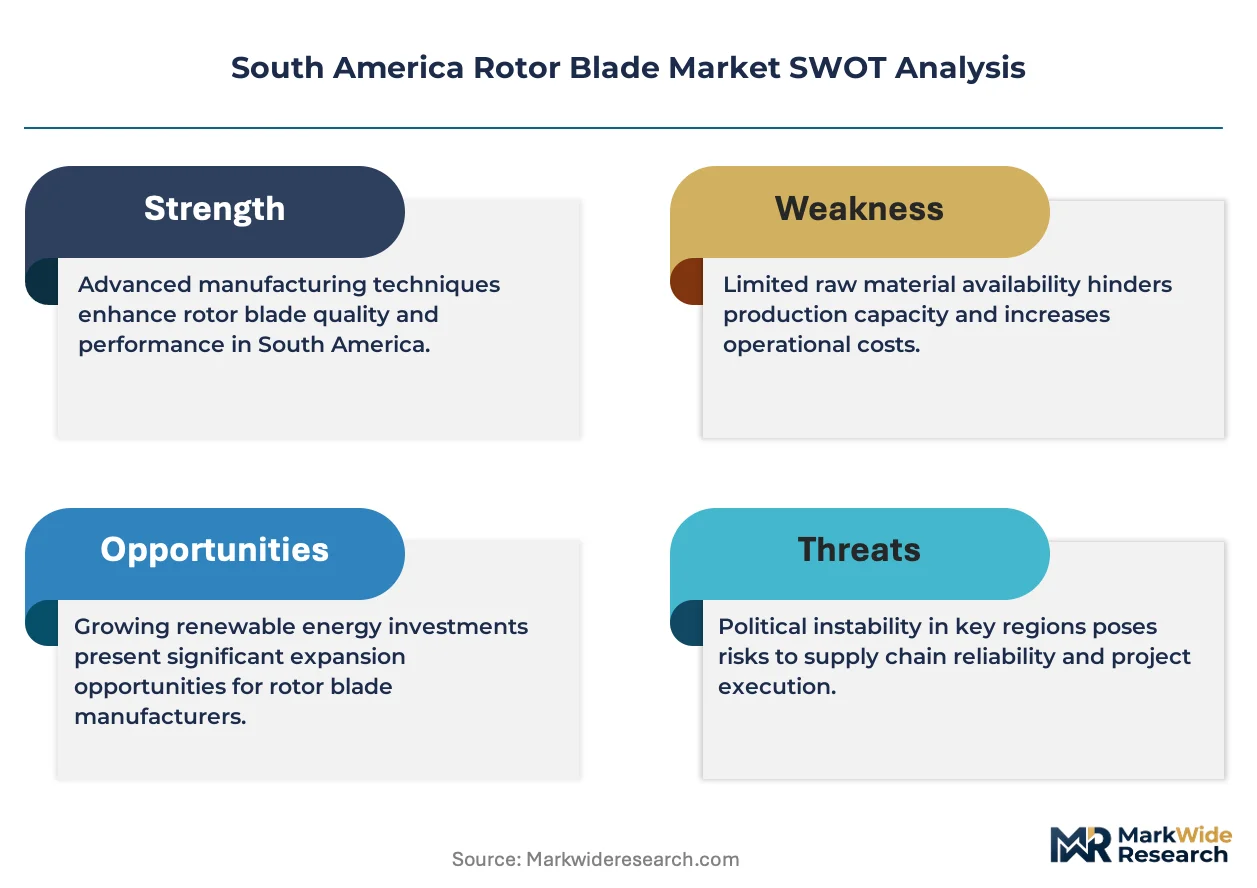
The South America rotor blade market is experiencing structural compression as INMETRO certification requirements tighten quality thresholds while transport infrastructure constraints on blade length force manufacturers toward modular design architectures.
Growth Catalysts
- ANEEL grid connection standards:Brazil's national electric energy agency mandates rigorous blade structural testing, creating sustained demand for certified composite manufacturing capacity across the Northeast wind corridor.
- Carbon fiber spar cap technology:Material substitution enables blade lengths exceeding 70 meters without exceeding regional road weight limits, unlocking higher capacity factors at low-wind-speed sites.
- Argentina's local content mandates:Procurement rules enforced by the national energy regulator compel developers to source blade components from qualified domestic suppliers, stimulating manufacturing investment.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margins for fiberglass-reinforced composite producers serving price-sensitive utility-scale developers.
- Transport infrastructure bottlenecks:Brazil's highway network imposes dimensional restrictions that limit maximum blade length and concentrate production near coastal port facilities.
- Reciprocity gaps in Mercosur certification:Divergent technical standards between member states fragment procurement pools and inflate compliance costs for cross-border suppliers.
Strategic Opportunities
- Uruguay's low-wind-speed territories:Specialty blade designs for sites below 6 meters per second average wind speed represent untapped addressable demand as developers expand beyond traditional high-resource zones.
- Refurbishment service unbundling:Aging Brazilian wind fleets create recurring revenue streams for blade repair specialists capable of predictive maintenance integration.
- Hybrid tower-blade logistics:Coordinated transport solutions combining blade and tower components reduce per-megawatt installation costs for remote project sites.
Industry Challenges
- Composite technician scarcity:Specialized laminating and quality inspection skills required for INMETRO-compliant production outpace vocational training program output across the region.
- Certification timeline compression:Extended INMETRO testing protocols delay product launches and tie up capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Rotor Blade Market |
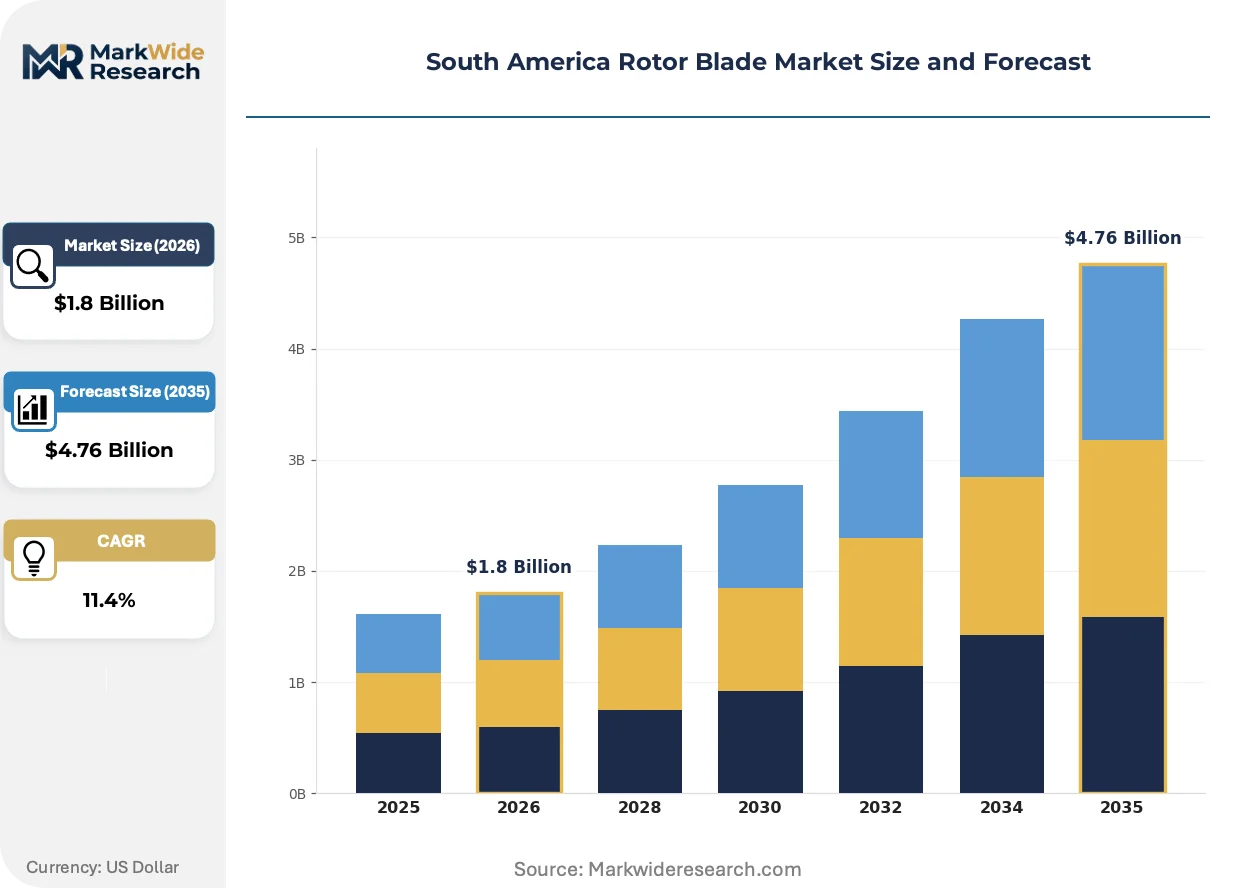
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Ducted, Specialty Material: Fiberglass, Carbon Fiber, Aluminum, Steel End User: Wind Energy, Aerospace, Marine, Industrial Application: Energy Production, Propulsion, Manufacturing, Others |
| Companies Covered | TPI Composites SA, LM Wind Power, Siemens Gamesa Renewable Energy SA, Vestas Wind Systems A/S, Enercon GmbH, Aeris Energy, Nordex SE, Suzlon Energy, Acciona SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Rotor Blade Market Evolving Landscape
Material science advances and regulatory harmonization pressures are restructuring how blade manufacturers compete across South America's fragmented national markets. Design methodologies are converging toward lighter, longer structures that optimize regional transport constraints.
Carbon fiber reinforcement is migrating from premium offshore applications to mainstream onshore products as Brazilian developers pursue capacity factor improvements. Northeast corridor wind farm operators now specify carbon spar caps for turbines above 4 megawatts. This technology is migrating from niche high-performance segments to standard procurement specifications, compressing the cost premium against all-glass designs.
ANEEL technical standards for grid-connected wind equipment are tightening blade lightning protection and structural load testing requirements. Manufacturers must now submit full-scale fatigue test data rather than scaled simulations. Brazilian OEMs and independent blade producers are responding by consolidating testing partnerships with INMETRO-accredited laboratories in São Paulo state.
Service contract unbundling is fragmenting traditional turbine supply agreements across Argentine and Brazilian markets. Developers now separately negotiate blade refurbishment, inspection, and predictive analytics rather than accepting bundled OEM service packages. This pattern is most visible in Brazil's Northeast corridor, where independent service providers capture maintenance spend from aging wind farms entering their second decade of operation.
South America Rotor Blade Market Segmentation
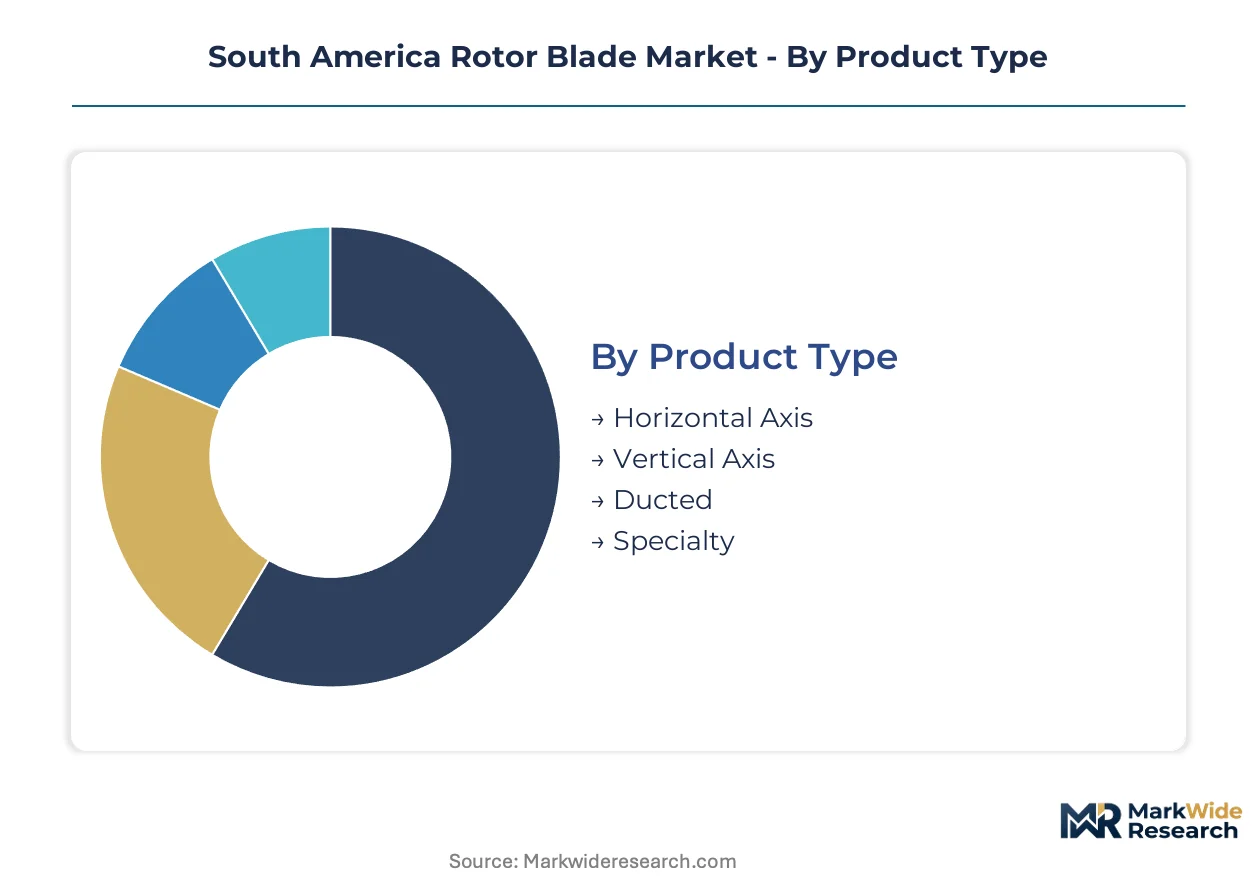
South America's rotor blade market segments along four dimensions that determine procurement cycles, margin profiles, and technical qualification pathways. Product type and material composition dominate capital allocation decisions, while end-user verticals and application scope shape aftermarket service attach rates across Brazil's Northeast corridor and Argentine wind zones.
Product Type:
Horizontal axis configurations turn over on 15-20 year replacement cycles tied to turbine life, while specialty and ducted designs refresh faster as developers experiment with site-specific aerodynamics.
- Horizontal Axis:Dominant configuration employs fiberglass-reinforced epoxy shells with carbon fiber spar caps exceeding 50 meters in length. Demand concentrates in Brazil's Northeast wind corridor where trade wind consistency rewards proven aerodynamic efficiency, though transport infrastructure limits maximum blade dimensions on regional highway networks.
- Vertical Axis:Darrieus and Savonius variants serve distributed generation niches and urban installations where omnidirectional wind capture offsets lower efficiency metrics. Argentine developers deploy these systems in Patagonian microgrids where maintenance access constraints favor simpler drive train architectures.
- Ducted:Shrouded rotor designs accelerate airflow through Venturi enclosures for low-wind-speed sites in Uruguay's interior provinces.
- Specialty:Custom aerodynamic profiles address turbulence-heavy terrain along Brazil's southern escarpment where standard blade geometries underperform.
Horizontal axis anchors the volume base while specialty designs gain share at the steepest rate as developers target marginal wind territories previously excluded from project pipelines.
Material:
Cost tiers separate commodity fiberglass from premium carbon fiber, with hybrid laminates occupying a mid-market position where weight reduction justifies partial substitution.
- Fiberglass:E-glass and S-glass rovings embedded in epoxy resin matrices constitute the baseline material platform for blades under 60 meters. Brazilian manufacturers in Ceará and Rio Grande do Norte states maintain captive fiberglass supply chains to meet INMETRO certification volume requirements for utility-scale deployments.
- Carbon Fiber:T700 and T800 grade prepregs enable spar cap reinforcement in blades exceeding 70 meters without violating Brazil's federal highway weight restrictions. Northeast corridor operators now specify carbon-reinforced structures for turbines above 4 megawatts as capacity factor optimization outweighs material cost premiums.
- Aluminum:Extruded and cast alloys serve small turbine segments below 100 kilowatts where manufacturing simplicity trumps aerodynamic refinement.
- Steel:Forged and fabricated spar elements persist in experimental vertical axis prototypes and heavy-duty industrial applications.
Fiberglass retains the dominant volume position while carbon fiber expands most quickly as longer blade architectures penetrate mainstream procurement specifications.
End User:
Wind energy customers operate on decade-scale replacement horizons, while aerospace and marine verticals demand faster refresh cycles driven by fatigue life and corrosion exposure.
- Wind Energy:Onshore and offshore wind farm operators constitute the primary demand pool, with Brazilian developers in Piauí and Rio Grande do Norte states driving procurement volumes through ANEEL-regulated auction mechanisms.
- Aerospace:Small unmanned aerial systems and experimental aircraft programs in Argentina's Córdoba aerospace cluster source composite propeller blades with tight dimensional tolerances.
- Marine:Tidal current turbines and auxiliary sail propulsion systems for coastal shipping routes in Uruguay's Río de la Plata estuary create niche demand for corrosion-resistant laminates.
- Industrial:Ventilation and process cooling applications in Brazilian manufacturing facilities employ scaled-down blade geometries adapted from wind turbine architectures.
Wind energy anchors the volume base while marine applications gain share at the steepest rate as tidal energy pilot projects advance through Uruguay's national energy ministry approval processes.
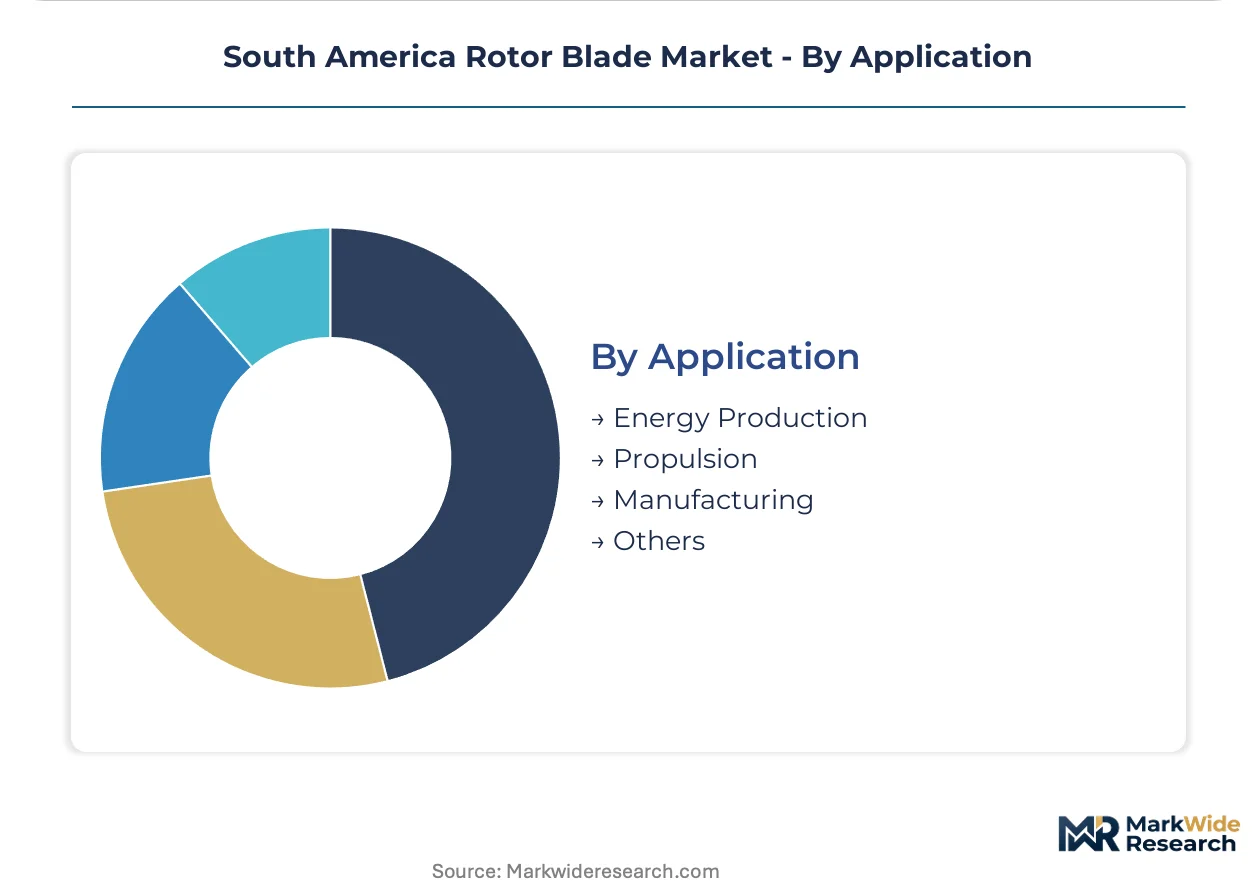
Application:
Energy production applications command the longest asset lives and most stringent certification requirements, while manufacturing and propulsion segments permit faster design iteration.
- Energy Production:Grid-connected electricity generation represents the core value proposition, with blades engineered for 20-year fatigue life under IEC 61400 structural integrity protocols enforced by ANEEL and Uruguay's energy ministry.
- Propulsion:Mechanical drive applications including pumps, compressors, and direct mechanical power transmission serve Argentine agricultural processing facilities in Mendoza and San Juan provinces.
- Manufacturing:Process air movement and material handling systems employ industrial-scale fan blades derived from wind turbine aerodynamic research.
- Others:Research platforms, educational installations, and hybrid renewable demonstration projects complete the application spectrum.
Energy production anchors the volume base while propulsion applications gain share at the steepest rate as off-grid mechanical power systems expand in Argentina's agricultural interior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South American procurement zones. Brazilian developers in the Northeast corridor prioritize certified manufacturing capacity over unit cost, while Argentine operators face acute budget constraints under currency volatility. Uruguay's emerging project pipeline shows intermediate elasticity, balancing performance specifications against limited financing availability.
Brazil
ANEEL-regulated auction mechanisms drive blade procurement volumes through Piauí and Rio Grande do Norte states. INMETRO certification requirements enforce full-scale fatigue testing protocols that extend qualification timelines. São Paulo state hosts INMETRO-accredited laboratories where manufacturers consolidate testing partnerships to meet tightening structural integrity standards.
Argentina
Patagonian wind zones attract developers targeting high-capacity-factor resources despite transmission infrastructure gaps. The national energy regulator enforces local content mandates compelling blade component sourcing from qualified domestic suppliers. Córdoba province's aerospace cluster supplies composite technicians whose laminating skills transfer to wind blade production.
Uruguay
Interior provinces below 6 meters per second average wind speed create demand for specialty low-wind-speed blade designs. The energy ministry maintains technical standards aligned with IEC 61400 series for structural certification. Río de la Plata estuary tidal pilot projects generate niche corrosion-resistant laminate requirements for marine turbine applications.
Chile
Atacama Desert and southern Magallanes regions present extreme temperature differentials requiring thermal-expansion-tolerant blade materials. The national electrical coordinator enforces grid code compliance for variable renewable integration. Antofagasta mining corridor microgrids deploy scaled blade systems for hybrid solar-wind installations serving remote extraction sites.
Colombia
Andean ridge wind resources remain underdeveloped due to complex terrain and community consultation requirements. The mining and energy planning unit regulates environmental licensing for renewable project development. La Guajira peninsula offshore wind assessments advance through feasibility studies evaluating blade corrosion resistance in Caribbean salt-air conditions.
South America Rotor Blade Market Competitive Landscape
Capability concentration sits with integrated OEMs possessing INMETRO-certified testing infrastructure; scale advantage sits with independent blade specialists operating multi-country manufacturing footprints. The market structures around three tiers: full-service turbine OEMs with captive blade production, dedicated composite manufacturers serving multiple OEMs, and regional fabricators capturing local content mandates. Consolidation pressure intensifies as certification timeline compression favors players with established laboratory partnerships. Dominant competitive moves include backward integration into carbon fiber spar cap production and geographic expansion through Mercosur reciprocity positioning.
Within the integrated OEM tier, Siemens Gamesa Renewable Energy SA and Vestas Wind Systems A/S exemplify full-service architectures spanning blade design through aftermarket service networks. TPI Composites SA represents the independent specialist model, operating as a merchant supplier to multiple turbine manufacturers across the Americas. These three entities anchor distinct competitive positions: Siemens Gamesa SA and Vestas A/S leverage service contract bundling while TPI Composites SA captures refurbishment revenue from aging Brazilian wind fleets entering second-decade operational cycles.
| Leading Market Players |
|---|
| TPI Composites SA |
| LM Wind Power |
| Siemens Gamesa Renewable Energy SA |
| Vestas Wind Systems A/S |
| Enercon GmbH |
| Aeris Energy |
| Nordex SE |
| Suzlon Energy |
| Acciona SA |
| Others |
Value Network & Pricing Analysis
Brazil's Northeast wind corridor freight routes impose dimensional surcharges on blades exceeding 60 meters, concentrating supply around coastal manufacturing clusters and forcing price differentiation between modular designs and integrated longer structures. ANEEL-regulated developers absorb transport premiums for certified composite capacity, while Argentine operators facing currency volatility prioritize domestic sourcing to hedge forex exposure.
Pricing Analysis
Long-term offtake agreements dominate procurement for utility-scale Brazilian wind farms, with spot purchasing limited to emergency replacements and small-scale distributed projects. Three-tier pricing structure across premium, standard, and economy levels separates INMETRO-certified carbon fiber spar cap designs from fiberglass-only alternatives and uncertified regional fabricator output. Cost compression in economy-tier fiberglass blades is intensifying because epoxy resin feedstock volatility erodes margins for non-integrated producers. Price-sensitive independent power producers in Argentina's Patagonian zones drive hardest negotiations, while least-sensitive buyers are Brazilian Northeast corridor operators locking multi-year service-bundled contracts.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier financing arrangements as Brazilian developers stretch working capital across ANEEL auction cycles. Raw material sourcing draws from China's carbon fiber prepeg supply, Germany's epoxy resin formulations, and domestic Brazilian fiberglass roving production in Ceará state. Single-source vulnerability concentrates in T700-grade carbon fiber spar cap supply chains where qualified alternative vendors remain limited. Distribution runs through port-centric manufacturing hubs in Pecém and Suape, with final-mile logistics coordinated via specialized blade transport carriers serving Piauí and Rio Grande do Norte wind zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's rotor blade market sits in a cyclical recovery phase as Brazil's auction pipeline replenishes following regulatory timeline compression, with replacement demand from aging Northeast corridor fleets providing underlying floor support.
For Market Incumbents: Build certification moats through INMETRO-accredited laboratory partnerships in São Paulo state. Siemens Gamesa SA and Vestas A/S should deepen captive repair network density across Brazilian operating sites to capture unbundled service spend from independent providers. TPI Composites SA must secure carbon fiber spar cap backward integration before cost premiums compress against all-glass competitors. Threat substitution from modular blade architectures favors early movers controlling hybrid tower-blade logistics coordination. For New Entrants and Emerging Players: Mid-scale refurbishment specialists in Brazil's Northeast corridor represent the most penetrable entry point, where predictive maintenance capability gaps exceed qualified technician supply. Argentine local content mandates create white-space for Córdoba province composite fabricators transferring aerospace laminating skills to wind applications. Uruguay's sub-6-meter-per-second interior provinces demand specialty low-wind-speed blade designs absent established incumbent focus. Go-to-market should anchor through EPC contractor partnerships rather than direct OEM competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates holding stranded composite manufacturing assets without wind-specific certification pathways. Long-term viability hinges on regulatory reciprocity harmonization across Mercosur members enabling cross-border supply chain reconfiguration. Acquisition archetypes include INMETRO-accredited independent laboratories and carbon fiber spar cap pre-form specialists. Signal to monitor: ANEEL auction volume announcements and INMETRO testing queue backlogs as capacity utilization indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Spar Cap Production | Captive supply of T700 prepregs insulates margin compression from petrochemical volatility. |
| INMETRO-Accredited Testing Partnership Consolidation | São Paulo laboratory access compresses certification timelines for product launch velocity. |
| Hybrid Tower-Blade Logistics Coordination | Coordinated transport solutions reduce per-megawatt installation costs at remote Argentine sites. |
| Predictive Maintenance Platform Deployment | Service unbundling in Brazil's aging fleet creates recurring revenue attach opportunities. |
| Uruguay Low-Wind-Speed Specialty Design Development | Interior province site expansion addresses untapped addressable demand below 6 m/s average. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANEEL auction databases, INMETRO certification registries, and Mercosur trade flow records. Primary interviews engaged wind farm operators in Piauí and Rio Grande do Norte, composite manufacturing plant managers in Ceará, EPC contractors, and ANEEL regulatory affairs specialists. Secondary validation drew from ANEEL technical standards documentation, IEC 61400 series protocols, and Brazilian federal highway transport regulations. Bottom-up blade shipment tracking and top-down wind capacity installation data were triangulated to anchor volume estimates.
Forecast inputs include ANEEL-regulated auction schedules, carbon fiber spar cap cost curves, and INMETRO certification timeline trajectories across the projection horizon. Segmentation modeling incorporated product type, material composition, end-user vertical, and application scope dimensions with regional regulatory cluster overlays. CAGRs were derived from regression analysis against installed capacity buildout assumptions and replacement cycle timing. Industry-specific inputs capture epoxy resin feedstock volatility patterns and Mercosur reciprocity agreement negotiation status.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine peso convertibility regimes, or regional petrochemical pricing would shift the trajectory. Forecasts reflect documented assumptions around ANEEL auction execution, INMETRO testing capacity expansion, and carbon fiber supply chain diversification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market