
 Composite Pylon Fairing Systems for New Engine Options Market | 2026-2036
Composite Pylon Fairing Systems for New Engine Options Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Pylon Fairing Systems for New Engine Options Market Insights
Modular pylon fairing kits bundled with engine integration packages is restructuring procurement patterns across the aerostructures supply chain. Collins Aerospace leverages its vertically integrated composites portfolio to anchor long-term contracts with airframers. Spirit AeroSystems competes through manufacturing scale at its Wichita and Kinston facilities. FACC AG differentiates via specialized thermoplastic processing capabilities for acoustic attenuation panels.
Composite pylon fairing systems enclose and streamline the engine-to-wing structural interface, typically fabricated from carbon fiber-epoxy prepregs with Nomex honeycomb cores and cured via autoclave processing to achieve aerospace-grade void content below 2 percent. Their primary purpose is to reduce aerodynamic drag, attenuate fan noise, and protect critical fuel and hydraulic lines from foreign object damage. Carbon fiber composite dominates current production volumes due to its stiffness-to-weight ratio, while resin transfer molding is gaining traction for complex geometries where autoclave size constraints limit throughput. Military jets represent a concentrated margin pool as stealth-compatible formulations command premium pricing.
FAA airworthiness directives and EASA CS-25 certification standards govern pylon structural integrity and fire containment, compelling suppliers to maintain dual-approval testing protocols. EPA noise regulations under 14 CFR Part 36 and ICAO Chapter 14 standards are forcing acoustic liner redesigns that increase composite part count per pylon. Stakeholders must monitor how sustainable aviation fuel compatibility requirements from EASA and FAA reshape thermal management specifications in next-generation fairing designs.
Market Dynamics
Engine re-engining programs for narrowbody aircraft are forcing accelerated pylon redesign cycles, compressing supplier development timelines from 48 months to 30 months while tightening acoustic and thermal performance thresholds.
Growth Catalysts
- FAA Part 36 Stage 5 Noise Standards:Stricter ICAO Chapter 14 compliance deadlines are mandating enhanced acoustic liner integration in pylon fairings, expanding composite part count per shipset.
- Thermoplastic Processing Advancement:Out-of-autoclave consolidation techniques are reducing cycle times for complex acoustic attenuation geometries, enabling throughput scaling for re-engining programs.
- Wichita-Kinston Manufacturing Cluster:Concentrated aerostructures capacity in Kansas and North Carolina is anchoring domestic supply security for Boeing's next-generation powerplant integration.
Market Restraints
- Carbon Fiber Prepreg Cost Volatility:Aerospace-grade carbon fiber-epoxy systems face pricing pressure from competing demand in wind turbine blade manufacturing, squeezing fairing margins.
- Autoclave Throughput Bottlenecks:Physical size constraints on existing autoclave infrastructure limit production scaling for single-piece pylon skins exceeding 6 meters in length.
- EASA-FAA Dual Certification Burden:Divergent testing protocols for fire containment and lightning strike protection add 8-12 months to qualification timelines for new fairing designs.
Strategic Opportunities
- Resin Transfer Molding Adoption:RTM processes for complex pylon geometries are penetrating programs where autoclave capacity constraints previously blocked supplier entry.
- Sustainable Aviation Fuel Thermal Compatibility:Higher combustion temperatures from SAF blends are creating retrofit demand for next-generation thermal barrier coatings in existing fairing fleets.
- Stealth-Compatible Formulation Development:Radar-absorbent composite formulations for military engine integration command premium pricing and long-term sole-source contracts.
Industry Challenges
- Certified Bonding Technician Scarcity:FAA-approved composite repair stations face shortages of technicians qualified for Nomex honeycomb core restoration and lightning strike remediation.
- Legacy Fleet Integration Complexity:Retrofitting new-engine pylons onto airframes with original equipment structural interfaces demands extensive finite element remodeling and physical testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Pylon Fairing Systems for New Engine Options Market |
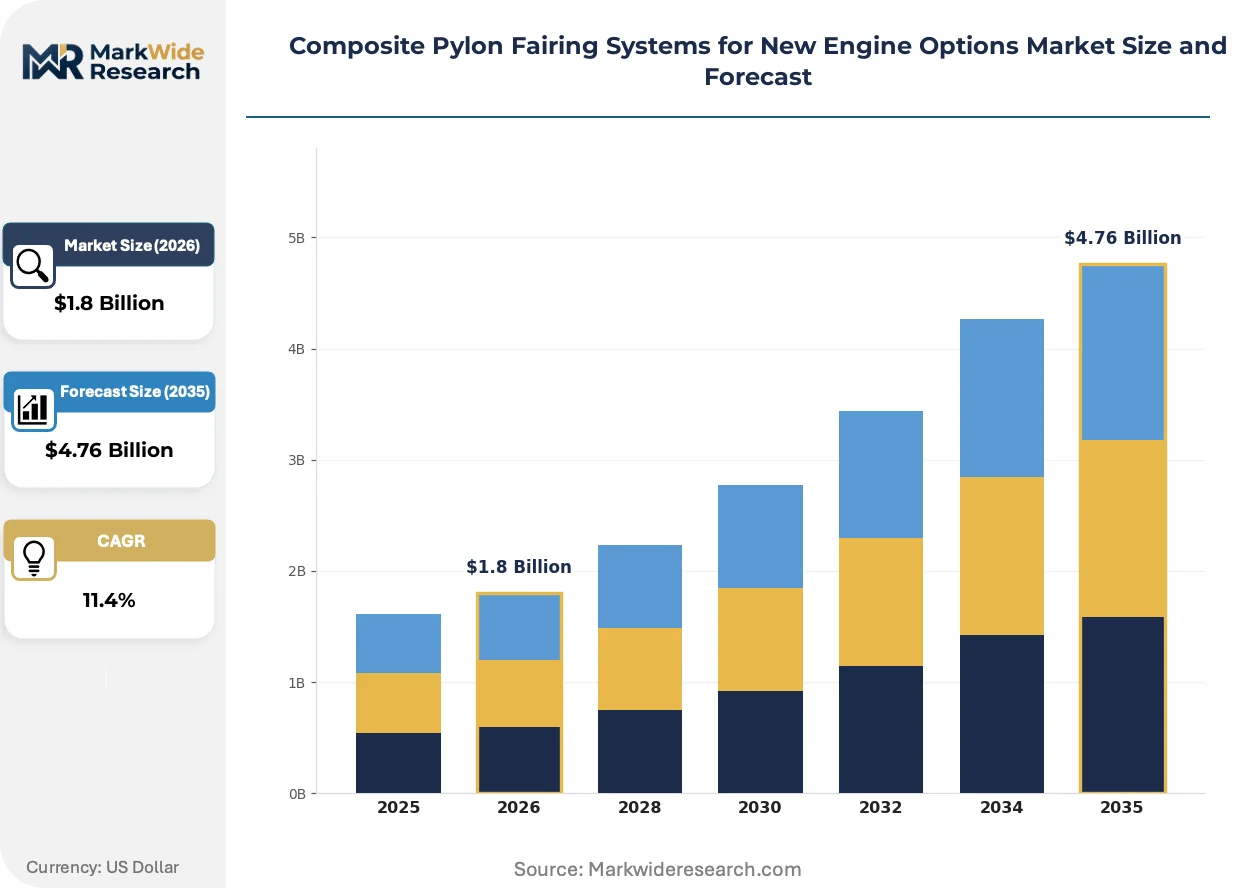
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kevlar Composite, Carbon Fiber Composite, Glass Fiber Composite, Hybrid Composite Technology: Autoclave Processing, Resin Transfer Molding, Vacuum Infusion, Filament Winding Application: Commercial Aircraft, Military Jets, Business Aviation, Cargo Transport End User: Aircraft Manufacturers, Tier-1 Suppliers, Maintenance Providers, Aero-structural Assemblers |
| Companies Covered | Collins Aerospace, Spirit AeroSystems, Triumph Group, FACC AG, Strata Manufacturing, CTRM Aerocomposites, Korean Air Aerospace Division, ShinMaywa Industries, Royal Engineered Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Pylon Fairing Systems for New Engine Options Market Trends and Innovations
Material substitution and manufacturing process evolution are compressing development cycles while regulatory pressure on noise and emissions intensifies design complexity. These forces are restructuring supplier technical capabilities and procurement relationships.
Resin transfer molding is overtaking autoclave processing for pylon fairing primary structures where geometric complexity exceeds 5-meter single-piece dimensions. Tier 1 aerostructures suppliers are adopting RTM for acoustic panel integration to bypass autoclave queue constraints. This shift is enabling new entrants to compete on lead time rather than capital-intensive autoclave infrastructure ownership.
EASA CS-25 Amendment 25-148 introduced revised fire containment requirements for engine nacelle and pylon structures, mandating 15-minute flame resistance at 1100°C for composite fairings. European OEMs are redesigning pylon lower skins with integrated firewalls and thermoplastic tie layers. The narrowbody re-engining segment faces the steepest compliance cost increase as grandfathered designs lose certification grandfathering.
Airframers are unbundling engine integration packages from propulsion OEMs to retain pylon fairing specification control and multi-source leverage. Boeing's 737 MAX re-engining program established separate RFPs for engine, nacelle, and pylon fairing work packages. This procurement fragmentation is most advanced in the United States, where antitrust scrutiny of vertical integration has accelerated supplier base diversification mandates.
Composite Pylon Fairing Systems for New Engine Options Market Segmentation
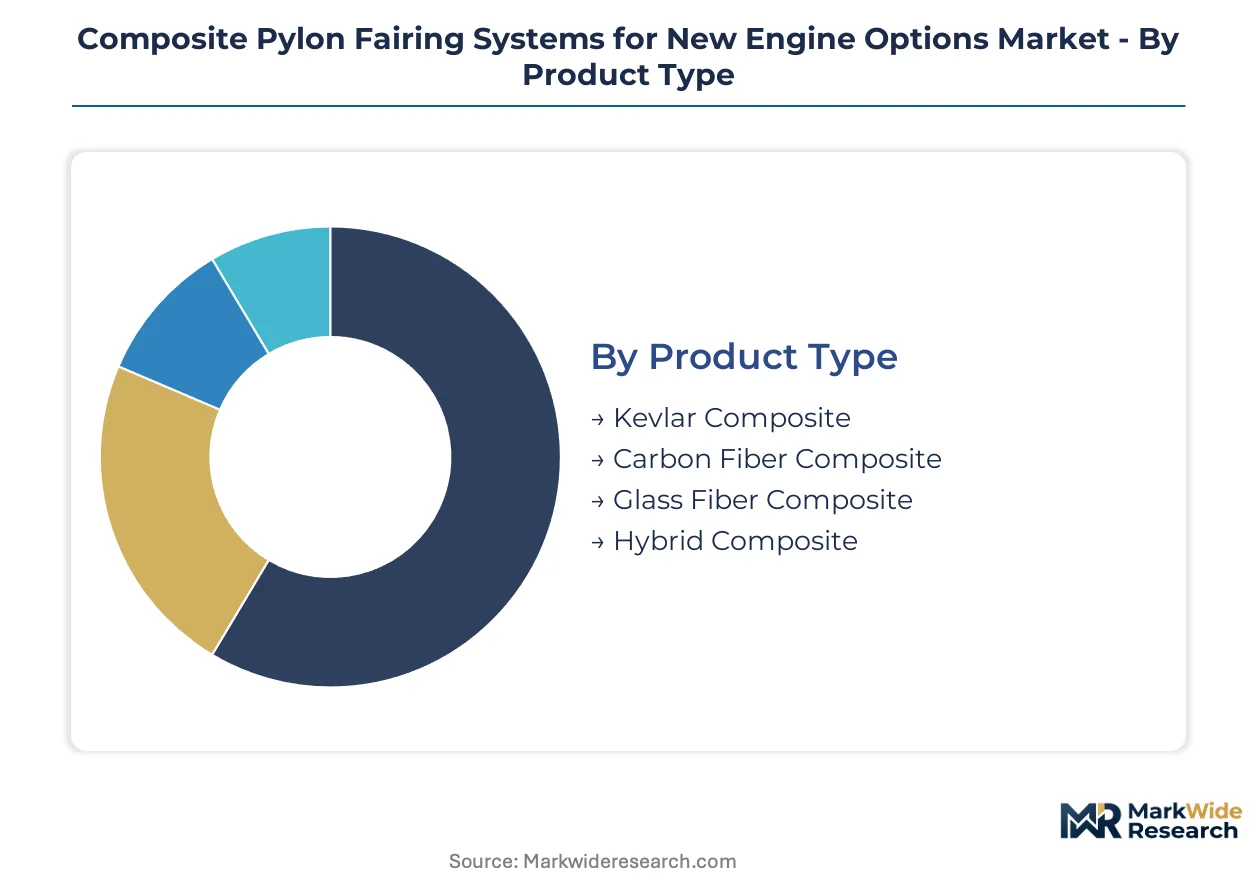
Pylon fairing procurement patterns fragment across material grades, manufacturing processes, and certification tiers. Each segment carries distinct FAA and EASA approval burdens that reshape supplier qualification timelines and contract structures.
Product Type:
Carbon fiber-epoxy systems demand full FAA Part 25 and EASA CS-25 structural substantiation, while aramid and glass variants face lighter acoustic-panel-only certification paths.
- Carbon Fiber Composite:High-modulus carbon fiber-epoxy prepregs with Nomex honeycomb cores dominate current narrowbody re-engining programs. Boeing's 737 MAX pylon redesigns in the United States concentrate demand for autoclave-cured skins meeting sub-2% void content specifications.
- Hybrid Composite:Carbon-glass interlayers optimize cost-performance balance for acoustic attenuation panels, with Spirit AeroSystems' Wichita facility driving volume for blended winglet-integrated fairings. EASA Amendment 25-148 fire resistance mandates are accelerating hybrid adoption for firewall-adjacent applications.
- Kevlar Composite:Aramid-based systems serve specialized military applications requiring ballistic impact resistance alongside radar signature management.
- Glass Fiber Composite:E-glass formulations anchor lower-cost cargo conversion programs where acoustic performance requirements remain minimal.
Carbon Fiber Composite sits at the top of the volume ranking, with Hybrid Composite climbing the fastest.
Technology:
Process selection determines capital intensity, throughput scalability, and geometric complexity limits across supplier tiers.
- Autoclave Processing:Legacy aerospace standard achieving aerospace-grade consolidation for single-piece skins exceeding 5 meters. Physical size constraints at existing United States facilities limit throughput for next-generation narrowbody programs.
- Resin Transfer Molding:Closed-mold injection processes bypass autoclave queues for complex acoustic panel geometries. FACC AG's Austrian thermoplastic RTM lines are capturing European narrowbody re-engining contracts previously blocked by capital barriers.
- Vacuum Infusion:Out-of-autoclave alternative gaining traction for prototype and low-rate initial production phases.
- Filament Winding:Automated fiber placement for cylindrical pylon structural elements and duct segments.
Autoclave Processing retains dominant share, though Resin Transfer Molding expands most quickly as queue constraints harden.
Application:
Military and commercial segments diverge sharply on stealth compatibility, fire containment, and acoustic specification stringency.
- Commercial Aircraft:Narrowbody re-engining programs generate highest absolute volumes, with FAA Stage 5 noise compliance forcing acoustic liner redesigns that expand composite part count per shipset. Boeing and Airbus procurement fragmentation is unbundling pylon fairing specifications from engine OEM packages.
- Military Jets:Stealth-compatible formulations command premium pricing and sole-source contract structures. Radar-absorbent composite development for fifth-generation powerplant integration concentrates margins with qualified suppliers.
- Business Aviation:Low-volume, high-customization segment with extended lead times for fractional ownership fleet retrofits.
- Cargo Transport:Freighter conversion programs prioritize cost minimization over acoustic performance, favoring glass fiber and simplified geometries.
Commercial Aircraft leads absolute volume, while Military Jets delivers steepest margin expansion.
End User:
Tier positioning determines specification control, multi-source leverage, and aftermarket capture economics.
- Aircraft Manufacturers:Boeing and Airbus retain pylon fairing specification authority as engine integration packages unbundle. Direct contracting with Collins Aerospace and Spirit AeroSystems is restructuring traditional propulsion OEM supply chains.
- Tier-1 Suppliers:Aerostructures specialists with vertically integrated composites portfolios anchor long-term narrowbody contracts. Wichita-Kinston manufacturing clusters in the United States concentrate qualified capacity.
- Maintenance Providers:FAA-certified repair stations face technician scarcity for Nomex honeycomb core restoration and lightning strike remediation.
- Aero-structural Assemblers:Sub-tier fabricators serving regional jet and business aviation programs with limited thermal management capabilities.
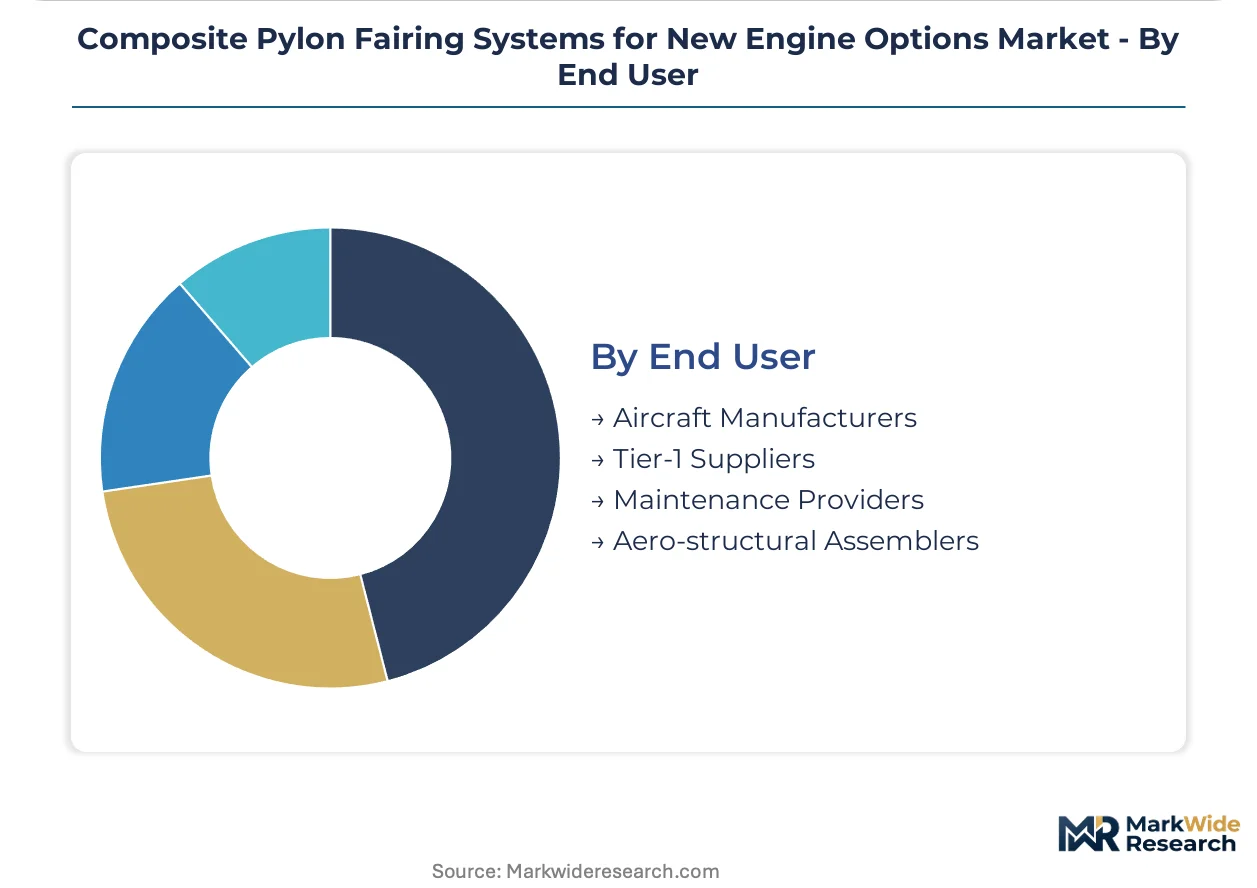
Aircraft Manufacturers command specification authority, with Tier-1 Suppliers gaining procurement volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The composite pylon fairing industry traces its commercial scale to Boeing's 737 program expansions in Wichita, Kansas during the 1980s, when autoclave-cured carbon fiber-epoxy systems first replaced aluminum in engine-to-wing structural interfaces. This heritage established the United States as the foundational market for aerostructures integration expertise.
United States
Boeing's 737 MAX and 777X re-engining programs drive concentrated demand for pylon redesign cycles in Washington State and Kansas. FAA Part 25 certification requirements and Stage 5 noise standards under 14 CFR Part 36 compel enhanced acoustic liner integration. The Wichita-Kinston manufacturing corridor anchors domestic supply security, with Spirit AeroSystems' Kansas facilities processing high-modulus carbon fiber prepregs for narrowbody shipsets.
Germany
Airbus A320neo family production in Hamburg and Toulouse generates substantial procurement volume for pylon fairing systems optimized for Pratt & Whitney and CFM International powerplants. EASA CS-25 Amendment 25-148 fire containment mandates are accelerating thermoplastic tie-layer adoption in firewall-adjacent structures. The Hamburg Finkenwerder aerostructures cluster hosts specialized composite repair stations qualified for dual FAA-EASA certification protocols.
France
Safran's engine integration leadership at Villaroche and Toulouse creates adjacent demand for nacelle and pylon system coordination. REACH regulation compliance for resin systems and EU Green Deal decarbonization targets are reshaping material qualification pathways. The Toulouse-Blagnac aerospace valley concentrates Tier-1 supplier engineering centers focused on out-of-autoclave process development for acoustic attenuation panels.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries sustain defense and regional jet pylon fabrication for F-2 fighters and SpaceJet programs. METI industrial policy supports domestic carbon fiber supply chain security through Toray Industries' precursor manufacturing. The Nagoya aerospace cluster maintains specialized autoclave capacity for military-grade void content specifications below 1.5 percent.
United Kingdom
Rolls-Royce's Derby engine integration center drives pylon thermal management requirements for UltraFan and Trent powerplant families. The UK Civil Aviation Authority's post-Brexit certification autonomy is diverging from EASA protocols on lightning strike protection testing. The Southwest England composites corridor around Bristol harbors niche RTM specialists serving business aviation and cargo conversion programs.
Composite Pylon Fairing Systems for New Engine Options Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and thermal management capability, with military stealth-compatible formulations commanding pricing multiples over commercial narrowbody equivalents. The supplier base concentrates around three strategic archetypes: vertically integrated aerostructures conglomerates with captive composites portfolios, specialized thermoplastic processors focused on acoustic attenuation, and regional fabricators serving freighter conversion and aftermarket repair segments. Dominant competitive moves include backward integration into carbon fiber prepreg supply and geographic co-location with airframer final assembly lines.
Within the vertically integrated tier, Collins Aerospace exemplifies the conglomerate archetype through its breadth of aerospace-grade composite capabilities, while Spirit AeroSystems occupies a position as a scale-driven aerostructures specialist with concentrated narrowbody exposure. FACC AG represents the European specialist model, anchoring thermoplastic processing expertise for acoustic panel applications. These three entities collectively illustrate how supplier positioning stratifies across capital intensity, certification breadth, and geographic proximity to major airframer engineering centers.
| Leading Market Players |
|---|
| Collins Aerospace |
| Spirit AeroSystems |
| Triumph Group |
| FACC AG |
| Strata Manufacturing |
| CTRM Aerocomposites |
| Korean Air Aerospace Division |
| ShinMaywa Industries |
| Royal Engineered Composites |
| Others |
Pricing and Supply Chain Analysis
Captive autoclave infrastructure at Wichita and Kinston facilities anchors pricing power for incumbent suppliers serving Boeing's narrowbody re-engining programs, while outsourced RTM processing enables new entrants to compete on lead time compression rather than capital ownership. FAA-EASA dual certification requirements for fire containment and lightning strike protection create tiered pricing stratification that rewards qualified incumbents with premium contract structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates military stealth-compatible formulations from commercial narrowbody shipsets and cargo conversion programs. Price differentiation rests on certification tier and thermal management capability, with Stage 5 noise compliance mandates adding acoustic liner complexity that expands part count per shipset. Cost compression in standard commercial tiers is intensifying because carbon fiber prepreg demand from wind energy applications is squeezing aerospace-grade material availability. Cargo conversion operators exhibit highest price sensitivity, while military integrators accept premium positioning for radar-absorbent formulations.
Supply Chain Analysis
Certified bonding technician scarcity in the United States, Germany, and Japan constrains throughput scaling for Nomex honeycomb core restoration and lightning strike remediation. Raw material dependencies draw from Toray Industries carbon fiber precursors, Huntsman epoxy resin systems, and DuPont aramid honeycomb cores. Single-source vulnerability around aerospace-grade autoclave capacity exceeding 6-meter dimensions creates qualification bottlenecks for next-generation narrowbody programs. Distribution runs through Tier-1 aerostructures suppliers with direct airframer contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EASA CS-25 Amendment 25-148 fire containment mandates are accelerating redesign cycles and expanding addressable demand for thermoplastic tie-layer integration.
For Market Incumbents: Cement long-term contract structures with Boeing and Airbus by co-locating engineering resources at Wichita and Hamburg final assembly centers, insulating against RTM-based new entrants competing on lead time compression. Invest in backward integration into carbon fiber prepreg supply to offset material cost volatility from wind energy sector demand competition. For New Entrants and Emerging Players: Regional jet aftermarket repair stations represent an underserved buyer archetype facing acute technician scarcity for lightning strike remediation and core restoration services. Target FAA-certified repair stations with mobile training and equipment lease programs, bypassing capital-intensive autoclave ownership requirements that block primary structure entry. For Investors and Strategic Acquirers: Roll-up economics work for specialized thermoplastic processors because EASA fire resistance mandates are fragmenting procurement away from consolidated propulsion OEM packages toward multi-source fairing specifications. Monitor SAF thermal compatibility retrofit demand as the inflection signal for next-generation thermal barrier coating market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Adoption | RTM and thermoplastic consolidation bypass queue constraints at Wichita facilities. |
| Dual Certification Investment | FAA-EASA approval protocols open military and commercial contract eligibility. |
| Thermal Barrier Coating Development | SAF compatibility requirements from EASA drive retrofit demand for existing fleets. |
| Repair Station Network Expansion | Certified technician scarcity creates captive aftermarket revenue streams. |
| Stealth Formulation R&D | Radar-absorbent composites command sole-source military contracts. |
Research Methodology
Coverage spans the United States, Germany, France, Japan, and the United Kingdom, with primary inputs from each region's aerospace manufacturing clusters. The analysis combines structured interviews with aerostructures procurement directors, FAA certification engineers, composite manufacturing plant managers, and airline fleet planning executives with secondary validation from EASA CS-25 amendment filings, FAA airworthiness directives, and customs trade data on carbon fiber precursor imports. Bottom-up shipset demand modeling and top-down OEM procurement budget analysis provide triangulation across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across material grade, manufacturing process, application segment, and end-user tier dimensions. CAGRs were derived from fitted trend analysis incorporating narrowbody re-engining program schedules, regulatory compliance deadlines, and autoclave capacity utilization rates. Forecast inputs include Pratt & Whitney and CFM International powerplant delivery projections, plus EASA and FAA rulemaking calendars for noise and fire containment standards.
Inputs from regulatory filing databases and OEM procurement disclosures were available through the study window; gaps in military program classification introduce uncertainty bands around stealth-compatible formulation demand. Forecasts reflect assumptions on certification timeline continuity and material supply chain stability. Material deviation in SAF mandate acceleration or autoclave capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market