
 Helicopter Blades Market | 2026-2036
Helicopter Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Blades Market Analysis
Performance-based logistics contracting is expanding as the dominant service-layer model in helicopter blade procurement, shifting revenue from unit sales to flight-hour availability guarantees. Airbus Helicopters leverages European military sustainment frameworks to anchor long-term blade overhaul contracts across NATO fleets. Sikorsky Aircraft Corporation sustains its position through vertical integration into proprietary titanium root fitting production. Bell Textron competes on civil medical evacuation platforms where folding blade systems reduce hangar footprint requirements.
Helicopter blades are aerodynamic lifting surfaces fabricated from composite laminates, titanium root attachments, and erosion-resistant leading-edge coatings, engineered to withstand cyclic fatigue loads exceeding ten million rotor revolutions while maintaining precise chordwise mass balance. Their primary purpose is generating controlled lift and thrust vectoring for vertical flight operations in military, civil, and energy-sector missions. Carbon fiber blade types command premium positioning due to superior fatigue life and damage tolerance compared with legacy aluminum extrusions. Military Operations within the Application dimension dominates procurement volumes, though Medical Evacuation segments exhibit faster fleet renewal cycles driven by hospital network expansion.
FAA airworthiness directives govern civil blade certification timelines in the United States, while EASA CS-29 standards shape European large rotorcraft access, and India's DGCA aligns with ICAO frameworks under bilateral recognition agreements. Military blade specifications additionally fall under DOD MIL-STD-810 environmental testing protocols, creating dual-track compliance burdens for dual-use suppliers. Stakeholders must monitor evolving noise certification stringency from ICAO Chapter 14 amendments, which will force acoustic redesign investments before next-generation urban air mobility platforms achieve commercial scale.
Market Dynamics
Carbon fiber prepreg manufacturing is consolidating blade supply chains around automated fiber placement, compressing lead times for military spar replacements while raising capital barriers for new composite entrants.
Growth Catalysts
- NATO Fleet Modernization:Multi-year defense procurement frameworks in member states are accelerating blade replacement cycles for aging UH-60 and CH-47 platforms.
- REACH Compliance Migration:European environmental standards on chemical substances in coatings are forcing suppliers to reformulate erosion-resistant leading-edge materials, creating upgrade demand.
- Automated Fiber Placement:Robotic layup systems are reducing labor content in spar fabrication, enabling faster throughput for high-cycle fatigue-rated components.
Market Restraints
- Titanium Root Fitting Concentration:Forging capacity for high-strength titanium attachments concentrates among a handful of aerospace metallurgical suppliers, creating single-source vulnerability.
- Dual-Track Certification Burden:Suppliers serving both civil and military segments must simultaneously satisfy FAA Part 29 and DOD MIL-STD-810 protocols, doubling compliance overhead.
- Aluminum Spar Obsolescence:Legacy machined aluminum designs face accelerated replacement by composite alternatives, stranding capital equipment at incumbent machine shops.
Strategic Opportunities
- Urban Air Mobility Noise Standards:ICAO Chapter 14 amendments will mandate acoustic redesign for next-generation electric vertical takeoff platforms, opening engineering service contracts.
- Medical Evacuation Fleet Expansion:Hospital network growth in secondary US cities is driving demand for folding-blade configurations that reduce hangar footprint requirements.
- Performance-Based Logistics:Flight-hour availability contracts are shifting revenue from unit blade sales to long-term sustainment partnerships with military operators.
Industry Challenges
- Composite Repair Technician Scarcity:Non-destructive inspection and bonded repair of carbon fiber laminates requires specialized certification that outpaces vocational training pipeline output.
- Chordwise Mass Balance Precision:Achieving rotor track tolerance within fractions of a gram demands metrology investment that smaller tier-two suppliers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Blades Market |
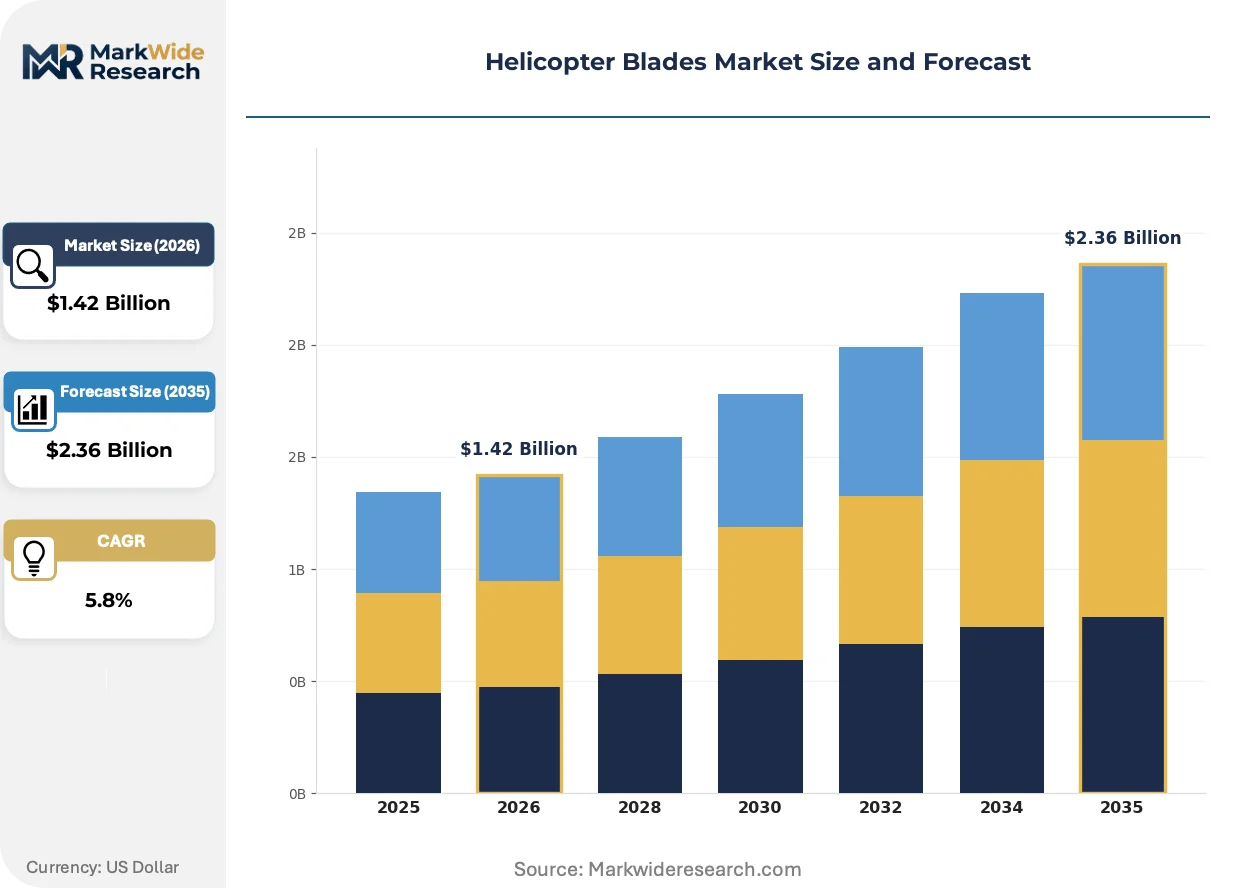
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Fixed, Folding, Rigid, Semi-Rigid Material: Aluminum, Composite, Carbon Fiber, Steel Application: Aerial Work, Medical Evacuation, Law Enforcement, Military Operations End User: Civil Aviation, Military, Oil & Gas, Search and Rescue |
| Companies Covered | Airbus Helicopters, Bell Textron Inc., Sikorsky Aircraft Corporation, Boeing, Lockheed Martin Corporation, Hindustan Aeronautics Limited, Van Horn Aviation, Carson Helicopters, Kaman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Blades Market Emerging Trajectories
Blade engineering is pivoting from incremental metallurgy improvements to radical composite architecture redesigns, with regulatory noise limits and sustainment economics now driving R&D allocation more than raw lift performance.
Thermoplastic resin systems are decentralizing repair infrastructure for military field operations. Marine Corps aviation units in expeditionary environments are adopting portable hot-bonding equipment that enables spar patching without depot-level support. This capability is compressing mean-time-to-repair metrics and reducing dependency on continental US overhaul facilities.
EASA CS-29 large rotorcraft standards are tightening damage tolerance demonstration requirements for composite blades. European OEMs must now prove residual strength after specified impact events, forcing redesign of leading-edge sheath attachments. Civil operators in Germany and France are absorbing certification delays while awaiting amended type certificates.
Power-by-the-hour contracting is consolidating blade procurement decisions under airframe OEMs rather than operator maintenance departments. Airlines and medical fleets are outsourcing availability risk to Sikorsky and Airbus Helicopters, who in turn are backward integrating into proprietary spar production. This channel shift is visible most acutely in US Army and Navy sustainment budgets, where flight-hour guarantees now dominate blade replacement scheduling.
Helicopter Blades Market Segmentation
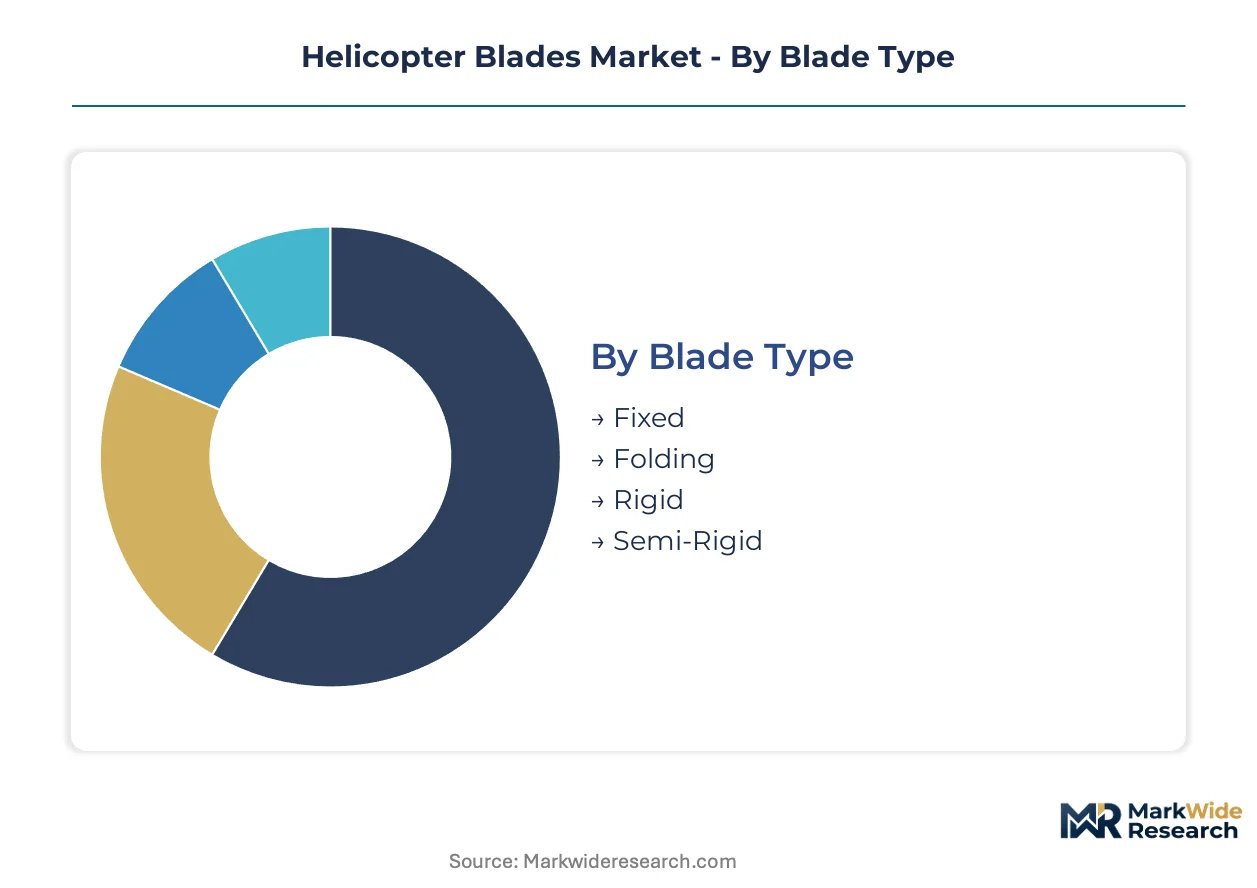
Blade procurement decisions in this market diverge sharply across operational environments, with military sustainment frameworks demanding flight-hour availability guarantees while civil operators prioritize hangar footprint reduction and acoustic compliance. Understanding these segment-specific buying logics reveals where pricing power concentrates and where suppliers must absorb availability risk.
Blade Type:
Rotor system architecture directly determines platform mission flexibility, with folding mechanisms commanding substantial premiums for naval and urban deployment scenarios.
- Fixed:Traditional hingeless designs dominate heavy-lift military platforms where structural simplicity maximizes reliability under high-cycle fatigue loading. Army and Navy sustainment budgets in the United States direct replacement demand toward these proven configurations.
- Folding:Articulated hub mechanisms reduce aircraft footprint for shipboard stowage and congested heliports. Hospital network expansion across secondary US cities is accelerating adoption for medical evacuation fleets where hangar space constraints bind.
- Rigid:Bearingless rotor systems eliminate elastomeric components to extend overhaul intervals. Oil and gas operators in the North Sea specify these for offshore platform resupply missions.
- Semi-Rigid:Teetering hub designs balance manufacturing cost with vibration isolation. Law enforcement fleets in Germany favor this architecture for patrol helicopter economics.
Fixed blades lead on scale; folding blades lead on momentum.
Material:
Material selection now pivots on sustainment economics rather than first-unit cost, with composite fatigue life advantages reshaping fleet modernization trade-offs.
- Aluminum:Machined spar extrusions from legacy 7075-T6 stock face accelerated obsolescence as composite alternatives displace them from NATO procurement specifications.
- Composite:Glass-reinforced laminates occupy mid-tier positioning between aluminum cost floors and carbon fiber performance ceilings. European OEMs specify these for training helicopter fleets where damage tolerance requirements moderate.
- Carbon Fiber:Prepregs with toughened epoxy matrices deliver superior damage tolerance and fatigue life exceeding ten million rotor revolutions. Automated fiber placement is compressing lead times for military spar replacements while raising capital barriers for new entrants.
- Steel:High-strength martensitic alloys retain niche application in tail rotor assemblies and wear-resistant leading-edge sheaths. Russian and Chinese domestic platforms continue specifying these for supply chain autonomy.
Carbon fiber dominates value capture; composite laminates anchor volume.
Application:
Mission profile severity dictates certification burden and aftermarket attachment rates, with military operators accepting higher unit costs for depot-level repairability.
- Aerial Work:External load operations in construction and logging impose high-cycle fatigue demands. Canadian operators in British Columbia drive demand for erosion-resistant leading-edge coatings on composite spars.
- Medical Evacuation:Hospital network expansion is accelerating fleet renewal cycles faster than military procurement. FAA Part 27 certification timelines in the United States govern blade replacement scheduling for air ambulance operators.
- Law Enforcement:Surveillance and patrol missions prioritize low acoustic signatures. EASA CS-29 noise standards are forcing acoustic redesign investments for European police aviation units.
- Military Operations:Combat search and rescue and assault transport specifications fall under DOD MIL-STD-810 environmental testing protocols. Performance-based logistics contracting is shifting procurement decisions from unit sales to flight-hour availability guarantees.
Military operations command procurement volume; medical evacuation exhibits the steepest expansion trajectory.
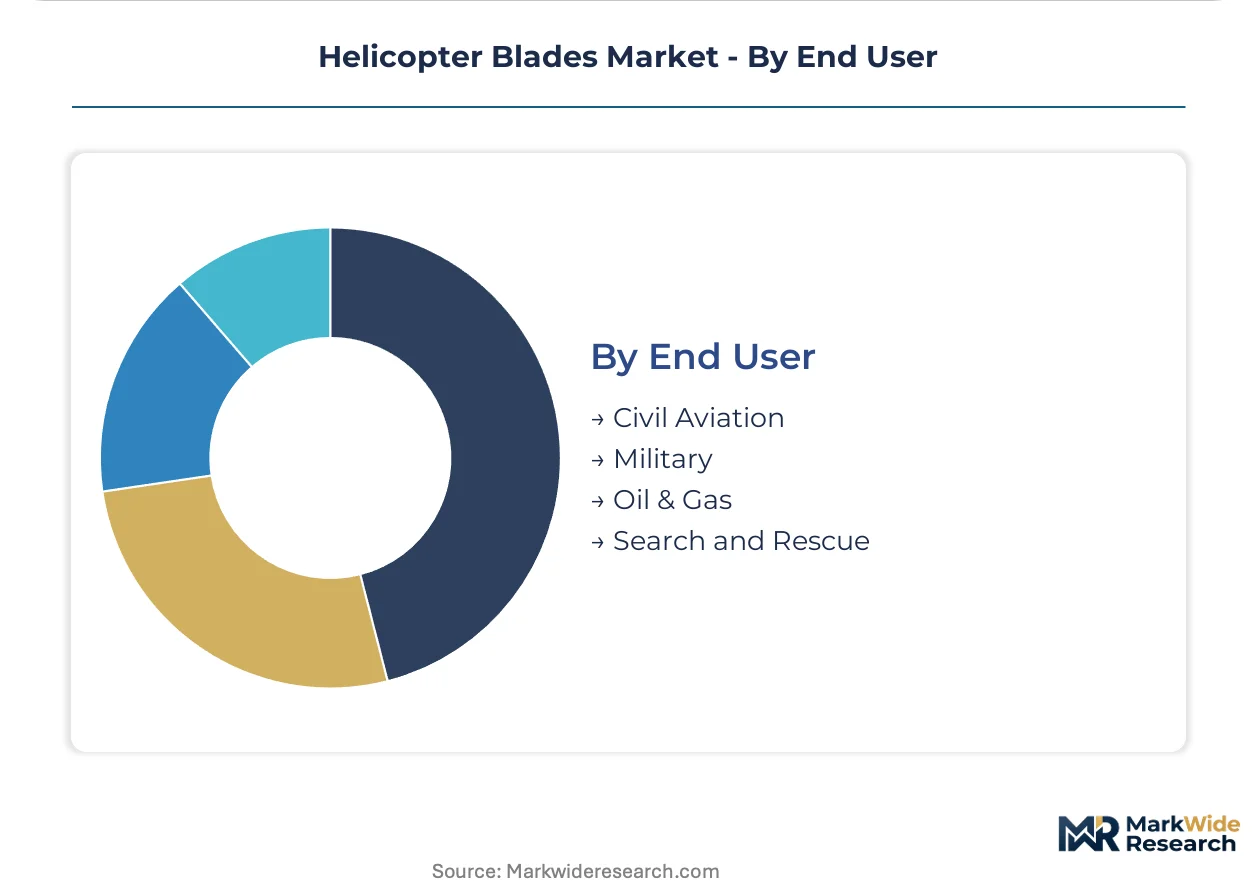
End User:
Customer type determines contract structure, with military frameworks consolidating purchasing power under airframe OEMs while civil operators fragment across independent maintenance departments.
- Civil Aviation:Corporate and charter operators prioritize dispatch reliability over unit economics. Power-by-the-hour contracting is consolidating blade procurement decisions under airframe OEMs rather than operator maintenance departments.
- Military:Army and Navy sustainment budgets in the United States direct blade replacement cycles through multi-year defense procurement frameworks. Flight-hour guarantees now dominate scheduling for UH-60 and CH-47 platforms.
- Oil and Gas:Offshore platform resupply demands corrosion-resistant root fittings and erosion-tolerant leading edges. North Sea operators specify these for salt spray exposure.
- Search and Rescue:All-weather operational requirements drive damage tolerance certification stringency. Coast Guard specifications in the United States mandate residual strength demonstration after specified impact events.
Military end users anchor contract value; civil aviation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting blade production toward jurisdictions with streamlined military airworthiness certification, as dual-track compliance burdens in mature markets raise effective production costs for composite spar manufacturers.
United States
Army and Navy sustainment budgets direct replacement cycles for UH-60 and CH-47 platforms through multi-year defense procurement frameworks. FAA Part 29 and DOD MIL-STD-810 protocols create dual-track compliance requirements for suppliers serving civil and military segments. Connecticut and Texas host concentrated OEM engineering centers where Sikorsky and Bell Textron anchor proprietary titanium root fitting production.
France
Airbus Helicopters leverages European military sustainment frameworks to secure long-term blade overhaul contracts across NATO fleets. EASA CS-29 standards govern large rotorcraft certification timelines and damage tolerance demonstration requirements. The Toulouse-Blagnac aerospace cluster concentrates composite prepreg manufacturing capabilities for military spar replacements.
Germany
Law enforcement aviation units prioritize low acoustic signatures under tightening EASA noise standards. REACH compliance migration forces suppliers to reformulate erosion-resistant leading-edge coating chemistries. Bavaria hosts specialized metallurgical forging capacity for high-strength titanium root attachments serving dual-use blade programs.
India
Domestic helicopter assembly programs under Hindustan Aeronautics Limited drive localized blade sourcing requirements. DGCA aligns civil certification with ICAO frameworks under bilateral recognition agreements, though military specifications follow indigenous standards. Bangalore and Hyderabad clusters develop composite repair technician training pipelines to address capability scarcity.
United Kingdom
Offshore oil and gas operators in the North Sea specify corrosion-resistant root fittings and erosion-tolerant leading edges for salt spray exposure. Military procurement through the Ministry of Defence sustains demand for heavy-lift platform blade replacements. The South West England aerospace corridor maintains legacy machining capacity for aluminum spar components facing accelerated obsolescence.
Helicopter Blades Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with airframe OEMs consolidating procurement decisions under power-by-the-hour contracting while independent blade shops compete on spot replacement availability. The vendor base organizes around three strategic archetypes: vertically integrated airframe manufacturers with captive spar production, specialized composite fabricators serving military depot networks, and regional overhaul shops focused on bonded repair services. Competitive moves center on backward integration into titanium forging capacity and automated fiber placement technology licensing to compress military lead times.
Within the integrated OEM tier, Airbus Helicopters and Sikorsky Aircraft Corporation exemplify the shift toward flight-hour availability guarantees, while Bell Textron occupies a position emphasizing civil platform specialization. These three anchors demonstrate how procurement consolidation under airframe manufacturers is displacing independent blade suppliers from long-term military sustainment contracts.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Bell Textron Inc. |
| Sikorsky Aircraft Corporation |
| Boeing |
| Lockheed Martin Corporation |
| Hindustan Aeronautics Limited |
| Van Horn Aviation |
| Carson Helicopters |
| Kaman Corporation |
| Others |
Supply Flow & Price Mechanics
Carbon fiber prepreg certification tiers separate flight-hour-guaranteed military spars from spot-market civil replacements, concentrating pricing power with automated fiber placement operators in Connecticut and Texas while fragmenting commodity aluminum spar sourcing across legacy machine shops. This bifurcation channels NATO procurement through vertically integrated OEMs commanding premium availability contracts, whereas independent repair stations compete on erosion-resistant leading-edge coating turnaround times.
Pricing Analysis
Distributor markups compress as power-by-the-hour contracting consolidates blade procurement decisions under airframe OEMs. Three-tier pricing structure across flight-hour availability, per-unit transactional, and spot repair tiers differentiates by certification grade and after-sales bundling intensity. Cost compression in legacy aluminum spar replacement intensifies because composite alternatives displace machined extrusions from NATO specifications. Civil medical evacuation operators exhibit highest price sensitivity due to hospital network budget constraints; military sustainment programs demonstrate lowest sensitivity under multi-year defense procurement frameworks.
Supply Chain Analysis
FAA Part 29 and DOD MIL-STD-810 dual-track qualification gating restricts spar fabrication to certified composite shops in the United States, France, and Germany. Raw material dependencies center on carbon fiber prepregs, toughened epoxy matrices, and high-strength titanium forgings. Single-source vulnerability concentrates in metallurgical forging capacity for root attachments. Distribution runs through military depot networks and civil OEM authorized service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Helicopter Blades Market functions as a stable compounder anchored by NATO fleet modernization schedules that sustain predictable replacement demand regardless of civil aviation cyclicality.
For Market Incumbents: Anchor proprietary titanium root fitting production through backward integration into Bavarian and Connecticut forging capacity to defend against emerging Asian composite entrants. Secure automated fiber placement technology licenses to compress military lead times. Lock in multi-year performance-based logistics contracts with Army and Navy sustainment programs before flight-hour availability standardization commoditizes pricing. For New Entrants and Emerging Players: Regional overhaul shops in India and Southeast Asia represent the most penetrable channel partner type for bonded repair service specialization. Target medical evacuation fleet expansion in secondary US cities where folding-blade hangar footprint constraints create upgrade demand. Pursue portable hot-bonding equipment partnerships with expeditionary military units to bypass continental US depot dependency. For Investors and Strategic Acquirers: Consolidation pressure builds where composite repair technician certification scarcity constrains aftermarket service expansion. Five-to-ten year viability favors suppliers with captive automated fiber placement capacity and dual-use civil-military certification portfolios. Signal to watch: EASA CS-29 damage tolerance demonstration requirement amendments forcing European OEM redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Licensing | Compresses military spar replacement lead times for Sikorsky and Airbus Helicopters. |
| Performance-Based Logistics Contracting | Shifts revenue from unit blade sales to Army and Navy flight-hour availability guarantees. |
| Titanium Root Forging Backward Integration | Secures captive supply of high-strength attachments against single-source metallurgical risk. |
| Portable Hot-Bonding Equipment Deployment | Enables Marine Corps expeditionary repair without continental US depot dependency. |
| REACH-Compliant Coating Reformulation | Forces European suppliers to upgrade erosion-resistant leading-edge chemistries. |
Methodological Framework
Bottom-up military and civil fleet modeling reconciled against top-down composite prepreg supply tracking forms the analytical core of this study. Primary interviews with blade program managers at airframe OEMs, military depot operations officers, composite repair technicians, and hospital network aviation procurement directors combined with secondary validation from FAA airworthiness directive filings, DOD procurement databases, EASA type certificate amendments, and NATO defense expenditure reports. Triangulation across these sources ensures demand-side fleet projections align with supply-side manufacturing capacity.
Input-output matrices map carbon fiber prepreg consumption to spar fabrication throughput across blade type, material grade, application severity, and end-user contract structure segments. CAGRs derive from regression analysis of historical replacement cycles projected across the analysis window. Industry-specific forecast inputs include UH-60 and CH-47 platform sustainment schedules, medical evacuation fleet renewal timelines, and ICAO Chapter 14 noise standard implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to composite material substitution rates and urban air mobility platform certification delays. Projections reflect assumptions regarding NATO defense budget continuity and REACH compliance migration timelines. A model refresh is warranted upon material change in military flight-hour availability contracting penetration or EASA damage tolerance demonstration requirement amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market