

Enclosure Support Arm Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Enclosure Support Arm Systems Market Insights
Asset-light leasing models for industrial automation infrastructure is reconfiguring competitive dynamics in enclosure support arm procurement, allowing mid-sized facilities to access premium articulating systems without capital-heavy balance sheet commitments. ROSE Systemtechnik leverages its vertical integration into aluminum extrusion and powder-coat finishing to control lead times for custom enclosure pairings. Siemens anchors its position through channel dominance in integrated building technology packages that bundle support arms with power distribution units.
Enclosure support arm systems are mechanical articulating assemblies, typically fabricated from aluminum or steel with sealed bearing joints and adjustable counterbalance mechanisms, designed to suspend, position, and route cables to control enclosures, monitors, or interface panels in industrial and commercial environments. The electric and counterbalance technology segments command margin concentration due to precision motorization and ergonomic load-compensation requirements in medical and broadcast applications, while mechanical arms retain volume leadership in cost-sensitive manufacturing deployments. Multi-joint and telescopic arm configurations are capturing expanded application scope as data center rack densities and broadcast studio flexibility demands intensify.
CE marking under the EU Machinery Directive and compliance with ISO 11226 ergonomic lifting standards shape product certification requirements for European market access, while OSHA workplace ergonomics guidelines influence North American specification criteria for repetitive-adjustment duty cycles. The FCC's equipment authorization framework indirectly governs integrated cable routing for electromagnetic compatibility in command center and telecommunications deployments. Stakeholders must monitor evolving interoperability standards between support arm systems and smart building management platforms as facility digitization accelerates specification complexity.
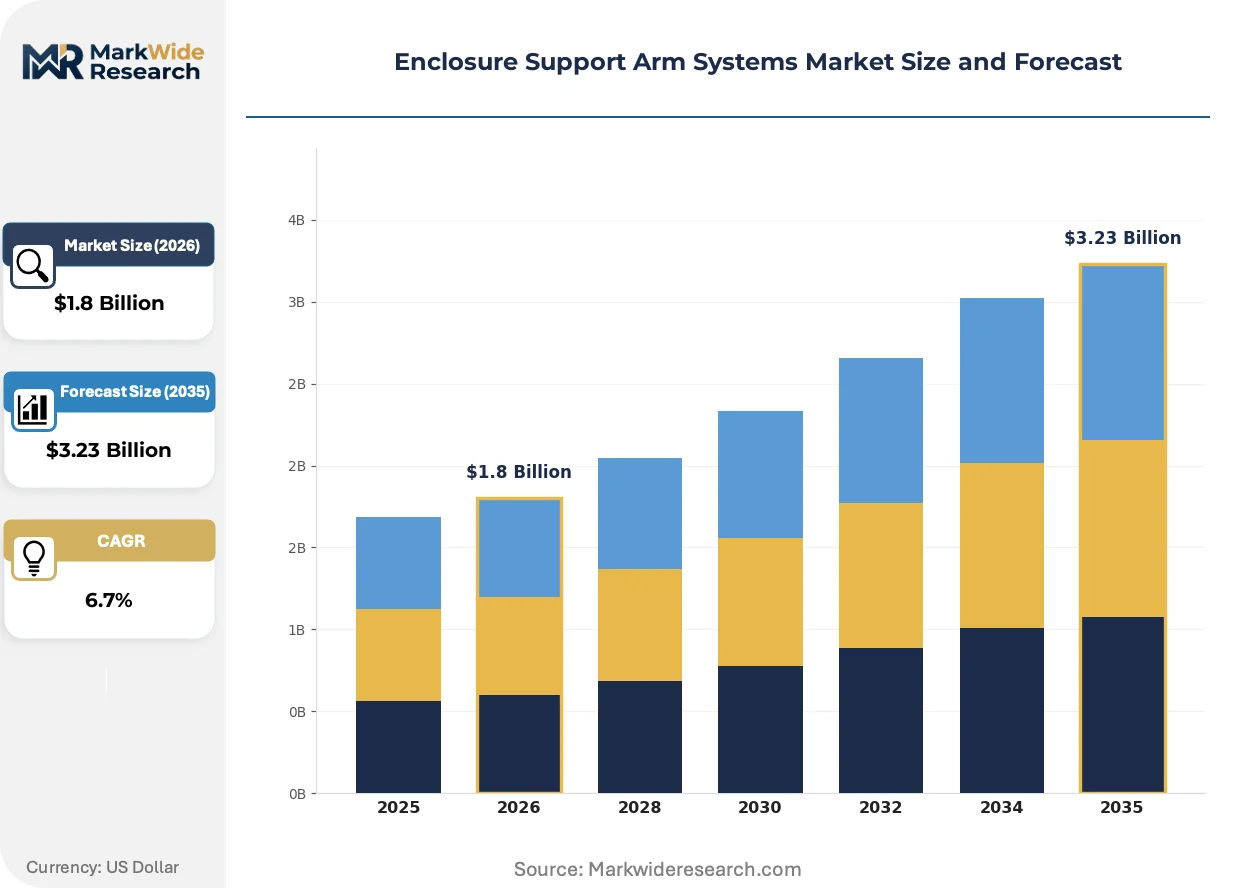
Market Dynamics
Medical OEMs in Germany and the US are consolidating supplier relationships around single-source articulating arm platforms that integrate ISO 11226 ergonomic certification with embedded cable management, compressing procurement cycles for surgical suite builders.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for adjustable load-bearing assemblies are forcing industrial automation buyers to replace legacy mechanical arms with certified counterbalance systems in automotive assembly plants.
- Aluminum extrusion process advances:Stuttgart-area precision engineering clusters have reduced lead times for custom hollow-section arm tubing, enabling faster turnaround for diagnostic equipment OEMs.
- Diagnostic imaging suite expansion:Hospital capital expenditure on MRI and CT mounting infrastructure is pulling multi-joint articulating configurations into radiology department retrofits across tertiary care networks.
Market Restraints
- Aluminum alloy price volatility:LME aluminum fluctuations compress margin buffers for mid-tier fabricators dependent on spot-market raw material sourcing.
- Precision bearing supply concentration:Sealed joint assemblies for high-cycle medical applications rely heavily on Baden-Württemberg component suppliers, creating single-source vulnerability.
- Electromechanical substitution pressure:Linear actuator-based positioning systems are capturing share in fixed-mount industrial monitoring applications where articulation range is limited.
Strategic Opportunities
- India healthcare infrastructure buildout:PLI scheme incentives for medical device manufacturing are opening procurement channels for cost-optimized mechanical arm configurations in diagnostic imaging.
- Smart building management convergence:Integration protocols between articulating arm position sensors and BACnet-enabled facility automation platforms are creating specification pull from commercial building integrators.
- OSHA ergonomic enforcement expansion:Workplace adjustment mandate coverage for repetitive-motion injury prevention is accelerating replacement demand in North American control room deployments.
Industry Challenges
- Mechatronics engineering talent scarcity:Shortage of designers fluent in both mechanical counterbalance physics and motor control firmware is delaying electric arm development cycles.
- Multi-joint fatigue testing bottlenecks:ISO 11226 validation protocols for extended-reach configurations require specialized test rigs with 18-month calibration queues at accredited German laboratories.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enclosure Support Arm Systems Market Trends and Innovations
Digital twin workflows are compressing design validation cycles for articulating arm assemblies, while regulatory pressure on workplace ergonomics is embedding sensor feedback into next-generation counterbalance mechanisms.
Digital twin simulation software is virtualizing the structural load-testing phase for multi-joint arm configurations, allowing Munich-based engineering teams to iterate bearing joint geometries without physical prototyping. Medical device OEMs in Bavaria are adopting these virtualized workflows to accelerate FDA pre-submission documentation for surgical suite mounting systems. The compression of validation timelines is virtualizing competitive advantage toward firms with captive simulation capabilities rather than traditional metal-bending scale.
REACH restrictions on hexavalent chromium surface treatments are forcing powder-coat finishing transitions across European supply chains, eliminating legacy electroplating options for aluminum arm assemblies. Automotive tier-one suppliers in Stuttgart are responding by qualifying ceramic-based coating alternatives that maintain salt-spray corrosion resistance for factory-floor deployments. The regulatory friction is concentrating finishing capability among vertically integrated extruders with in-house thermal spray investment.
Outcome-based service contracting is displacing capital purchase models for broadcast studio infrastructure, with arm system vendors retaining ownership and charging per-adjustment-cycle fees. Production facility operators in Los Angeles and London are accepting these arrangements to align mounting hardware costs with project-based revenue volatility. The shift is most visible in streaming content creation verticals where equipment utilization fluctuates with commissioning schedules.
Enclosure Support Arm Systems Market Segmentation
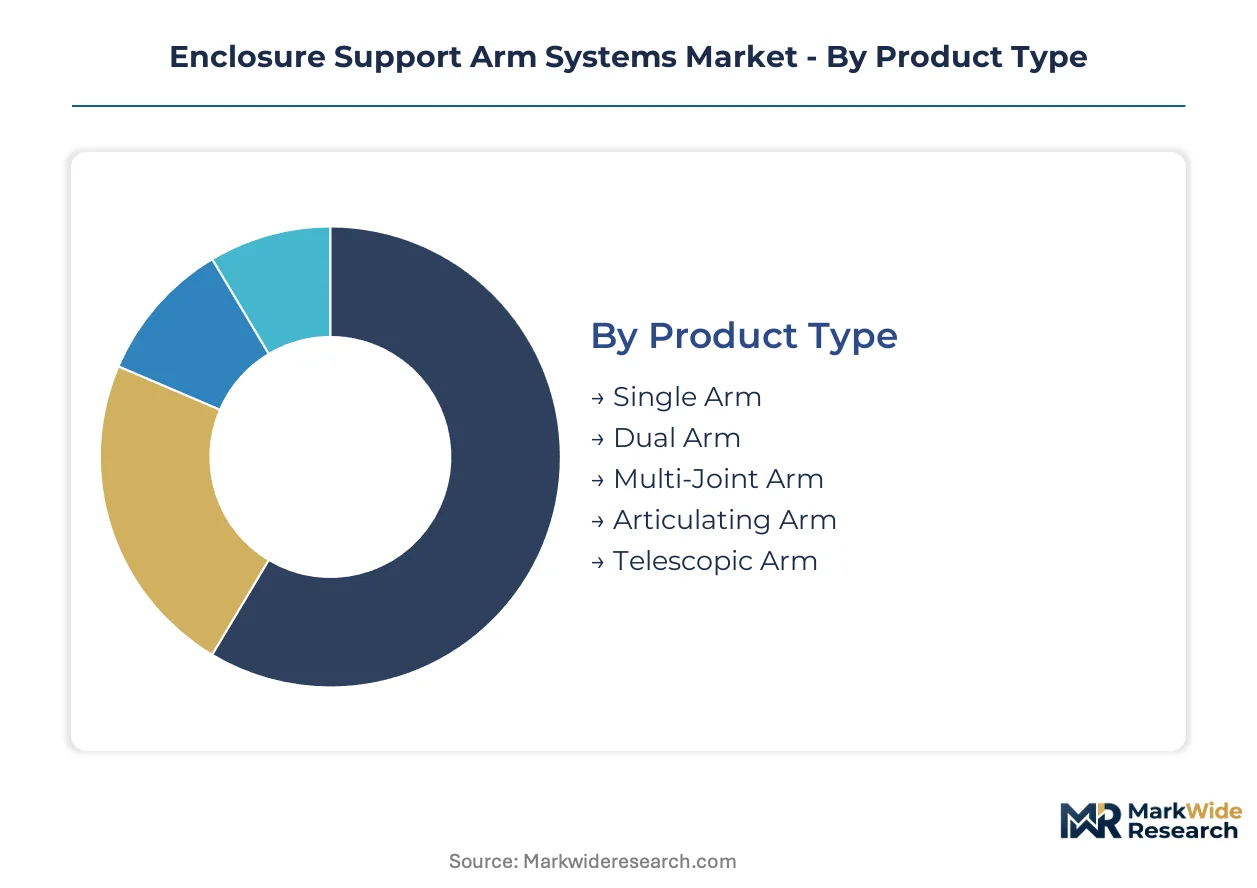
Enclosure support arm systems fragment across mechanical complexity, actuation physics, deployment environment, and procurement authority. These dimensions determine certification requirements, margin structure, and replacement cycle velocity for fabricators and system integrators.
Product Type:
Mature configurations dominate installed base maintenance, while emerging geometries capture specification shifts toward extended reach and compact stowage in high-density environments.
- Multi-Joint Arm:Sealed bearing assemblies with four to seven degrees of freedom enable surgical suite positioning where ISO 11226 ergonomic compliance is mandatory. German diagnostic OEMs in Bavaria specify these for MRI mounting infrastructure, pulling demand from tertiary care network capital expenditure programs.
- Telescopic Arm:Nested aluminum tubing sections extend operational reach while minimizing stowed footprint for data center aisle constraints. Hyperscale facility operators in Frankfurt and Amsterdam specify these for high-density rack access where aisle width is fixed.
- Single Arm:Fixed-pivot cantilever designs serve cost-sensitive manufacturing monitoring stations with minimal adjustment duty cycles.
- Dual Arm:Parallel linkage configurations stabilize heavy control enclosures in automotive assembly plant human-machine interface stations.
- Articulating Arm:Two to three pivot joint assemblies balance flexibility with mechanical simplicity for broadcast studio camera control mounting.
Multi-Joint Arm retains volume leadership; Telescopic Arm holds the steepest expansion curve.
Technology:
Actuation method determines precision, maintenance burden, and regulatory exposure across deployment contexts.
- Electric:Servo motor positioning with encoder feedback enables sub-millimeter repeatability for surgical navigation system mounting. Medical device manufacturers in Stuttgart specify these for FDA pre-submission pathways, though mechatronics engineering scarcity extends development timelines.
- Counterbalance:Spring or gas-spring load compensation eliminates motorization while maintaining fingertip adjustability across the full motion envelope. Broadcast studio integrators in Los Angeles favor these for silent operation during live production.
- Hydraulic:Fluid power actuation persists in heavy industrial applications where load capacity exceeds electric motor torque density.
- Pneumatic:Compressed air systems serve explosive atmosphere classifications in chemical processing facilities where electrical spark risk is prohibited.
- Mechanical:Friction and detent-based positioning retains specification in cost-optimized diagnostic imaging deployments where adjustment frequency is low.
Counterbalance commands margin concentration; Electric is climbing the fastest.
Application:
Environmental severity and uptime requirements differentiate specification criteria across deployment settings.
- Medical Facilities:Surgical suites and diagnostic imaging departments demand ISO 11226 ergonomic certification, sealed bearing construction for sterilization compatibility, and embedded cable management for electromagnetic compatibility. Hospital capital expenditure on MRI and CT infrastructure drives specification in German tertiary care networks.
- Data Centers:Hyperscale and colocation operators prioritize tool-free adjustment, hot-swap cable routing, and seismic restraint compliance for rack-mounted infrastructure. Frankfurt and Amsterdam facility expansions concentrate demand for telescopic configurations.
- Broadcast Studios:Production control rooms and on-air camera platforms require silent operation, rapid repositioning, and aesthetic integration with set design.
- Manufacturing Units:Automotive assembly and electronics fabrication specify high-cycle durability with minimal maintenance access for continuous operation environments.
- Command Centers:Security and telecommunications operations demand 24/7 availability with redundant positioning verification for critical monitoring functions.
Medical Facilities retain volume leadership; Data Centers hold the steepest expansion curve.
End User:
Procurement authority and capital allocation cycles shape vendor relationship structures and contract terms.
- Healthcare Institutions:Hospital systems and integrated delivery networks consolidate supplier relationships around single-source platforms that bundle ergonomic certification with installation validation. German medical OEMs compress procurement cycles through pre-qualified vendor lists.
- Industrial Plants:Automotive tier-one suppliers and electronics manufacturers prioritize total cost of ownership calculations over initial acquisition price, favoring high-duty-cycle counterbalance systems.
- Telecommunication Providers:Network operations centers and central office facilities specify integrated cable management for copper and fiber routing with electromagnetic shielding.
- Broadcast Networks:Streaming content creators and traditional broadcasters are shifting toward outcome-based service contracting to align mounting hardware costs with project-based revenue volatility.
- Security Agencies:Government command centers mandate domestic supply chain provenance and extended warranty terms for critical infrastructure protection.
Healthcare Institutions retain volume leadership; Broadcast Networks hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in enclosure support arm systems reveal concentrated production in German precision engineering clusters against rising import dependence in North American healthcare infrastructure. Trade flows favor intra-European component sourcing while Asian medical device manufacturing drives outbound demand for certified articulating assemblies.
Germany
Automotive assembly plant modernization and diagnostic imaging suite retrofits sustain demand for ISO 11226-certified counterbalance systems. CE marking under the EU Machinery Directive tightens compliance timelines for adjustable load-bearing assemblies. Stuttgart and Munich engineering clusters supply high-duty-cycle arm configurations to domestic OEMs and export markets.
United States
Hospital capital expenditure on MRI and CT mounting infrastructure pulls multi-joint articulating configurations through tertiary care networks. OSHA workplace ergonomics guidelines accelerate replacement demand in control room deployments for repetitive-motion injury prevention. Los Angeles broadcast studios adopt outcome-based service contracting for camera control mounting systems.
China
Data center hyperscale expansions in the Yangtze River Delta concentrate procurement for telescopic arm configurations with hot-swap cable routing. GB standards for mechanical safety equipment shape domestic certification requirements for industrial automation buyers. Shanghai facility operators prioritize seismic restraint compliance for high-density rack access infrastructure.
India
PLI scheme incentives for medical device manufacturing open procurement channels for cost-optimized mechanical arm configurations in diagnostic imaging. BIS certification requirements for imported industrial machinery create compliance friction for European suppliers. Maharashtra healthcare infrastructure buildout concentrates demand in Mumbai-Pune medical device corridors.
Japan
Broadcast studio digitization and surgical navigation system mounting sustain specification for sub-millimeter repeatability electric arm systems. METI industrial standards for ergonomic workplace equipment influence procurement criteria in manufacturing facilities. Osaka-area precision component suppliers feed bearing joint assemblies to domestic medical device OEMs.
Enclosure Support Arm Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in bearing joint and extrusion supply. The vendor base stratifies across three tiers: multinational building technology conglomerates bundling support arms with power distribution, regional enclosure fabricators with captive aluminum finishing, and precision component suppliers concentrated in Baden-Württemberg. Dominant competitive moves include backward integration into extrusion and thermal spray capabilities, plus outcome-based service contracting displacing capital purchase models in broadcast verticals.
Among German-based fabricators, ROSE Systemtechnik GmbH exemplifies the vertically integrated archetype with in-house aluminum extrusion and powder-coat finishing control. Phoenix Mecano AG and ROLEC Gehäuse-Systeme GmbH occupy positions within the precision enclosure tier serving industrial automation and medical OEM procurement channels. Siemens AG anchors the platform integrator segment through channel dominance in bundled building technology packages.
| Leading Market Players |
|---|
| ROSE Systemtechnik |
| Phoenix Mecano |
| ROLEC Gehäuse-Systeme |
| Delvalle Box |
| Siemens |
| Ergotron |
| Legrand |
| Fellowes |
| Oasys |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg precision engineering clusters around Stuttgart and Munich concentrate bearing joint and aluminum extrusion capacity, translating upstream supply discipline into asymmetric pricing power for certified counterbalance system fabricators serving medical OEM procurement channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation stems from ISO 11226 ergonomic certification grade and captive aluminum finishing capability. Cost compression in economy mechanical arms is intensifying because spot-market aluminum alloy sourcing exposes mid-tier fabricators to LME volatility. Hospital systems show least price sensitivity due to bundled installation validation requirements, while cost-optimized diagnostic imaging deployments in emerging markets exhibit highest sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for European fabricators serving Asian medical device manufacturing expansion. Component sourcing concentrates in Germany, Japan, and China. Precision bearing joint assemblies and hollow-section aluminum tubing constitute critical input dependencies. Single-source vulnerability persists for sealed medical-grade bearings from Baden-Württemberg suppliers. Distribution runs through direct OEM procurement channels and building technology integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity in mechatronics—specifically designers fluent in both mechanical counterbalance physics and motor control firmware—creates competitive asymmetry favoring firms with captive simulation and rapid prototyping capabilities.
For Market Incumbents: Build captive digital twin simulation capacity to compress FDA pre-submission validation cycles for surgical suite mounting systems. Deepen backward integration into aluminum extrusion and ceramic-based thermal spray finishing to neutralize REACH compliance friction. Defensive positioning requires neutralizing electromechanical substitution pressure from linear actuator-based positioning systems in fixed-mount industrial monitoring applications. For New Entrants and Emerging Players: Build out cost-optimized mechanical arm configurations for India's PLI scheme-enabled medical device manufacturing corridors, where BIS certification friction disadvantages European suppliers. Target diagnostic imaging OEMs in Maharashtra's Mumbai-Pune corridor with localized assembly partnerships. Go-to-market execution should leverage outcome-based service contracting models proven in Los Angeles broadcast studio verticals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated fabricators with in-house powder-coat finishing and bearing joint assembly capability. Long-term viability hinges on exposure to medical facility capital expenditure cycles and data center hyperscale expansion rather than cyclical industrial automation replacement demand. Monitor OSHA ergonomic enforcement expansion in North American control room deployments as inflection signal for counterbalance system replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | ROSE Systemtechnik's captive supply of hollow-section tubing neutralizes lead time volatility for custom diagnostic equipment pairings. |
| Digital Twin Workflow Deployment | Munich engineering teams leveraging virtualized load-testing compress ISO 11226 validation timelines without physical prototyping bottlenecks. |
| Outcome-Based Service Contracting | Los Angeles broadcast studios accepting per-adjustment-cycle fees align mounting hardware costs with project-based commissioning volatility. |
| Ceramic-Based Coating Qualification | Stuttgart automotive tier-one suppliers responding to REACH hexavalent chromium restrictions maintain salt-spray corrosion resistance. |
| Smart Building Protocol Integration | Articulating arm position sensor interoperability with BACnet-enabled platforms creates specification pull from commercial building integrators. |
Research Methodology
Cross-validation between primary interviews with surgical suite builders, diagnostic equipment OEM procurement leads, hospital biomedical engineers, and GPO contracts managers anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings for surgical navigation mounting systems, EU Machinery Directive CE marking databases, OSHA workplace ergonomics enforcement records, and hospital capital expenditure tracking databases. Bottom-up demand modeling triangulates against top-down macroeconomic calibration.
Calibration against historical replacement cycle data and announced facility expansion pipelines shapes the analytical framework across the analysis window. Segmentation dimensions include product type complexity, actuation technology physics, deployment environment severity, and procurement authority concentration. CAGRs derive from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporate PLI scheme incentive disbursement timelines and data center hyperscale capex disclosure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese aluminum extruders or accelerated electromechanical substitution in industrial monitoring would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.