
 Inlet Lip Anti-Icing and De-Icing Component Systems Market | 2026-2036
Inlet Lip Anti-Icing and De-Icing Component Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Inlet Lip Anti-Icing and De-Icing Component Systems Market Insights
EU Green Deal aviation decarbonization targets is hardening sustainability mandates across European procurement chains. RTX leverages its thermal systems expertise to anchor long-term supplier contracts with regional airframers. Textron specializes in integrated electrothermal architectures for business aviation platforms. John Bean Technologies competes through ground-based de-icing equipment that complements airborne inlet lip systems at major hubs.
Inlet lip anti-icing and de-icing component systems integrate thermal, pneumatic, and electrothermal subsystems bonded to engine nacelle leading edges, typically operating at power densities between 5 and 15 kW per square meter to maintain ice-free surfaces during descent and hold patterns. These systems prevent ice accretion that degrades aerodynamic performance, engine stability, and fuel efficiency across turbine-powered aircraft. Electrothermal elements command the dominant share of new platform designs due to lighter weight and precise zone control, while bleed air systems retain installed-base dominance on legacy narrow-body fleets. Hot air circulation technology faces displacement pressure as electric heating architectures advance on next-generation propulsion concepts, though pneumatic boots sustain relevance in rotorcraft where electrical load budgets remain constrained.
FAA airworthiness standards under Part 25 Appendix C govern ice certification requirements for transport category aircraft, while EASA CS-25 harmonizes European type certification with equivalent icing envelope specifications. The EPA regulates chemical de-icing fluid discharges under NPDES permitting, pushing operators toward closed-loop ground systems and advanced hydrophobic coatings that reduce glycol dependency. Stakeholders must monitor evolving OEM propulsion strategies around hybrid-electric and hydrogen combustion architectures, as thermal management priorities will redefine inlet lip system specifications before current fleet replacement cycles conclude.
Market Dynamics
Electrothermal architectures are displacing pneumatic bleed-air systems across next-generation narrow-body and regional jet platforms, compressing supplier development cycles and recalibrating thermal management specifications for hybrid-electric propulsion concepts.
Growth Catalysts
- FAA Part 25 Appendix C Certification Stringency:Tighter ice-envelope testing requirements for transport category aircraft are mandating redundant heating zones and advanced sensor integration on inlet lip assemblies.
- Commercial Fleet Modernization:North American airlines are specifying electrothermal systems with zone-specific power modulation for new-generation single-aisle deliveries.
- Ground Glycol Discharge Restrictions:EPA NPDES permitting constraints at major US hubs are accelerating closed-loop de-icing infrastructure that complements airborne anti-icing system deployment.
Market Restraints
- Electrical Load Budget Constraints in Rotorcraft:Helicopter electrical system limitations preserve pneumatic boot dominance, fragmenting supplier R&D investment across incompatible thermal architectures.
- Certification Timeline Compression:EASA CS-25 harmonization delays with evolving FAA icing envelope interpretations extend type certification cycles for multi-regional platform approvals.
- Nickel-Chromium Alloy Supply Concentration:Heating element substrate sourcing clusters in limited metallurgical processing regions, exposing electrothermal system manufacturers to input price volatility.
Strategic Opportunities
- Urban Air Mobility Thermal Management:eVTOL platforms require distributed electrothermal protection for distributed propulsion nacelles with severe weight and power-draw constraints.
- Hydrogen Combustion Architecture Adaptation:Cryogenic fuel systems demand redesigned inlet lip heating profiles to manage thermal gradients between hydrogen storage and engine airflow.
- EU Green Deal Aviation Decarbonization:Sustainability-linked procurement mandates favor lightweight electrothermal systems with documented lifecycle carbon reductions over pneumatic alternatives.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled thermal-structural-aerodynamic modeling for ice accretion prediction requires specialized computational fluid dynamics expertise concentrated at limited academic and national laboratory centers.
- Legacy Platform Retrofit Integration:Electrothermal system backfit onto bleed-air-designed nacelles demands structural reinforcement and electrical harness routing through certified pressure bulkheads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inlet Lip Anti-Icing and De-Icing Component Systems Market |
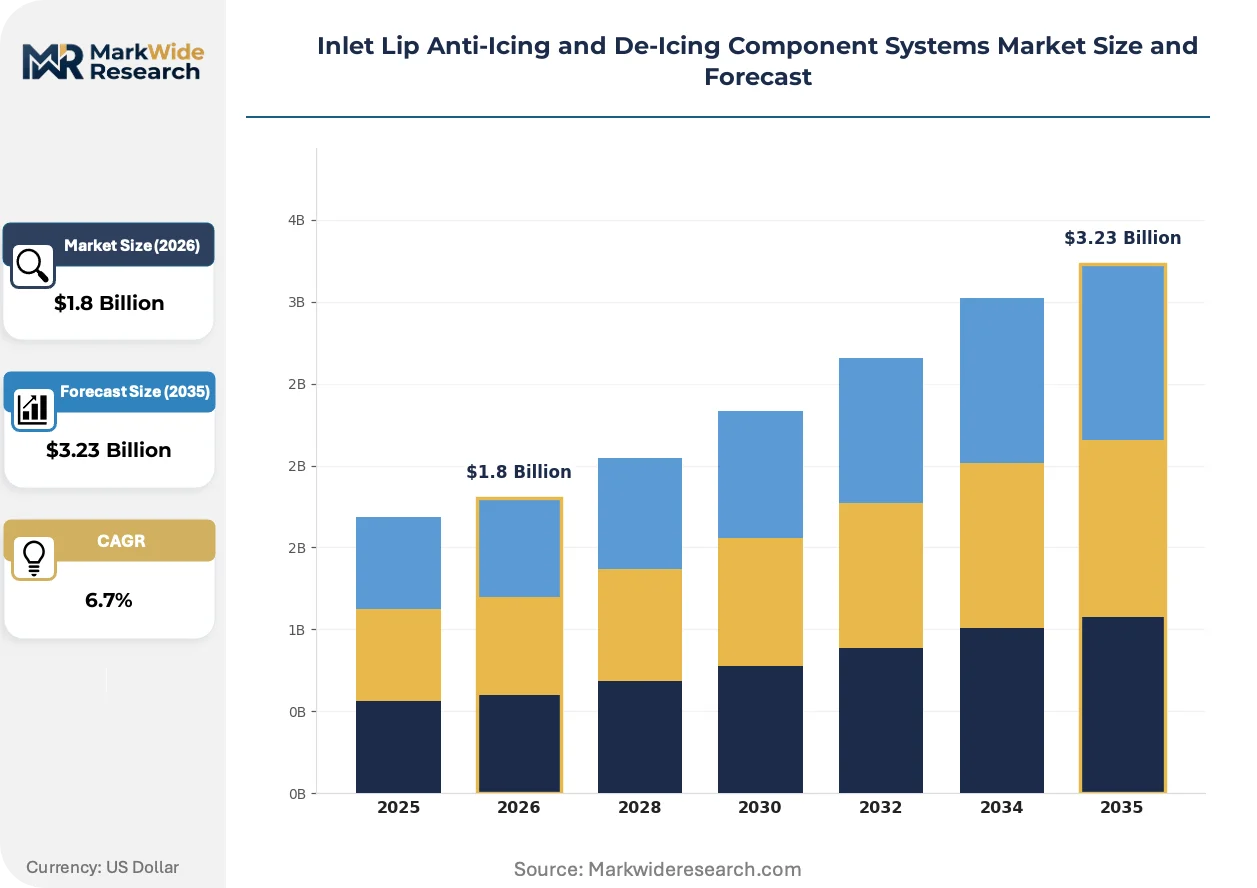
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Thermal Systems, Electrothermal Elements, Pneumatic Boots, Bleed Air Systems, Hydrophobic Coatings Technology: Electric Heating, Hot Air Circulation, Chemical Application, Microwave Heating, Phase Change Materials Application: Commercial Aircraft, Military Jets, Business Aviation, Rotorcraft, Unmanned Aerial Vehicles End User: Airframe Manufacturers, Component Suppliers, Maintenance Repair Operators, Airlines |
| Companies Covered | RTX, Textron, General Atomics, John Bean Technologies, Vestergaard Company, Global Ground Support, Inland Group of Companies, Mallaghan, Tronair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inlet Lip Anti-Icing and De-Icing Component Systems Market Trends and Innovations
Carbon nanotube heating films and predictive ice-detection algorithms are converging to enable responsive, zone-optimized thermal protection that minimizes power draw while maintaining aerodynamic surface integrity.
Carbon nanotube conductive heating elements bonded directly to composite nacelle skins eliminate metallic mesh substrates and reduce system mass by approximately one-third versus conventional wire-wound mats. Boeing and Airbus tier-one suppliers are qualifying these films for next-generation single-aisle programs with 2028-2032 entry-into-service targets. This materials transition is rewriting supplier qualification requirements, favoring composite specialists with thin-film deposition capabilities over legacy wire-harness manufacturers.
The EU F-Gas Regulation phase-down of high-global-warming-potential fluorinated gases is restricting pneumatic system working-fluid options and accelerating electrothermal migration in European-registered fleets. Industrial consequence includes stranded engineering investment in optimized bleed-air ducting and valve architectures. European regional airframers are responding by pre-specifying all-electric thermal protection on clean-sheet designs, compressing the addressable market for pneumatic subsystem suppliers.
Airline technical procurement teams are consolidating vendor relationships from discrete component sourcing to integrated thermal system packages spanning sensors, controllers, and heating elements. This bundling displaces fragmented multi-vendor integration responsibility onto tier-one aerostructures suppliers. The shift is most visible in United States-based carrier fleet renewal programs, where single-source accountability for ice protection system airworthiness is reducing contractual interface complexity.
Inlet Lip Anti-Icing and De-Icing Component Systems Market Segmentation
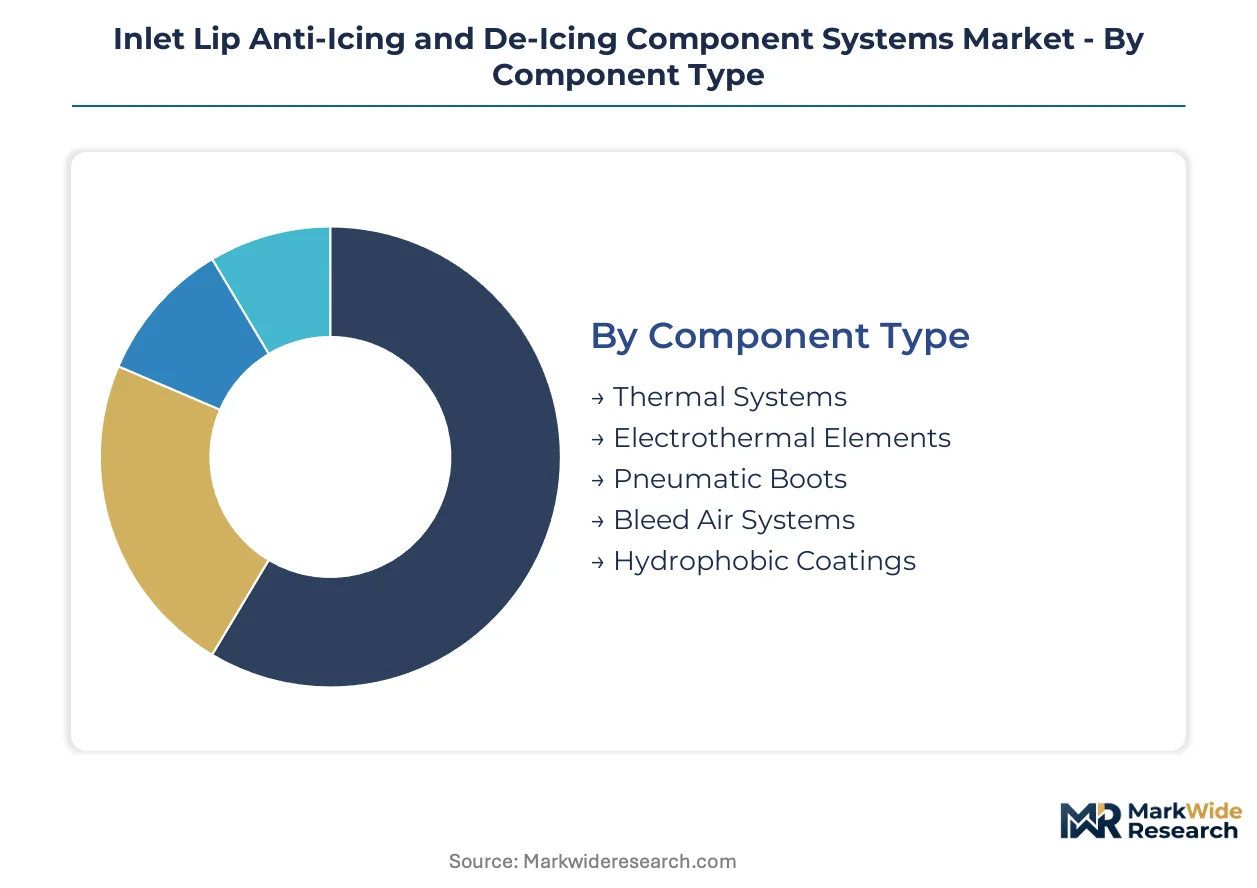
Inlet lip anti-icing and de-icing component systems fragment across thermal architectures, propulsion platforms, and procurement channels. Buyer decisions hinge on weight penalties, electrical load budgets, and certification pathway complexity for each target airframe program.
Component Type:
Platform weight targets and power density specifications drive supplier selection across heating architectures.
- Electrothermal Elements:Thin-film conductive heaters bonded to composite nacelle skins deliver zone-specific temperature control at 5-15 kW per square meter. Demand concentrates in United States-based carrier fleet renewal programs where single-aisle OEMs mandate reduced mass versus bleed-air alternatives.
- Thermal Systems:Integrated packages combining sensors, controllers, and heating matrices into unified nacelle assemblies. Procurement is shifting toward tier-one aerostructures suppliers bundling complete ice protection accountability for airframers.
- Pneumatic Boots:Expandable rubber membranes deployed on rotorcraft and legacy turboprops where electrical generation capacity remains constrained.
- Bleed Air Systems:Hot air ducting tapped from engine compressors retains installed-base dominance on aging narrow-body fleets facing replacement cycles.
- Hydrophobic Coatings:Advanced surface treatments reducing glycol dependency for ground-based de-icing operations at EPA-regulated United States hubs.
Volume sits with Bleed Air Systems; growth tilts toward Electrothermal Elements.
Technology:
Energy efficiency mandates and FAA Part 25 Appendix C certification stringency are recalibrating heating method preferences across new platform development.
- Electric Heating:Resistive wire and carbon nanotube architectures enabling precise zone modulation with reduced power draw during hold patterns. United States single-aisle programs specify these systems for entry-into-service timelines.
- Hot Air Circulation:Engine bleed extraction through regulated valves and insulated ducting faces displacement pressure as hybrid-electric propulsion concepts reduce available compressor tap points.
- Chemical Application:Glycol-based ground de-icing constrained by EPA NPDES discharge permitting at major operational hubs.
- Microwave Heating:Emerging volumetric ice melting for specialized military applications requiring rapid thermal response.
- Phase Change Materials:Latent heat storage systems under evaluation for eVTOL platforms with severe transient power limitations.
Deployment share clusters with Electric Heating; steepest expansion trajectory belongs to Phase Change Materials in urban air mobility segments.
Application:
Mission profiles and electrical architecture maturity determine thermal system specification across aviation categories.
- Commercial Aircraft:Transport category platforms governed by FAA Part 25 Appendix C and EASA CS-25 icing envelope requirements. Fleet modernization in North America specifies electrothermal zone control for next-generation narrow-body deliveries.
- Rotorcraft:Helicopter electrical load budgets preserve pneumatic boot relevance, fragmenting supplier R&D investment across incompatible thermal architectures.
- Business Aviation:Integrated electrothermal architectures from Textron and comparable OEMs targeting premium cabin segments with weight-sensitive nacelle designs.
- Military Jets:Specialized microwave and hybrid heating systems for combat aircraft operating in extreme icing envelopes beyond civil certification standards.
- Unmanned Aerial Vehicles:Minimal power-draw electrothermal films for long-endurance surveillance platforms with constrained onboard generation.
Procurement volume concentrates in Commercial Aircraft; technology adaptation is climbing the fastest in Unmanned Aerial Vehicles.
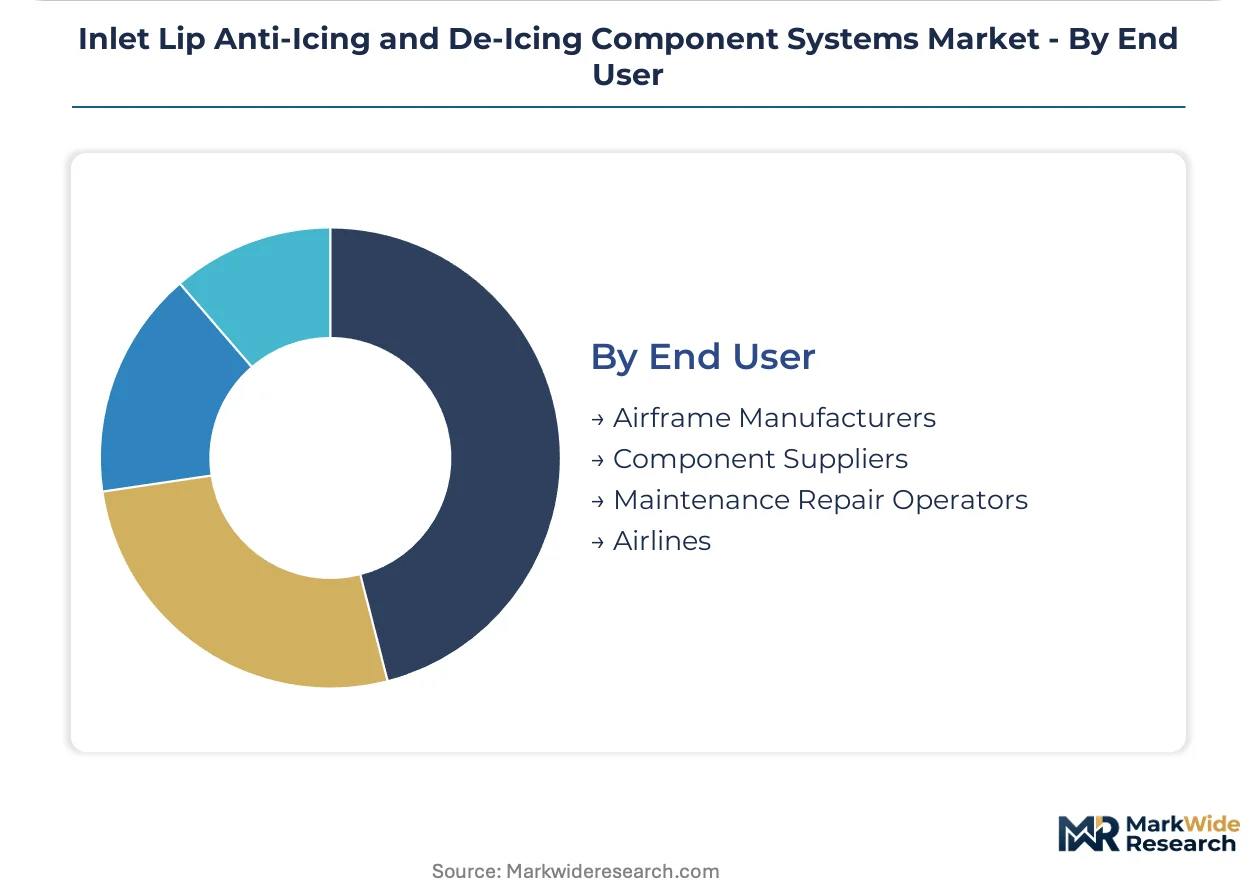
End User:
Contractual risk allocation and airworthiness accountability shape vendor relationships across the value chain.
- Airframe Manufacturers:Boeing, Airbus, and regional jet OEMs specifying integrated thermal system packages with single-source supplier accountability for certification compliance.
- Airlines:Technical procurement teams at United States majors consolidating from discrete component sourcing to bundled ice protection system contracts reducing interface complexity.
- Component Suppliers:RTX and tier-one aerostructures specialists anchoring long-term agreements with thermal management expertise.
- Maintenance Repair Operators:Aftermarket service providers managing legacy bleed-air system sustainment and electrothermal retrofit integration onto aging nacelles.
Specification authority rests with Airframe Manufacturers; procurement decision-making is gaining share fastest among Airlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established aerospace clusters while consumption patterns track fleet modernization cycles across major aviation markets. The United States anchors manufacturing capacity through tier-one aerostructures suppliers, whereas European and Asian demand responds to distinct regulatory timelines for ice protection system upgrades.
United States
Commercial fleet renewal programs at major carriers specify electrothermal zone control for next-generation narrow-body deliveries. FAA Part 25 Appendix C certification stringency tightens testing requirements for redundant heating zones and sensor integration. Wichita, Kansas hosts concentrated aerostructures engineering where Textron and tier-one suppliers coordinate thermal system specification for business aviation platforms.
Germany
Airbus supply chain procurement drives specification authority for integrated thermal packages across A320 family programs. EU F-Gas Regulation phase-down restricts pneumatic system working-fluid options and accelerates electrothermal migration. Hamburg and Munich anchor composite nacelle manufacturing clusters where carbon nanotube heating film qualification proceeds for 2028-2032 entry-into-service targets.
France
Airframe OEM technical procurement teams consolidate vendor relationships toward single-source accountability for ice protection airworthiness. EASA CS-25 harmonization with evolving FAA icing envelope interpretations extends type certification cycles. Toulouse hosts integrated thermal system engineering where supplier bundling displaces fragmented multi-vendor integration responsibility.
United Kingdom
RTX leverages thermal systems expertise to anchor long-term supplier contracts with regional airframers serving European markets. REACH compliance requirements govern chemical de-icing fluid formulations and surface treatment chemistries. Southwest England maintains specialized aerostructures testing facilities where multiphysics simulation capabilities concentrate for coupled thermal-structural-aerodynamic modeling.
Japan
METI industrial policy supports aerospace supply chain development targeting tier-two thermal component manufacturing. JIS standards govern materials qualification for heating element substrates in regional jet programs. Nagoya aerospace cluster hosts composite processing capabilities where thin-film deposition expertise develops for next-generation electrothermal architectures.
Inlet Lip Anti-Icing and De-Icing Component Systems Market Competitive Landscape
The competitive structure tilts toward diversified aerospace conglomerates with thermal management heritage. Consolidation around integrated system packaging favors suppliers bundling sensors, controllers, and heating elements under single-source airworthiness accountability. Three archetypes dominate: legacy aerostructures tier-ones with nacelle integration capabilities, specialized ground support equipment manufacturers, and diversified industrial conglomerates with thermal systems divisions. Competitive moves center on long-term OEM alignment contracts and composite heating film qualification programs for next-generation platforms.
Within the diversified conglomerate tier, RTX occupies a position representing thermal systems expertise leveraged across commercial and military propulsion applications. Among ground support specialists, John Bean Technologies exemplifies equipment manufacturers competing through closed-loop infrastructure that complements airborne systems at regulated operational hubs. Vestergaard Company anchors the European ground-based segment with Denmark-based engineering serving EU Green Deal procurement mandates. These three represent distinct competitive vectors: integrated airborne thermal systems, regulatory-compliant ground infrastructure, and sustainability-linked regional equipment supply.
| Leading Market Players |
|---|
| RTX |
| Textron |
| General Atomics |
| John Bean Technologies |
| Vestergaard Company |
| Global Ground Support |
| Inland Group of Companies |
| Mallaghan |
| Tronair |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FAA Part 25 Appendix C-compliant electrothermal systems and legacy pneumatic alternatives manifests in parallel supply chain configurations, with premium-tier suppliers capturing long-term OEM contracts while commodity-grade component vendors face margin compression from nickel-chromium alloy price volatility.
Pricing Analysis
Cost-down pressure on electrothermal system manufacturers accelerates because tier-one aerostructures suppliers are consolidating vendor relationships into single-source bundled contracts. Three-tier pricing structure across premium certified, standard qualified, and economy unverified levels tracks FAA certification tier and volume scale. Price differentiation hinges on zone-control precision and after-sales sensor calibration service bundling. Airlines operating EPA NPDES-constrained hubs exhibit highest price sensitivity; business aviation OEMs demonstrate lowest sensitivity due to weight-performance tradeoff priorities.
Supply Chain Analysis
Direct-to-OEM channels handle fleet renewal program demand from United States-based carriers, while tier-two component distribution feeds aftermarket maintenance repair operators. Geographic supply concentration clusters in the United States, Germany, and Japan for composite nacelle manufacturing and thin-film deposition capabilities. Raw material dependencies center on nickel-chromium heating element substrates, carbon nanotube conductive films, and specialized polyimide insulation layers. Single-source vulnerability in metallurgical processing regions for heating element substrates poses structural supply chain risk. Distribution runs through tier-one aerostructures integrators bundling complete thermal system accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrothermal architecture displacement of pneumatic systems constitutes a consolidation play, as certification timeline compression and composite heating film qualification requirements force capital-constrained suppliers toward exit.
For Market Incumbents: Anticipate margin pressure from carbon nanotube heating film qualification programs by securing backward integration into thin-film deposition capabilities and anchoring long-term OEM alignment contracts before 2028-2032 entry-into-service deadlines. Defensive positioning requires preemptive sensor-controller integration investments to maintain single-source bundling advantages against fragmented multi-vendor competitors. For New Entrants and Emerging Players: Enter via urban air mobility electrothermal specialization targeting eVTOL distributed propulsion nacelles with severe weight constraints, the most penetrable segment given established aerospace suppliers' legacy platform focus. Hydrogen combustion architecture adaptation presents secondary white-space opportunity. Go-to-market execution should emphasize multiphysics simulation partnerships with academic CFD centers to overcome talent scarcity barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified aerospace conglomerates seeking thermal management capabilities. Long-term viability favors suppliers with demonstrated FAA Part 25 Appendix C certification track records and composite heating film qualification progress. Acquisition target archetype: tier-two electrothermal component manufacturers with thin-film deposition expertise and pending OEM validation contracts. Signal to watch: EASA CS-25 harmonization delays that extend certification cycles and strain working capital reserves.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Nanotube Heating Film Qualification | Boeing and Airbus tier-one suppliers are rewriting supplier requirements, favoring composite specialists over legacy wire-harness manufacturers. |
| Single-Source Thermal System Bundling | United States-based carrier technical procurement teams are consolidating vendor relationships to reduce contractual interface complexity. |
| Backward Integration into Thin-Film Deposition | Electrothermal system manufacturers are securing captive supply of carbon nanotube conductive elements to mitigate nickel-chromium price volatility. |
| Urban Air Mobility Thermal Management Partnerships | eVTOL platform developers require distributed electrothermal protection with severe weight and power-draw constraints. |
| Hydrogen Combustion Architecture R&D Investment | Cryogenic fuel systems demand redesigned inlet lip heating profiles to manage thermal gradients between hydrogen storage and engine airflow. |
Research Methodology
Multi-period observation of FAA certification timeline evolution, EASA CS-25 harmonization delays, and EPA NPDES permitting trends anchored the trend analysis, supplemented by interviews with tier-one aerostructures procurement directors, thermal system engineering leads at major OEMs, airline technical fleet managers, and carbon nanotube materials specialists. Secondary validation drew from FAA airworthiness directive filings, EASA type certification databases, SEC 10-K aerospace segment disclosures, and customs trade data for heating element substrate flows. Bottom-up segment sizing triangulated against top-down fleet modernization projections across the analysis window.
Input-output matrices mapped electrothermal and pneumatic system deployment shares against propulsion platform entry-into-service timelines, thermal architecture segmentation, and regional regulatory cluster adoption patterns. CAGRs were derived from installed-base replacement cycle modeling and new platform specification trajectories. Industry-specific forecast inputs incorporated hybrid-electric propulsion thermal management requirements and EU F-Gas Regulation phase-down compliance deadlines.
Revisions become necessary when FAA Appendix C icing envelope interpretations shift, nickel-chromium alloy supply disruptions materialize, or hybrid-electric propulsion architectures accelerate faster than projected. Forecasts reflect assumptions about certification timeline stability and OEM propulsion strategy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market