
 Aircraft Vertical Stabilizer Market | 2026-2036
Aircraft Vertical Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Vertical Stabilizer Market Analysis
AS9100D certification is reorganizing supplier eligibility across the aircraft vertical stabilizer value chain, forcing tier-two fabricators to upgrade quality management systems or exit the market. Airbus SE leverages composite manufacturing scale in Europe to sustain dual-aisle program output. Boeing anchors North American supply through its integrated vertical fin production in Washington state. Liebherr Aerospace competes on actuation-integrated stabilizer designs for regional jet platforms.
An aircraft vertical stabilizer is the fixed aerodynamic surface mounted on the empennage that provides directional stability and houses the rudder control surface, typically constructed from carbon fiber reinforced polymer skins over aluminum or titanium substructures to achieve strength-to-weight ratios exceeding 150 kN·m/kg. Its primary purpose is to counter adverse yaw, maintain coordinated flight, and enable controlled turns across commercial, military, and unmanned platforms. Composite material adoption leads segment value due to Boeing 787 and Airbus A350 programs specifying CFRP primary structures, while aluminum retains volume dominance in single-aisle retrofit and military trainer markets. Civil aviation application pools the largest share of recurring demand, though unmanned systems represent the fastest-growing category as tactical UAV programs specify miniaturized V-tail configurations.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern structural integrity, flutter margins, and damage tolerance for transport-category vertical stabilizers, creating compliance cost barriers that favor incumbent OEMs with dedicated certification engineering staff. The EU Green Deal's emerging sustainable aviation fuel mandates and corresponding airframe efficiency targets will pressure stabilizer designers to reduce weight further while maintaining electromagnetic interference shielding performance. Stakeholders must monitor evolving MEE emissions benchmarks in China and their potential to reshape export qualification protocols for aerostructure suppliers serving COMAC programs.
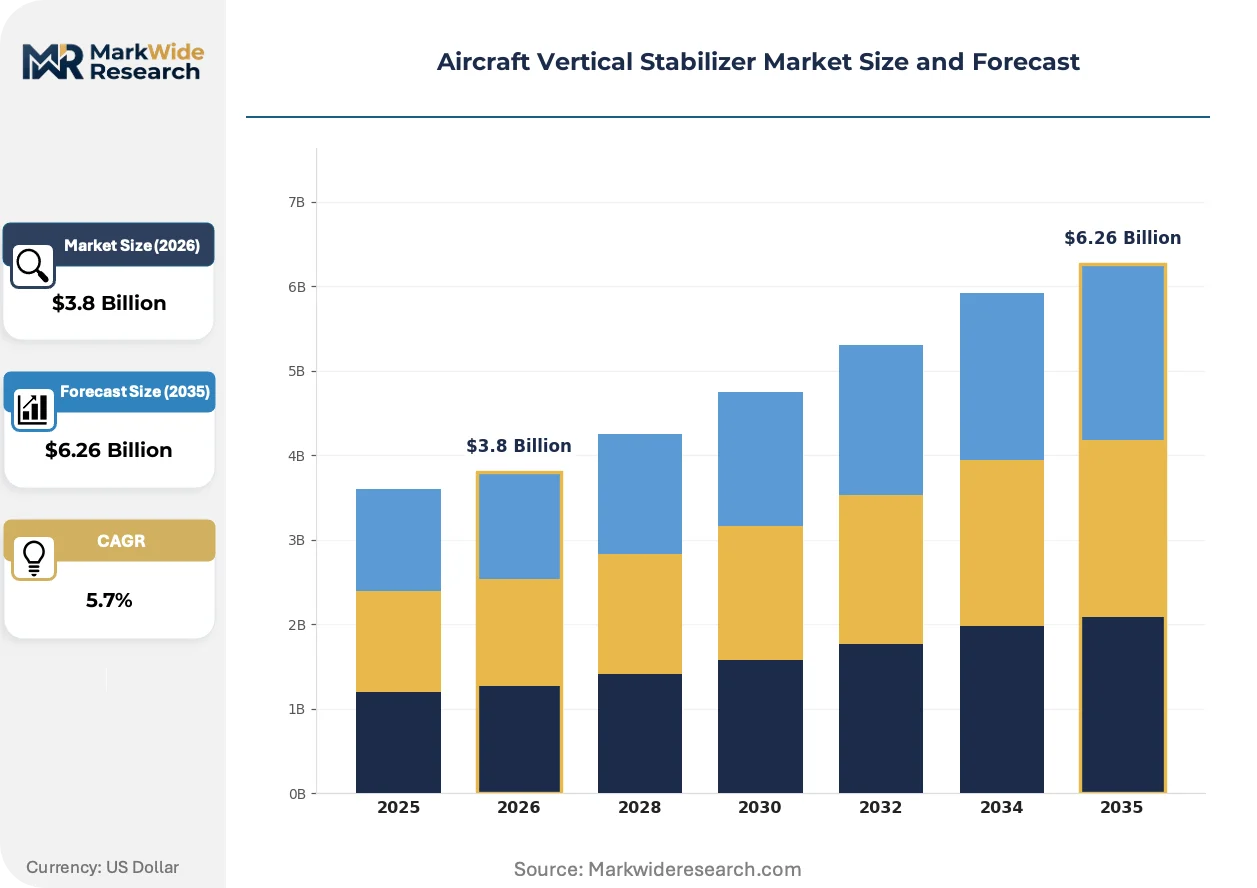
Market Dynamics
AS9100D certification mandates are forcing tier-two fabricators to either upgrade quality management systems or exit the aircraft vertical stabilizer supply chain entirely. This regulatory filter is consolidating supplier eligibility while reshaping procurement relationships between OEMs and sub-tier manufacturers.
Growth Catalysts
- Post-pandemic fleet expansion:Commercial airlines are restoring narrow-body and wide-body capacity to meet recovered passenger volumes, driving replacement and new-build stabilizer demand.
- FAA Part 25 structural integrity standards:Updated airworthiness directives on fatigue resistance and lightning strike protection are mandating material upgrades across the installed base.
- Carbon fiber reinforced polymer maturation:Automated fiber placement and out-of-autoclave curing are reducing production cycle times for composite primary structures.
Market Restraints
- Titanium input cost volatility:Sponge and mill product price swings destabilize substructure cost forecasting for multi-year production contracts.
- Washington state supply concentration:Boeing's integrated vertical fin production anchors North American capacity, creating single-point vulnerability for regional suppliers.
- Lightning strike protection technical ceiling:Conventional metallic mesh solutions add parasitic weight that conflicts with airframe efficiency targets.
Strategic Opportunities
- Unmanned systems V-tail miniaturization:Tactical UAV programs are specifying integrated vertical stabilizer configurations that combine directional stability with reduced radar signature.
- EU Green Deal sustainable aviation fuel mandates:Corresponding airframe efficiency targets pressure stabilizer designers toward lighter electromagnetic interference shielding architectures.
- India defense indigenization:The country's PLI scheme for aerospace components creates qualification pathways for foreign tier-two fabricators establishing local production.
Industry Challenges
- Composite technician skill scarcity:Automated fiber placement and resin transfer molding operations require specialized labor pools that outpace vocational training output.
- EASA CS-25 certification timeline compression:Damage tolerance and flutter margin validation protocols extend new design approval cycles beyond program launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Vertical Stabilizer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rudder, T-tail, V-tail, Flying Wing Material: Aluminum, Composite, Steel, Titanium Application: Civil Aviation, Military Aviation, Unmanned Systems, Business Aviation Production Method: Machining, Molding, Assembly, 3D Printing |
| Companies Covered | Airbus SE, The Boeing Company, BAE Systems plc, Moog Inc., Aernnova Aerospace, Liebherr Aerospace, Parker Hannifin Corporation, RUAG Aerostructures, KIHOMAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Vertical Stabilizer Market Emerging Trajectories
Stabilizer manufacturing is splitting between legacy metallic architectures and next-generation composite integration, with regulatory pressure and material science advancement driving divergent investment patterns across the supplier base.
Thermoplastic composite welding is bifurcating repair and assembly workflows in the aftermarket. Regional MRO facilities are adopting induction welding for skin-to-spar joints to eliminate fastener drilling and sealing operations. This technology is bifurcating service capabilities between shops with capital equipment for thermoplastic processing and those confined to thermoset bonding or metallic replacement.
EASA's evolving CS-25 certification requirements for damage tolerance are compressing design iteration cycles for new stabilizer programs. The standards now mandate explicit residual strength demonstrations after discrete source damage scenarios. European OEMs and their tier-one partners are responding by front-loading structural testing budgets and embedding certification engineers within preliminary design teams.
Airline procurement departments are consolidating aerostructure sourcing under fleet-wide lifecycle cost frameworks rather than unit-price bidding. Long-term service agreements now bundle stabilizer inspection, repair, and replacement entitlements with initial airframe purchases. North American full-service carriers have been fastest to adopt these total-cost-of-ownership models, pressuring suppliers to price risk across twenty-year operational horizons.
Aircraft Vertical Stabilizer Market Segmentation
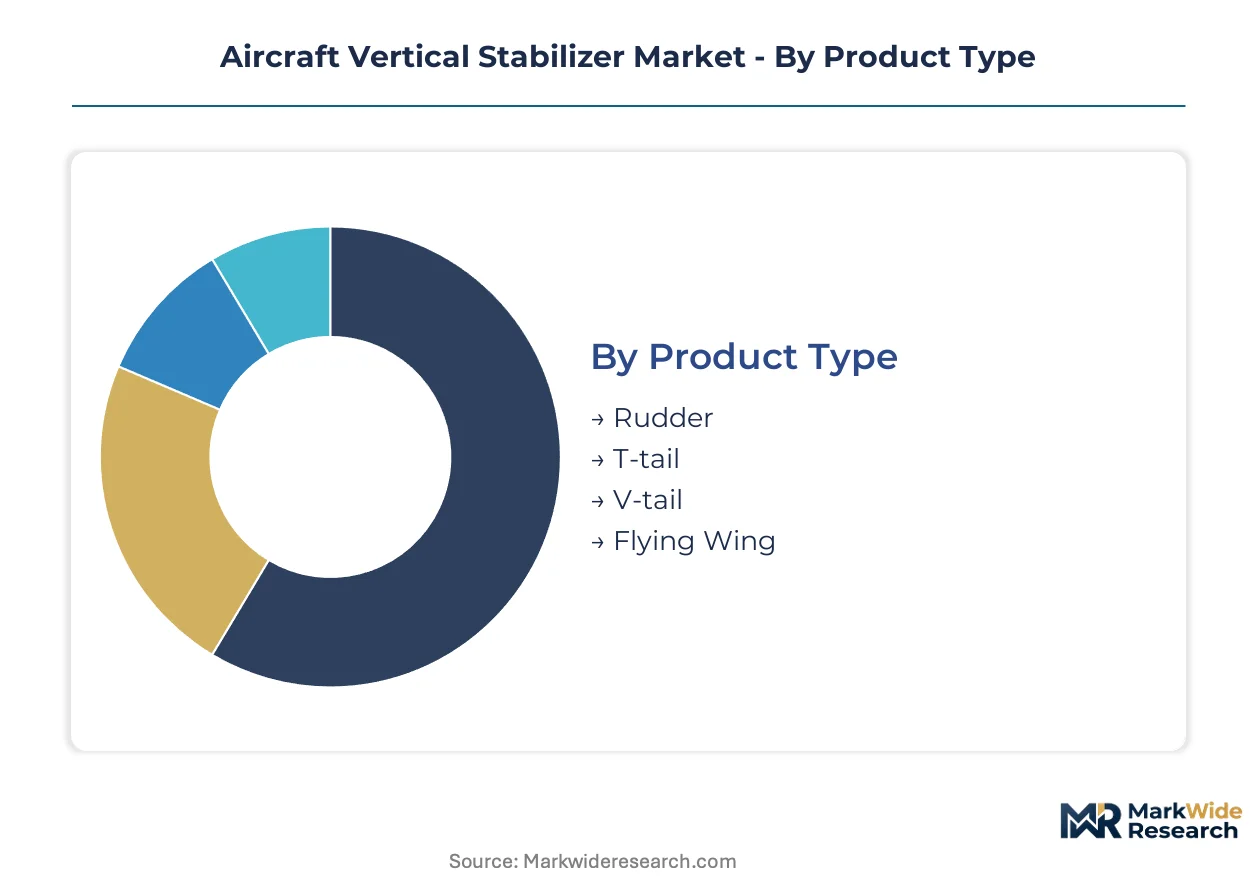
Aircraft vertical stabilizer procurement channels diverge sharply by platform type and certification tier. OEM direct contracts dominate high-volume commercial programs, while defense contractors and UAV specialists source through specialized aerospace distributors with ITAR-compliant handling capabilities.
Product Type:
Channel mix varies by configuration complexity: rudder-integrated units flow through OEM captive supply chains, while specialized T-tail and V-tail designs reach tier-one integrators via technical distributor networks.
- Rudder:The conventional hinged control surface mounted on the vertical stabilizer trailing edge, typically actuated by hydraulic or fly-by-wire systems. Commercial narrow-body production in the United States concentrates demand for high-cycle fatigue-rated rudder assemblies. FAA Part 25 certification timelines constrain supplier switching.
- T-tail:Configuration mounting the horizontal stabilizer atop the vertical fin, common in regional jets and military trainers to reduce prop wash interference. European regional aircraft programs in France and Germany sustain T-tail volume despite higher structural loading requirements.
- V-tail:Combined vertical and horizontal surface arrangement reducing wetted area and radar cross-section. Tactical UAV specifications in Israel and Turkey favor V-tail miniaturization for endurance platforms.
- Flying Wing:Tailless architecture eliminating discrete stabilizer surfaces through blended wing-body integration. Northrop Grumman B-21 and experimental programs in California drive classified development activity.
By volume, rudder configurations lead. By growth pace, V-tail designs are expanding most quickly.
Material:
Cost tier stratification separates premium composite primary structures from standard aluminum retrofit components and economy-grade steel trainers.
- Aluminum:Legacy alloy skins and extruded spars dominate single-aisle aftermarket replacement and military trainer fleets. Indian defense indigenization programs under the PLI scheme concentrate aluminum stabilizer sourcing for domestic trainer aircraft.
- Composite:Carbon fiber reinforced polymer skins with titanium substructures achieve strength-to-weight ratios exceeding metallic alternatives. Boeing 787 and Airbus A350 final assembly in Washington state and Toulouse anchor CFRP demand.
- Steel:High-strength alloy applications limited to high-load military interfaces and legacy platform spares. Russian and Chinese domestic programs retain steel for cost-sensitive transport categories.
- Titanium:Mill product substructures and lightning strike protection mesh in premium commercial platforms. Sponge price volatility from Russian and Ukrainian supply disruptions constrains long-term contracting.
Composite materials command the highest unit values. Aluminum retains the largest installed base requiring aftermarket support.
Application:
Customer type segmentation separates fleet operators with lifecycle cost frameworks from defense procurement agencies with mission-specific technical requirements.
- Civil Aviation:Commercial airline and cargo operator demand for transport-category stabilizers under FAA and EASA continuous airworthiness programs. Post-pandemic narrow-body re-fleeting in the United States and China drives new-build volume.
- Military Aviation:Fighter, transport, and tanker platforms with damage tolerance specifications exceeding civil standards. Lockheed Martin F-35 production in Texas and BAE Systems Tempest development in the United Kingdom concentrate military demand.
- Unmanned Systems:Tactical and strategic UAV platforms specifying miniaturized stabilizers with integrated sensor apertures. Turkish Bayraktar and Israeli Elbit programs expand fastest among NATO-aligned forces.
- Business Aviation:Fractional ownership and corporate flight departments with customized interior and exterior configurations. Gulfstream and Bombardier final assembly in Georgia and Quebec sustain premium demand.
Civil aviation pools the largest revenue share. Unmanned systems show the steepest expansion trajectory.
Production Method:
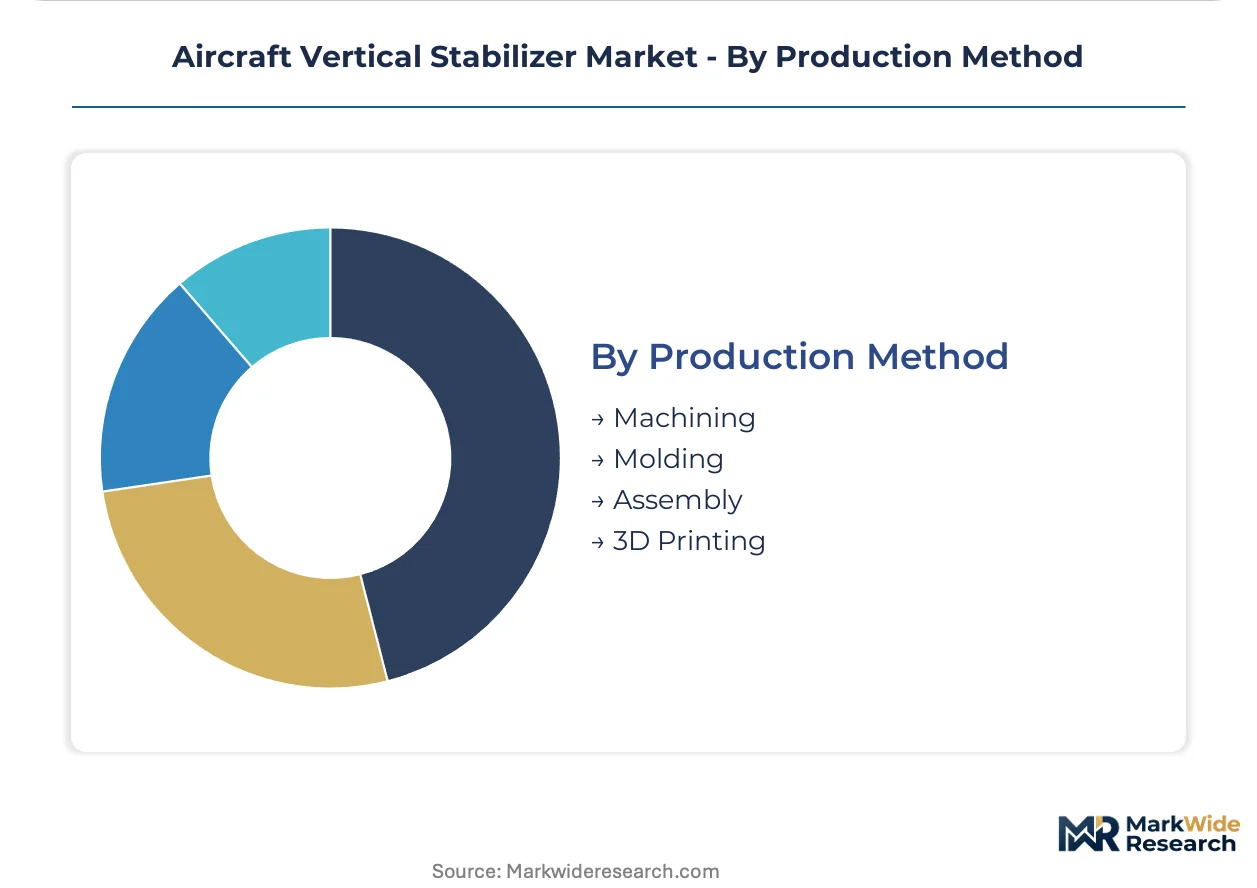
Supply concentration clusters around machining and molding capabilities, with emerging 3D printing qualifications creating new vendor entry pathways.
- Machining:Five-axis CNC milling of aluminum and titanium structural elements with tight tolerance requirements. Legacy supplier bases in Connecticut and Ohio retain machining dominance for military programs.
- Molding:Resin transfer molding and autoclave curing for composite primary structures. Automated fiber placement in South Carolina and Hamburg factories reduces labor content.
- Assembly:Mechanical joining, bonding, and system integration of subcomponents into shipset deliveries. Boeing's integrated vertical fin production in Washington state represents the largest single assembly node.
- 3D Printing:Directed energy deposition and powder bed fusion for titanium brackets and ducting with topology-optimized geometries. Emerging qualification pathways through FAA AC 20-178 guidance in Texas and California.
Molding processes lead by production value. 3D printing is gaining share fastest among new qualification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements are reshaping supplier eligibility across national boundaries, with procurement departments prioritizing AS9100D-qualified fabricators in final assembly proximity.
United States
Boeing's integrated vertical fin production in Washington state anchors North American supply chains for 787 and 737 programs. FAA airworthiness directives on fatigue resistance and lightning strike protection are mandating material upgrades across the installed base. The Pacific Northwest cluster concentrates composite manufacturing capacity alongside legacy aluminum machining operations in Connecticut and Ohio.
France
Airbus SE leverages composite manufacturing scale in Toulouse to sustain A350 and A320 family output. EASA CS-25 damage tolerance requirements are compressing design iteration cycles for new stabilizer programs. The Occitanie region hosts automated fiber placement facilities serving European final assembly lines.
Germany
Liebherr Aerospace competes on actuation-integrated stabilizer designs for regional jet platforms from its Baden-Württemberg operations. EU Green Deal sustainable aviation fuel mandates are pressuring airframe efficiency targets that filter down to stabilizer weight reduction requirements. Bavaria and Hamburg house tier-one integrators with EASA-certified testing capabilities.
Israel
Tactical UAV programs specify miniaturized V-tail configurations for endurance platforms developed by Elbit Systems. The country's defense procurement agency prioritizes indigenous aerostructure capabilities with ITAR-aligned export protocols. Tel Aviv and Haifa clusters concentrate composite fabrication for unmanned systems with reduced radar signature requirements.
India
The PLI scheme for aerospace components creates qualification pathways for foreign tier-two fabricators establishing local production. DGFT export protocols and BIS standards are converging with FAA and EASA benchmarks for trainer aircraft stabilizers. Karnataka and Maharashtra are attracting machining and assembly investments for domestic defense programs.
Aircraft Vertical Stabilizer Market Vendor Landscape
Player mix skews toward integrated OEMs with captive aerostructure divisions and tier-one specialists with EASA-certified testing capabilities. Market structure concentrates around three strategic archetypes: full-airframe integrators controlling stabilizer production in-house, tier-one aerostructure houses with multi-program portfolios, and component specialists focused on actuation or material processing. Competitive moves center on backward integration into composite preform manufacturing and strategic partnerships for unmanned systems qualification.
Among European-based aerostructure houses, Airbus SE and BAE Systems plc exemplify the integrated OEM archetype with captive supply chains spanning preliminary design through final assembly. Liebherr Aerospace occupies a position within the tier-one specialist tier, representing the actuation-integrated design approach for regional platforms. These three anchors demonstrate how geographic proximity to EASA regulators and final assembly lines shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| BAE Systems plc |
| Moog Inc. |
| Aernnova Aerospace |
| Liebherr Aerospace |
| Parker Hannifin Corporation |
| RUAG Aerostructures |
| KIHOMAC |
| Others |
Supply Flow & Price Mechanics
Automated fiber placement capacity utilization above 85% in Washington state and Toulouse anchors composite stabilizer cost floors, compressing margins for tier-two metallic fabricators unable to achieve equivalent scale economies. Boeing's integrated vertical fin production and Airbus SE's captive supply chains concentrate procurement leverage among dual-aisle OEMs, while AS9100D certification mandates force price-quality tradeoffs at the supplier tier.
Pricing Analysis
Certification level creates the primary spread across the aircraft vertical stabilizer market, with AS9100D-qualified composite primary structures commanding premium positioning over aluminum retrofit components lacking equivalent quality system credentials. Three-tier pricing structure separates FAA Part 25-certified shipsets for transport-category programs from EASA CS-25-compliant regional jet configurations and economy-grade military trainer spares. Pricing pressure stems from airline procurement departments consolidating aerostructure sourcing under fleet-wide lifecycle cost frameworks that compress unit-price premiums. Cargo operators and low-cost carriers exhibit highest price sensitivity, while fractional ownership business aviation clients prioritize customization over cost minimization.
Supply Chain Analysis
Inbound logistics costs for titanium sponge from Russian and Ukrainian sources have destabilized substructure cost forecasting, forcing multi-year contract renegotiations across Pacific Northwest assembly nodes. Supply concentrates in the United States, France, and Germany, with Boeing's Washington state vertical fin production, Airbus SE's Toulouse composite facilities, and Liebherr Aerospace's Baden-Württemberg operations anchoring tier-one capacity. Raw material dependencies span carbon fiber preforms from Japan and the United States, titanium mill products from Russia and Ukraine, and specialized epoxy resin systems from Germany. Single-source vulnerability around Boeing's integrated production creates regional supply risk for North American narrow-body programs. Distribution runs through OEM captive supply chains for high-volume commercial programs and ITAR-compliant aerospace distributors for defense and unmanned systems procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft vertical stabilizer demand sits in early-cycle expansion as post-pandemic narrow-body re-fleeting accelerates and tactical UAV programs specify miniaturized V-tail configurations at rates exceeding legacy platform replacement.
For Market Incumbents: Consolidate backward integration into composite preform manufacturing to capture margin erosion from carbon fiber suppliers, while embedding certification engineers within preliminary design teams to compress EASA CS-25 approval timelines. Threat substitution from thermoplastic composite welding in regional MRO facilities demands capability investment in induction welding equipment or strategic partnership with repair network specialists. Capacity addition in South Carolina and Hamburg automated fiber placement facilities reinforces scale advantages against metallic retrofit competitors. For New Entrants and Emerging Players: Anchor in India's PLI scheme for aerospace components to access qualification pathways for domestic trainer aircraft stabilizers under converging DGFT export protocols and BIS standards. Tactical UAV V-tail miniaturization for Israeli and Turkish endurance platforms represents the most penetrable white-space segment, with reduced radar signature specifications creating technical differentiation opportunities. Go-to-market execution should prioritize ITAR-aligned partnerships with Elbit Systems and Bayraktar supply chain managers over direct OEM engagement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tier-one aerostructure houses with EASA-certified testing capabilities and multi-program composite manufacturing portfolios over component specialists tethered to single-platform metallic architectures. Long-term viability across the projection horizon rests on qualification breadth spanning Boeing 787, Airbus A350, and emerging COMAC C919 aftermarket opportunities. Acquisition target archetype: automated fiber placement operators with out-of-autoclave curing qualifications and existing FAA repair station authorizations. Signal to watch: MEE emissions benchmark revisions in China and their potential to reshape export qualification protocols for aerostructure suppliers serving COMAC programs.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Preform Manufacturing Scale-Up | Captures margin from carbon fiber suppliers while securing Boeing 787 and Airbus A350 program allocation. |
| Out-of-Autoclave Curing Qualification | Reduces production cycle times for CFRP primary structures, enabling competitive positioning against legacy autoclave operators. |
| ITAR-Compliant Distribution Partnership | Opens unmanned systems procurement channels with Israeli Elbit and Turkish Bayraktar defense programs. |
| India PLI Scheme Local Production | Establishes DGFT-aligned assembly nodes for domestic trainer aircraft under BIS-converged certification pathways. |
| Embedded Certification Engineering Investment | Front-loads structural testing budgets to compress EASA CS-25 damage tolerance approval timelines for new stabilizer programs. |
Methodological Framework
Desk research of FAA airworthiness directive filings, EASA CS-25 certification databases, and OEM annual reports preceded structured interviews with aerostructure procurement directors, composite manufacturing engineers, MRO facility managers, and regulatory affairs specialists across the United States, France, and Germany. Primary fieldwork with tier-one integrators and tier-two fabricators validated production capacity utilization, certification backlog durations, and material cost pass-through mechanisms. Secondary sources included customs trade data for titanium sponge and carbon fiber preform imports, SEC 10-K disclosures from Boeing and Airbus SE, and EU Green Deal sustainable aviation fuel mandate documentation. Bottom-up platform-level demand estimates triangulated against top-down fleet projection models from aviation lessors and airline re-fleeting announcements.
Variance decomposition across product type, material grade, application segment, and production method dimensions shaped the analytical framework over the projection horizon. Composite material adoption curves for Boeing 787 and Airbus A350 programs, aluminum aftermarket replacement cycles for single-aisle fleets, and unmanned systems V-tail penetration rates in NATO-aligned defense budgets provided industry-specific forecast inputs. CAGRs derived from logistic growth modeling of platform-level production rates, adjusted for airworthiness directive compliance retrofit demand and emerging COMAC program qualification pathways.
Material uncertainties — titanium input cost volatility from Eastern European supply disruptions, EASA CS-25 certification timeline compression beyond program launch windows, and evolving MEE emissions benchmarks in China — sit outside the modeled envelope. Forecasts reflect assumptions regarding post-pandemic travel recovery sustaining narrow-body fleet expansion, AS9100D certification mandates consolidating supplier eligibility without regulatory reversal, and composite technician training pipeline expansion matching automated fiber placement capacity additions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Pylon and Strut Fairing Retrofit Kits Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Aircraft Exterior Structure Digital Twin Platforms Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Aerospace Nuts Market