
 Low-Noise Landing Gear Fairing Composite Designs Market | 2026-2036
Low-Noise Landing Gear Fairing Composite Designs Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Noise Landing Gear Fairing Composite Designs Market Insights
France is tilting toward expanded thermoplastic composite capacity around Toulouse aerospace clusters. Safran Landing Systems leverages in-house resin transfer molding expertise to dominate European OEM supply chains. GKN Aerospace anchors its position through long-term contracts with Airbus Aerostructures for integrated rib fairing architectures. Collins Aerospace competes on acoustic test data libraries that shorten FAA certification cycles for U.S. platform integrators.
Low-noise landing gear fairing composite designs encompass engineered polymer-matrix structures with embedded acoustic damping layers, typically 3-8 mm thick, manufactured via autoclave curing or out-of-autoclave processes to attenuate turbulent airflow noise during approach and landing phases. Carbon fiber formulations occupy the premium tier where specific strength-to-acoustic-impedance ratios justify unit cost premiums, while thermoplastic composites represent the fastest-expanding material category as recyclability mandates intensify across European supply chains. Commercial aircraft applications generate the dominant revenue pool, though UAV segments attract disproportionate R&D investment due to modular fairing replacement protocols.
FAA Part 36 noise certification requirements and EASA CS-36 standards collectively dictate minimum acoustic performance thresholds that composite fairing designs must demonstrably exceed. The EU Green Deal's embodied carbon tracking provisions and REACH chemical compliance protocols are forcing material substitutions away from certain epoxy systems toward bio-based resin alternatives. Stakeholders must monitor evolving MEE emissions regulations in China, where COMAC's C919 ramp-up will create parallel certification pathways distinct from Western regulatory frameworks.
Market Dynamics
ICAO Chapter 14 noise standards are compressing design-to-certification timelines, forcing OEMs to pre-validate acoustic performance through digital twin simulations before physical prototyping begins.
Growth Catalysts
- Thermoplastic composite adoption:Recyclability mandates under the EU Green Deal are accelerating resin system conversions in European supply chains. Airbus Aerostructures specifications now prioritize melt-reprocessable matrices for landing gear fairing architectures.
- FAA Part 36 stringency:Tighter approach-phase noise limits are expanding the addressable market for multi-layer acoustic damping configurations. Boeing's supply chain requirements now specify embedded viscoelastic layers as baseline for new platform integrations.
- Out-of-autoclave curing:Large-format oven and press consolidation processes are reducing energy intensity and capital requirements for fairing production. Tier-2 suppliers in Wichita and Toulouse aerospace clusters are retooling capacity around this process shift.
Market Restraints
- Carbon fiber feedstock concentration:Precursor supply is dominated by Japanese and U.S. chemical conglomerates, exposing fairing manufacturers to acrylonitrile price volatility and long-dated purchase agreements.
- REACH chemical compliance:ECHA restrictions on certain amine hardeners and bisphenol derivatives are forcing qualified material list revisions, creating formulation revalidation costs that disadvantage smaller composite shops.
- Metallic fairing residual demand:Legacy narrow-body fleets and cargo conversion programs continue specifying aluminum-lithium alternatives where acoustic performance is secondary to unit cost minimization.
Strategic Opportunities
- Urban air mobility integration:eVTOL platforms require modular, rapidly replaceable fairing segments for distributed propulsion systems. Joby Aviation and Archer Aviation procurement specifications are creating parallel design standards distinct from Part 25 certification pathways.
- MEE emissions alignment:China's dual carbon goals and evolving aviation decarbonization frameworks are creating regulatory tailwinds for bio-epoxy and recycled fiber formulations in COMAC C919 supplier qualifications.
- Digital thread convergence:Coupling acoustic simulation software with automated fiber placement is collapsing prototype iteration cycles. Safran Landing Systems and GKN Aerospace are piloting closed-loop design-to-manufacture workflows.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled fluid-structure-acoustic modeling requires specialized computational mechanics expertise that concentrates in Toulouse, Wichita, and Munich engineering centers.
- FAA certification timeline compression:Physical test article requirements for flap and slat noise contribution assessments are creating bottlenecks as acoustic test facility availability tightens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Noise Landing Gear Fairing Composite Designs Market |
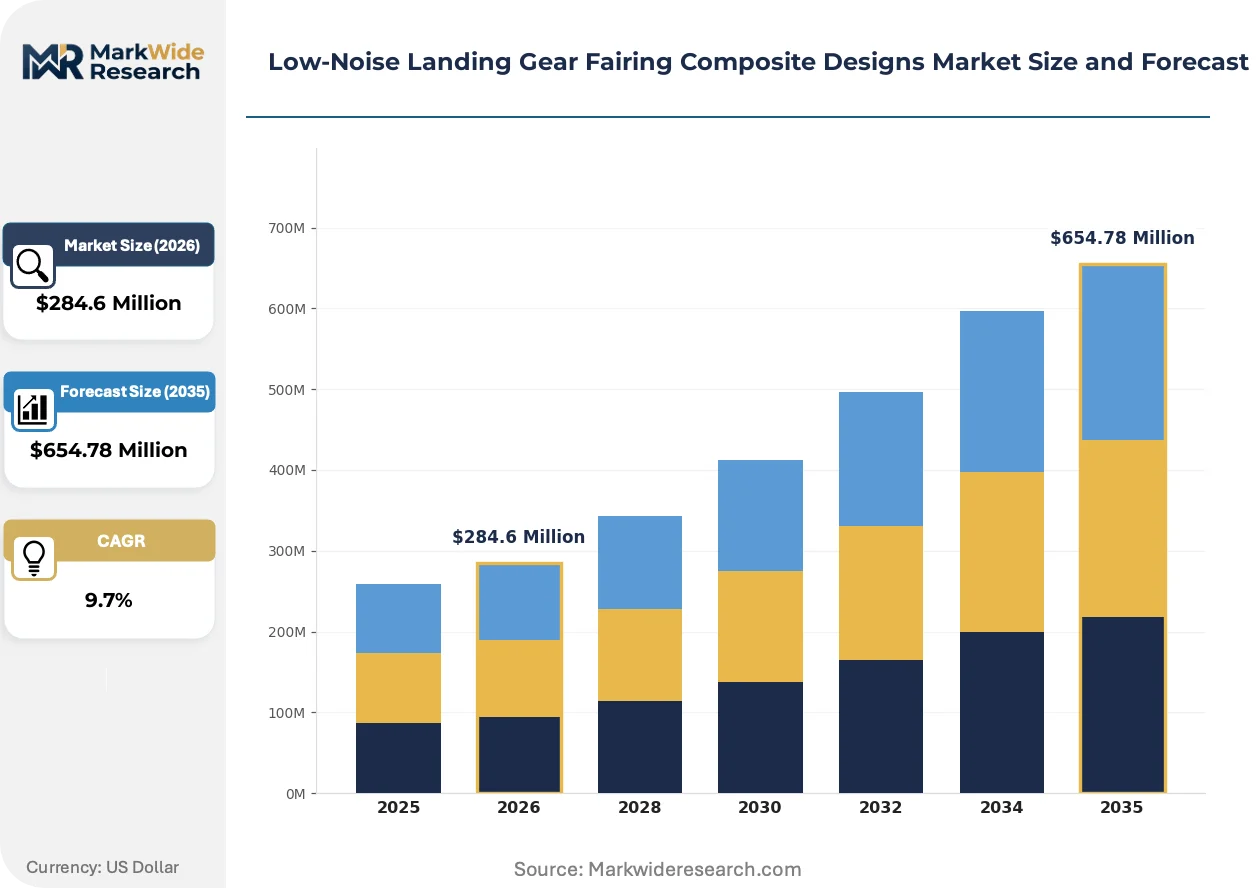
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $654.78 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites, Thermoplastic Composites Design Approach: Monolithic, Sandwich Structure, Corrugated, Multi-Layered, Integrated Rib Application: Commercial Aircraft, Military Jets, Regional Aircraft, Business Jets, UAVs End User: OEMs, Tier-1 Suppliers, Aircraft Maintenance Providers, Retrofit Specialists |
| Companies Covered | Safran Landing Systems, Collins Aerospace, GKN Aerospace, Spirit AeroSystems, Magellan Aerospace, Ducommun, TRIUMPH, FACC AG, Airbus Aerostructures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Noise Landing Gear Fairing Composite Designs Market Trends and Innovations
Computational methods and material science advances are converging to collapse traditional trade-offs between acoustic performance, structural weight, and manufacturing throughput in landing gear fairing production.
Automated fiber placement with in-situ thermoplastic consolidation is collapsing the distinction between raw material conversion and final part geometry realization. Tier-1 suppliers are adopting robotic deposition cells that integrate laser-assisted heating with real-time porosity monitoring. The structural consequence is collapsing the supplier tier between prepreg converters and finished component fabricators.
EU Green Deal embodied carbon tracking provisions are mandating lifecycle emissions disclosure for aerospace structures placed on the European market. EASA is developing certification memo guidance for bio-based resin qualification that parallels existing CMH-17 handbook protocols. Suppliers with existing FAA test data libraries face parallel requalification costs to access European OEM supply chains.
Airline procurement departments are unbundling acoustic performance guarantees from airframe purchase agreements, creating standalone fairing replacement contracts indexed to measured noise reduction. Maintenance, repair, and overhaul providers are capturing specification influence previously held by original equipment manufacturers. This shift is most visible in U.S. carrier fleet renewal programs where Delta and United technical operations teams now dictate retrofit fairing acoustic targets.
Low-Noise Landing Gear Fairing Composite Designs Market Segmentation
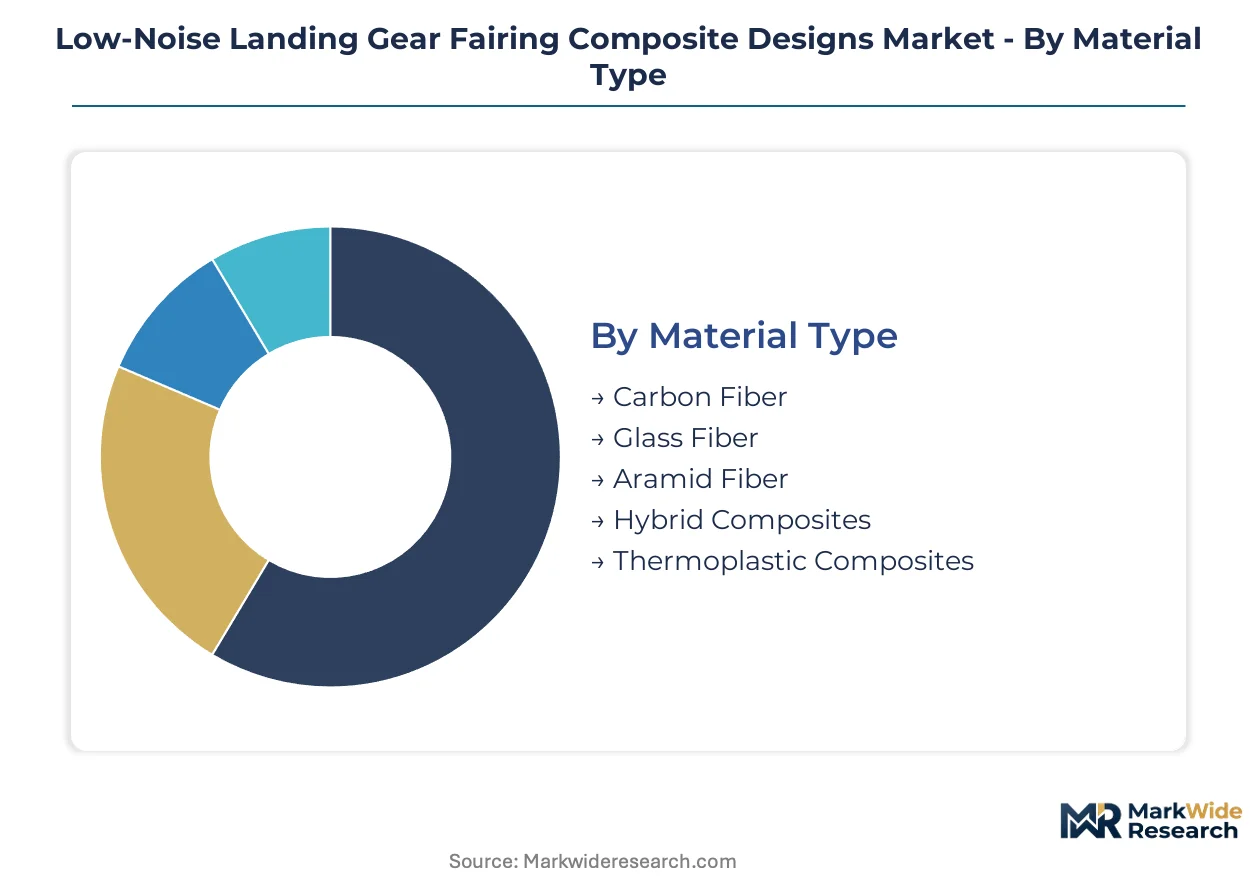
Segmentation in low-noise landing gear fairing composites reveals divergent procurement rhythms across material grades and design architectures. OEM qualification cycles stretch across years for primary structures, while retrofit channels turn inventory in months for modular replacement segments.
Material Type:
Replacement frequency varies dramatically across fiber systems, with thermoplastic formulations enabling rapid field repair cycles that carbon fiber architectures cannot match.
- Carbon Fiber:High-modulus PAN-based prepregs deliver superior stiffness-to-acoustic-impedance ratios for primary fairing structures. Boeing and Airbus specifications dominate procurement in Wichita and Toulouse clusters, where FAA-EASA dual certification requirements lock in multi-year supplier relationships.
- Thermoplastic Composites:Melt-reprocessable PEEK and PPS matrices enable automated fiber placement with in-situ consolidation, collapsing production cycle times. EU Green Deal recyclability mandates are accelerating resin system conversions in European supply chains, with Airbus Aerostructures now prioritizing these matrices for new platform integrations.
- Glass Fiber:E-glass and S-glass formulations serve cost-sensitive regional aircraft applications where acoustic performance thresholds are less stringent.
- Aramid Fiber:Kevlar and Twaron hybrids provide impact resistance for military landing gear fairings operating from unprepared surfaces.
- Hybrid Composites:Carbon-glass and carbon-aramid layups balance cost and performance for business jet retrofits.
Carbon fiber anchors the volume base while thermoplastic composites gain share at the steepest rate.
Design Approach:
Manufacturing complexity and acoustic validation burden separate premium architectures from commodity configurations.
- Sandwich Structure:Nomex or aluminum honeycomb cores bonded between composite facesheets create tuned mass-damping systems. FAA Part 36 stringency around approach-phase noise limits is expanding specification of these multi-layer configurations in Boeing supply chain requirements.
- Integrated Rib:Unitized fairing-rib architectures eliminate mechanical fasteners and their associated turbulent noise generation. GKN Aerospace's long-term contracts with Airbus Aerostructures center on this design philosophy, consolidating what previously required multi-supplier assembly.
- Monolithic:Single-skin composite panels serve legacy narrow-body retrofits where acoustic improvement is secondary to unit cost minimization.
- Corrugated:Geometric stiffening patterns reduce panel resonance without added mass, finding niche application in UAV platforms.
- Multi-Layered:Embedded viscoelastic damping layers between structural plies target specific frequency bands, specified by Collins Aerospace for U.S. platform integrators leveraging proprietary acoustic test data libraries.
Sandwich structures dominate current procurement volumes while integrated rib architectures are climbing the fastest as OEMs pursue assembly cost reduction.
Application:
Certification pathway complexity and fleet replacement dynamics create divergent growth trajectories across aircraft categories.
- Commercial Aircraft:Part 25 certification requirements for transport-category aircraft impose the most rigorous acoustic validation protocols. ICAO Chapter 14 compliance deadlines are compressing design-to-certification timelines, forcing pre-validation through digital twin simulations before physical prototyping.
- UAVs:Modular fairing replacement protocols and distributed propulsion architectures enable rapid design iteration unconstrained by legacy certification frameworks. Joby Aviation and Archer Aviation procurement specifications are creating parallel design standards distinct from Part 25 pathways.
- Military Jets:Survivability and signature management requirements override pure acoustic optimization in defense procurement.
- Regional Aircraft:Cost-sensitive operators prioritize unit economics over marginal noise reduction, sustaining metallic fairing demand.
- Business Jets:Custom interiors and low-volume production favor hand-layup techniques with limited automation.
Commercial aircraft applications anchor the revenue base while UAV segments attract disproportionate R&D investment due to unconstrained design iteration cycles.
End User:
Specification authority is migrating downstream as airlines unbundle acoustic performance guarantees from airframe purchase agreements.
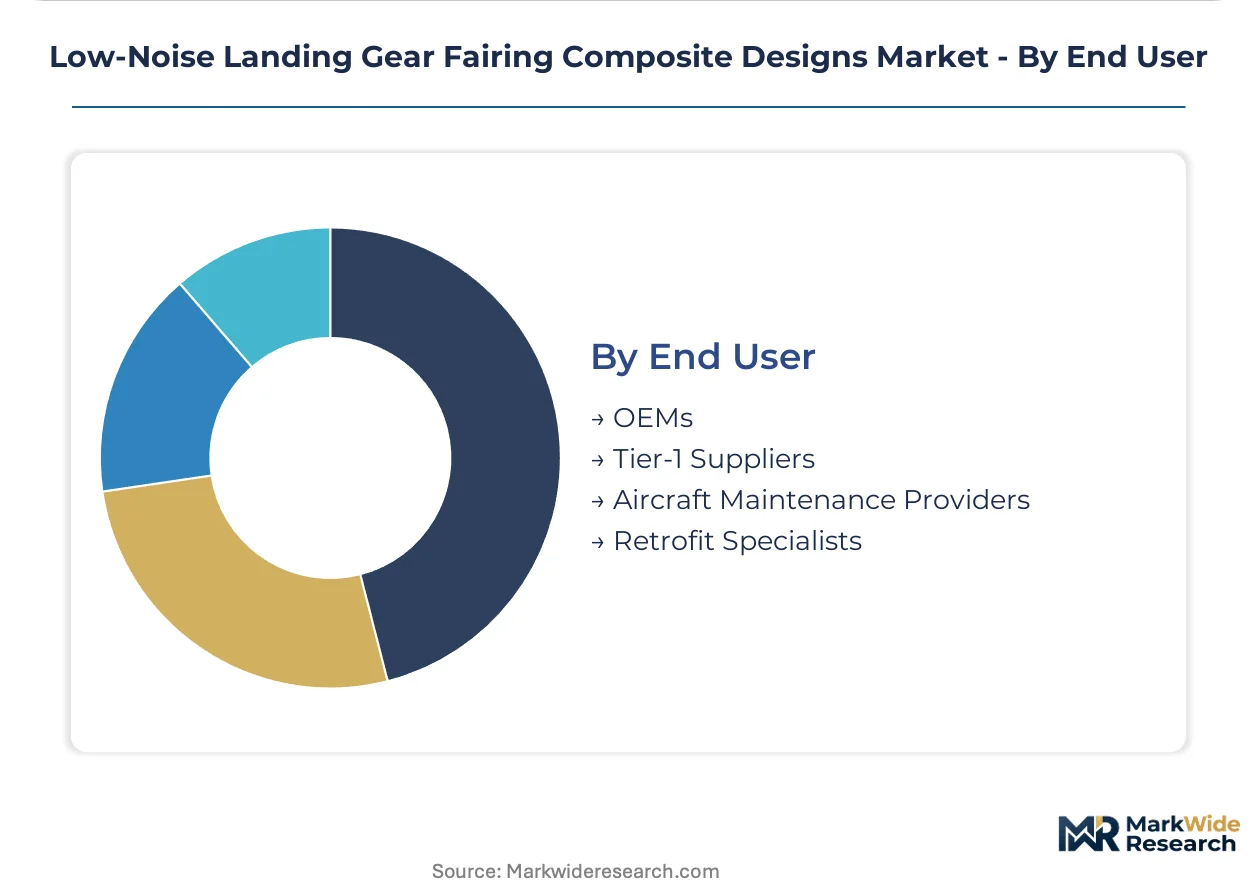
- OEMs:Boeing and Airbus retain design authority for new platform integrations, embedding acoustic targets in supplier technical requirement documents. Their procurement specifications now mandate embedded viscoelastic layers as baseline for landing gear fairing architectures.
- Aircraft Maintenance Providers:Delta and United technical operations teams now dictate retrofit fairing acoustic targets in U.S. carrier fleet renewal programs, capturing specification influence previously held by original equipment manufacturers.
- Tier-1 Suppliers:Safran Landing Systems and GKN Aerospace intermediate between OEMs and raw material converters, consolidating through automated fiber placement investments.
- Retrofit Specialists:Narrow-body cargo conversion programs and legacy fleet upgrades drive demand for aftermarket fairing modules.
OEMs retain the largest contract values while aircraft maintenance providers are expanding their specification influence fastest through standalone replacement contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement around FAA Part 36 certification timelines, while France and Germany prioritize EU Green Deal recyclability mandates. China operates under parallel MEE emissions frameworks that diverge from Western regulatory pathways.
United States
Boeing's supply chain requirements shape composite design specifications for acoustic-dampening fairings. FAA certification timelines compress design-to-certification windows, forcing pre-validation through digital twin simulations. Wichita aerospace clusters host Tier-2 suppliers retooling capacity around out-of-autoclave curing processes.
France
Toulouse aerospace clusters anchor expanded thermoplastic composite capacity for landing gear fairing production. EU Green Deal embodied carbon tracking provisions mandate lifecycle emissions disclosure for structures placed on the European market. Safran Landing Systems leverages in-house resin transfer molding expertise to dominate European OEM supply chains.
Germany
REACH chemical compliance protocols force material substitutions away from certain epoxy systems toward bio-based resin alternatives. ECHA restrictions on amine hardeners create formulation revalidation costs across composite shops. Munich engineering centers concentrate scarce multiphysics simulation talent for coupled fluid-structure-acoustic modeling.
China
COMAC's C919 ramp-up creates parallel certification pathways distinct from FAA-EASA frameworks. MEE emissions regulations evolve under dual carbon goals, generating regulatory tailwinds for bio-epoxy formulations. Domestic suppliers face qualification requirements that diverge from Western test data libraries.
United Kingdom
GKN Aerospace anchors market position through long-term contracts with Airbus Aerostructures for integrated rib fairing architectures. Post-Brexit regulatory alignment creates parallel requalification burdens for suppliers accessing both UK and EU markets. Southwest England manufacturing bases serve as consolidation points for automated fiber placement investments.
Low-Noise Landing Gear Fairing Composite Designs Market Competitive Landscape
Capability concentration sits with integrated aerostructures specialists; scale advantage sits with diversified aerospace conglomerates. The supplier base organizes around three archetypes: landing gear system integrators with captive composite fabrication, independent aerostructures contractors with multi-platform qualifications, and Tier-2 specialists focused on process-specific competencies. Dominant competitive moves include automated fiber placement capacity expansion and digital thread convergence for collapsing prototype iteration cycles.
Among landing gear system integrators, Safran Landing Systems exemplifies the capability-concentrated archetype through in-house resin transfer molding expertise. Collins Aerospace occupies a position anchored on acoustic test data libraries that shorten certification cycles. GKN Aerospace represents the diversified aerostructures contractor model, securing long-term supply relationships through integrated rib fairing architectures.
| Leading Market Players |
|---|
| Safran Landing Systems |
| Collins Aerospace |
| GKN Aerospace |
| Spirit AeroSystems |
| Magellan Aerospace |
| Ducommun |
| TRIUMPH |
| FACC AG |
| Airbus Aerostructures |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Wichita aerospace clusters is compressing lead times for out-of-autoclave curing capacity, forcing Tier-2 suppliers to prioritize long-term offtake agreements over spot orders and tilting pricing power toward composite converters with qualified FAA-EASA dual certification.
Pricing Analysis
Long-term offtake contracts dominate procurement for carbon fiber prepreg formulations serving Boeing and Airbus platforms, while spot purchasing persists for glass fiber retrofits in regional aircraft applications. Price differentiation hinges on FAA Part 36 certification tier and embedded viscoelastic layer complexity, with multi-layer acoustic configurations commanding substantial premiums over monolithic alternatives. Cost compression in thermoplastic formulations is intensifying because EU Green Deal recyclability mandates are accelerating resin system conversions, eroding carbon fiber's historical margin advantage. Cargo conversion programs exhibit the highest price sensitivity, prioritizing aluminum-lithium alternatives where acoustic performance is secondary to unit cost minimization.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk planning for acrylonitrile precursor feedstocks. Carbon fiber precursor production concentrates in Japan and the United States, while thermoplastic resin compounding clusters in Germany and France. Raw material dependencies span PAN-based carbon fiber, PEEK/PPS thermoplastic matrices, and amine hardener chemistries. Single-source vulnerability pervades qualified material lists for FAA-certified epoxy systems, where ECHA restrictions on bisphenol derivatives have eliminated alternative suppliers. Distribution runs through Tier-1 aerostructures contractors that intermediate between OEM technical requirement documents and Tier-2 composite fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital thread convergence between acoustic simulation software and automated fiber placement is collapsing traditional supplier tier boundaries, creating interoperability advantages for converters that master closed-loop design-to-manufacture workflows.
For Market Incumbents: Build certification-data moats by expanding proprietary acoustic test libraries that shorten FAA-EASA dual certification cycles for platform integrators. Anchor capacity additions in Toulouse and Wichita clusters to capture thermoplastic conversion demand from EU Green Deal mandates. Defend against emerging modular fairing specialists in urban air mobility by embedding viscoelastic damping specifications in OEM technical requirement documents before eVTOL design standards crystallize. For New Entrants and Emerging Players: Pursue urban air mobility procurement channels where Joby Aviation and Archer Aviation specifications remain unsettled, creating white-space for rapidly replaceable fairing segments in distributed propulsion architectures. Target UAV retrofit markets where modular replacement protocols enable field repair cycles unconstrained by Part 25 certification burdens. Enter through automated fiber placement partnerships with existing Tier-2 shops rather than greenfield capacity investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermoplastic composite sub-segments as in-situ consolidation eliminates autoclave infrastructure requirements. Long-term viability favors converters with backward integration into resin formulation and forward integration into acoustic testing services. Watch for inflection signals in COMAC C919 supplier qualification announcements, which would validate parallel certification pathways distinct from Western frameworks and unlock Chinese domestic demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Capacity Expansion | Safran Landing Systems pilots robotic deposition cells that collapse raw material conversion and final part geometry realization. |
| Backward Integration into Resin Formulation | GKN Aerospace secures supply chain control over bio-based epoxy alternatives forced by REACH chemical compliance protocols. |
| Acoustic Test Data Library Expansion | Collins Aerospace leverages proprietary databases to compress FAA certification timelines for U.S. platform integrators. |
| Urban Air Mobility Partnership | Joby Aviation procurement specifications create parallel design standards distinct from Part 25 certification pathways. |
| EU Green Deal Compliance Certification | Airbus Aerostructures mandates lifecycle emissions disclosure for structures placed on the European market. |
Research Methodology
Cross-validation between primary interviews with composite manufacturing directors, OEM procurement leads, FAA certification engineers, and acoustic testing specialists anchors the qualitative findings, while secondary sources including FAA Part 36 noise certification databases, EASA CS-36 submissions, customs trade data for carbon fiber precursor imports, and SEC filings from publicly traded aerostructures contractors provide quantitative grounding. Bottom-up segment sizing across material type, design approach, and application categories triangulates against top-down market value estimates derived from OEM procurement disclosure patterns.
Calibration against historical certification timeline data and announced capacity investments by Tier-1 suppliers shapes the analytical framework across the projection horizon. Segmentation dimensions include fiber system grade, manufacturing process type, acoustic performance tier, aircraft platform category, and regional regulatory cluster. CAGRs emerge from fitted growth curves applied to disclosed OEM delivery schedules and retrofit fleet penetration assumptions, with explicit modeling of thermoplastic conversion rates driven by EU Green Deal recyclability mandates and out-of-autoclave process adoption curves.
Macroeconomic conditions sit as an overlay; deviation in commercial aircraft delivery rates, acrylonitrile feedstock pricing, or MEE emissions enforcement intensity in China would shift the trajectory. Forecasts reflect documented assumptions regarding ICAO Chapter 14 compliance deadlines and FAA-EASA regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market