
 Europe Drone Motor Market | 2026-2036
Europe Drone Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drone Motor Market Analytics
The capital-intensity gap between integrated manufacturers and component assemblers is collapsing as in-house magnet production becomes essential for cost control. T-Motor Co. Ltd. leverages captive winding facilities to anchor its position in high-thrust agricultural applications. Maxon Motor differentiates through Swiss-precision manufacturing that dominates defense-adjacent government contracts across the continent. KDE Direct LLC sustains niche leadership in premium aerial cinematography motors through specialized cooling architectures.
A drone motor converts electrical energy into mechanical torque to drive propeller rotation, with brushless DC variants employing permanent-magnet rotors and electronic commutation to achieve power densities exceeding 500W per kilogram for sustained hover operations. The primary purpose spans commercial flight platforms, military reconnaissance systems, and precision agriculture drones where thermal stability determines mission endurance. Brushless DC motors command the largest installed base due to their efficiency advantage in multirotor configurations, while the above 1000W power rating segment captures the fastest growth as heavy-lift delivery trials expand across European logistics networks. Coreless motor architectures retain relevance in recreational micro-drones where minimizing rotational inertia outweighs absolute torque requirements.
EASA's drone certification framework and the EU Green Deal's embodied-carbon tracking requirements are reshaping motor material sourcing and end-of-life recyclability obligations for manufacturers operating within Europe. CE marking compliance under the Machinery Directive imposes electromagnetic compatibility standards that filter out low-cost imports from non-European suppliers. Stakeholders must monitor how EASA's proposed urban air mobility regulations redefine power-to-weight thresholds for motors deployed in congested airspace corridors.
Market Dynamics
EASA's tightening certification framework for unmanned aircraft systems is compressing motor replacement cycles across European commercial fleets. The EU Green Deal's embodied-carbon tracking requirements are forcing manufacturers to reconfigure magnet sourcing and end-of-life recyclability protocols.
Growth Catalysts
- Precision Agriculture Expansion:French and German farming cooperatives are scaling drone fleets for crop monitoring and variable-rate spraying, driving sustained demand for high-thrust brushless DC motors with thermal stability for extended field operations.
- EASA Regulatory Harmonization:The European Union Aviation Safety Agency's unified certification standards are eliminating national fragmentation, enabling cross-border fleet deployments that standardize motor procurement specifications across member states.
- Urban Air Mobility Trials:Heavy-lift logistics networks in Rotterdam, Hamburg, and Milan are piloting last-mile delivery drones, creating demand for above-1000W power-rated motors capable of sustained payload operations in congested corridors.
Market Restraints
- Neodymium Price Volatility:Rare-earth magnet supply concentration in Chinese processing facilities exposes European motor assemblers to input cost swings that compress margin structures on fixed-price government contracts.
- CE Marking Compliance Costs:Electromagnetic compatibility testing under the Machinery Directive filters low-cost non-European imports, raising effective procurement costs for small-scale surveying operators in Southern Europe.
- Battery Energy Density Ceiling:Lithium-polymer pack limitations constrain flight endurance regardless of motor efficiency gains, capping mission utility for long-range infrastructure inspection applications.
Strategic Opportunities
- Poland and Romania Agricultural Modernization:EU Common Agricultural Policy subsidies are accelerating precision farming adoption in Eastern European member states where motor-equipped drone penetration remains below Western European levels.
- Modular Motor-Propeller Integration:Standardized quick-swap architectures are emerging as a procurement preference among Dutch greenhouse operators seeking to minimize field downtime during pollination missions.
- Recyclability Certification Premiums:The EU Green Deal's carbon-border adjustment mechanisms are creating price differentiation for motors with documented closed-loop magnet recovery, favoring producers with captive recycling partnerships.
Industry Challenges
- Electromagnetic Interference Engineering Talent:Shortages of specialists capable of optimizing motor-controller pairing for urban air mobility noise and interference specifications are extending product development timelines for Tier-2 suppliers.
- Multi-Jurisdiction Certification Parallelism:Divergent national implementation timelines for EASA's implementing regulations require manufacturers to maintain multiple technical file versions, inflating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drone Motor Market |
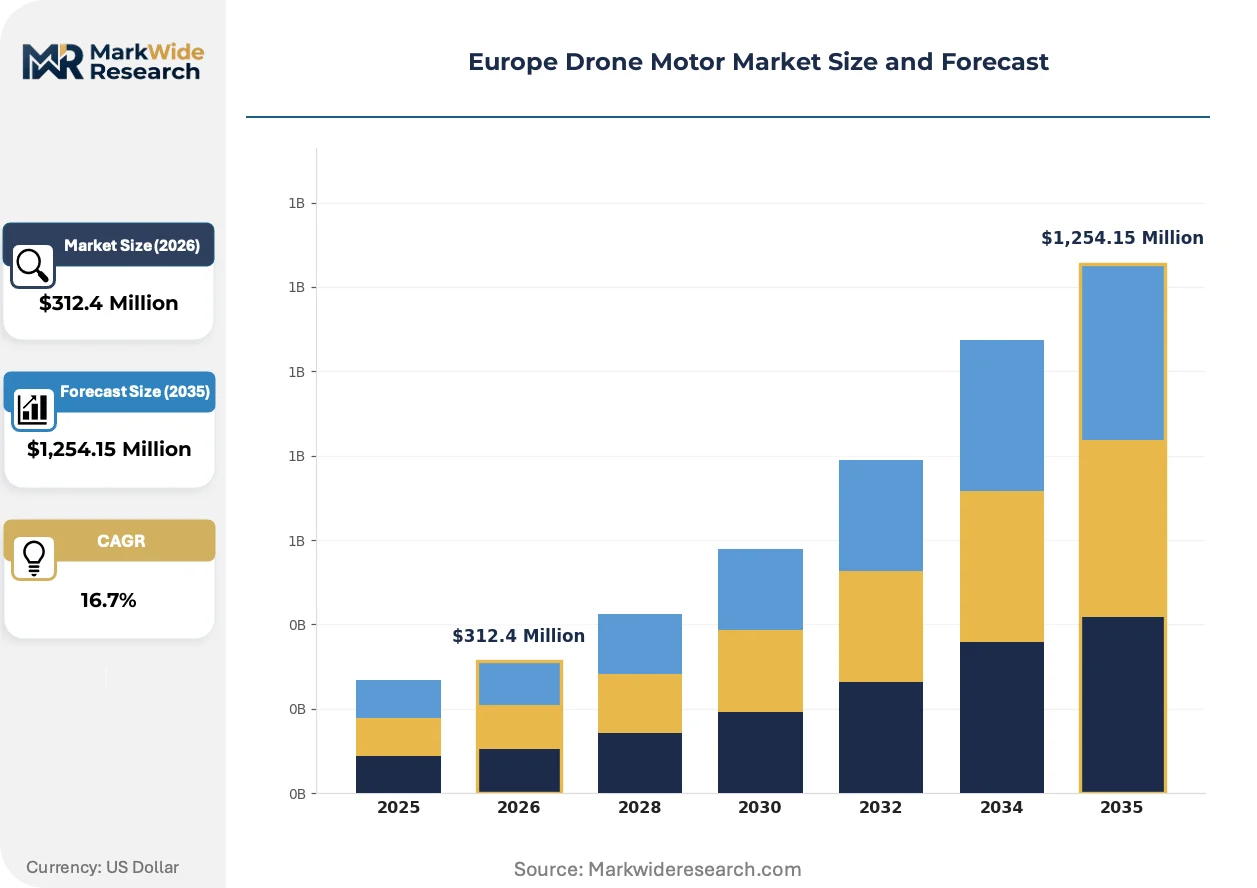
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,254.15 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC, Brushless AC, Coreless, Stepper Application: Aerial Photography, Agriculture, Surveying, Delivery End User: Aerospace, Commercial, Government, Recreational Power Rating: Below 100W, 100-500W, 500-1000W, Above 1000W |
| Companies Covered | KDE Direct LLC, EMAX Innovations Co. Ltd., T-Motor Co. Ltd., Align Corporation Limited, Parrot SAS, Nidec Corporation, SunnySky USA, XXD Motor Co. Ltd., Maxon Motor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drone Motor Market Evolving Landscape
Permanent-magnet rotor architectures are fragmenting into application-specific variants as thermal management and power density requirements diverge across European use cases. Three developments are compressing competitive positioning.
Halbach array magnet configurations are fragmenting conventional surface-mounted rotor designs by concentrating magnetic flux in targeted pole arcs. Agricultural drone OEMs in Spain and Italy are adopting these arrays for high-torque hover efficiency, enabling smaller motor footprints without sacrificing thrust output. The technology is fragmenting supplier tiers by rewarding in-house magnet shaping capabilities over commodity winding operations.
The EU AI Act's risk-classification framework for autonomous flight systems is mandating deterministic motor control algorithms with verifiable failure modes. Manufacturers serving defense-adjacent government contracts must document electromagnetic torque ripple limits under fault conditions, shifting firmware development resources toward formal verification processes. Swiss and German suppliers with existing aerospace quality systems are capturing specification-setting roles in this transition.
Leasing arrangements for motor-propeller subassemblies are displacing outright purchase in Scandinavian commercial surveying fleets. Danish and Norwegian operators facing seasonal demand fluctuations prefer operational expenditure models that bundle predictive maintenance analytics, transferring thermal degradation risk to component suppliers. This restructuring concentrates procurement authority with fleet management platforms rather than individual drone OEMs.
Europe Drone Motor Market Segmentation
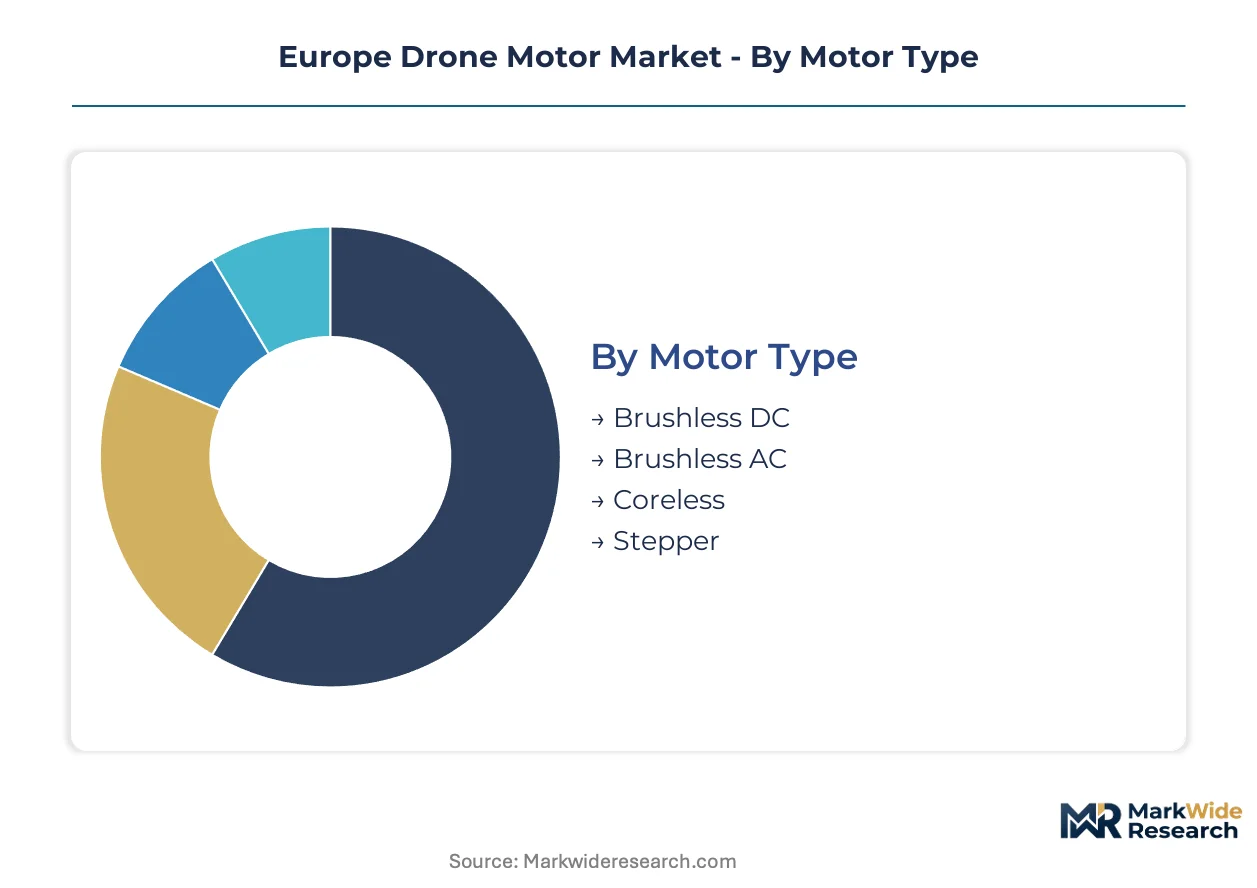
Motor specifications across European drone fleets diverge sharply by mission profile and regulatory classification. EASA's tiered operational categories directly constrain power-to-weight ratios and electromagnetic compatibility requirements for each segment.
Motor Type:
EASA's electromagnetic compatibility standards under the Machinery Directive filter import eligibility by commutation architecture and magnet composition.
- Brushless DC:Permanent-magnet rotors with electronic commutation achieve power densities exceeding 500W per kilogram. French and German precision agriculture fleets specify these for thermal stability during extended field spraying operations.
- Brushless AC:Synchronous designs with sinusoidal drive waveforms reduce torque ripple for aerial cinematography. Italian and Spanish commercial surveying operators prioritize these for vibration-sensitive payload stabilization.
- Coreless:Eliminated iron cores minimize rotational inertia in sub-250g recreational platforms. Belgian and Dutch hobbyist retailers stock these for EU drone regulation weight-class compliance.
- Stepper:Discrete angular positioning suits gimbal actuation and camera stabilization subsystems. German industrial inspection OEMs integrate these for precise sensor orientation.
Established volume favors Brushless DC; emerging adoption favors Brushless AC.
Application:
End-use concentration maps directly onto subsidy flows and regulatory sandbox geographies across member states.
- Agriculture:Variable-rate spraying and crop monitoring in France, Germany, and Poland drive procurement of high-thrust thermal-stable architectures. EU Common Agricultural Policy subsidies compress payback periods for motor-equipped fleet expansion.
- Surveying:Topographic mapping and infrastructure inspection across Southern Europe demands precision positioning with minimal electromagnetic interference. Spanish and Italian operators specify shielded motor housings for utility corridor flights.
- Delivery:Last-mile logistics trials in Rotterdam, Hamburg, and Milan require above-1000W sustained payload capability. Urban air mobility corridors impose noise and redundancy specifications that filter motor suppliers.
- Aerial Photography:Cinematic production in Scandinavian markets prioritizes smooth torque delivery and rapid thermal recovery. Danish and Norwegian leasing models bundle predictive maintenance for seasonal demand peaks.
Subsidy-dependent agriculture anchors current procurement; delivery trials are climbing the fastest.
End User:
Customer-type segmentation aligns with certification burden and contract structure rather than absolute unit volume.
- Commercial:Fleet operators in precision agriculture and surveying face compressed replacement cycles as EASA implements stricter airworthiness directives. Dutch greenhouse cooperatives favor modular quick-swap architectures to minimize pollination mission downtime.
- Government:Defense-adjacent contracts across Switzerland and Germany mandate documented failure modes and formal verification of control algorithms. Swiss-precision manufacturers capture specification-setting roles through existing aerospace quality systems.
- Aerospace:Urban air mobility developers in German and French corridors prototype heavy-lift platforms with redundant motor configurations. EASA's proposed congested airspace regulations redefine power-to-weight thresholds for certification.
- Recreational:Sub-250g platforms dominate Belgian and Austrian hobbyist markets. CE marking compliance filters low-cost non-European imports, raising effective procurement costs for entry-level operators.
Commercial fleets generate highest unit velocity; aerospace applications show steepest expansion trajectory.
Power Rating:
Power tier selection constrains mission endurance and payload flexibility within lithium-polymer energy density limits.
- Above 1000W:Heavy-lift delivery drones and agricultural sprayers require sustained thermal performance. Rotterdam and Hamburg logistics pilots specify these for last-mile payload operations in urban corridors.
- 500-1000W:Professional surveying and mapping platforms balance thrust with flight duration. Italian infrastructure inspectors deploy these for medium-range transmission line assessments.
- 100-500W:Recreational photography and light commercial monitoring dominate this tier. Polish and Romanian agricultural modernization programs subsidize motor upgrades into this range.
- Below 100W:Micro-drones and educational platforms operate here. Coreless architectures minimize inertia for agility-focused applications in training environments.
Mid-range power ratings anchor installed base; above-1000W systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers command pricing premiums over Southern European assemblers, while Polish and Romanian agricultural modernization programs compress procurement costs through EU subsidy flows.
Germany
Defense-adjacent government contracts and urban air mobility corridors in Hamburg drive demand for formally verified motor control systems. EASA's implementing regulations filter suppliers through electromagnetic compatibility standards. Bavarian and Baden-Württemberg industrial clusters concentrate aerospace-quality manufacturing for heavy-lift logistics trials.
France
Farming cooperatives in the Île-de-France and Auvergne-Rhône-Alpes regions scale precision agriculture fleets for crop monitoring and variable-rate spraying. EU Common Agricultural Policy subsidies compress payback periods for motor-equipped drone expansion. Toulouse and Paris-Saclay aerospace clusters prototype redundant motor configurations for congested airspace operations.
Netherlands
Greenhouse operators in the Randstad region favor modular quick-swap motor-propeller architectures to minimize pollination mission downtime. CE marking compliance under the Machinery Directive raises effective procurement costs above non-European import levels. Rotterdam logistics pilots specify above-1000W motors for last-mile delivery trials in urban corridors.
Poland
EU Common Agricultural Policy subsidies accelerate precision farming adoption where motor-equipped drone penetration trails Western European levels. The EU Green Deal's embodied-carbon tracking requirements reshape magnet sourcing protocols for assemblers. Warsaw and Krakow distribution hubs channel Eastern European procurement toward standardized brushless DC architectures.
Italy
Commercial surveying operators in Lombardy and Emilia-Romagna prioritize shielded motor housings for utility corridor flights with minimal electromagnetic interference. Brushless AC synchronous designs reduce torque ripple for vibration-sensitive payload stabilization. Milan's urban air mobility sandbox creates specification pressure for noise-compliant motor configurations.
Europe Drone Motor Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive magnet production and Swiss-precision fabricators serving defense-adjacent contracts. The vendor base stratifies across three tiers: large-scale agricultural motor specialists, premium cinematography component suppliers, and commodity assemblers dependent on external rare-earth sourcing. Two dominant competitive moves are reshaping positioning: backward integration into permanent-magnet supply chains and modular quick-swap architecture development for agricultural fleet operators.
Within the integrated manufacturing tier, T-Motor Co. Ltd. and Maxon Motor exemplify divergent specialization paths. T-Motor represents the high-thrust agricultural archetype with captive winding facilities, while Maxon occupies the Swiss-precision position for formally verified government contracts. KDE Direct LLC sits within the premium cinematography niche, anchoring specialized cooling architecture demand from Scandinavian leasing-based fleets.
| Leading Market Players |
|---|
| KDE Direct LLC |
| EMAX Innovations Co. Ltd. |
| T-Motor Co. Ltd. |
| Align Corporation Limited |
| Parrot SAS |
| Nidec Corporation |
| SunnySky USA |
| XXD Motor Co. Ltd. |
| Maxon Motor |
| Others |
Value Network & Pricing Analysis
CE marking compliance under the Machinery Directive gates both supplier qualification and price differentiation simultaneously, filtering low-cost non-European imports while creating tiered procurement costs across member states. Agricultural fleet operators in France and Germany absorb premium pricing for formally verified thermal-stable architectures, whereas Southern European surveying contractors face compressed margins from electromagnetic compatibility testing overhead.
Pricing Analysis
Configured-to-order pricing for formally verified motor control systems commands spreads of 40-60% above standard brushless DC catalog offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and magnet traceability documentation. Cost compression in the standard tier is intensifying because Polish and Romanian assemblers leverage EU Common Agricultural Policy subsidies to undercut Western European sourcing. Small-scale recreational operators exhibit highest price sensitivity, while defense-adjacent government buyers prioritize failure-mode documentation over unit economics.
Supply Chain Analysis
Rare-earth magnet processing concentration in Chinese facilities creates a chokepoint that exposes European motor assemblers to input cost volatility and regulatory scrutiny under the EU Green Deal's embodied-carbon tracking. Neodymium-iron-boron magnets, copper windings, and silicon steel laminations draw from concentrated Asian supply bases. Single-source vulnerability in magnet alloying operations amplifies margin risk for fixed-price government contracts. Distribution runs through Warsaw and Krakow hubs for Eastern European agricultural markets, with Rotterdam and Hamburg serving logistics trial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electromagnetic interference engineering talent shortages are constraining product development timelines, creating asymmetric returns for stakeholders who secure captive capabilities before EASA's urban air mobility regulations finalize.
For Market Incumbents: Compound defensive positioning through backward integration into permanent-magnet supply chains and captive recycling partnerships that satisfy EU Green Deal recyclability premiums. Swiss-precision manufacturers should extend formally verified control algorithm documentation to capture specification-setting roles as the EU AI Act mandates deterministic failure modes. Threat of emerging Polish and Romanian assemblers with subsidy-backed cost structures demands preemptive channel control in greenhouse pollination segments. For New Entrants and Emerging Players: EASA's proposed fast-track certification pathway for sub-250g platforms offers entry into Belgian and Dutch recreational markets where CE marking filters incumbent dominance. White-space targets include modular quick-swap architectures for Dutch greenhouse operators and shielded housings for Italian utility corridor surveying. Go-to-market positioning should emphasize operational expenditure models bundling predictive maintenance analytics to mirror Scandinavian leasing preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across above-1000W power-rated segments as heavy-lift delivery trials demand redundant thermal management systems. Long-term viability favors integrated manufacturers with captive magnet production or Swiss-precision fabricators holding defense-adjacent aerospace quality certifications. Acquisition target archetypes include Tier-2 suppliers with electromagnetic interference optimization capabilities and documented EASA technical files. Signal to monitor: EASA's implementing regulation timeline divergence across member states, which would inflate multi-jurisdiction quality assurance overhead for non-integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium sourcing insulates margin structures from Chinese processing volatility under EU carbon-border adjustments. |
| Modular Quick-Swap Architecture Development | Standardized motor-propeller integration captures Dutch greenhouse procurement preferences for minimized pollination downtime. |
| Formal Verification of Control Algorithms | Documented deterministic failure modes satisfy EU AI Act mandates for defense-adjacent Swiss and German government contracts. |
| Recyclability Certification Investment | Closed-loop magnet recovery documentation commands price premiums under EU Green Deal carbon-border mechanisms. |
| Eastern European Distribution Hub Establishment | Warsaw and Krakow positioning captures EU Common Agricultural Policy subsidy flows accelerating Polish and Romanian agricultural modernization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with precision agriculture fleet managers, electromagnetic compatibility testing engineers, EASA certification specialists, and brushless DC motor procurement leads at Dutch greenhouse cooperatives. Secondary validation drew from EASA implementing regulation drafts, EU Common Agricultural Policy subsidy disbursement records, CE marking compliance databases, and rare-earth magnet trade flow customs data. Bottom-up unit economics from motor replacement cycle data were triangulated against top-down market sizing from agricultural drone fleet expansion projections.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by motor type, power rating tier, application end-use, and customer certification burden. CAGRs were derived from trajectory fitting to EASA regulatory implementation schedules and subsidy program renewal assumptions. Industry-specific inputs included lithium-polymer energy density constraints on flight endurance and thermal degradation curves from predictive maintenance analytics in Scandinavian leasing fleets.
Decision-makers should treat outputs as directional under assumptions of EASA regulatory harmonization proceeding on published timelines; material deviation in national implementation schedules would warrant model refresh. Forecasts embed assumptions around neodymium price volatility bands and EU Green Deal carbon-border adjustment enforcement intensity. Practitioners should keep alternative scenarios live as EASA's urban air mobility power-to-weight threshold proposals and EU AI Act risk-classification refinements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aerostructure Equipment Market