
 Aerostructure Equipment Market | 2026-2036
Aerostructure Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aerostructure Equipment Market Analysis
European machining consortiums is repositioning capacity toward titanium and composite hybrid processing for next-generation wing boxes. GKN Aerospace leverages its Bristol and Munich facilities to sustain long-term supply contracts with Airbus A350 and Boeing 787 programs. Spirit AeroSystems anchors fuselage panel production in Wichita, Kansas, while Safran S.A. competes through specialized landing gear and nacelle equipment integration.
Aerostructure equipment encompasses the machinery, tooling, and automated systems used to fabricate, assemble, and inspect primary aircraft structural components, typically operating to tolerances of ±0.005 inches for metallic assemblies and ±0.010 inches for large composite bonds, with primary purpose being the conversion of raw materials into flight-critical assemblies that meet strict fatigue and damage-tolerance requirements. CNC Machining equipment occupies the largest installed base across airframe and wing structure applications, while Additive Manufacturing represents the fastest-growing technology segment as wire-arc and powder-bed systems penetrate titanium bracket production. Robotics automation commands premium margins in fuselage drilling and fastening cells where throughput consistency determines program economics.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and ISO 9100 quality management frameworks collectively dictate equipment calibration protocols, traceability systems, and supplier qualification pathways for aerostructure manufacturers. The EU Green Deal emissions benchmarks and emerging sustainable aviation fuel mandates are redirecting R&D budgets toward energy-efficient forming presses and reduced-waste composite layup systems. Stakeholders must monitor how dual carbon goals in China and Europe reshape capital allocation between metallic and composite processing equipment portfolios.
Market Dynamics
Composite-intensive airframe programs are forcing capital reallocation across metallic and hybrid processing equipment portfolios as Boeing and Airbus accelerate single-aisle output targets.
Growth Catalysts
- FAA Part 25 Certification Standards:Stringent fatigue and damage-tolerance requirements for metallic assemblies drive precision equipment upgrades across North American final assembly lines. Tier-1 suppliers in Wichita and Charleston expand automated drilling cells to meet these protocols.
- Narrowbody Production Surge:Airbus A320 and Boeing 737 rate increases pull demand for high-throughput wing box machining centers. Final assembly lines in Toulouse and Renton anchor this equipment procurement cycle.
- Wire-Arc Additive Manufacturing:Titanium bracket production via directed energy deposition reduces buy-to-fly ratios. Powder-bed systems penetrate low-volume structural applications in defense and space segments.
Market Restraints
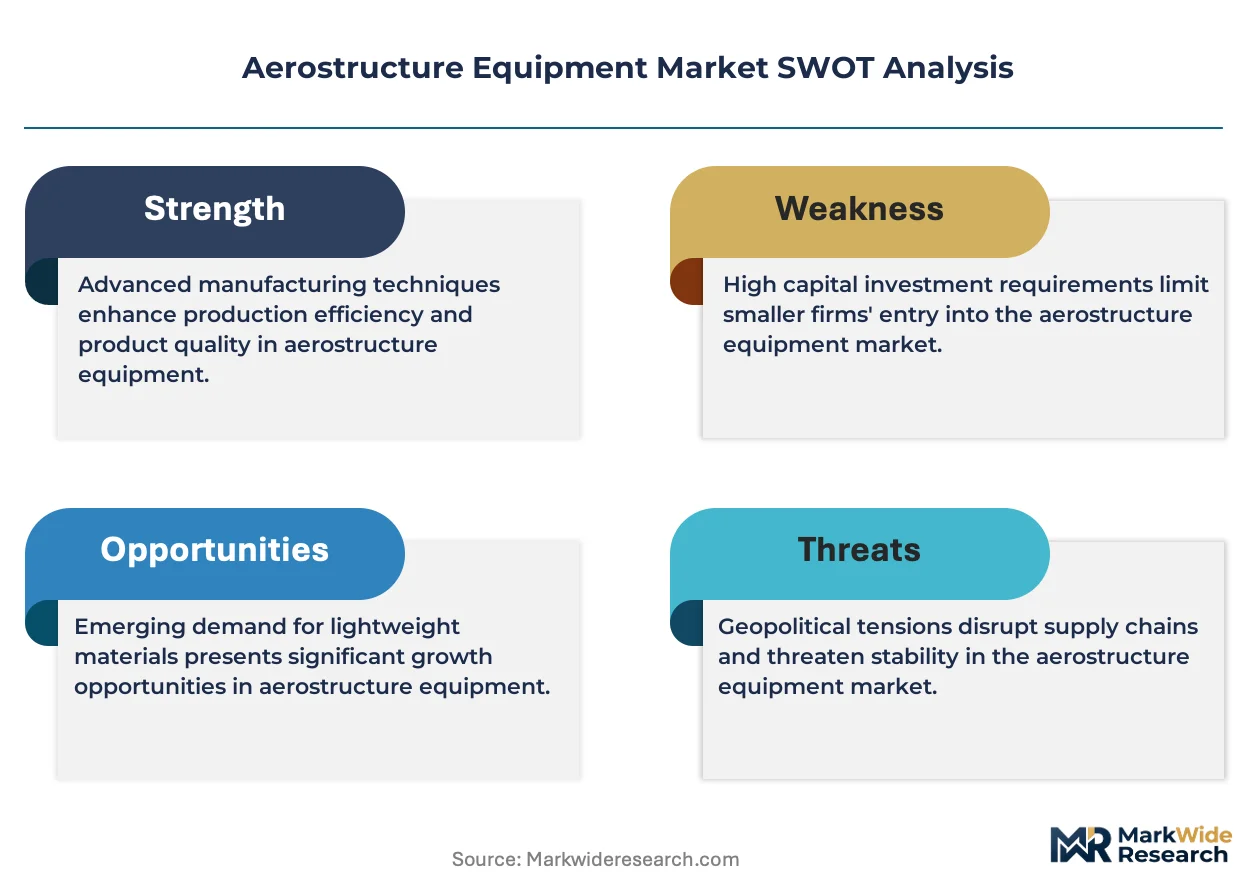
- Titanium Input Volatility:Sponge and mill product price swings compress margin predictability for long-lead equipment contracts. Russian supply displacement strains Western aerospace material chains.
- European Equipment Concentration:Specialized forming press and autoclave manufacturing clusters in Germany and France create single-source dependency risks for tier-2 fabricators.
- Legacy CNC Interoperability:Decades-old machine tool fleets lack data architecture for digital thread integration. Retrofit costs deter mid-tier suppliers from connectivity upgrades.
Strategic Opportunities
- India Defense Localization:Indigenization mandates under the Defence Acquisition Procedure create captive demand for airframe fabrication equipment. Hindustan Aeronautics and private consortia build greenfield composites capability.
- EU Green Deal Alignment:Energy-efficient forming presses and reduced-waste AFP/ATL systems qualify for sustainable manufacturing incentives. Equipment vendors reposition R&D toward carbon-footprint reduction metrics.
- Robotics-Fiber Placement Convergence:Automated fiber placement heads integrated with collaborative robotics enable complex geometries previously manual. This hybrid architecture penetrates nacelle and control surface production.
Industry Challenges
- Composite Technician Scarcity:Lamination, bond assembly, and NDT inspection skills lag program ramp rates. Training pipeline gaps extend equipment commissioning timelines.
- EASA CS-25 Certification Burden:New equipment qualification for flight-critical applications demands extensive witness testing. Documentation protocols stretch supplier onboarding to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerostructure Equipment Market |
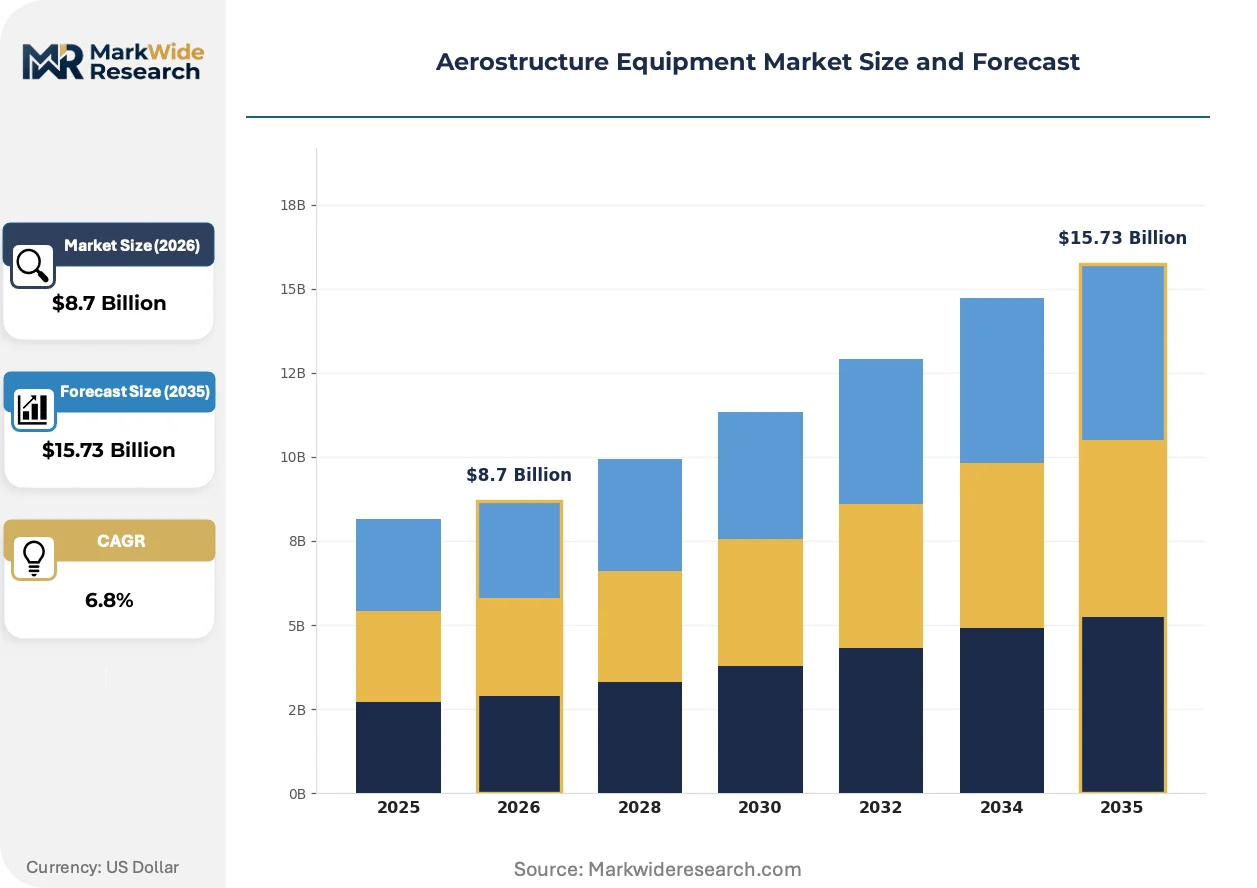
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machining, Assembly, Inspection, Automation Technology: Additive Manufacturing, CNC Machining, Robotics, Composites End User: Commercial Aviation, Defense, Space, Aftermarket Application: Airframe, Wing Structure, Fuselage, Tail Section |
| Companies Covered | GKN Aerospace, Safran S.A., Spirit AeroSystems, Inc., Mitsubishi Heavy Industries Ltd., Collins Aerospace, Airbus SE, Leonardo S.p.A., Triumph Group, Inc., Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerostructure Equipment Market Emerging Trajectories
Digital thread architecture and sustainable manufacturing mandates are compressing equipment replacement cycles while redefining supplier qualification pathways across tier-1 and tier-2 fabricators.
Automated fiber placement systems are automating complex composite layup sequences previously executed by skilled technicians. Boeing 787 and Airbus A350 wing skin producers deploy these cells to achieve ±0.010 inch tolerance consistency at production rates exceeding 40 meters per hour. The technology is automating workforce reduction in high-cost manufacturing geographies while enabling defect traceability through the full part pedigree.
EASA CS-25 and FAA Part 25 harmonization efforts on composite damage tolerance are mandating enhanced ultrasonic inspection integration within fabrication cells. Equipment suppliers must embed phased-array NDT capability directly into AFP and ATL platforms. European wing box manufacturers in Germany and the United Kingdom face the steepest compliance retrofit requirements.
Performance-based equipment contracting is displacing traditional capital purchase models for mid-tier aerostructure suppliers. Airbus and Boeing tier-1 partners now contract drilling and fastening cells on cost-per-hole or cost-per-fastener metrics. This shift concentrates most visibly in French and Italian supplier parks where program risk-sharing agreements dominate procurement architecture.
Aerostructure Equipment Market Segmentation
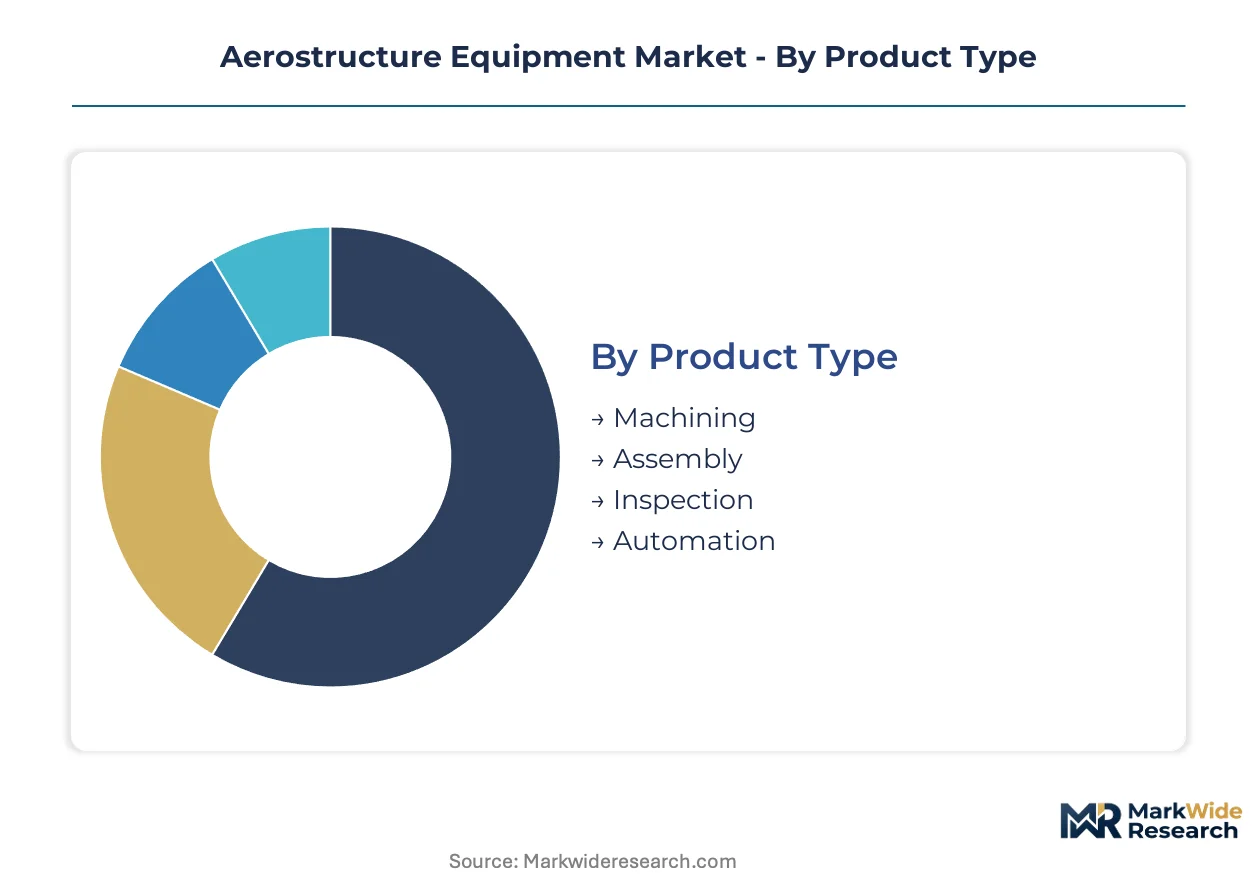
Aerostructure equipment procurement patterns diverge sharply across product categories, with commercial aviation OEMs prioritizing throughput consistency while defense contractors emphasize flexibility for low-volume, high-mix programs. Understanding these segment boundaries clarifies where capital allocation concentrates and where technology transitions create displacement risk.
Product Type:
Buyers in this category separate by production philosophy—high-volume final assembly lines demand integrated cells, while job shops prioritize modularity and retooling speed.
- Machining:Five-axis CNC centers and titanium-optimized mill-turn platforms dominate wing spar and bulkhead fabrication. Airbus A320 rate increases in Toulouse and Boeing 737 output in Renton anchor demand for high-throughput configurations. FAA Part 25 fatigue specifications drive precision requirements to ±0.005 inches for metallic assemblies.
- Assembly:Automated drilling and fastening cells integrate force-feedback robotics with real-time quality verification. Spirit AeroSystems in Wichita deploys these systems for fuselage panel joining where throughput consistency determines program economics. EASA CS-25 documentation protocols extend equipment commissioning timelines to 18-24 months.
- Inspection:Phased-array ultrasonic and computed tomography systems embed defect traceability into production workflows. These platforms serve flight-critical bond verification for composite-intensive airframes.
- Automation:Collaborative robotics and autonomous guided vehicles streamline material handling across tier-1 supplier parks. The segment captures systems that reduce manual intervention without full process replacement.
Machining leads volumes today; Automation is gaining share fastest as labor costs climb in established manufacturing clusters.
Technology:
Capital deployment here tracks material transitions—titanium and composite growth pulls investment away from legacy aluminum-optimized systems.
- CNC Machining:Conventional subtractive platforms retain the largest installed base across airframe and wing applications. European machining consortiums in Bristol and Munich reposition capacity toward titanium-composite hybrid processing for next-generation wing boxes.
- Additive Manufacturing:Wire-arc directed energy deposition reduces buy-to-fly ratios in titanium bracket production. Powder-bed systems penetrate low-volume structural applications in defense and space segments where lot sizes justify slower build rates.
- Robotics:Force-controlled drilling and fastening end-effectors achieve ±0.001 inch positional repeatability in fuselage assembly. Premium margins concentrate where throughput guarantees underpin risk-sharing contracts.
- Composites:Automated fiber placement and tape laying systems automate layup sequences previously executed by skilled technicians. Boeing 787 and Airbus A350 wing skin producers deploy these cells to achieve ±0.010 inch tolerance consistency.
CNC Machining retains the dominant installed base; Additive Manufacturing is climbing the fastest as wire-arc systems mature for structural bracket applications.
End User:
Customer type determines specification stringency—commercial programs prioritize rate and cost, while defense and space accept longer lead times for customized capability.
- Commercial Aviation:Narrowbody and widebody OEMs drive the dominant equipment procurement cycle. Final assembly lines in the United States, France, and China anchor demand for high-throughput, standardized platforms.
- Defense:Military airframe programs require flexible equipment capable of absorbing design changes mid-production. Indigenization mandates under India's Defence Acquisition Procedure create captive demand for fabrication equipment as Hindustan Aeronautics builds greenfield composites capability.
- Space:Launch vehicle and satellite structures demand specialized tooling for thin-wall aluminum-lithium and carbon fiber tanks. Low volumes and extreme performance requirements justify premium equipment configurations.
- Aftermarket:MRO providers retrofit legacy fleets with corrosion-resistant replacements and structural modifications. Equipment needs concentrate on portable inspection systems and modular repair cells.
Commercial Aviation dominates absolute equipment spend; Defense is expanding most quickly as Western nations reshore critical airframe manufacturing capacity.
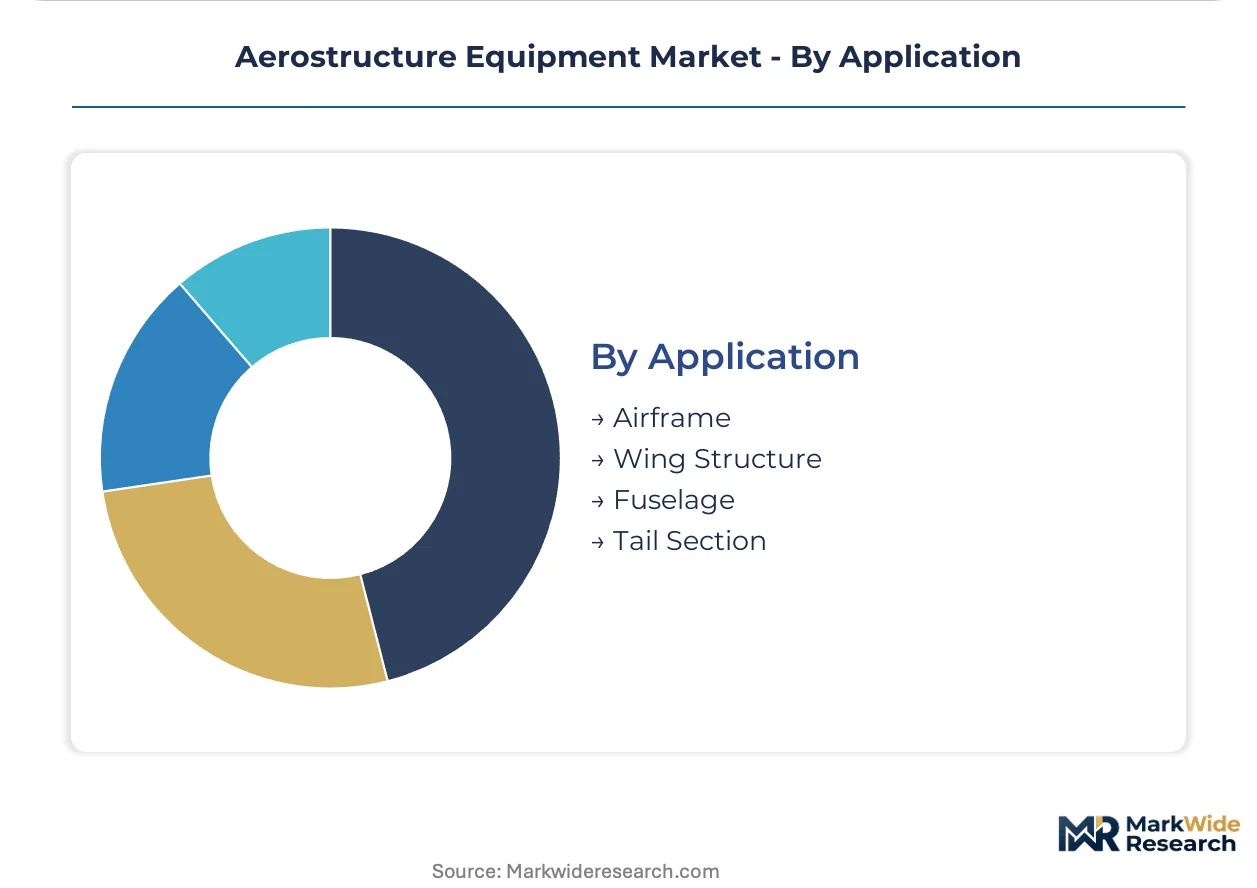
Application:
Structural location dictates equipment scale and tolerance requirements—wing boxes demand the largest machining envelopes, while tail sections prioritize complex contouring capability.
- Airframe:Central structural elements including bulkheads, frames, and longerons require multi-axis machining centers with 20-meter-plus bed lengths. GKN Aerospace sustains long-term supply contracts through its Bristol and Munich facilities for these components.
- Wing Structure:Spar, rib, and skin fabrication commands the most capital-intensive equipment configurations. European wing box manufacturers in Germany and the United Kingdom face steep compliance retrofit requirements as EASA and FAA harmonize composite damage tolerance standards.
- Fuselage:Panel assembly and joining operations rely on automated drilling and sealing systems. Safran S.A. competes through specialized equipment integration for landing gear and nacelle adjacent structures.
- Tail Section:Empennage components require complex contour machining and composite layup for control surfaces. Smaller structural envelopes permit more flexible, reconfigurable equipment platforms.
Wing Structure leads capital deployment today; Airframe is gaining share fastest as next-generation programs adopt integrated monolithic designs requiring fewer joints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting aerostructure equipment procurement toward jurisdictions where FAA and EASA compliance costs diverge from emerging certification pathways. Tier-1 suppliers now optimize capital deployment across final assembly clusters based on harmonization gaps between Western airworthiness standards and localized industrial policy incentives.
United States
FAA Part 25 certification protocols anchor precision equipment demand across Boeing's Renton and Charleston final assembly lines. The Buy American Act and Defense Production Act incentives strengthen domestic machining and composite fabrication capacity. Wichita, Kansas hosts Spirit AeroSystems' fuselage panel operations alongside specialized drilling cell deployments.
France
Airbus A320 rate increases in Toulouse pull high-throughput wing box machining center procurement from European suppliers. EU Green Deal sustainable manufacturing benchmarks redirect R&D toward energy-efficient forming presses. The Toulouse-Blagnac supplier park concentrates automated fiber placement systems for A350 wing skin production.
China
Dual carbon goals and indigenous airframe programs under COMAC accelerate composite layup equipment localization. MIIT industrial policy supports domestic CNC machining center development for C919 narrowbody production. The Shanghai Pudong and Tianjin final assembly clusters anchor equipment demand from state-owned tier-1 fabricators.
Germany
EASA CS-25 harmonization efforts with FAA standards impose steep compliance retrofit requirements on wing box manufacturers. The Bavarian and Hamburg aerospace clusters specialize in titanium-composite hybrid processing equipment for next-generation programs. German forming press and autoclave manufacturing maintains concentrated supply positions.
India
Defence Acquisition Procedure indigenization mandates create captive demand for airframe fabrication equipment. Hindustan Aeronautics Limited builds greenfield composites capability under BIS quality frameworks. The Bangalore and Hyderabad defense manufacturing corridors attract automated fiber placement and inspection system deployments.
Aerostructure Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue wire-arc additive manufacturing and robotics-fiber placement convergence. The vendor base stratifies across integrated OEM-affiliated units, independent tier-1 specialists, and regional fabrication equipment suppliers. Three archetypes dominate: aerospace-integrated conglomerates with captive equipment divisions; pure-play aerostructure fabricators with long-term program contracts; and technology-forward equipment vendors penetrating automated inspection and additive platforms. Competitive moves concentrate on strategic partnerships for digital thread integration and geographic expansion into India and Southeast Asian defense supply chains.
Among UK-based aerospace-integrated specialists, GKN Aerospace exemplifies the conglomerate archetype through its Bristol and Munich facility network. French industrial group Safran S.A. occupies a position within the tier-1 specialist tier, while US-based Spirit AeroSystems, Inc. anchors the pure-play fabricator segment with Wichita-centered fuselage operations. These three entities represent distinct capital allocation strategies: European machining consortium repositioning, specialized landing gear and nacelle integration, and high-volume narrowbody panel production respectively.
| Leading Market Players |
|---|
| GKN Aerospace |
| Safran S.A. |
| Spirit AeroSystems, Inc. |
| Mitsubishi Heavy Industries Ltd. |
| Collins Aerospace |
| Airbus SE |
| Leonardo S.p.A. |
| Triumph Group, Inc. |
| Boeing Company |
| Others |
Supply Flow & Price Mechanics
Titanium sponge index volatility cascades through three distinct pricing tiers as tier-1 fabricators pass input cost swings through equipment contracts with varying force-protection clauses. Long-lead machining center procurement in Wichita and Toulouse absorbs these shocks differently depending on contract structure and buyer consolidation power.
Pricing Analysis
Direct-to-OEM discounting dominates high-volume narrowbody programs where Airbus and Boeing tier-1 partners negotiate cost-per-hole performance contracts. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified precision cells from ISO-compliant mid-tier platforms and uncertified job-shop equipment. Cost compression in standard-tier CNC centers intensifies because Chinese domestic suppliers undercut European forming press margins. Defense contractors show lowest price sensitivity due to indigenization mandates and sole-source qualification requirements.
Supply Chain Analysis
Transatlantic freight cost spikes for oversized autoclave and press shipments have compressed margin structures for German and French equipment exporters serving North American final assembly lines. Manufacturing concentration in Germany, France, and China draws from titanium sponge feedstock, precision ball screw assemblies, and high-torque servo motors. Single-source vulnerability around specialized forming press manufacturing in Bavaria and Hamburg creates procurement risk for tier-2 fabricators lacking dual-qualification pathways. Distribution runs through OEM-affiliated captive suppliers and independent regional distributors with localized service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EASA CS-25 certification timelines stretch 18-24 months versus FAA Part 25 pathways, creating cost and speed differentials for equipment vendors selecting qualification jurisdictions.
For Market Incumbents: Lock in long-term supply contracts with Airbus A350 and Boeing 787 programs before wire-arc additive manufacturing displaces conventional titanium bracket machining. Backward integration into titanium-composite hybrid processing capability in Bristol and Munich facilities defends against emerging entrants with robotics-fiber placement convergence technology. Certification investment in dual FAA-EASA qualification pathways preserves access to both Atlantic basin procurement cycles.
For New Entrants and Emerging Players: Enter via India's Defence Acquisition Procedure indigenization mandates where Hindustan Aeronautics Limited builds greenfield composites capability with limited incumbent equipment presence. Automated fiber placement systems for nacelle and control surface production represent the most penetrable white-space segment given complex geometry requirements and skilled technician scarcity. Go-to-market positioning through performance-based cost-per-fastener contracting models aligns with tier-1 risk-sharing agreement structures in French and Italian supplier parks.
For Investors and Strategic Acquirers: Asymmetric upside sits with wire-arc additive manufacturing specialists and robotics-integrated inspection platform developers over the coming decade. Acquisition targets should demonstrate embedded digital thread architecture and sustainable manufacturing credentials qualifying for EU Green Deal incentives. Watch for EASA-FAA harmonization completion on composite damage tolerance standards as the signal for accelerated equipment replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Processing | GKN Aerospace's Bristol facility secures long-term A350 wing box supply through captive titanium-composite hybrid capacity. |
| Robotics-Fiber Placement Convergence | Collaborative robotics integration with AFP heads penetrates nacelle production previously requiring manual skilled labor. |
| Dual Certification Investment | Simultaneous FAA Part 25 and EASA CS-25 qualification expands addressable market across Atlantic basin final assembly lines. |
| Performance-Based Contracting Transition | Cost-per-hole and cost-per-fastener models concentrate in French and Italian supplier parks with risk-sharing procurement architecture. |
| India Defense Localization Partnership | Hindustan Aeronautics Limited's greenfield composites buildout under BIS frameworks creates captive equipment demand. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's tier-1 fabrication clusters. The research combines structured interviews with equipment procurement directors, aerospace manufacturing engineers, composite process specialists, and aftermarket service heads with secondary validation through FAA airworthiness directives, EASA certification filings, MIIT industrial policy documents, and ISO 9100 quality framework updates. Bottom-up equipment shipment data triangulates against top-down OEM production rate announcements.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user category, and application with regional regulatory cluster overlays. CAGRs derive from equipment replacement cycle analysis, production rate ramp assumptions, and technology penetration curves for additive manufacturing and robotics automation. Forecast inputs incorporate titanium input price trajectories and EASA-FAA harmonization timeline assumptions.
Inputs from tier-1 supplier procurement teams and OEM program offices were available through the study window; gaps in tier-2 fabricator equipment utilization data introduce uncertainty bands around automation penetration forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Europe Rotor Blade Market