
 Europe Aerospace and Defense Market | 2026-2036
Europe Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerospace and Defense Market Foresight
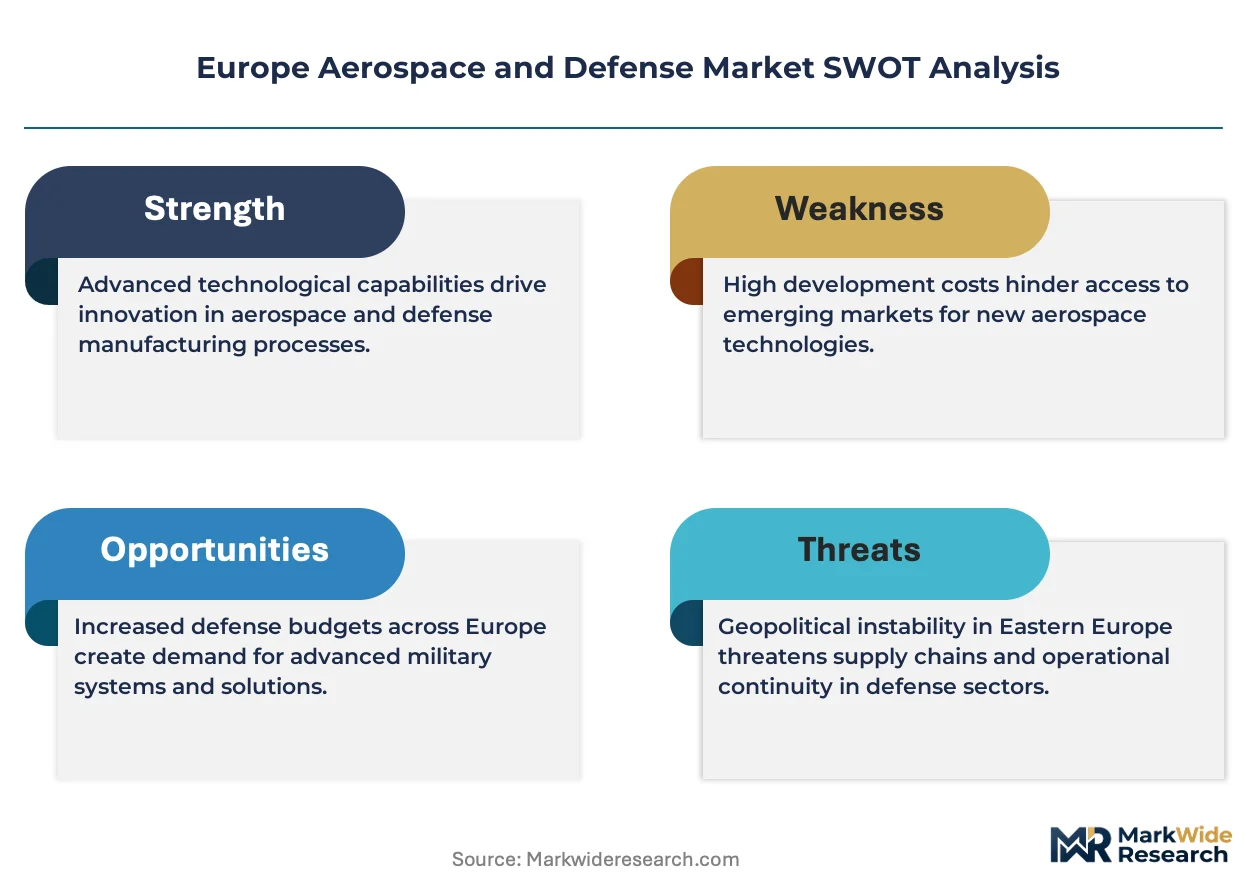
European defense industrial capacity is expanding across France, Germany, and Italy as governments accelerate procurement timelines. BAE Systems anchors British naval and electronic warfare programs through sustained investment in shipbuilding and intelligence systems. Airbus competes in military transport and space segments while leveraging its commercial aerospace supply chain for dual-use manufacturing. Safran dominates propulsion and landing systems, extending its position through specialized engine architectures for both civilian and combat aircraft.
The Europe Aerospace and Defense sector encompasses the design, manufacture, and sustainment of atmospheric and exo-atmospheric vehicles, platforms, and mission systems, typically operating across altitude regimes from sea level to geostationary orbit and requiring materials such as titanium aluminides, carbon fiber reinforced polymers, and nickel-based superalloys to satisfy strength-to-weight and thermal performance parameters. The primary purpose spans sovereign security projection, commercial air transport, satellite communications, and intelligence gathering. Commercial Aircraft remains the most mature revenue pool within Product Type segments, while Unmanned Aerial Vehicles represent the fastest-growing category as militaries prioritize reduced-risk reconnaissance and strike capabilities. Avionics within Technology segments commands premium margins due to software-defined architecture and cybersecurity certification requirements that limit supplier entry.
EMA, EASA, and the EU Green Deal collectively shape market access through emissions standards for aviation propulsion, defense procurement directives prioritizing European supply chains, and sustainability disclosure requirements affecting contractor eligibility. REACH chemicals regulation constrains material selection in composites and surface treatments, compelling reformulation of legacy manufacturing processes. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous targeting and flight control algorithms, as compliance architecture will determine which platforms achieve operational certification.
Market Dynamics
NATO's collective defense commitments are accelerating military aircraft procurement timelines across the continent, while the EU Green Deal's emissions standards simultaneously reshape propulsion system requirements for next-generation platforms.
Growth Catalysts
- REACH chemicals regulation:Material reformulation mandates are stimulating demand for advanced composites and surface treatments that reduce environmental impact while maintaining thermal performance parameters.
- France-Germany-UK defense spending:Concentrated procurement commitments in these three markets are pulling forward platform development cycles and sustainment contract awards.
- Software-defined avionics:Cybersecurity certification requirements are creating premium-margin opportunities for architectures that integrate flight control with electronic warfare systems.
Market Restraints
- Titanium aluminide supply concentration:Limited qualified foundry capacity for nickel-based superalloys and advanced ceramics constrains production scaling for combat engine hot sections.
- EMA emissions compliance costs:Certification overhead for sustainable aviation fuels and hybrid-electric propulsion architectures extends development timelines and capital requirements.
- Carbon fiber precursor volatility:Acrylonitrile price swings and PAN supply bottlenecks transmit directly to airframe manufacturing cost structures.
Strategic Opportunities
- Italy's underdeveloped UAV industrial base:Rome's lagging unmanned systems capability relative to France and Germany creates white space for platform integration partnerships and subsystem supply.
- EU AI Act autonomous targeting framework:Early compliance architecture for risk-classified flight control algorithms will determine which platforms achieve operational certification across member states.
- Satellite-to-aircraft laser communications:Convergence of optical terminal miniaturization with hardened space electronics opens new mission profiles for intelligence-gathering aircraft.
Industry Challenges
- Systems engineering talent scarcity:Deep expertise in model-based systems engineering for military certification remains concentrated at a handful of primes and specialized consultancies.
- Dual-use export control navigation:ITAR and EU dual-use regulation divergence complicates transatlantic supply chain configuration for components with civilian-military applicability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerospace and Defense Market |
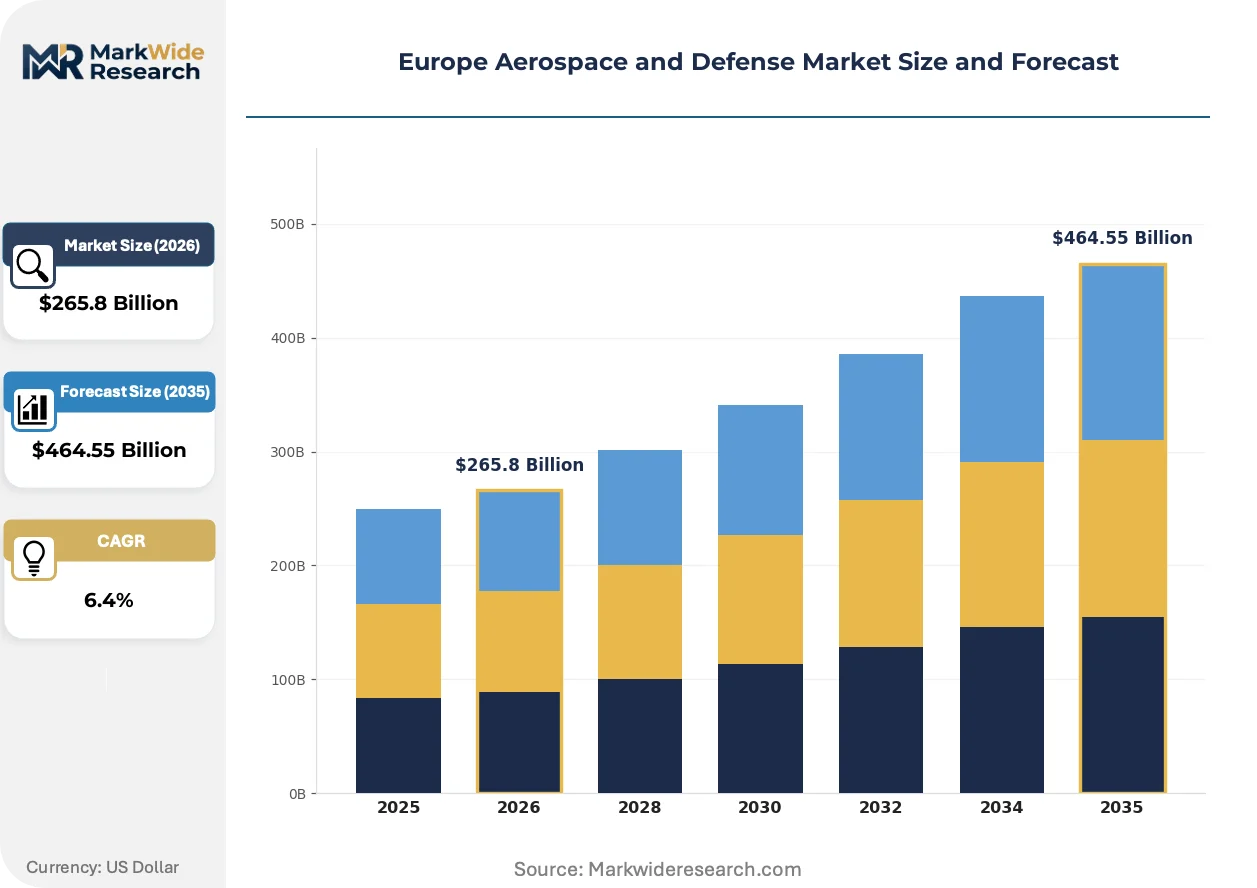
| Market Size in 2026 | $265.8 Billion |
| Market Size in 2035 | $464.55 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Aircraft, Military Aircraft, Spacecraft, Unmanned Aerial Vehicles Technology: Aerospace Composites, Avionics, Propulsion Systems, Navigation Systems End User: Government, Defense Contractors, Airlines, Space Agencies Service Type: Maintenance, Repair, and Overhaul, Training Services, Ground Support Equipment, Simulation Services |
| Companies Covered | BAE Systems, Airbus, Leonardo, Thales, Safran, Rheinmetall, Dassault Aviation, Saab, Fincantieri, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerospace and Defense Market Shifts & Advancements
Propulsion electrification and autonomous mission systems are compressing traditional development cycles while forcing reconvergence of commercial and military supply chains around shared material platforms.
Hybrid-electric distributed propulsion is unifying thermal management and power electronics architectures across commercial and combat aircraft programs. Safran and Rolls-Royce are accelerating test campaigns for megawatt-class generators integrated into turbofan nacelles. This convergence is unifying supplier qualification processes that previously separated civilian and military certification streams.
The EU AI Act's risk classification framework for autonomous systems is mandating formal verification protocols for flight control software that exceed traditional DO-178C requirements. Defense primes must now document algorithmic decision boundaries and failure modes for certification authorities. Combat aircraft and unmanned strike platforms face the steepest compliance ramps as member state regulators interpret high-risk system definitions.
Platform-as-a-service contracting is displacing traditional capital acquisition for military transport and training aircraft. The UK Royal Air Force and French Armée de l'Air are piloting availability-based payment structures where contractors retain asset ownership and deliver flight hours. Germany remains more resistant to this shift due to Bundestag budget execution rules.
Europe Aerospace and Defense Market Segmentation
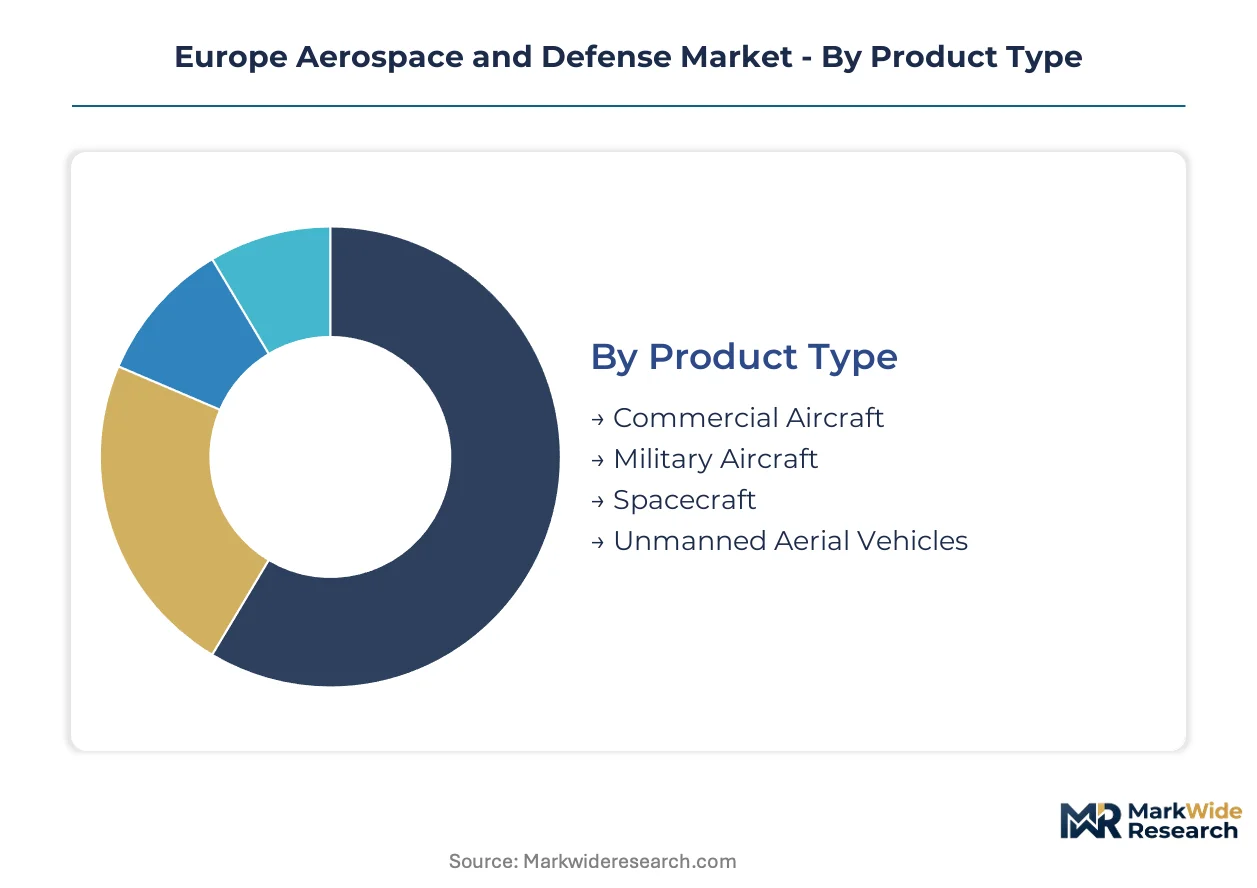
Segmentation in European aerospace and defense reveals how certification burdens concentrate value capture. EASA type certificates, NATO STANAG compliance, and EU AI Act risk classifications create tiered barrier structures that reshape competitive dynamics across product categories.
Product Type:
EASA type certification and NATO STANAG interoperability requirements impose divergent compliance architectures across vehicle categories, with manned platforms facing substantially longer validation timelines than unmanned systems.
- Commercial Aircraft:Twin-aisle and single-aisle platforms require EASA CS-25 airworthiness certification with EU Green Deal emissions compliance for entry into service. Demand concentrates at Airbus final assembly lines in Toulouse and Hamburg where production rates determine regional supplier contract volumes.
- Military Aircraft:Combat and transport platforms must satisfy both national military airworthiness codes and NATO STANAG interoperability standards. France, Germany, and the United Kingdom are pulling forward procurement timelines through multilateral programs like FCAS and Tempest, accelerating subsystem development cycles.
- Spacecraft:Launch vehicles and orbital platforms face ESA qualification protocols combined with national space agency mission assurance requirements.
- Unmanned Aerial Vehicles:Tactical and strategic drones operate under lighter EASA SORA frameworks for civilian variants and national military exemptions for combat systems.
Leading the category by volume: Commercial Aircraft. Growing fastest: Unmanned Aerial Vehicles.
Technology:
Material and system technologies stratify by margin structure, with software-defined architectures commanding premium pricing due to cybersecurity certification requirements that limit qualified supplier pools.
- Aerospace Composites:Carbon fiber reinforced polymers and titanium aluminides deliver strength-to-weight ratios essential for fuel efficiency targets. REACH chemicals regulation is forcing reformulation of resin systems and surface treatments, compelling foundries in Germany and France to qualify alternative chemistries.
- Avionics:Software-defined flight control and electronic warfare systems integrate DO-178C safety certification with EU AI Act algorithmic transparency mandates. Cybersecurity certification from EASA and national military authorities creates multi-year supplier qualification barriers that protect incumbent positions.
- Propulsion Systems:Turbofan, turboprop, and emerging hybrid-electric architectures must satisfy EASA CS-E engine certification and EU Green Deal emissions standards.
- Navigation Systems:GNSS-augmented and inertial reference platforms require Galileo compatibility and military-grade anti-jam specifications.
Capturing the highest margins: Avionics. Facing the steepest compliance ramps: Propulsion Systems.
End User:
Contracting structures diverge sharply between sovereign procurement and commercial service provision, with availability-based payment models displacing capital acquisition in select military segments.
- Government:National defense ministries and NATO procurement agencies execute long-cycle competitive tenders with offset requirements favoring domestic industrial participation. French DGA, German BAAINBw, and UK Defence Equipment and Support anchor demand through platform development and sustainment contracts.
- Defense Contractors:Prime systems integrators and tier-1 suppliers purchase subsystems and components under flow-down contractual regimes. BAE Systems, Airbus Defence and Space, and Leonardo aggregate demand across multiple national programs, consolidating supplier bases.
- Airlines:Network carriers and low-cost operators drive commercial aircraft specification through fleet renewal decisions.
- Space Agencies:ESA and national space organizations procure launch services and satellite platforms through geographic return mechanisms.
Contract volume concentrates with: Government. Platform-as-a-service adoption advancing among: Defense Contractors.
Service Type:
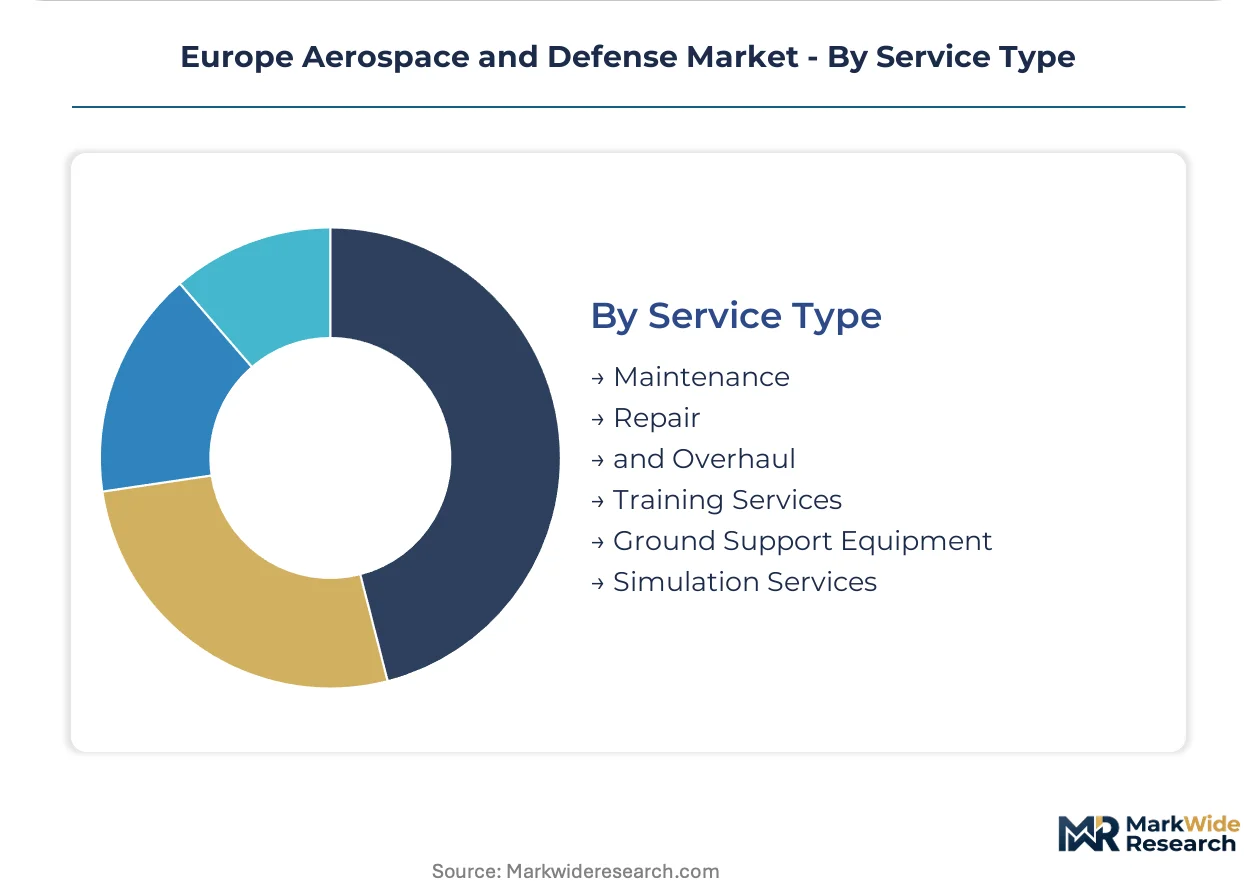
Service delivery models are compressing toward performance-based structures where contractors assume asset availability risk rather than executing discrete maintenance events.
- Maintenance, Repair, and Overhaul:Airframe, engine, and component overhaul services must maintain EASA Part-145 approval for commercial operations and national military technical authority accreditation. Safran and Rolls-Royce are expanding power-by-the-hour contracts across European operator fleets, transferring utilization risk to OEMs.
- Training Services:Pilot and maintainer instruction requires EASA Part-147 certification for civilian programs and national military training authority oversight. Synthetic training device qualification under EASA CS-FSTD is extending simulation fidelity requirements.
- Ground Support Equipment:Aircraft handling and servicing equipment must satisfy CE marking and military environmental hardness specifications.
- Simulation Services:Distributed mission training and synthetic environment generation face emerging EU AI Act scrutiny for autonomous adversary algorithms.
Revenue maturity sits with: Maintenance, Repair, and Overhaul. Contracting innovation centers on: Training Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium aluminide foundries in France and nickel-based superalloy suppliers in Germany anchor the continent's aerospace material base. These feedstock localities concentrate platform development cycles across NATO procurement corridors.
France
Dassault Aviation and Safran drive combat aircraft and propulsion demand through the Rafale program and FCAS development. The DGA enforces national military airworthiness codes that prioritize domestic industrial participation. Toulouse and Bordeaux clusters concentrate final assembly and subsystem integration for both military and commercial platforms.
Germany
Rheinmetall and Airbus Defence and Space anchor land systems and military transport procurement under accelerated Bundestag spending commitments. The BAAINBw executes competitive tenders with offset requirements favoring German supplier bases. Munich and Hamburg industrial zones concentrate avionics development and final assembly operations.
United Kingdom
BAE Systems anchors naval and combat aircraft programs through Tempest development and submarine construction. Defence Equipment and Support mandates UK industrial content thresholds in platform awards. Lancashire and Bristol clusters concentrate electronic warfare systems and shipbuilding capacity.
Italy
Leonardo leads rotorcraft and naval systems procurement with Fincantieri anchoring surface combatant construction. Rome's lagging UAV capability relative to France and Germany creates subsystem partnership opportunities. Turin and Genoa industrial zones concentrate aerostructures and marine engineering.
Sweden
Saab drives Gripen fighter sustainment and sensor systems development for Nordic defense cooperation. The Swedish Defence Materiel Administration prioritizes interoperability with NATO STANAG standards. Linköping and Stockholm clusters concentrate aerospace electronics and signature management technologies.
Europe Aerospace and Defense Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue unmanned systems and satellite services through specialized subcontracts. The vendor base stratifies across prime integrators, tier-1 subsystem suppliers, and national champions with protected domestic markets. Two archetypes dominate: state-linked defense conglomerates with captive procurement pipelines, and commercial aerospace OEMs leveraging dual-use manufacturing flexibility. Competitive moves center on multilateral program partnerships and supply chain consolidation around shared material platforms.
Among British and French prime contractors, BAE Systems and Dassault Aviation exemplify the state-linked archetype with entrenched domestic positions. Airbus occupies a position spanning commercial and military segments through unified manufacturing architectures. Safran represents the tier-1 specialist model, anchoring propulsion supply across multiple national programs without final platform integration exposure.
| Leading Market Players |
|---|
| BAE Systems |
| Airbus |
| Leonardo |
| Thales |
| Safran |
| Rheinmetall |
| Dassault Aviation |
| Saab |
| Fincantieri |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions mandates are compressing procurement timelines for hybrid-electric propulsion architectures, forcing foundries in France and Germany to qualify alternative chemistries and pass reformulation costs through to platform integrators.
Pricing Analysis
Power-by-the-hour contracts bundle engine overhaul with flight-hour guarantees, unbundling traditional capital acquisition into availability-based payment streams. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EASA Part-145 approved services commanding substantial premiums over uncertified maintenance. Cost compression in standard-tier subsystem supply is intensifying because Bundestag budget execution rules delay German program awards relative to French and British procurement cycles. Defense contractors exhibit the highest price sensitivity due to flow-down contractual regimes, while government buyers prioritize industrial participation thresholds over unit cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for carbon fiber reinforced polymers and nickel-based superalloys, bypassing distributor markups for qualified foundry capacity. Supply concentrates in France for titanium aluminide hot-section components, Germany for precision-machined superalloy castings, and the United Kingdom for electronic warfare subsystems. Raw material dependencies rest on acrylonitrile for PAN precursor synthesis, cobalt for superalloy creep resistance, and rare earth elements for avionics magnetics. Single-source vulnerability in qualified foundry capacity for combat engine hot sections exposes production scaling to queue delays. Distribution runs through prime systems integrators with captive supplier qualification processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe aerospace and defense sector is consolidating around backward integration into critical material supply, with primes acquiring foundry capacity and resin formulation capabilities to secure qualified feedstock access.
For Market Incumbents: To counter emerging entrants in unmanned aerial vehicle subsystems, BAE Systems and Airbus Defence and Space should acquire Italian aerostructure suppliers to preempt platform integration partnerships in Rome's lagging UAV industrial base. Certification investment in EU AI Act compliance architecture for autonomous targeting algorithms will determine which platforms achieve operational certification across member states, locking out late-moving competitors. For New Entrants and Emerging Players: REACH chemicals regulation in Europe opens a window for specialized composite suppliers offering reformulated resin systems that satisfy thermal performance parameters without legacy chemistry disqualification. Italy's underdeveloped UAV capability relative to France and Germany represents the most penetrable geography for subsystem partnerships, with subsystem supply contracts to Leonardo's rotorcraft programs offering a credible go-to-market angle for navigation and sensor package providers. For Investors and Strategic Acquirers: The window for entry favors tier-1 specialists with captive positions in propulsion or avionics rather than final platform integrators exposed to program cancellation risk. Long-term viability rests on supplier qualification barriers that protect incumbent margins through multi-year certification timelines. Watch for Bundestag acceleration of FCAS funding commitments as the inflection indicator for German procurement normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Secures qualified titanium aluminide supply for Safran and Rolls-Royce engine programs. |
| EU AI Act Compliance Certification | Determines operational authorization for Dassault and BAE autonomous targeting architectures. |
| Platform-as-a-Service Contracting | Transforms RAF and French Armée de l'Air capital acquisition into availability-based revenue streams. |
| Italian UAV Subsystem Partnership | Exploits Rome's capability gap relative to Paris and Berlin for Leonardo platform integration. |
| REACH-Compliant Material Reformulation | Enables German and French foundries to maintain EASA certification under EU Green Deal standards. |
Research Methodology
Document review covered EASA type certificate databases, NATO STANAG interoperability specifications, and EU procurement directive filings, complemented by interviews with program managers at French DGA, German BAAINBw, and UK Defence Equipment and Support, plus secondary validation through ESA mission assurance protocols and REACH chemical substance registrations. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the European defense spending envelope.
Revenue and volume outputs across the analysis window reflect analytical frameworks incorporating product type segmentation by certification burden, technology tier by margin structure, and end-user contracting modality by payment structure. CAGRs were derived from regression analysis of historical procurement cycles against NATO collective defense commitment trajectories. Industry-specific forecast inputs included FCAS and Tempest program development timelines and EU Green Deal emissions compliance phase-in schedules.
Caveats apply where Bundestag budget execution delays, REACH chemical substance reclassification, or NATO STANAG revision cycles could materially shift the outlook for platform development and sustainment contract awards. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market