
 Japan Aircraft Windshield Wiper and Washer System Market | 2026-2036
Japan Aircraft Windshield Wiper and Washer System Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aircraft Windshield Wiper and Washer System Market Insights
Modular assembly configurations is broadening buyer choice across Japan's aircraft windshield wiper and washer system market. Mitsubishi Heavy Industries leverages its integrated aerospace manufacturing footprint to bundle wiper systems with broader airframe contracts. JAMCO Corporation anchors aftermarket demand through its maintenance, repair and overhaul network serving Japan Airlines and ANA fleets. Safran SA competes on technology leadership in electromechanical wiper actuation for next-generation narrowbody platforms.
Aircraft windshield wiper and washer systems comprise motor-driven blade assemblies, fluid distribution manifolds, and control interfaces engineered to maintain pilot visibility during precipitation and runway contamination events, typically operating at sweep rates exceeding 45 cycles per minute under icing conditions. Electric wiper technology dominates new installations given weight advantages and reduced pneumatic infrastructure demands on modern flight decks. Commercial aviation application segments command the largest installed base, though helicopter configurations present higher-margin opportunities due to specialized blade geometries and NVG-compatible coatings.
Japan Civil Aviation Bureau certification standards, aligned with MLIT airworthiness protocols, mandate de-icing fluid compatibility and electromagnetic interference shielding for all flight-critical visibility equipment. METI industrial policy on aerospace supply chain resilience incentivizes domestic sourcing of wiper system components, reinforcing local manufacturing obligations for foreign OEMs. Stakeholders must monitor evolving JIS standards on environmental fluid formulations and assess backward integration into washer fluid chemistry to preserve margin pools as regulatory thresholds tighten.
Market Dynamics
MLIT airworthiness directives on visibility systems are tightening certification thresholds, forcing suppliers to requalify legacy wiper assemblies and accelerating replacement cycles across Japan's commercial fleet.
Growth Catalysts
- Domestic Fleet Expansion:Japan Airlines and ANA are adding narrowbody aircraft to meet post-recovery route demand, directly expanding the installed base for integrated wiper-washer systems.
- METI Supply Chain Resilience Policy:Industrial policy incentives for domestic aerospace component sourcing are reinforcing local manufacturing obligations for foreign OEMs seeking market access.
- Electromechanical Actuation:Electric wiper technology is displacing pneumatic systems in new installations, reducing weight and infrastructure demands on modern flight decks.
Market Restraints
- Specialized Fluid Chemistry:De-icing fluid compatibility requirements under JCAB certification limit supplier flexibility and raise formulation costs for washer system providers.
- Kanto Corridor Concentration:Maintenance hub clustering around Tokyo-Narita and Haneda creates geographic supply vulnerability and regional price anchoring.
- Helicopter NVG Coating Complexity:Night vision goggle-compatible blade coatings require specialized application processes that constrain production scalability.
Strategic Opportunities
- Kansai Maintenance Network:Osaka-Kobe aerospace clusters present underdeveloped aftermarket capacity for wiper system MRO services outside the Kanto corridor.
- JIS Environmental Fluid Standards:Evolving standards on biodegradable washer formulations create first-mover advantage for suppliers with backward integration into chemistry.
- Sensor-Wiper Convergence:Integration of precipitation detection sensors with automated wiper control interfaces opens premium positioning on next-generation regional jets.
Industry Challenges
- Electromagnetic Interference Shielding Certification:JCAB electromagnetic compatibility testing for flight-critical visibility equipment extends qualification timelines and raises engineering overhead.
- Legacy Fleet Retrofit Complexity:Older Boeing 737 and Airbus A320 variants in domestic service require custom bracket modifications for electromechanical wiper upgrades, fragmenting inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aircraft Windshield Wiper and Washer System Market |
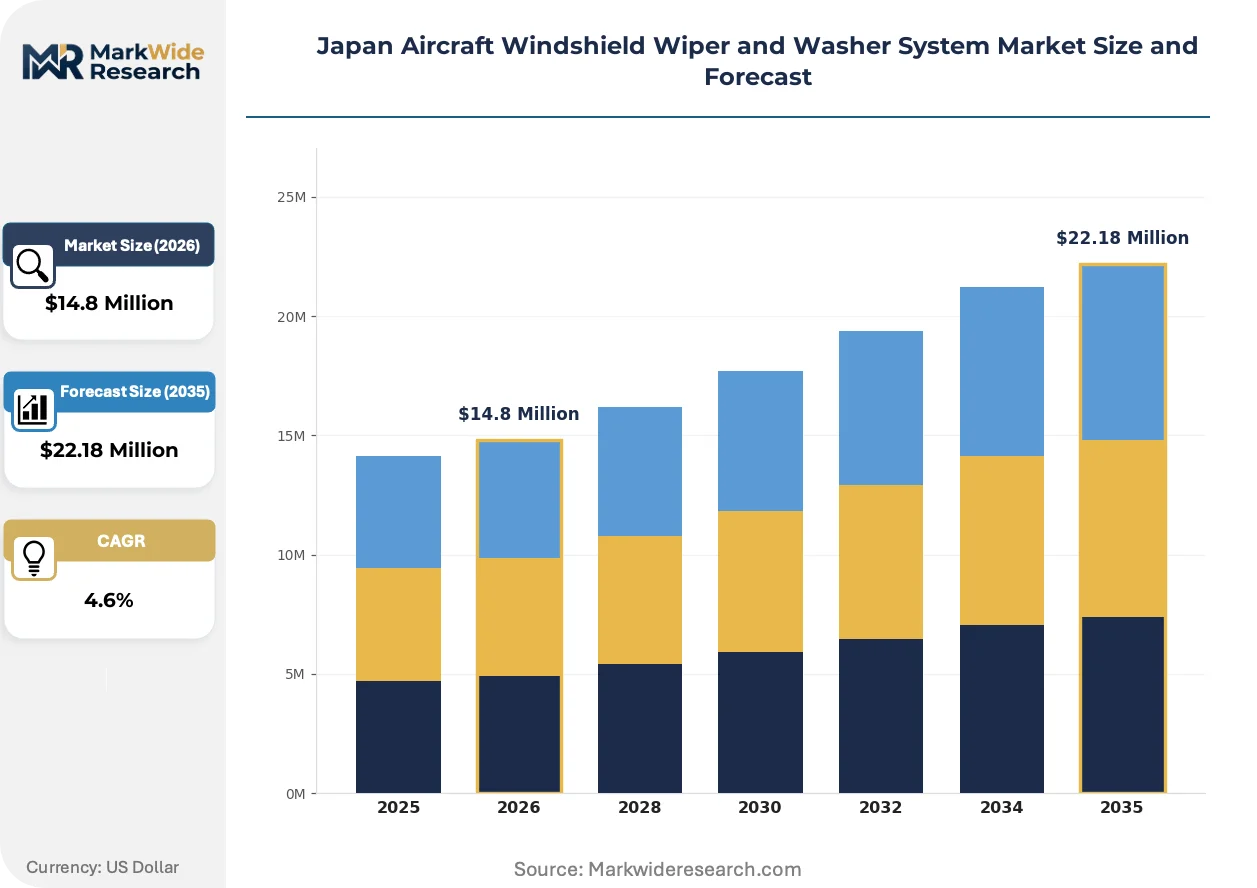
| Market Size in 2026 | $14.8 Million |
| Market Size in 2035 | $22.18 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipers, Washers, Controls, Assemblies Application: Commercial Aviation, Military Aviation, Helicopters, Drones Technology: Electric, Pneumatic, Hydraulic, Hybrid End User: OEMs, Aftermarket Providers, Maintenance Facilities, Airlines |
| Companies Covered | Mitsubishi Heavy Industries, JAMCO Corporation, Safran SA, Collins Aerospace, Liebherr-Aerospace, Eaton Corporation, GKN Aerospace, RTX Corp., ITT Aerospace Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aircraft Windshield Wiper and Washer System Market Trends and Innovations
Active precipitation management on Japan's flight decks is shifting from mechanical reliability toward intelligent automation, with sensor integration and predictive maintenance protocols redefining supplier value propositions.
Carbon fiber reinforced polymer wiper arms are absorbing structural loads previously managed by aluminum extrusions, cutting per-assembly weight by nearly one-third. Japan Airlines engineering teams are specifying CFRP for new A350 deliveries, and this material transition is compressing the addressable market for traditional metal-forming subcontractors.
MLIT alignment with ICAO visibility equipment standards is mandating enhanced de-icing fluid dispersal uniformity across all certified replacement components. This regulatory convergence is disqualifying legacy manifold designs and forcing domestic suppliers to retool fluid distribution architectures before the compliance deadline.
Airlines are unbundling wiper system maintenance from airframe heavy check contracts, creating direct procurement relationships with specialized component OEMs. This channel disintermediation is most pronounced at ANA's Haneda technical center, where line-replaceable unit sourcing now bypasses integrated MRO providers for faster turnaround times.
Japan Aircraft Windshield Wiper and Washer System Market Segmentation
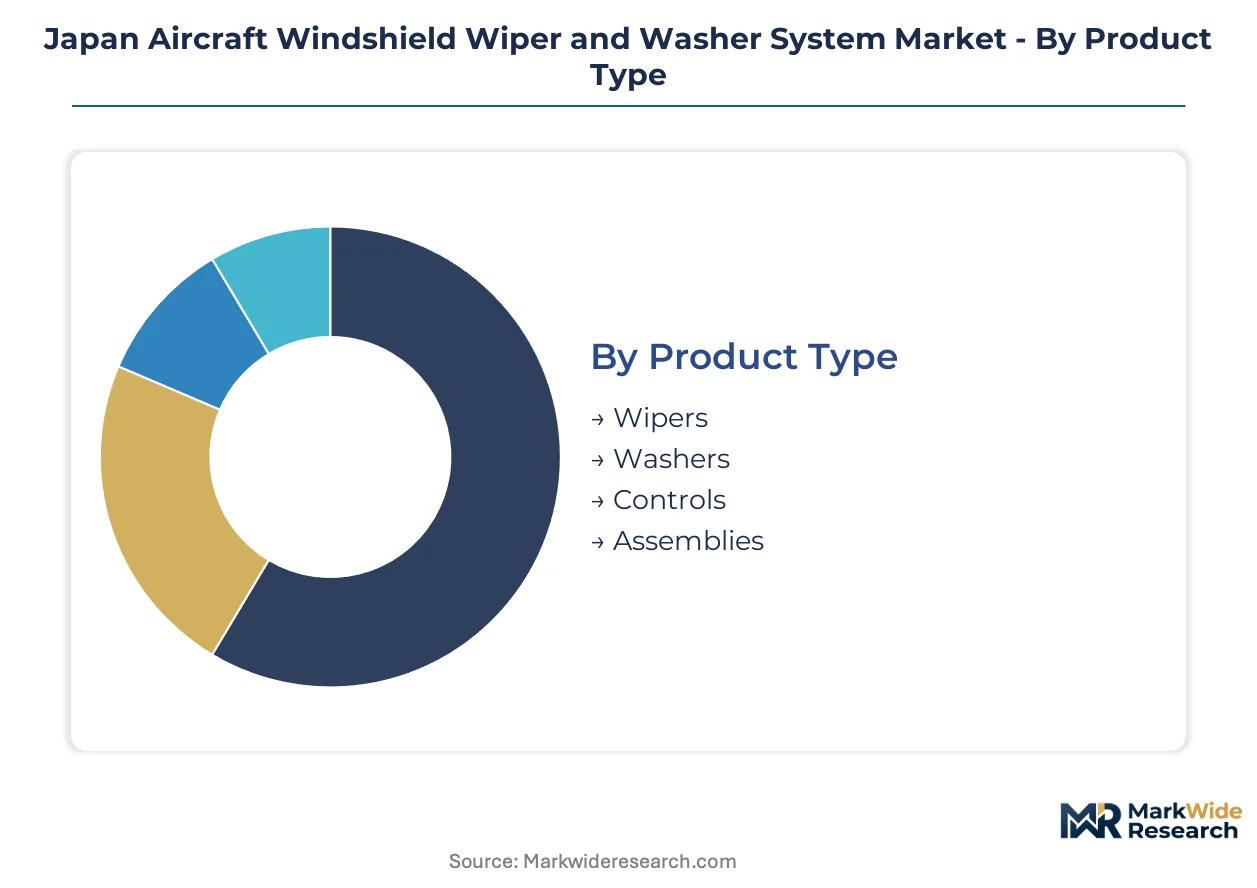
Windshield wiper and washer system procurement patterns in Japan diverge sharply across product architectures, operational environments, and buyer types. Each segmentation axis reveals distinct margin pools and qualification barriers that shape supplier strategy.
Product Type:
Standardization pressure from JCAB certification protocols creates tiered sourcing strategies across this category, with integrated assemblies commanding premium positioning versus component-level procurement.
- Wipers:Motor-driven blade assemblies incorporating CFRP structural arms and NVG-compatible coatings for rotary-wing applications. Demand concentrates at JAMCO Corporation's Narita maintenance hub, where ANA and Japan Airlines specify electromechanical actuation for narrowbody retrofits.
- Washers:Fluid distribution manifolds with de-icing compatibility and electromagnetic interference shielding per MLIT airworthiness directives. Procurement clusters around Tokyo-Haneda technical centers as airlines unbundle maintenance from heavy check contracts.
- Controls:Pilot interface modules governing sweep rate and precipitation response timing.
- Assemblies:Integrated wiper-washer systems bundled under single part numbers for line-replaceable unit efficiency.
Leading the category by volume: Wiper blade assemblies. Expanding most quickly: Integrated assemblies as procurement shifts toward bundled LRUs.
Application:
Operational tempo and regulatory exposure vary dramatically across flight regimes, with commercial fixed-wing operations driving volume and rotary-wing segments offering margin differentiation.
- Commercial Aviation:Narrowbody and widebody platforms operating under JCAB Part 25 certification with visibility equipment mandates aligned to ICAO standards. Fleet expansion at Japan Airlines and ANA sustains replacement demand through Kanto corridor maintenance hubs.
- Military Aviation:Japan Air Self-Defense Force transport and patrol aircraft with specialized electromagnetic compatibility requirements. Procurement flows through Mitsubishi Heavy Industries integrated manufacturing contracts with constrained aftermarket access.
- Helicopters:Specialized blade geometries with night vision goggle-compatible coatings for law enforcement and emergency medical services.
- Drones:Miniaturized wiper systems for beyond-visual-line-ofsight platforms with emerging regulatory frameworks.
Commercial Aviation dominates procurement volume. Helicopters deliver steepest margin expansion due to coating complexity and low supplier density.
Technology:
Weight reduction imperatives on modern flight decks are accelerating displacement of legacy pneumatic infrastructure, though certification timelines fragment adoption curves.
- Electric:Brushless DC motor actuation with integrated control electronics and reduced wiring harness weight. Mitsubishi Heavy Industries specifies electromechanical systems for new A350 deliveries, compressing addressable market for pneumatic subsystem suppliers.
- Pneumatic:Legacy compressed-air drive systems requiring dedicated infrastructure on older Boeing 737 and Airbus A320 variants. Retrofit complexity fragments inventory requirements across Japan's domestic fleet.
- Hydraulic:High-torque actuation for heavy transport platforms with extreme icing exposure.
- Hybrid:Dual-mode systems switching between electric and pneumatic sources for redundancy-critical applications.
Electric systems capture the majority of new installations. Hybrid configurations are gaining share fastest in military procurement specifications.
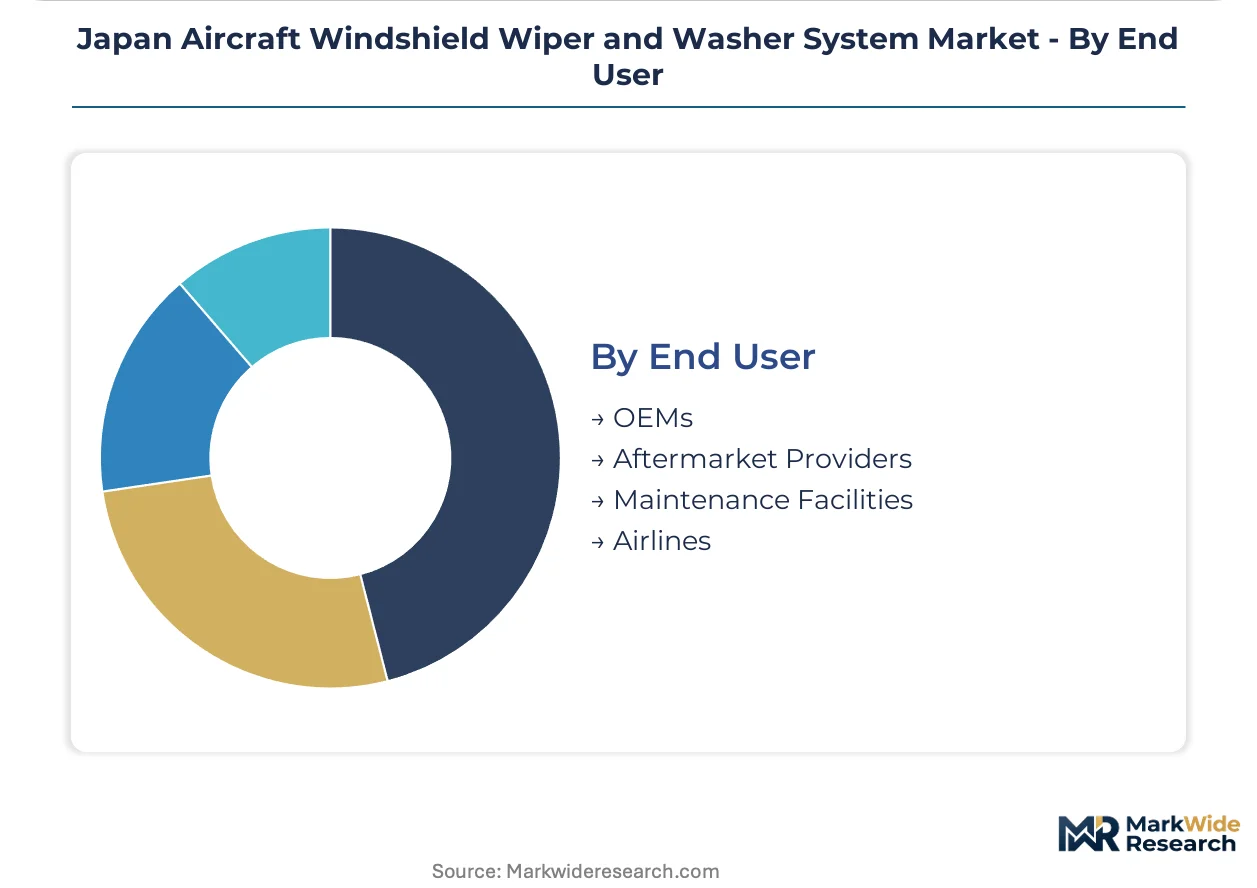
End User:
Channel structure is restructuring as airlines bypass integrated MRO providers for direct component relationships, fragmenting historical procurement hierarchies.
- OEMs:Mitsubishi Heavy Industries and tier-one airframe integrators sourcing wiper systems as bundled airframe contracts with multi-year qualification cycles.
- Aftermarket Providers:JAMCO Corporation and specialized distributors serving line-replaceable unit demand outside manufacturer service networks.
- Maintenance Facilities:Haneda and Narita technical centers with unbundled procurement authority for faster turnaround times.
- Airlines:Japan Airlines and ANA engineering teams specifying direct component sourcing for wiper system lifecycle management.
Aftermarket Providers handle the greatest transaction volume. Airlines are climbing the fastest as direct procurement authority expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's aircraft windshield wiper and washer system production concentrates in the Kanto industrial corridor while consumption spreads across domestic maintenance hubs and airline engineering centers. The supply-demand geography reflects aerospace manufacturing legacy and fleet distribution patterns.
Kanto/Tokyo
Tokyo-Narita and Haneda maintenance hubs anchor aftermarket demand for integrated wiper-washer assemblies as Japan Airlines and ANA expand direct procurement authority. MLIT airworthiness directives on visibility systems flow through the Civil Aviation Bureau headquarters in Kasumigaseki. Mitsubishi Heavy Industries leverages its Yokohama aerospace complex to bundle wiper systems with airframe contracts for domestic carriers.
Kansai/Osaka
Osaka-Kobe aerospace clusters present underdeveloped aftermarket capacity relative to Kanto, creating strategic whitespace for wiper system MRO services. METI supply chain resilience policies incentivize component sourcing diversification beyond the Tokyo corridor. Kansai International Airport technical centers are expanding line-replaceable unit handling capabilities to reduce turnaround dependency on eastern hubs.
Chubu/Nagoya
Central Japan International Airport maintenance operations support Boeing 787 and Airbus A350 fleets with specialized electromechanical wiper retrofit programs. JIS standards on environmental fluid formulations are drafted through Nagoya-based industrial standards committees. Toyota-affiliated suppliers in Aichi Prefecture are exploring carbon fiber reinforced polymer applications for next-generation wiper arm production.
Kyushu
Fukuoka and Kitakyushu aerospace subcontracting networks feed component assemblies to tier-one integrators in western Japan. Japan Air Self-Defense Force bases in Kagoshima and Miyazaki generate military aviation demand with specialized electromagnetic compatibility requirements. Local METI regional bureaus administer aerospace supply chain grants targeting wiper system component localization.
Hokkaido
New Chitose Airport cold-weather operations drive demand for heavy-duty de-icing fluid distribution systems and extended-sweep wiper configurations. Regional airline maintenance facilities handle turboprop visibility equipment with distinct procurement patterns from jet operators. Sapporo-based engineering services support helicopter operators requiring NVG-compatible blade coatings for law enforcement and emergency medical missions.
Japan Aircraft Windshield Wiper and Washer System Market Competitive Landscape
The competitive structure tilts toward integrated aerospace conglomerates with bundled airframe contracting authority. Domestic fabrication specialists and foreign technology leaders occupy distinct tier positions with limited direct overlap. Three archetypes dominate: multi-divisional heavy industry groups with captive aerospace verticals, dedicated aircraft component OEMs with MRO network anchoring, and European-American transnational suppliers with electromechanical technology portfolios. Consolidation pressure operates through airframe manufacturer qualification requirements rather than horizontal merger activity.
Among Japan-based industrial groups, Mitsubishi Heavy Industries occupies a position exemplifying the integrated conglomerate archetype with bundled system contracting. JAMCO Corporation represents the specialized component OEM model with aftermarket network density. Safran SA anchors the foreign technology leader tier with electromechanical actuation positioning. These three patterns illustrate how supplier structure maps to procurement channel segmentation across OEM direct sales, airline technical center relationships, and maintenance facility distribution.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| JAMCO Corporation |
| Safran SA |
| Collins Aerospace |
| Liebherr-Aerospace |
| Eaton Corporation |
| GKN Aerospace |
| RTX Corp. |
| ITT Aerospace Controls |
| Others |
Pricing and Supply Chain Analysis
CFRP fabrication specialists concentrated in Aichi Prefecture feed into three distinct pricing tiers, with labor-cost differentials between Nagoya engineering clusters and Tokyo technical centers widening spreads between premium electromechanical assemblies and economy-grade pneumatic retrofits.
Pricing Analysis
Margin tightening in economy-grade pneumatic retrofits traces to JCAB requalification burdens and fragmented inventory requirements across aging Boeing 737 and Airbus A320 fleets. Three-tier pricing structure across premium electromechanical, standard integrated assemblies, and economy pneumatic replacements separates OEM bundled contracts from airline direct procurement and aftermarket component sourcing. Cost-down pressure on standard integrated assemblies accelerates because airlines are unbundling wiper maintenance from heavy check contracts. Commercial aviation fleet operators exhibit highest price sensitivity due to volume procurement authority, while helicopter operators with NVG-compatible coating requirements show lowest sensitivity given supplier scarcity.
Supply Chain Analysis
Regional distribution centers anchored in Yokohama and Osaka-Kobe aerospace clusters operate hub-and-spoke patterns feeding Kanto and Kansai maintenance hubs. Manufacturing concentration rests on Japan, with carbon fiber reinforced polymer inputs drawn from domestic Toyota-affiliated suppliers and electromechanical actuation components sourced from French and American transnational technology leaders. Single-source vulnerability concentrates in specialized NVG-compatible coating application processes with limited qualified subcontractors. Distribution runs through line-replaceable unit channels direct to airline technical centers, bypassing traditional integrated MRO hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's aircraft windshield wiper and washer system market sits in a technology-transition phase as electric electromechanical actuation displaces legacy pneumatic infrastructure across new narrowbody deliveries.
For Market Incumbents: Anchor aftermarket network density through JAMCO Corporation-style MRO hub expansion in underdeveloped Kansai corridors, while accelerating CFRP wiper arm qualification to defend against Toyota-affiliated suppliers entering upstream component production. Certification investment in JCAB electromagnetic compatibility testing represents the critical defensive lever against foreign technology leaders. For New Entrants and Emerging Players: Sensor-wiper convergence technology offers a technology-first wedge into premium regional jet retrofit programs, with Kansai International Airport technical centers presenting the most penetrable geography outside Kanto corridor saturation. Direct airline procurement relationships at ANA and Japan Airlines engineering teams provide the optimal go-to-market angle bypassing incumbent MRO gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized component OEMs possessing backward integration into environmental fluid chemistry given evolving JIS biodegradable formulation standards. Long-term viability over the coming decade hinges on regulatory compliance positioning rather than volume scale. The signal to watch is MLIT alignment with ICAO visibility equipment standards accelerating replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Washer Fluid Chemistry | JIS environmental standards create margin preservation for suppliers with captive formulation capabilities. |
| CFRP Wiper Arm Production Scale-Up | Aichi Prefecture manufacturing clusters enable weight reduction compliance for Mitsubishi Heavy Industries A350 contracts. |
| Kansai MRO Hub Establishment | Osaka-Kobe aerospace clusters reduce geographic supply vulnerability concentrated in Tokyo-Narita corridor. |
| Sensor-Wiper Control Interface Development | Precipitation detection integration opens premium positioning on next-generation regional jet platforms. |
| JCAB Electromagnetic Compatibility Certification Investment | MLIT airworthiness directive compliance accelerates qualification timelines for flight-critical visibility equipment. |
Research Methodology
Independent corroboration across JCAB certification databases, METI supply chain resilience policy filings, and airline engineering procurement records underwrites the qualitative findings. Primary interviews with MRO facility directors, airline fleet engineering managers, and tier-one aerospace procurement officers combined with secondary validation through MLIT airworthiness directive archives, JIS standards committee documentation, and customs component trade data. Bottom-up triangulation across maintenance hub transaction volumes and top-down reconciliation against fleet expansion schedules anchored the market sizing framework.
Comparable-period anchoring referenced historical replacement cycle patterns through prior regulatory transition phases across the projection horizon. Segmentation modeling spanned product architecture, application flight regime, actuation technology type, and procurement channel structure. CAGRs derived from installed base expansion trajectories and requalification velocity assumptions, with electromechanical adoption curves and CFRP material transition timelines serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced airframe manufacturer design changes, abrupt JCAB regulatory acceleration, and geopolitical disruption to carbon fiber supply chains. Forecasts reflect documented assumptions on fleet retirement schedules and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Light and Very Light Jets Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aircraft Fairings Market
Aircraft
Airplane Brackets Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Australia Aviation Market
Aircraft
Airplane Ailerons Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Supersonic Jet Market
Aircraft
Global Helicopter Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
North America Military Helicopters Market