
 Composite Flap Track Fairing Systems for Drag Reduction Market | 2026-2036
Composite Flap Track Fairing Systems for Drag Reduction Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Flap Track Fairing Systems for Drag Reduction Market Insights
Aerospace composites engineering talent scarcity is reorganizing supplier hierarchies across the fairing systems value chain. Spirit AeroSystems leverages its Wichita manufacturing footprint to sustain high-volume autoclave capacity for narrowbody programs. FACC AG differentiates through Austrian-based R&D in automated fiber placement, competing for European retrofit contracts. The NORDAM Group anchors aftermarket revenue streams through Tulsa-based MRO operations that control regional distribution channels.
Composite flap track fairing systems enclose the exposed mechanical linkage between wing trailing-edge flaps and their actuators, typically fabricated from carbon fiber-epoxy laminates with thermoset matrices cured under controlled temperature-pressure cycles to achieve specific stiffness-to-weight ratios and aerodynamic surface tolerances. These assemblies reduce parasite drag and interference drag at critical high-lift interfaces, directly improving aircraft fuel burn performance during climb and cruise phases. Carbon fiber formulations dominate commercial aircraft applications where specific strength requirements justify material premiums, while glass fiber segments occupy military trainer and unmanned aerial vehicle platforms where cost sensitivity outweighs marginal weight savings. Autoclave curing technology leads in structural certification acceptance, though resin transfer molding segments are expanding fastest among second-tier suppliers seeking capital-efficient entry into retrofit markets.
FAA airworthiness directives and EPA aircraft emissions standards shape U.S. product qualification pathways, while EASA certification specifications and the EU Green Deal's sustainable aviation fuel mandates influence European procurement specifications. Compliance with ISO 9001 and AS9100 quality frameworks determines supplier eligibility for OEM tier-1 contracts across jurisdictions. Stakeholders must monitor evolving ICAO carbon offset requirements and assess whether in-house prepreg layup capabilities or outsourced filament winding partnerships better align with pending military qualification changes.
Market Dynamics
FAA emissions mandates and EU F-Gas Regulation are compressing qualification timelines for composite fairing systems, forcing suppliers to accelerate autoclave throughput or risk losing OEM tier-1 status to competitors with certified resin transfer molding capacity.
Growth Catalysts
- Retrofit Program Expansion:Commercial aircraft operators in the United States are upgrading narrowbody fleets with composite fairing systems to meet tightening EPA aircraft emissions standards and reduce fuel burn during high-lift phases.
- REACH Compliance Pressure:European MRO hubs are sourcing thermoset matrix alternatives with lower volatile organic compound profiles to satisfy ECHA substance restrictions and avoid supply chain disqualification.
- Automated Fiber Placement:Austrian-based R&D centers are deploying robotic layup systems that cut cycle times for carbon fiber-epoxy laminates, enabling second-tier suppliers to bid competitively on European retrofit contracts.
Market Restraints
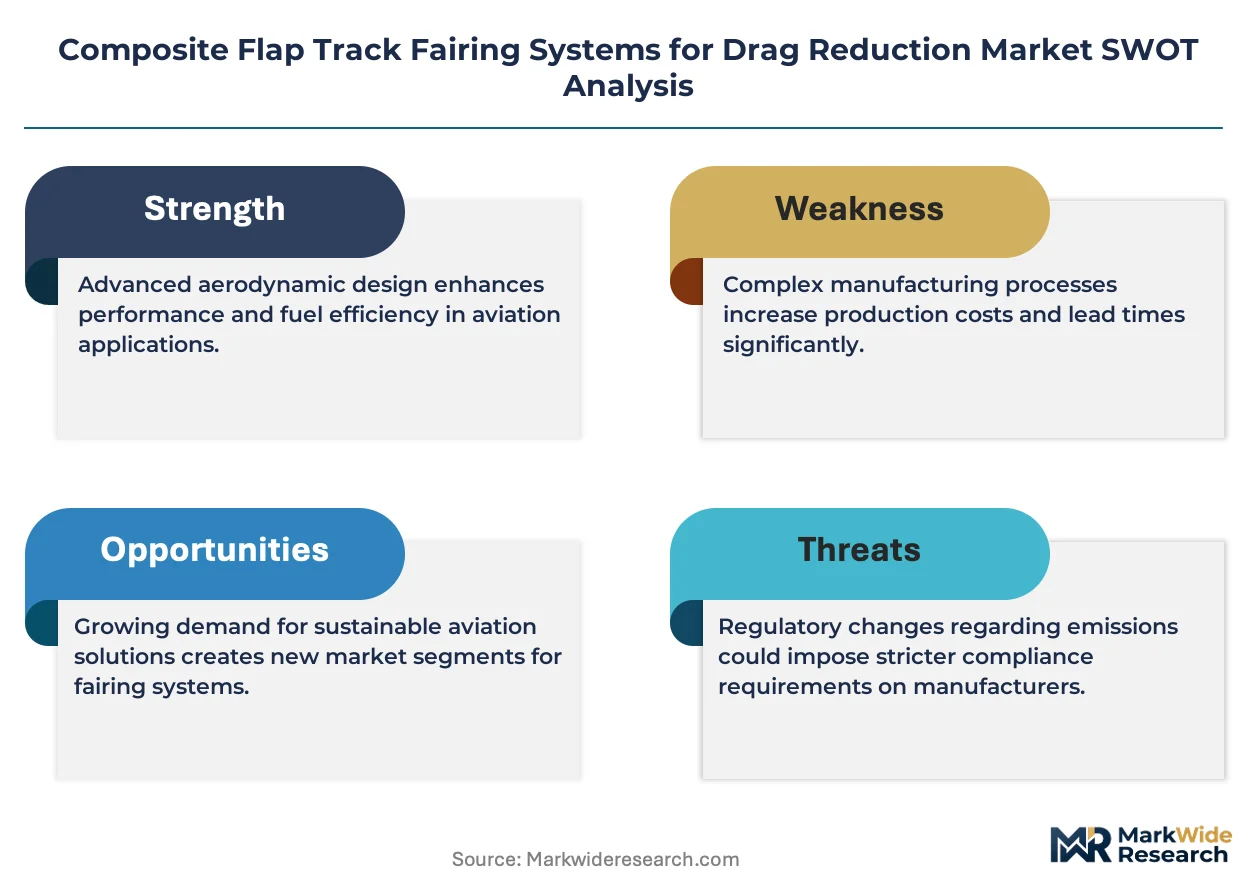
- Prepreg Cost Volatility:Carbon fiber tow and epoxy resin prices fluctuate with energy markets, compressing margins for suppliers locked into fixed-price OEM contracts without raw material escalation clauses.
- Autoclave Bottleneck Concentration:High-volume curing capacity clusters in Wichita and Tulsa, creating geographic single-point-of-failure risk for narrowbody program deliveries during equipment maintenance cycles.
- Metallic Substitution Persistence:Aluminum-lithium alloys retain certification grandfathering advantages for certain flap track bracket interfaces, slowing full composite adoption in military trainer platforms where cost sensitivity dominates.
Strategic Opportunities
- Unmanned Aerial Vehicle Glass Fiber Demand:Military drone manufacturers in the United States are specifying lower-cost glass fiber fairings for reconnaissance platforms, opening volume segments outside commercial aviation price structures.
- EU Green Deal SAF Mandates:Sustainable aviation fuel requirements are accelerating airline fleet renewal decisions, pulling forward replacement demand for drag-reducing fairing systems on next-generation narrowbodies.
- Filament Winding Channel Innovation:Direct-to-operator digital procurement platforms are disintermediating traditional distributor networks for aftermarket fairing replacements, capturing margin previously held by regional MRO intermediaries.
Industry Challenges
- Aerospace Composites Engineering Scarcity:Qualified autoclave technicians and laminate stress analysts command premium wages, constraining production ramp rates for suppliers without established apprenticeship pipelines.
- AS9100 Certification Timeline Compression:New entrants face 18-24 month qualification periods for OEM tier-1 eligibility, locking out capital-constrained competitors from retrofit contract windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Flap Track Fairing Systems for Drag Reduction Market |
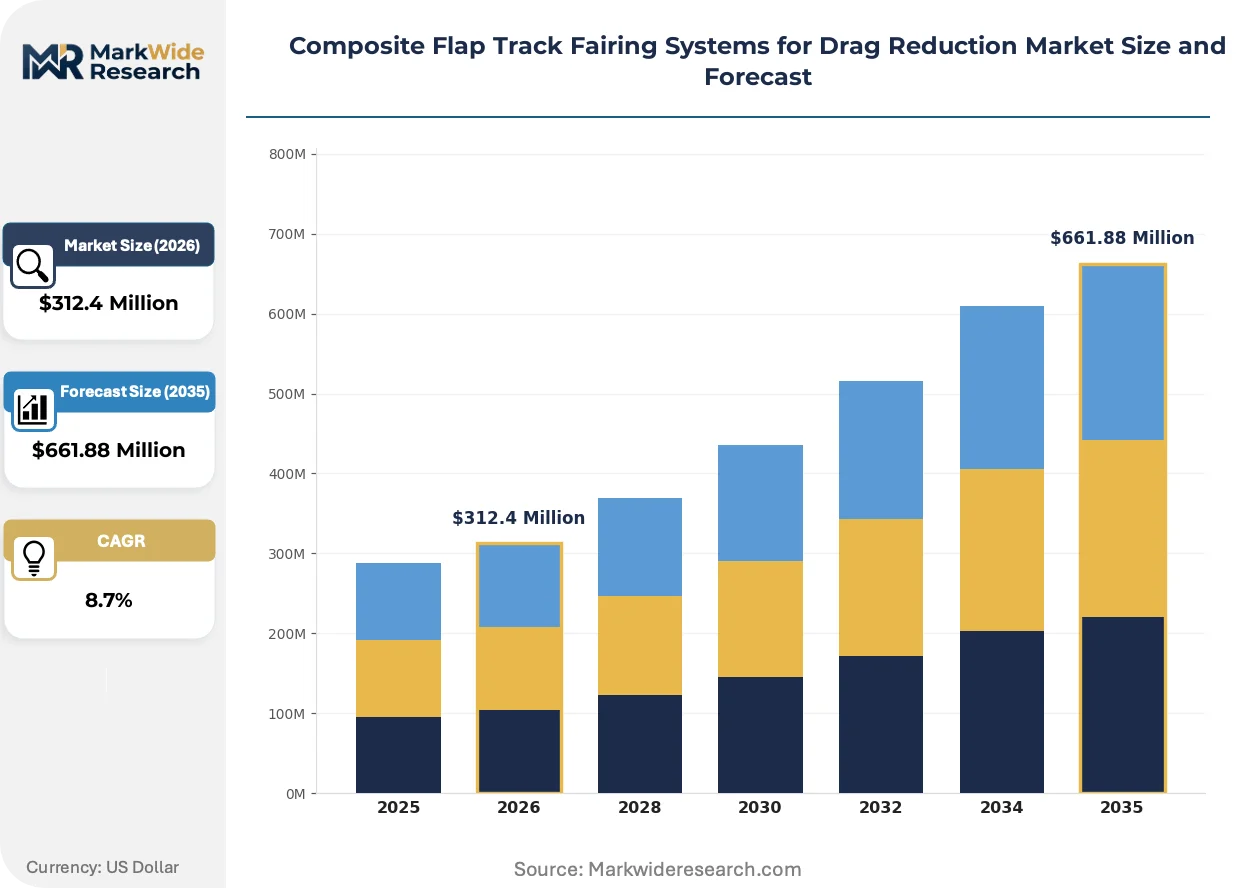
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites Technology: Resin Transfer Molding, Prepreg Layup, Filament Winding, Autoclave Curing Application: Commercial Aircraft, Military Jets, Business Aircraft, Unmanned Aerial Vehicles End User: Aircraft Manufacturers, Aerospace Tier-1 Suppliers, Maintenance Providers, Research Institutes |
| Companies Covered | Aero Design Labs, Aviation Partners Boeing, Vortex Control Technologies, SACS Aerospace, ALOFT AeroArchitects, The NORDAM Group, Lufthansa Technik, Spirit AeroSystems, FACC AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Flap Track Fairing Systems for Drag Reduction Market Trends and Innovations
Manufacturing technology trajectories and regulatory compliance architectures are actively fragmenting competitive positioning across the composite fairing value chain, with curing methodology and geographic certification strategy emerging as primary differentiation axes.
Resin transfer molding is bifurcating the supplier base between high-capital autoclave incumbents and lean entrants targeting retrofit markets with out-of-autoclave qualification pathways. European second-tier suppliers are adopting RTM systems to bypass Wichita production gravity and capture EASA-certified aftermarket volume. This technology compression is enabling geographic diversification of fairing supply away from traditional Midwest manufacturing clusters.
The EU F-Gas Regulation is forcing reformulation of thermoset matrices toward lower-global-warming-potential curing agents. European prepreg manufacturers are accelerating bio-based hardener development to maintain ECHA compliance and avoid import restrictions on legacy epoxy systems. Narrowbody OEM procurement specifications are tightening substance declarations, disqualifying suppliers without EU-compliant material certifications.
Airline procurement teams are consolidating fairing purchases into airframe lifecycle contracts that bundle initial installation with scheduled replacement intervals. United States-based network carriers are negotiating multi-year supply agreements with MRO-integrated manufacturers, displacing spot-market aftermarket transactions. This bundling behavior concentrates procurement volume with vertically integrated suppliers controlling both production and Tulsa-based repair station networks.
Composite Flap Track Fairing Systems for Drag Reduction Market Segmentation
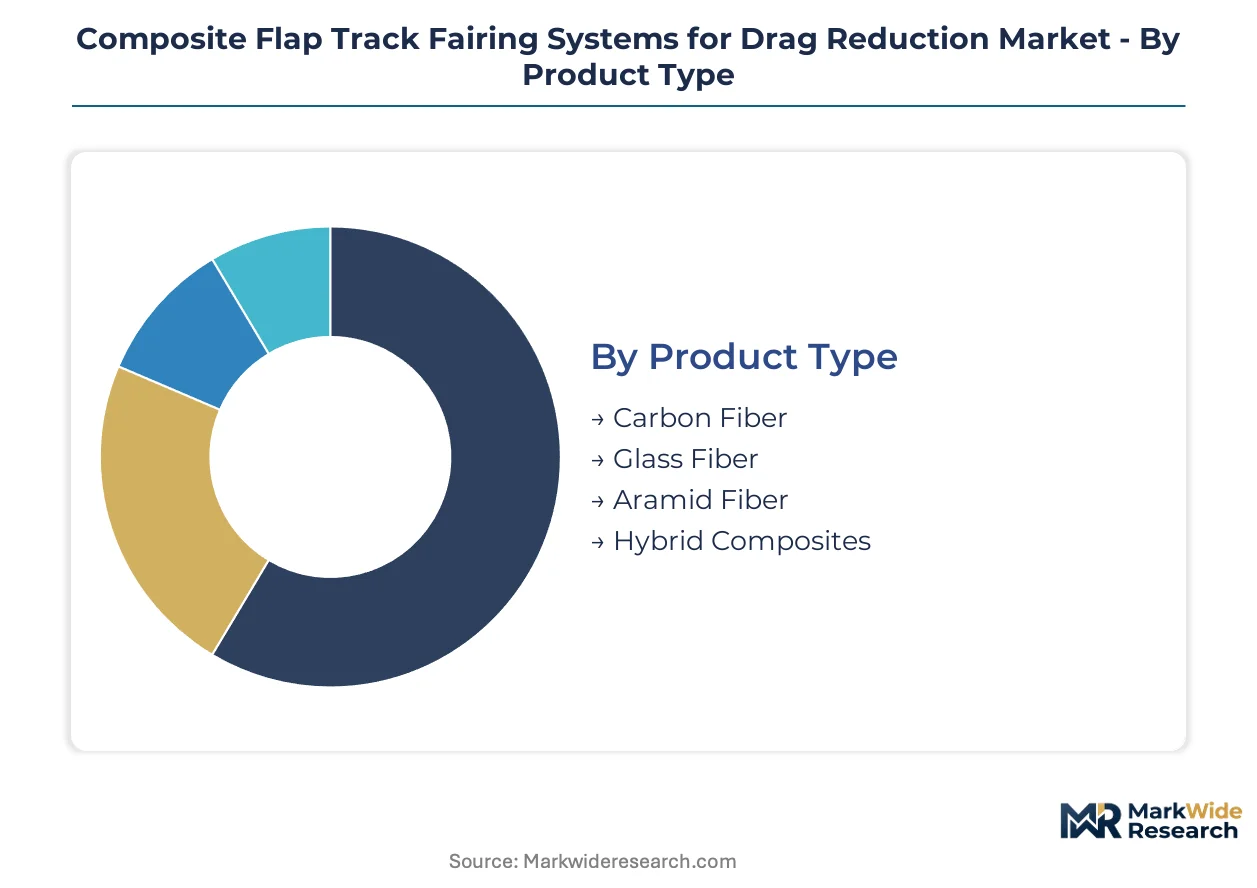
Material selection and curing methodology determine certification pathways and procurement eligibility across the composite fairing value chain. Segment boundaries reflect divergent capital requirements, regulatory compliance architectures, and end-use performance specifications that reshape supplier competitive positioning.
Product Type:
Substitution pressure from aluminum-lithium alloys and thermoplastic composites fragments material selection across cost-performance thresholds.
- Carbon Fiber:Carbon fiber-epoxy laminates deliver specific stiffness ratios exceeding 100 GPa/(g/cm³), qualifying for narrowbody wing trailing-edge interfaces where FAA airworthiness directives mandate fatigue resistance. Commercial aircraft OEMs in the United States specify these formulations for new-build programs despite raw material premiums.
- Glass Fiber:E-glass and S-glass reinforced polymers occupy cost-sensitive platforms where specific strength requirements fall below 40 GPa/(g/cm³). Military drone manufacturers specify these for reconnaissance fairings, trading marginal weight penalties against unit economics.
- Aramid Fiber:Kevlar-based composites provide impact damage tolerance for military trainer flap track enclosures where ballistic survivability supplements aerodynamic performance.
- Hybrid Composites:Carbon-glass interlaminar constructions balance cost and stiffness for business aircraft retrofit programs seeking incremental drag reduction without full carbon fiber conversion costs.
Carbon fiber retains volume leadership; hybrid composites hold the steepest expansion curve as regional jet operators pursue phased material upgrades.
Technology:
Capital deployment thresholds stratify supplier tiers between high-volume OEM qualification and lean aftermarket entry.
- Resin Transfer Molding:Closed-mold injection systems enable European second-tier suppliers to bypass Wichita autoclave gravity, capturing EASA-certified retrofit contracts with 40% lower fixed asset requirements than thermal curing alternatives.
- Prepreg Layup:Hand or automated placement of resin-impregnated fiber sheets dominates tier-1 OEM supply chains where AS9100 traceability requirements favor established material formats.
- Filament Winding:Automated fiber deposition around mandrels suits cylindrical fairing subcomponents, with direct-to-operator digital platforms disintermediating traditional MRO distribution for aftermarket replacements.
- Autoclave Curing:High-pressure thermal consolidation remains the certification gold standard for structural load-bearing fairings, concentrating qualified capacity in Spirit AeroSystems' Wichita footprint and NORDAM's Tulsa operations.
Autoclave curing commands the dominant revenue share; resin transfer molding expands most quickly among capital-constrained entrants targeting European retrofit windows.
Application:
Platform-specific certification timelines and fleet renewal cycles reshape demand concentration across aviation sectors.
- Commercial Aircraft:Narrowbody and widebody programs drive procurement volume where EPA aircraft emissions standards and EU Green Deal SAF mandates accelerate composite adoption for fuel burn reduction during climb and cruise phases.
- Military Jets:Fighter and trainer platforms sustain metallic grandfathering advantages for certain bracket interfaces, though F-35 program specifications are pulling carbon fiber fairing demand.
- Business Aircraft:Fractional ownership fleets and corporate operators specify drag-reducing retrofits to extend range performance without airframe replacement.
- Unmanned Aerial Vehicles:Reconnaissance and strike drone programs specify glass fiber constructions where mission endurance requirements outweigh structural optimization priorities.
Commercial aircraft absorbs the dominant procurement volume; unmanned aerial vehicles climb the fastest as defense procurement shifts toward attritable platforms.
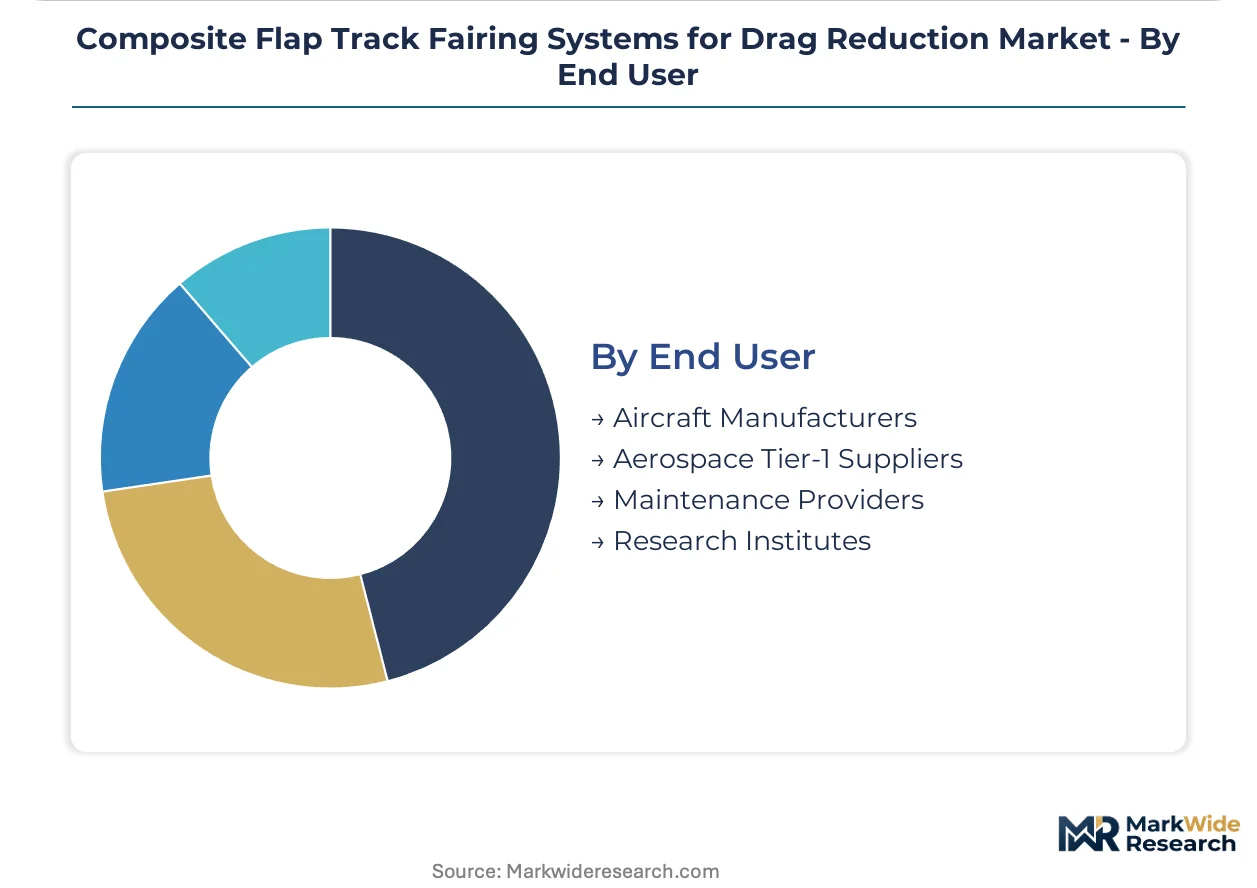
End User:
Procurement consolidation into lifecycle contracts restructures channel relationships between production and aftermarket service.
- Aircraft Manufacturers:Boeing and Airbus final assembly lines specify fairing systems through multi-year supply agreements that bundle initial installation with scheduled replacement intervals, concentrating volume with vertically integrated tier-1 suppliers.
- Aerospace Tier-1 Suppliers:Spirit AeroSystems and FACC AG intermediate between OEMs and raw material providers, controlling autoclave capacity and automated fiber placement R&D respectively.
- Maintenance Providers:Tulsa-based MRO hubs and European repair stations capture aftermarket replacement demand, with airline procurement teams consolidating purchases into airframe lifecycle contracts.
- Research Institutes:NASA and EU-funded aeronautics laboratories specify experimental fairing configurations for next-generation high-lift system validation.
Aircraft manufacturers retain procurement leadership; maintenance providers gain share fastest as fleet aging extends retrofit program timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States operators prioritize narrowbody retrofit volume for fuel efficiency compliance, while European procurement emphasizes REACH-compliant material formulations. Asian demand concentrates on new-build programs rather than aftermarket replacement.
United States
FAA emissions mandates and EPA aircraft standards drive narrowbody fleet upgrades. The country's national aviation regulator enforces continuous lower energy emissions noise regulations that accelerate composite adoption. Wichita and Tulsa anchor production gravity, with Spirit AeroSystems sustaining autoclave capacity and NORDAM controlling regional MRO distribution channels.
Germany
EASA certification specifications and EU Green Deal SAF mandates pull forward airline fleet renewal decisions. ECHA substance restrictions force thermoset matrix reformulation toward lower volatile organic compound profiles. Hamburg and Munich MRO hubs consolidate procurement into airframe lifecycle contracts that bundle initial installation with scheduled replacement intervals.
France
Airbus final assembly lines specify fairing systems through multi-year supply agreements with tier-1 suppliers. The EU F-Gas Regulation accelerates bio-based hardener development to maintain compliance and avoid import restrictions. Toulouse and Nantes aerospace clusters concentrate automated fiber placement R&D for European retrofit contract competition.
China
Commercial aircraft OEMs expand domestic supply chain localization for next-generation narrowbody programs. The country's national aviation regulator aligns certification pathways with ICAO carbon offset requirements. Shanghai and Xi'an manufacturing bases develop filament winding capacity for cost-efficient entry into military drone fairing segments.
United Kingdom
Business aircraft operators specify drag-reducing retrofits to extend range performance without airframe replacement. BSI quality frameworks determine supplier eligibility for defense procurement contracts. Bristol and Derby aerospace corridors concentrate hybrid composite development for regional jet phased material upgrade programs.
Composite Flap Track Fairing Systems for Drag Reduction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. The supplier base stratifies between high-capital autoclave incumbents and lean entrants targeting retrofit markets with out-of-autoclave qualification pathways. Three archetypes dominate: vertically integrated OEM-tier suppliers controlling production and MRO networks, European second-tier specialists leveraging automated fiber placement R&D, and regional MRO-integrated fabricators capturing aftermarket replacement demand. Competitive moves concentrate on geographic certification strategy and curing methodology diversification.
Among US-based fabricators, Spirit AeroSystems and The NORDAM Group occupy positions within the integrated supplier archetype, exemplifying the Midwest production gravity that concentrates qualified autoclave capacity. FACC AG represents the European specialist tier, anchoring Austrian-based R&D in automated fiber placement systems that enable competitive bidding on EASA-certified retrofit contracts.
| Leading Market Players |
|---|
| Aero Design Labs |
| Aviation Partners Boeing |
| Vortex Control Technologies |
| SACS Aerospace |
| ALOFT AeroArchitects |
| The NORDAM Group |
| Lufthansa Technik |
| Spirit AeroSystems |
| FACC AG |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between narrowbody OEMs and tier-1 suppliers lock in autoclave capacity access while fixing carbon fiber-epoxy laminate prices against raw material escalation clauses. These contracts bundle initial fairing installation with scheduled replacement intervals, compressing spot-market pricing visibility for aftermarket entrants lacking Tulsa-based MRO integration.
Pricing Analysis
Contract-based long-term offtake dominates tier-1 procurement, with price differentiation driven by AS9100 certification tier and volume scale commitments. Three-tier pricing structure across premium autoclave-cured, standard RTM-processed, and economy glass fiber tiers reflects manufacturing complexity gradients. Pricing pressure stems from prepreg cost volatility tied to energy markets, squeezing margins for suppliers without raw material escalation protection. Military drone manufacturers exhibit highest price sensitivity, while commercial aircraft OEMs prioritize certification reliability over unit cost.
Supply Chain Analysis
Inbound logistics costs for carbon fiber tow shipments from Japan and South Korea fluctuate with transpacific container availability, compressing landed cost predictability for Wichita-based fabricators. Geographic supply concentrates in the United States, Austria, and China, with raw material dependencies spanning Toray carbon fiber, Huntsman epoxy systems, and Solvay thermoset matrices. Single-source vulnerability runs through high-pressure autoclave equipment concentrated in Midwest manufacturing clusters. Distribution runs through vertically integrated tier-1 suppliers controlling both production and Tulsa-based repair station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as airline procurement teams disaggregate fairing purchases from full airframe contracts, creating niches for specialized retrofit suppliers. Demand-side shift toward unmanned aerial vehicle programs opens volume segments outside commercial aviation price structures.
For Market Incumbents: Secure autoclave capacity expansion in Wichita to defend against resin transfer molding entrants targeting European retrofit windows. Deepen backward integration into carbon fiber prepreg manufacturing to offset raw material cost volatility threatening fixed-price OEM contract margins. Prioritize AS9100 certification maintenance for tier-1 eligibility as FAA emissions mandates compress qualification timelines. For New Entrants and Emerging Players: Anchor in EASA-certified aftermarket channels by deploying automated fiber placement systems that bypass Midwest production gravity. Target unmanned aerial vehicle glass fiber segments where military cost sensitivity outweighs performance optimization. Pursue direct-to-operator digital procurement platforms that disintermediate traditional MRO distribution networks. For Investors and Strategic Acquirers: Capital is best deployed toward European second-tier specialists with certified out-of-autoclave capacity and established EASA compliance pathways. Long-term viability hinges on supplier positioning for sustainable aviation fuel-driven fleet renewal cycles. Watch for ICAO carbon offset requirement tightening as inflection indicator pulling forward composite adoption mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Deployment | Robotic layup systems cut cycle times for carbon fiber-epoxy laminates, enabling competitive European retrofit bidding. |
| Out-of-Autoclave Qualification Pathway | RTM certification bypasses Wichita capacity concentration, diversifying geographic supply for EASA-compliant aftermarket volume. |
| Backward Integration into Prepreg Manufacturing | In-house carbon fiber-epoxy production hedges against Huntsman and Solvay raw material price volatility. |
| Direct-to-Operator Digital Platform Launch | Disintermediation of Tulsa-based MRO distributors captures margin previously held by regional repair station intermediaries. |
| EU F-Gas Regulation Compliance Program | Bio-based hardener development maintains ECHA substance authorization and avoids import restrictions on legacy epoxy systems. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with tier-1 supplier procurement directors, autoclave operations managers, MRO contract negotiators, and FAA certification engineers; and secondary validation against EASA certification specifications, EPA aircraft emissions filings, customs trade records for carbon fiber imports, and SEC disclosures from aerospace component manufacturers. Bottom-up build from individual program volumes and top-down cross-check against fleet renewal projections ensured triangulation integrity.
Across the projection horizon, the analytical framework modeled demand by material type, curing technology, platform application, and procurement channel structure. CAGRs derived from segment-level volume trajectories weighted by regional regulatory enforcement intensity. Industry-specific forecast inputs included FAA airworthiness directive issuance timelines and EU Green Deal sustainable aviation fuel mandate implementation pacing.
Decision-makers should treat outputs as directional under assumptions of continued FAA emissions mandate enforcement and stable carbon fiber supply from Japanese and South Korean producers; material deviation in regulatory stringency or trade lane disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aircraft Exterior Structure Digital Twin Platforms Market