
 Advanced Turbine Blade Design Market | 2026-2036
Advanced Turbine Blade Design Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Turbine Blade Design Market Outlook
Project finance for offshore wind farms is reshaping which blade designers can compete at utility scale. GE Vernova leverages its captive manufacturing footprint to control cost structures across large-diameter offshore platforms. Siemens Gamesa Renewable Energy anchors European demand through integrated blade-to-nacelle engineering capabilities. Vestas Wind Systems A/S differentiates via its global service network that extends blade life cycles and captures recurring revenue streams.
Advanced turbine blade design encompasses the aerodynamic, thermal, and structural engineering of precision-engineered airfoils that convert fluid energy into rotational mechanical power, typically manufactured from nickel-based superalloys with internal cooling channels operating above alloy melting temperatures. The discipline serves aviation propulsion, land-based power generation, and marine propulsion systems where thermodynamic efficiency directly determines fuel consumption and emissions profiles. Single crystal casting dominates aerospace applications where creep resistance at extreme temperatures determines engine performance ceilings, while additive manufacturing represents the fastest-growing process segment as geometric complexity for internal cooling networks outstrips conventional investment casting capabilities. Composite materials occupy expanding niches in wind turbine applications where mass reduction at extreme rotor diameters determines transport and installation economics.
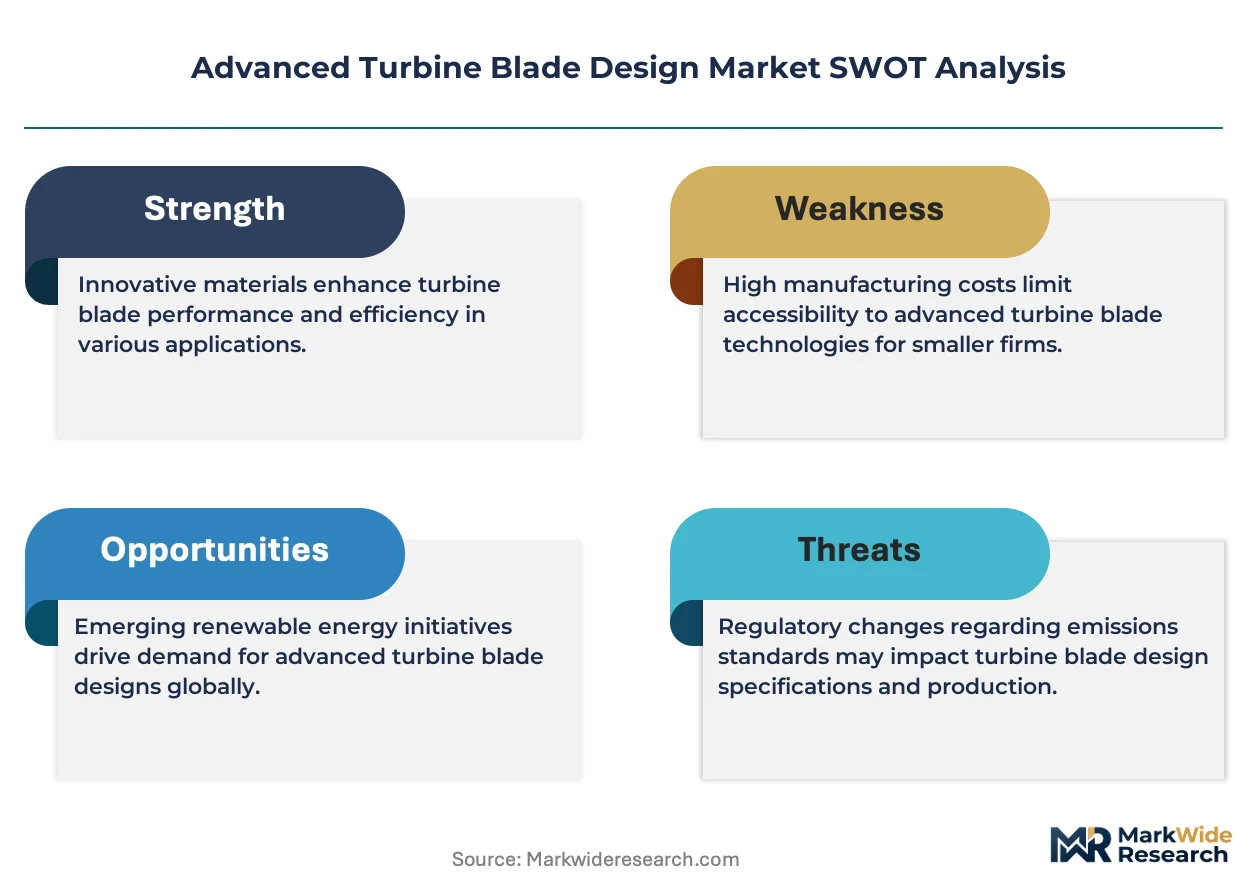
EASA certification requirements for engine durability and the FAA's continued airworthiness directives shape product development timelines and testing burdens for aviation-focused designers. The EU Green Deal's carbon intensity benchmarks and REACH chemical restrictions on coating formulations constrain material selection and surface treatment processes across European manufacturing. Stakeholders must monitor how tightening NOx and CO2 standards from multiple regulators simultaneously redirect R&D budgets toward hybrid-electric architectures that may redefine blade loading profiles and cooling requirements.
Market Dynamics
Geared turbofan architectures are forcing blade designers to reoptimize airfoil profiles for lower fan pressure ratios and reduced bypass duct losses. This engine cycle shift compresses development timelines while elevating thermal management requirements.
Growth Catalysts
- EASA emissions mandates:Certification timelines for reduced NOx and CO2 outputs accelerate procurement of advanced cooling geometries and thermal barrier coatings across European aviation programs.
- Single crystal casting:Aerospace propulsion OEMs specify creep-resistant superalloy microstructures for high-pressure turbine stages operating above alloy melting temperatures.
- German supplier density:Concentrated engineering talent around Munich and Berlin enables rapid prototype-to-production cycles for both aviation and power generation blade families.
Market Restraints
- Rhenium supply concentration:Superalloy creep resistance depends on this rare refractory metal sourced from limited Kazakh and Chilean mining operations.
- Investment casting capacity:Directional solidification furnaces require 18-24 month lead times, constraining volume scaling for new engine programs.
- REACH coating restrictions:EU chemical regulations limit hexavalent chromium and cobalt-based surface treatments, forcing reformulation of established protective systems.
Strategic Opportunities
- Hybrid-electric architectures:NASA and EU Clean Aviation initiatives fund blade designs optimized for partial-electric propulsion cycles with altered loading profiles.
- Additive manufacturing convergence:Laser powder bed fusion combined with hot isostatic pressing enables conformal cooling channels impossible in conventional casting.
- India defense procurement:Indigenous fighter engine programs create demand for technology transfer partnerships with established blade design houses.
Industry Challenges
- Computational fluid dynamics talent scarcity:Specialized expertise in conjugate heat transfer modeling for rotating machinery commands premium compensation and extended recruitment cycles.
- FAA engine certification timelines:Extended endurance testing and blade-out containment demonstrations delay revenue recognition by 12-18 months for new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Turbine Blade Design Market |
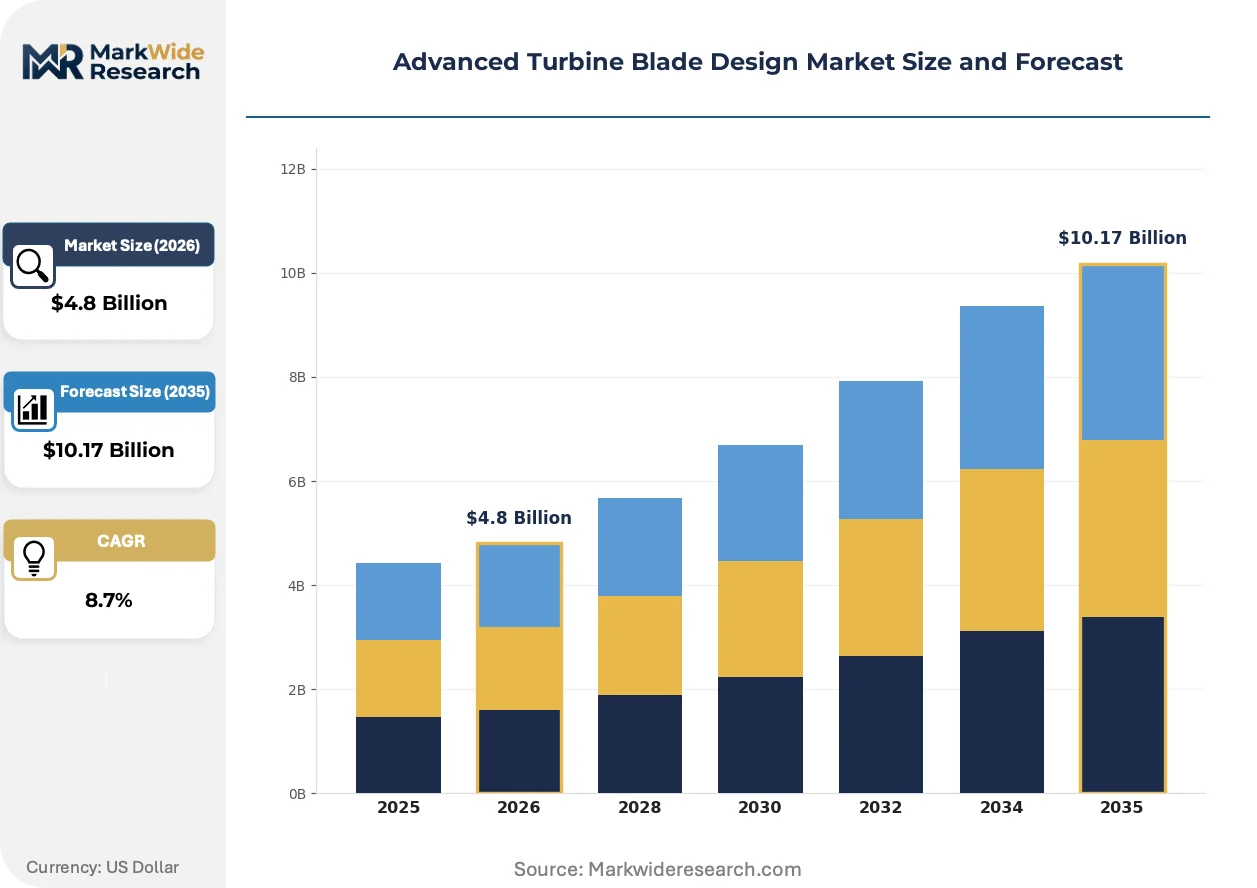
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Directional, Polycrystalline, Composite Manufacturing Process: Investment Casting, Additive Manufacturing, Forging, Machining End User: Aerospace, Power Generation, Marine, Industrial Material: Titanium Alloys, Nickel Alloys, Cobalt Alloys, Steel |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, GE Vernova, LM Wind Power, Nordex SE, TPI Composites, Goldwind Science & Technology, Suzlon Energy, ENERCON GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Turbine Blade Design Market Strategic Shifts
Digital thread integration across design, manufacturing, and in-service monitoring is collapsing iteration cycles. Blade engineers now embed fiber optic sensors and wireless telemetry directly into cast structures.
Additive manufacturing of nickel-based superalloys is hybridizing with subtractive finishing and hot isostatic pressing to deliver geometrically complex internal cooling networks. Aerospace OEMs adopt these hybrid processes for low-pressure turbine vanes where feature complexity exceeds casting resolution. The approach compresses lead times from 52 weeks to 16 weeks while enabling topology-optimized rib structures.
The EU Green Deal's carbon intensity benchmarks are forcing coating suppliers to eliminate hexavalent chromium from thermal barrier systems. REACH-compliant ceramic topcoats with rare-earth dopants now dominate European procurement specifications. Aviation-focused designers in Germany and France accelerate qualification of alternative bond coat chemistries to maintain EASA certification timelines.
Power generation utilities now unbundle blade life extension services from original equipment supply contracts. Independent service providers capture recurring revenue through condition-based maintenance programs using drone-mounted thermography. This procurement pattern shift is most visible in German offshore wind clusters where Siemens Energy and Vestas compete on service network density rather than hardware pricing alone.
Advanced Turbine Blade Design Market Segmentation
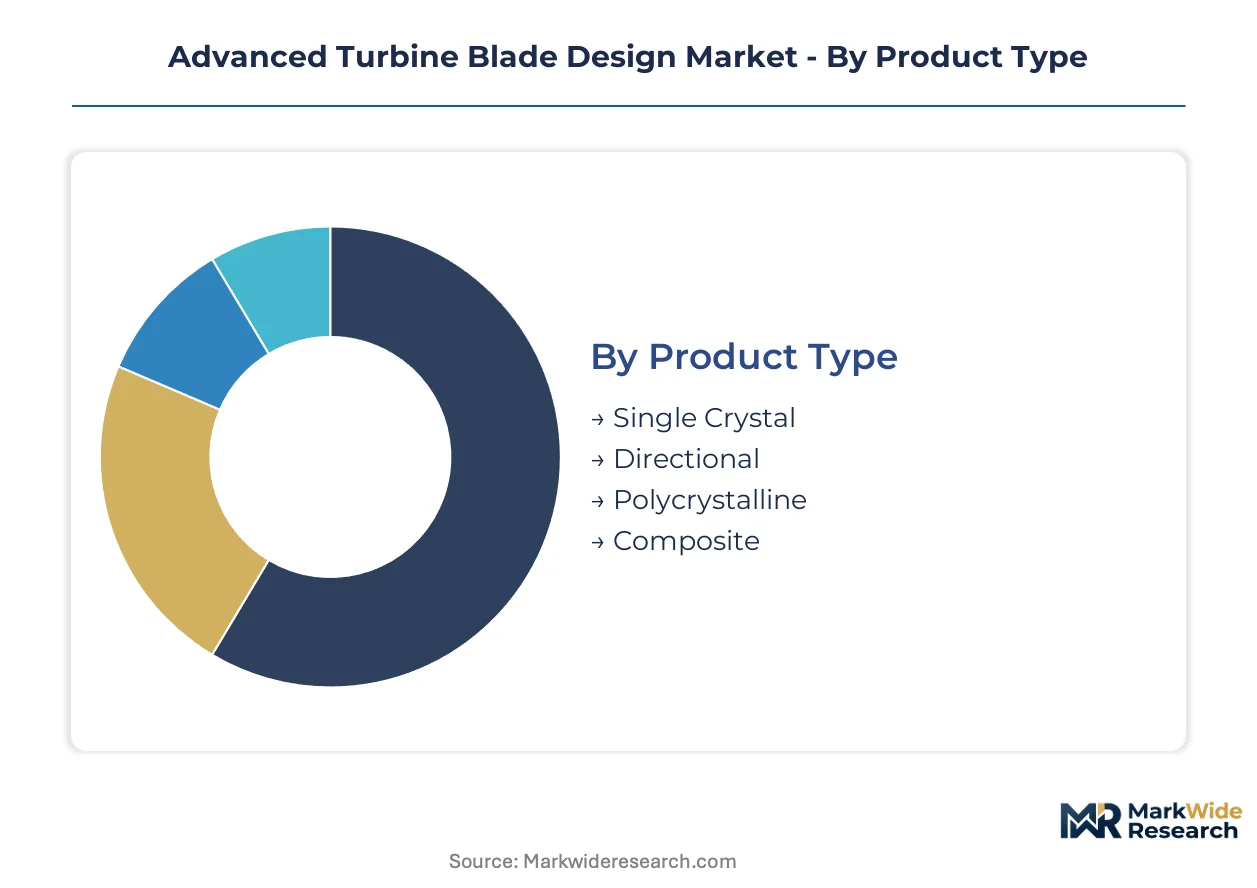
Segmentation in advanced turbine blade design reveals how material science and manufacturing economics split procurement budgets across radically different technical requirements. Aerospace OEMs prioritize creep resistance and thermal management, while power generation utilities balance capital cost against decades-long service intervals.
Product Type:
After-sales-service intensity varies dramatically across crystal structures, with single crystal blades demanding specialized repair networks and polycrystalline alternatives enabling broader maintenance options.
- Single Crystal:Creep-resistant superalloy microstructure eliminates grain boundaries for high-pressure turbine stages operating above alloy melting temperatures. Siemens Energy and MTU Aero Engines in Germany anchor procurement for next-generation geared turbofan programs where EASA emissions mandates accelerate adoption. By volume, polycrystalline leads. By growth pace, single crystal is ahead.
- Directional:Columnar grain alignment delivers intermediate creep performance for industrial gas turbines where thermal cycling tolerance outweighs absolute temperature capability. Demand concentrates in land-based power generation applications across German utility fleets seeking extended hot-path component life.
- Polycrystalline:Equiaxed grain structures serve lower-temperature compressor stages and cost-sensitive industrial applications.
- Composite:Polymer matrix and ceramic matrix variants address wind turbine rotors where mass reduction at extreme diameters determines transport logistics.
Service infrastructure investment tracks crystal complexity, with single crystal commanding captive repair networks that lock in multi-decade revenue streams.
Manufacturing Process:
Cost tier stratification separates capital-intensive directional solidification from emerging additive approaches that compress prototype-to-production cycles.
- Investment Casting:Directional solidification furnaces produce aerospace-grade single crystal and directional structures through controlled thermal gradients. German supplier clusters around Munich leverage 18-24 month furnace lead times as a competitive moat against new entrants. By volume, investment casting leads. By growth pace, additive manufacturing is ahead.
- Additive Manufacturing:Laser powder bed fusion enables conformal cooling geometries impossible in conventional casting, with hybrid processes compressing lead times from 52 weeks to 16 weeks for low-pressure turbine vanes. Aerospace OEMs qualify these methods for geometric complexity exceeding casting resolution.
- Forging:Closed-die and isothermal pressing shapes titanium alloy compressor blades where grain flow alignment determines fatigue resistance.
- Machining:Five-axis milling and abrasive finishing deliver final airfoil tolerances across all process routes, with specialized grinding of nickel-based superalloys representing a bottleneck skill.
Process selection locks in downstream economics, with additive methods expanding most quickly in prototyping while investment casting retains volume dominance in certified aerospace production.
End User:
Application-specific loading profiles and certification burdens fragment design requirements across propulsion, generation, and industrial duty cycles.
- Aerospace:Engine OEMs specify FAA and EASA-certified designs with blade-out containment and endurance testing extending development timelines 12-18 months beyond initial design freeze. Geared turbofan architectures force reoptimization of airfoil profiles for lower fan pressure ratios, with procurement accelerating from next-generation narrowbody programs.
- Power Generation:Combined cycle and frame gas turbines prioritize thermal barrier coating durability over thousands of start-stop cycles, with German offshore wind clusters driving unbundling of blade life extension services from original hardware supply.
- Marine:Naval and commercial propulsion systems balance corrosion resistance with cavitation tolerance in saltwater environments.
- Industrial:Mechanical drive and process applications accept shorter design life in exchange for lower capital cost and faster replacement availability.
Certification burden intensity separates aerospace from industrial tiers, with power generation occupying an intermediate position where utility procurement patterns increasingly resemble aviation's long-term service contracting.
Material:
Supply concentration for refractory alloying elements creates vulnerability cascades that reshape procurement strategies across end-use segments.
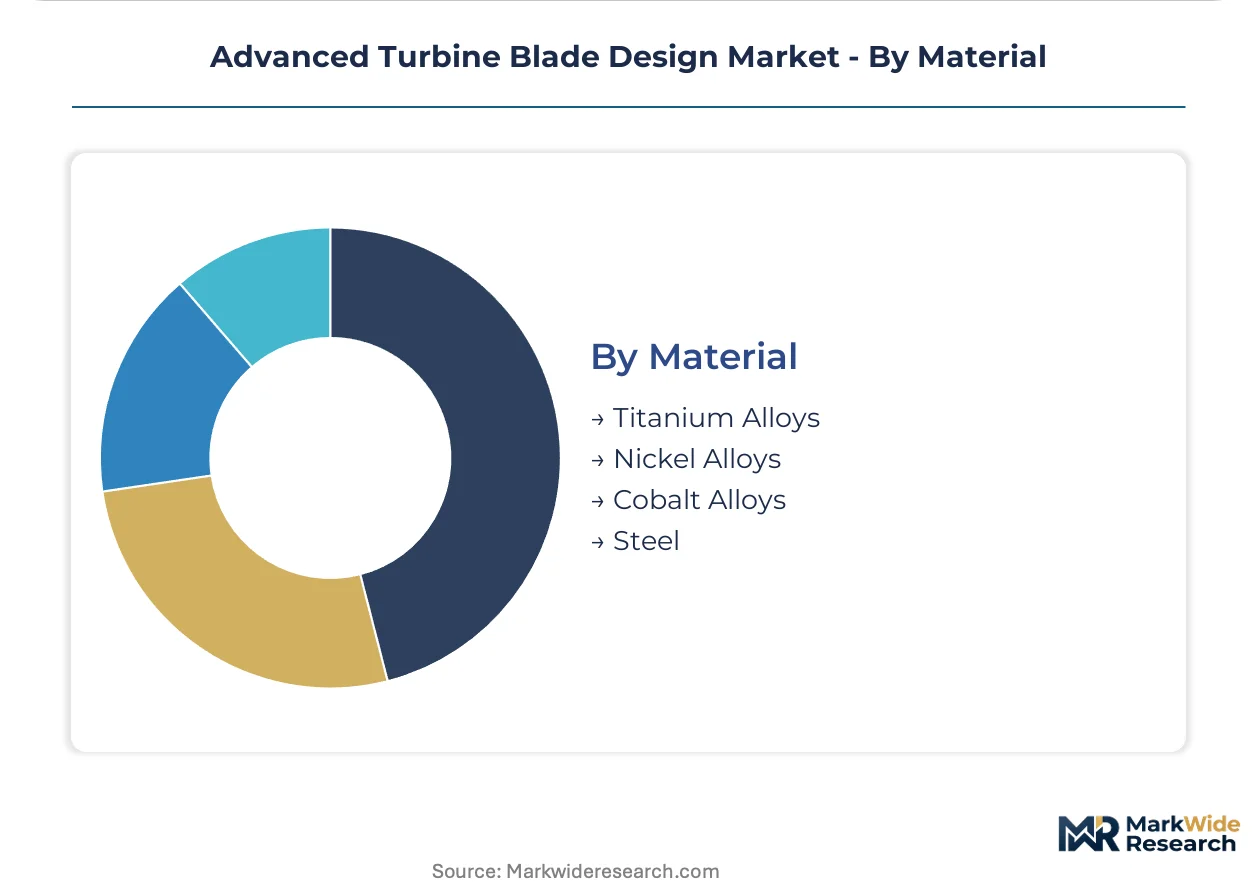
- Nickel Alloys:Gamma-prime strengthened superalloys with rhenium, tungsten, and tantalum additions dominate high-pressure turbine applications where creep resistance determines engine performance ceilings. REACH restrictions on cobalt-based bond coats force reformulation of established protective systems across European manufacturing.
- Titanium Alloys:Alpha-beta and near-alpha compositions serve compressor stages where specific strength and fatigue resistance outweigh temperature capability, with forgings concentrated in aerospace supply chains.
- Cobalt Alloys:Wear-resistant compositions persist in industrial turbine shrouds and seals despite regulatory pressure on raw material sourcing.
- Steel:Martensitic and precipitation-hardened grades address lower-temperature applications and structural hardware where cost sensitivity dominates material selection.
Material substitution timelines track regulatory pressure and mining economics, with rhenium supply concentration from Kazakh and Chilean operations constraining nickel superalloy scaling for new engine programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial advanced turbine blade trade surplus, exporting precision-engineered aerospace components to engine OEMs across North America and Asia while importing raw superalloy feedstock from Kazakhstan and Chile. This exchange pattern concentrates value-added design and manufacturing in German industrial clusters while externalizing upstream mining exposure.
Germany
EASA emissions mandates accelerate procurement of thermal barrier coatings and advanced cooling geometries from Munich and Berlin engineering clusters. REACH restrictions on hexavalent chromium force coating reformulation across Bavarian manufacturing sites. Siemens Energy and MTU Aero Engines anchor a dense supplier ecosystem serving both aviation geared turbofan programs and offshore wind blade extensions.
United States
FAA certification timelines for next-generation narrowbody engines extend development cycles 12-18 months, compressing procurement windows for domestic blade designers. The Inflation Reduction Act's clean energy tax credits redirect utility procurement toward domestic offshore wind manufacturing. GE Vernova leverages captive production footprints across multiple states to control cost structures for large-diameter wind platforms.
China
Dual carbon goals and MIIT industrial upgrading directives accelerate domestic superalloy casting capacity for indigenous fighter engine programs. Goldwind Science & Technology scales composite blade production for extreme-diameter onshore wind turbines. Yangtze River Delta manufacturing hubs concentrate investment casting and additive manufacturing hybrid processes for low-pressure turbine vanes.
India
Indigenous fighter engine development under DRDO programs creates technology transfer demand with established European blade design houses. PLI scheme incentives for aerospace components attract joint venture proposals into Karnataka and Telangana manufacturing corridors. Suzlon Energy maintains domestic wind blade fabrication for utility-scale renewable procurement auctions.
United Kingdom
Rolls-Royce UltraFan program procurement sustains Derby-area precision casting for high-pressure turbine stages. Offshore wind lease rounds in the North Sea drive demand for LM Wind Power blade extensions from Hull manufacturing facilities. UK Research and Innovation funding supports additive manufacturing qualification for conformal cooling geometries in aerospace applications.
Advanced Turbine Blade Design Market Competitive Environment
On the supply side, the industry is bifurcated between consolidated aerospace propulsion specialists and fragmented wind energy blade fabricators. Aerospace tiers concentrate around single-crystal casting capabilities with 18-24 month furnace lead times acting as entry barriers. Wind energy segments exhibit scale-driven competition where rotor diameter economics determine transport logistics and installation viability. Dominant competitive moves include captive manufacturing footprint expansion and unbundling of blade life extension services from original hardware supply.
Among European-anchored engineering groups, Siemens Gamesa Renewable Energy exemplifies integrated blade-to-nacelle capabilities, while Vestas Wind Systems A/S occupies a position emphasizing global service network density for recurring revenue capture. GE Vernova represents the scale-driven archetype leveraging vertical manufacturing control across offshore wind platforms. These three entities collectively illustrate how competitive positioning diverges between hardware-centric and service-centric revenue models.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy |
| GE Vernova |
| LM Wind Power |
| Nordex SE |
| TPI Composites |
| Goldwind Science & Technology |
| Suzlon Energy |
| ENERCON GmbH |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor connects German superalloy foundries to aerospace OEM assembly lines, with its congestion surcharges amplifying cost differentials between captive producers and merchant suppliers while forcing tiered pricing stratification across EASA-certified and uncertified blade tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across EASA-certified premium tiers, volume-scale standard tiers, and uncertified economy alternatives. Price differentiation rests on certification grade and after-sales service bundling, with REACH compliance costs compressing margins in European supply tiers. Cost compression in polycrystalline segments is intensifying due to additive manufacturing adoption, while aerospace procurement remains least price-sensitive.
Supply Chain Analysis
PCC Structurals, Howmet Aerospace, and Cannon-Muskegon concentrate directional solidification capacity across Germany, the United States, and Japan. Raw material sourcing draws from Kazakh rhenium, Chilean cobalt, and Australian tantalum. Single-source vulnerability in rhenium refining creates procurement risk. Distribution runs through engine OEM captive networks and independent MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where EASA and FAA certification timelines create switching costs that lock OEMs into qualified supplier relationships for multi-decade engine programs.
For Market Incumbents: Build certification moats by accelerating qualification of REACH-compliant thermal barrier coatings before regulatory deadlines force reformulation. Deepen backward integration into rhenium sourcing through offtake agreements with Kazakh mining operations. Additive manufacturing startups threaten prototyping revenue streams. For New Entrants and Emerging Players: India's defense procurement corridors offer underpenetrated access points where DRDO technology transfer requirements lower barriers for European design houses. Target composite blade repair services for German offshore wind clusters where Vestas and Siemens Gamesa unbundle life extension contracts. Pursue joint venture structures with established foundries to bypass furnace lead time constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial divisions holding dormant single-crystal casting licenses. Long-term viability hinges on hybrid-electric architecture readiness across the projection horizon. Monitor NASA and EU Clean Aviation funding disbursements as inflection signals for blade loading profile shifts. Watch rhenium spot price volatility for supply chain stress indicators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Qualification | EASA certification maintenance secures multi-decade OEM supply contracts against regulatory disruption. |
| Additive Manufacturing Hybridization | Laser powder bed fusion adoption compresses low-pressure turbine vane lead times from 52 weeks to 16 weeks. |
| Rhenium Supply Agreement | Long-term offtake contracts with Kazakh mining operations hedge against single-source concentration risk. |
| Blade Life Extension Unbundling | Independent service providers capture recurring revenue through drone-mounted thermography in German offshore clusters. |
| Hybrid-Electric Architecture R&D | NASA and EU Clean Aviation funding enables blade designs optimized for partial-electric propulsion cycles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EASA certification databases, FAA type certificate filings, and EU emissions directive texts. Primary interviews engaged aerospace propulsion engineers, thermal barrier coating formulators, superalloy procurement leads at engine OEMs, and directional solidification furnace operators. Secondary validation drew from customs trade data for rhenium and cobalt flows, SEC 10-K disclosures from listed suppliers, and IEA power generation equipment databases. Bottom-up blade demand modeling triangulated against top-down engine production forecasts.
Forecast inputs span crystal structure tier, end-use application, manufacturing process route, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level demand elasticity modeling calibrated to EASA and FAA program timelines. Industry-specific inputs include geared turbofan adoption curves and REACH chemical restriction phase-in schedules.
Practitioners should monitor EASA emissions mandate acceleration, rhenium supply disruption events, and hybrid-electric program funding cancellations for early signals of forecast revision. Quarterly review of furnace capacity utilization rates and coating qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market