
 Global Aircraft Seat Actuation System Market | 2026-2036
Global Aircraft Seat Actuation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Seat Actuation System Market Intelligence
A divergence in R&D investment for lightweight composite materials versus legacy metal fabrication is rotating competitive advantage toward specialized component suppliers. Large-scale integrators like SAFRAN and RTX leverage their extensive portfolios to offer complete seating solutions for airline customers. In contrast, specialists such as Bühler Motor GmbH differentiate through expertise in high-performance miniature motors. Moog Inc. competes by providing advanced motion control systems for both commercial and military aircraft applications.
An aircraft seat actuation system comprises the electromechanical or hydraulic components providing powered motion for functions like recline and leg rest adjustment. These systems must meet stringent requirements for low-noise operation and high reliability. Electric actuators now dominate new aircraft programs, displacing legacy hydraulic systems due to lower weight. The business jets application segment drives demand for the most advanced, customized actuation solutions.
Airworthiness standards from the FAA in the United States and EASA in Europe mandate rigorous testing for seat and system safety, including crash dynamics and fire resistance. These regulations directly influence material selection and electrical system design for all actuation components. Future competitive success depends on a supplier's ability to integrate smart diagnostics and predictive health monitoring into their actuation platforms.
Market Dynamics
The primary structural force reshaping the market is the technological migration from hydraulic to lighter electromechanical systems. This shift is driven by airline objectives for fuel efficiency, lower maintenance, and enhanced premium cabin functionality on passenger aircraft.
Growth Catalysts
- Premium Cabin Investment:Airline focus on differentiating the first and business class passenger experience stimulates demand for quieter, smoother, and more complex multi-function actuation systems for lie-flat seats.
- Fuel Efficiency Initiatives:The push for lighter aircraft components to reduce fuel consumption and emissions directly benefits electromechanical actuators, which offer significant weight savings over legacy hydraulic systems.
- Business Jet Customization:Demand from the business jets segment for highly personalized and technologically advanced cabin interiors provides a key innovation driver for compact, high-performance, and ultra-reliable actuation solutions.
Market Restraints
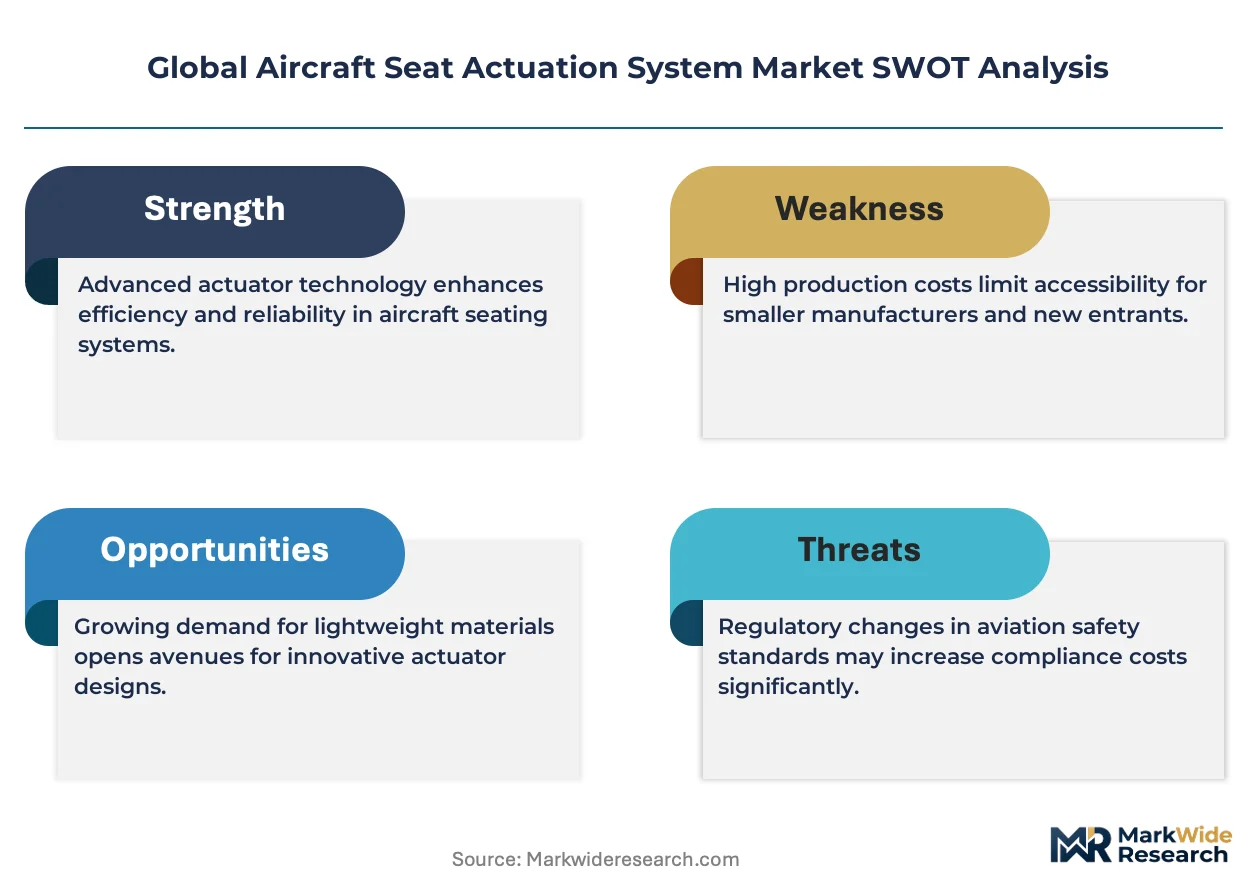
- Stringent Certification Hurdles:The extensive and costly airworthiness certification processes mandated by the FAA and EASA for all new electronic and mechanical seat components act as a significant barrier to entry.
- Legacy Fleet Integration Costs:Retrofitting modern electromechanical actuation systems into older aircraft designed for hydraulic or pneumatic power is often cost-prohibitive, slowing adoption in the aftermarket segment.
- Specialized Material Sourcing:Supply chain dependencies on a limited number of suppliers for high-strength, lightweight composites and specialty alloys for motor components can create production bottlenecks and price volatility.
Strategic Opportunities
- Predictive Health Monitoring:Integrating smart sensors and diagnostic software offers a pathway to new service-based revenue models, allowing suppliers to provide predictive maintenance analytics directly to airline customers.
- Urban Air Mobility (UAM):The development of eVTOL aircraft for urban transport creates a new application category for ultra-lightweight, power-efficient, and compact actuation systems for novel seating configurations.
- Advanced Composite Development:Continued R&D in carbon fiber and other composite materials for actuator housings and structural parts presents an opportunity to achieve further weight reductions and performance gains.
Industry Challenges
- Software Integration Complexity:Ensuring the seamless and cyber-secure integration of actuator control software with disparate aircraft cabin management systems and avionics platforms remains a persistent engineering challenge for suppliers.
- Talent Scarcity:A shortage of engineers with combined expertise in mechanical engineering, power electronics, and embedded software development constrains the pace of new product development across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Seat Actuation System Market |
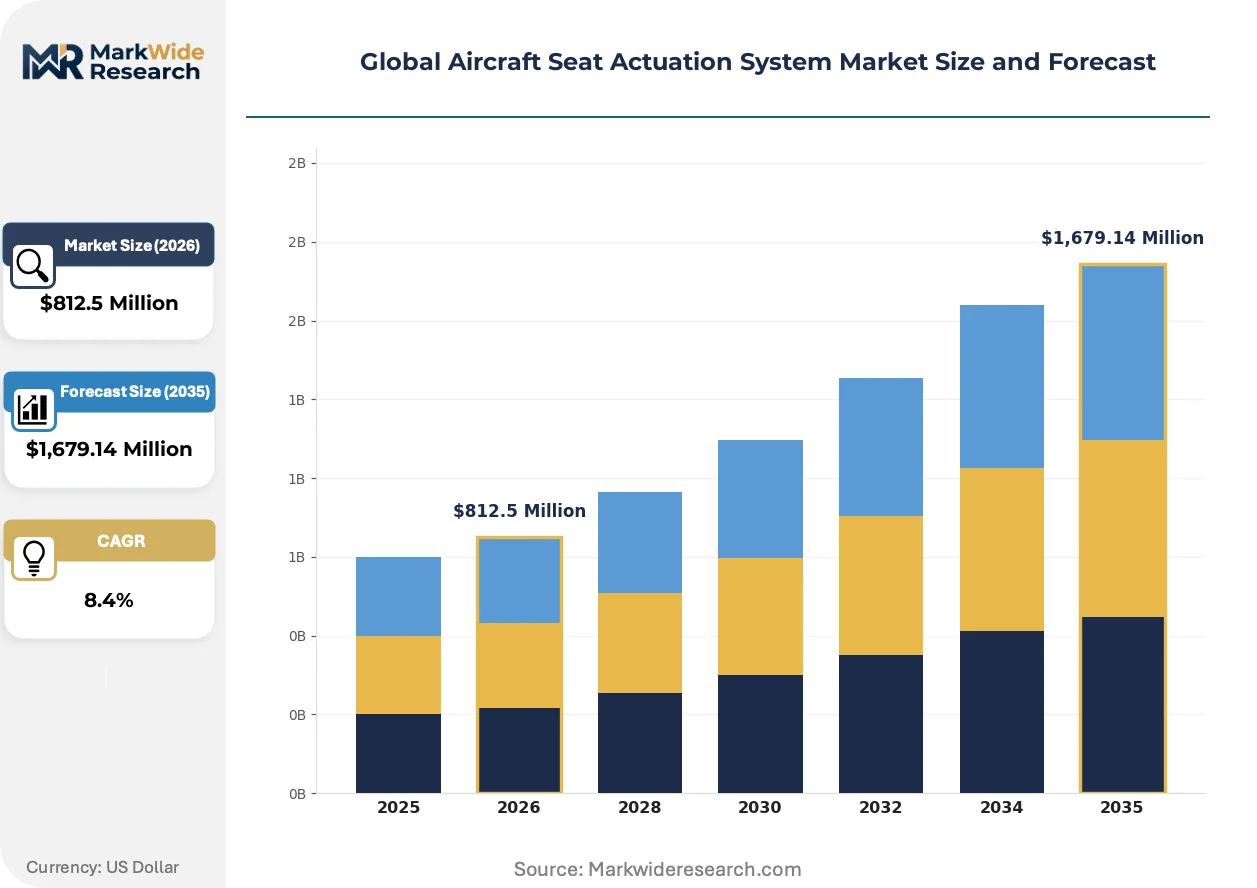
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,679.14 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators Technology: Linear Actuation, Rotary Actuation, Electromechanical, Electrohydraulic, Manual Application: Passenger Aircraft, Cargo Aircraft, Business Jets, Helicopters, Military Aircraft End User: OEMs, MRO Providers, Airlines, Leasing Companies, Aviation Retrofitters |
| Companies Covered | Moog Inc., RTX, Astronics Corporation, SAFRAN, Honeywell International Inc., Bühler Motor GmbH, ITT INC., NOOK Industries, INC., Crane Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Seat Actuation System Market Strategic Shifts & Innovations
A fundamental shift toward intelligent, networked systems defines the current product evolution cycle. This transition moves beyond simple mechanical motion to encompass data-driven performance, integrated diagnostics, and enhanced cybersecurity, altering the core value proposition of actuation platforms.
Integrated smart actuators now combine the motor, control electronics, and position sensors into a single, compact unit. This technology is being adopted rapidly in new-build wide-body and business jet programs to simplify installation and reduce wiring complexity. This integration of functions into a single module is decomposing the traditional architecture of separate motor, gearbox, and control units, creating a line-replaceable unit.
Heightened regulatory scrutiny on aircraft cybersecurity directly impacts actuator design. Mandates from the FAA and EASA, such as guidance found in DO-326A, require robust protection for any system connected to the aircraft network. This is forcing manufacturers to embed cybersecurity features into the firmware of their actuators, particularly for systems that can be controlled via passenger-facing interfaces or cabin crew panels.
Airline procurement behavior is evolving toward sourcing complete, pre-certified seating systems from large-scale integrators. This model disrupts the traditional channel where airlines might specify components from specialized actuator suppliers. The preference for a single-supplier solution for an entire cabin section is most visible in the procurement cycles for new wide-body aircraft in the United States and France.
Global Aircraft Seat Actuation System Market Segmentation
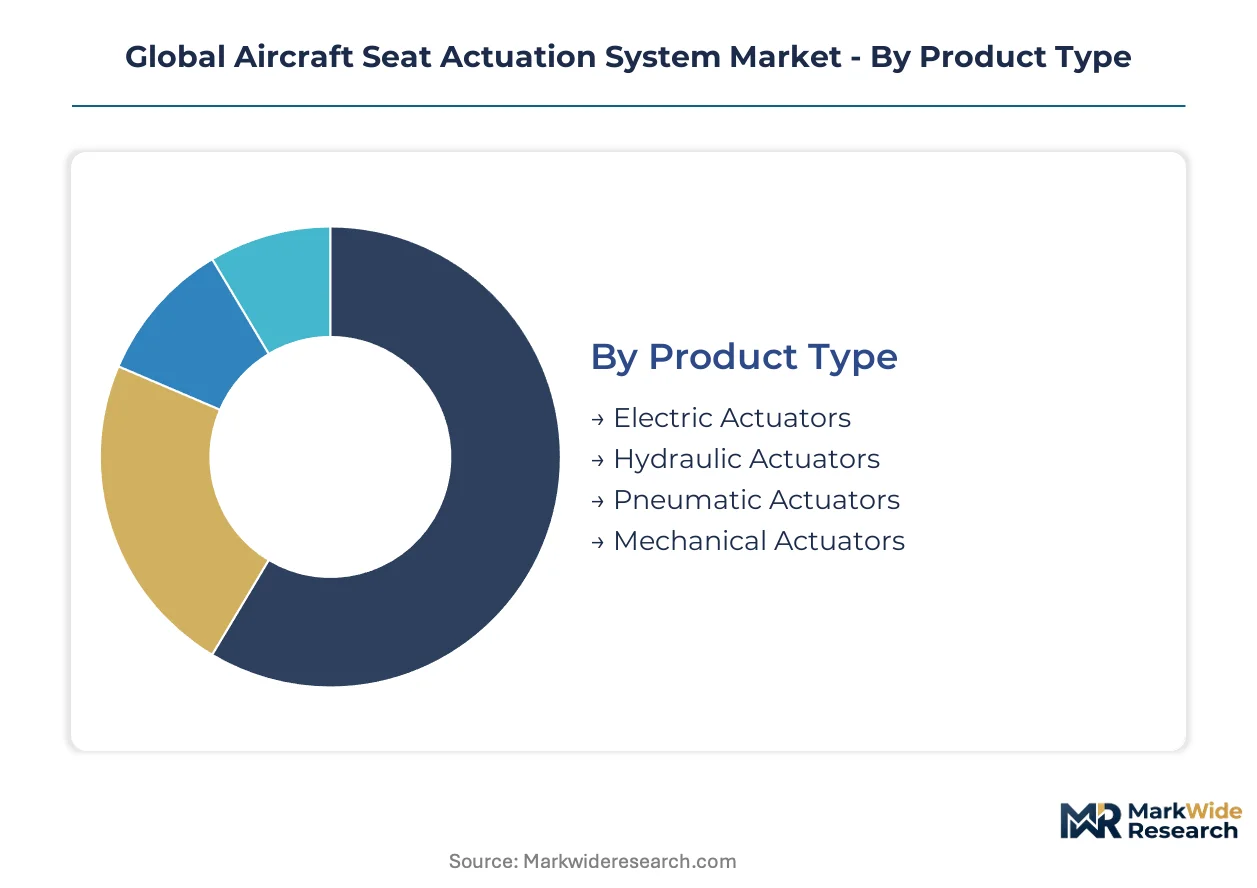
The aircraft seat actuation system market is segmented to reflect the diverse technological approaches and end-use applications defining its structure. Understanding these distinct segments provides clarity on where innovation is concentrating and how regulatory frameworks influence product development and adoption across the aerospace industry.
Product Type:
Airworthiness standards from authorities like the FAA and EASA significantly differentiate product type requirements, particularly concerning safety and reliability in passenger environments.
- Electric Actuators:These systems utilize electric motors and gearboxes to provide motion, offering precise control and significant weight savings over hydraulic alternatives. Demand concentrates in new-build wide-body aircraft programs in the United States, driven by airline mandates for improved fuel efficiency.
- Hydraulic Actuators:Employing pressurized fluid to generate force, these actuators are known for their high power density and robust performance in heavy-duty applications. Their presence is still strong in legacy aircraft fleets, particularly in older passenger aircraft where retrofit costs for electric systems are prohibitive.
- Pneumatic Actuators:These components operate using compressed air, offering a simple and lightweight solution for certain non-critical seat adjustments. Their use is often confined to specific, less complex functions within economy class seating.
- Mechanical Actuators:Relying on manual input or simple linkages, mechanical systems offer a cost-effective and inherently reliable solution for basic seat functions. These are typically found in lower-cost seating configurations or as backup systems.
Established volume favors Hydraulic Actuators; emerging adoption favors Electric Actuators.
Technology:
The application scope of various technologies determines their suitability for different aircraft types and seating configurations, influencing design complexity and certification pathways.
- Electromechanical:This technology integrates electric motors, control electronics, and mechanical components to provide precise and quiet motion, widely adopted in premium cabin seats. OEMs in France are increasingly integrating these systems for advanced lie-flat designs.
- Electrohydraulic:Combining electrical control with hydraulic power, these systems offer a balance of high force capability and controlled movement, suitable for specialized heavy-duty applications. This technology finds niche use where high power density is paramount without full electrification.
- Linear Actuation:These systems provide straight-line motion, essential for recline, leg rest extension, and other translational movements within aircraft seats. Linear actuators form the backbone of most adjustable seat mechanisms.
- Rotary Actuation:Generating rotational motion, these actuators are used for functions such as swiveling seats or adjusting headrest angles. Rotary actuation is critical for complex, multi-axis seat movements in business jet interiors.
- Manual:These systems depend on direct human input for adjustment, offering simplicity and reliability without requiring electrical power or complex controls. Manual actuation remains prevalent in standard economy class seating.
Rapid adoption is evident in Electromechanical technology, while Linear Actuation maintains a foundational presence.
Application:
Volume contribution from different aircraft segments significantly shapes demand for specific actuation system characteristics, driving innovation in tailored solutions.
- Passenger Aircraft:This segment includes commercial airliners, which represent the largest volume market for seat actuation systems, particularly for premium and business class seating. Airline investment in passenger comfort drives demand for advanced, multi-function systems.
- Business Jets:Characterized by high customization and stringent performance requirements, this segment demands compact, high-performance, and ultra-reliable actuation solutions for luxurious cabin interiors. Demand for unique configurations is strong from manufacturers in the United States.
- Cargo Aircraft:While less focused on passenger comfort, cargo aircraft sometimes utilize actuation systems for crew seating or specialized equipment. The requirements here emphasize durability and robustness over intricate functionality.
- Helicopters:Actuation systems in helicopters address specific needs for pilot and co-pilot seating, often requiring vibration damping and robust design. Custom solutions are frequently sought for specialized rotary-wing missions.
- Military Aircraft:This segment requires highly durable, reliable, and often custom-designed actuation systems for pilot and crew seating, frequently incorporating crashworthiness and ejection capabilities. Procurement cycles are influenced by defense budgets and mission requirements.
Demand for Business Jets is driven by specific requirements, contrasting with the broad utility of Passenger Aircraft.
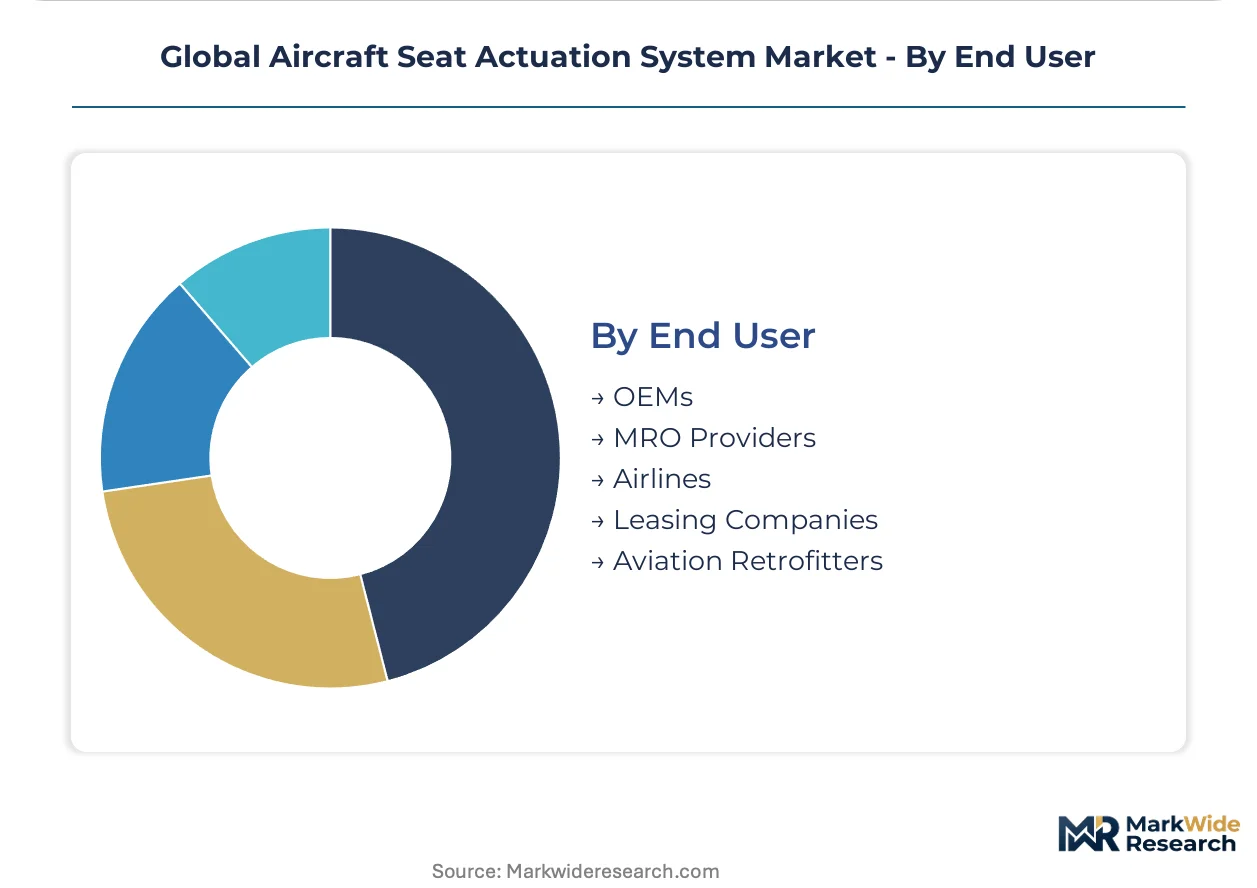
End User:
Procurement patterns among various end users dictate supply chain dynamics and influence the types of services and products offered by actuation system manufacturers.
- OEMs:Original Equipment Manufacturers integrate actuation systems into new aircraft seats and full cabin interiors during the manufacturing process. These customers prioritize long-term supply agreements and design integration support.
- MRO Providers:Maintenance, Repair, and Overhaul providers service existing aircraft fleets, requiring replacement parts and upgrade solutions for actuation systems. MROs in Europe support airlines seeking to extend the life of their cabin components.
- Airlines:Airlines directly procure actuation systems for cabin retrofits or specify them for new aircraft deliveries, focusing on reliability, maintainability, and passenger experience. Their procurement decisions are often tied to fleet modernization initiatives.
- Leasing Companies:These entities own and lease aircraft to airlines, influencing component selection based on asset value and ease of maintenance. Leasing companies often seek standardized, reliable solutions.
- Aviation Retrofitters:Specialists in upgrading and modifying existing aircraft cabins, these firms integrate new actuation systems into older airframes. Retrofitters require adaptable and certified solutions for diverse aircraft types.
The market structure favors OEMs for new systems, while MRO Providers remain critical for fleet sustainment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption mix for aircraft seat actuation systems shows distinct regional preferences, with advanced electromechanical systems dominating new programs in aerospace manufacturing hubs. Legacy hydraulic systems maintain a presence in older fleets across various geographies. This divergence influences demand patterns for both new installations and MRO activities.
United States
Demand for advanced electromechanical actuators stems from robust passenger aircraft and business jet production. FAA airworthiness standards mandate rigorous testing for seat and system safety, influencing material selection. The Seattle area and Wichita, Kansas, represent key aerospace manufacturing clusters driving innovation in actuation solutions.
France
OEMs in France drive significant demand for sophisticated electromechanical systems, especially for premium cabin lie-flat designs. EASA regulations, alongside national guidelines, ensure stringent certification processes for all new actuation components. Toulouse, a major aerospace center, concentrates R&D efforts for integrating smart diagnostics into actuation platforms.
Germany
The German market for aircraft seat actuation systems benefits from strong automotive engineering synergies, particularly in precision motor manufacturing. European CE marking and EASA standards influence the design and certification of high-performance miniature motors. Munich and Hamburg host significant aerospace suppliers, fostering development of compact, high-performance actuation solutions.
United Kingdom
UK aerospace companies focus on specialized actuation systems for both commercial and military aircraft applications, emphasizing reliability. The UK Civil Aviation Authority (CAA) and EASA regulations govern safety and performance requirements for all cabin components. Bristol and Derby are critical aerospace engineering hubs, contributing to advanced motion control system development.
Japan
Japanese aerospace manufacturers seek ultra-lightweight and power-efficient actuation systems for next-generation aircraft programs. The Japan Civil Aviation Bureau (JCAB) mandates strict safety and performance standards for all aircraft interior systems. Nagoya and Tokyo host key aerospace clusters, concentrating efforts on advanced composite development for actuator housings.
Global Aircraft Seat Actuation System Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the aircraft seat actuation system market. The market exhibits a tiered structure, with large-scale integrators offering complete seating solutions alongside specialized component suppliers. Strategic archetypes include full-system providers, high-performance motor specialists, and advanced motion control developers. Companies pursue strategic partnerships to broaden their portfolios and engage in technology licensing to enhance product capabilities.
Within the integrated leaders' segment, companies like SAFRAN and RTX leverage extensive portfolios to provide complete seating solutions to airlines. These firms often offer pre-certified systems for new wide-body aircraft programs. Bühler Motor GmbH exemplifies a specialist component supplier, differentiating through expertise in high-performance miniature motors for diverse applications. Moog Inc. occupies a position as a provider of advanced motion control systems for both commercial and military aircraft applications, emphasizing reliability and precision. These companies represent key players in driving innovation and market evolution within their respective niches.
| Leading Market Players |
|---|
| Moog Inc. |
| RTX |
| Astronics Corporation |
| SAFRAN |
| Honeywell International Inc. |
| Bühler Motor GmbH |
| ITT INC. |
| NOOK Industries, INC. |
| Crane Company |
| Others |
Cost & Logistics Intelligence
Airworthiness standards from the FAA and EASA gate component supply qualification, directly influencing price differentiation across critical safety-related systems.
Pricing Analysis
Long-term contract-based agreements define procurement for aircraft seat actuation systems, particularly for new aircraft programs. Price differentiation stems from the stringent certification level required by regulators and the high degree of customization for business jet interiors. Pricing pressure from airlines seeking fuel efficiency drives cost compression in the electromechanical segment. OEMs demonstrate lower price sensitivity for mission-critical components in new designs, while MRO providers and airlines focused on retrofits exhibit higher price sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume components, while custom solutions for business jets often require strategic stockpiles of specialized parts. Geographic supply concentration exists in the United States, France, and Germany due to established aerospace manufacturing. Raw material dependencies include high-strength lightweight composites and specialty alloys for motor components. Single-source vulnerability for advanced miniature motors presents a structural supply chain risk. Distribution runs through direct sales channels to OEMs and specialized distributors for MRO providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing high-growth disruption, driven by the technological migration from hydraulic to lighter electromechanical actuation systems.
For Market Incumbents:Consolidate core electromechanical actuator technologies to counter threats from specialized component suppliers. Secure long-term supply agreements for specialized materials, mitigating supply chain bottlenecks. Invest in advanced motion control R&D to maintain a competitive edge against emerging entrants with focused composite material research. This also strengthens their position against the threat of new entrants leveraging niche material science.
For New Entrants and Emerging Players:Differentiate on advanced composite material integration for ultra-lightweight actuation systems. Target urban air mobility (UAM) and eVTOL aircraft, which represent a new application category. The most penetrable segment involves compact, power-efficient solutions for novel seating configurations. Partnerships with emerging airframe manufacturers offer a key go-to-market angle.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across premium cabin actuation systems due to complex R&D and certification requirements. Long-term viability rests on suppliers integrating smart diagnostics and predictive health monitoring capabilities. Specialized firms with expertise in embedded software and miniature motor technology represent an attractive acquisition target archetype. Airline investment in predictive health monitoring services serves as a crucial signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Predictive Health Monitoring | This enhances service-based revenue models for airline customers. |
| Develop Advanced Composite Actuator Housings | This achieves further weight reductions for fuel-efficient aircraft programs. |
| Secure Specialized Material Supply | This mitigates production bottlenecks for high-performance components. |
| Expand Electromechanical System Integration | This supports new-build wide-body aircraft programs in the United States. |
| Foster Cybersecurity Expertise | This ensures compliance with FAA and EASA mandates for networked systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of aerospace manufacturer reports, regulatory filings, and trade publications. Primary interviews included R&D directors, procurement managers at OEMs, MRO service leads, and airline cabin design specialists. This approach combines bottom-up insights with top-down market validation through triangulation.
Segmentation dimensions modeled include product type, technology, application, end user, and key regional markets. The analytical framework projects market growth across the analysis window, considering historical trends and projected technological adoption. Compound annual growth rates derive from these trends and insights. Fuel efficiency targets and new aircraft program schedules serve as key forecast inputs.
Forecasts assume regulatory continuity in FAA and EASA regimes; material policy shifts would require re-modeling. These projections reflect current assumptions regarding technological advancements and market dynamics. Supply chain disruptions or significant shifts in airline investment priorities pose specific revision risks. Revision becomes warranted when these conditions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market