
 Commercial Aircraft Aftermarket Parts Market | 2026-2036
Commercial Aircraft Aftermarket Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Aftermarket Parts Market Analysis
Modular MRO service bundling is recalibrating how airlines procure aftermarket components, shifting discrete part purchases toward integrated maintenance contracts. General Electric Company leverages its captive engine overhaul network to lock in long-term aftermarket revenue streams. Honeywell International Inc. sustains competitive position through avionics upgrade programs that extend platform life cycles. AAR Corp. dominates the independent distribution channel with logistics infrastructure spanning multiple FAA-certified repair stations.
Commercial aircraft aftermarket parts comprise replacement components, refurbished assemblies, and PMA-certified alternatives manufactured to OEM or regulator-approved specifications for airframe, engine, and systems maintenance. These parts restore airworthiness, extend operational life, and maintain dispatch reliability across turbine-powered fixed-wing aircraft. Engine components command the largest value pool within the component type dimension, while MRO providers represent the fastest-growing end user segment as third-party maintenance outsourcing accelerates. The service type structure tilts toward overhaul rather than line maintenance, reflecting deeper technical content and higher margin capture per shop visit.
FAA airworthiness directives, EASA Part 145 certification, and OEM intellectual property enforcement collectively shape parts eligibility and market access for non-OEM suppliers. FAA PMA approval pathways determine which aftermarket manufacturers can compete for component replacements on US-registered aircraft. Stakeholders must monitor evolving bilateral aviation safety agreements between regulators, as mutual recognition shifts alter competitive boundaries for PMA and used serviceable material flows across jurisdictions.
Market Dynamics
Modular MRO service bundling is compressing discrete parts procurement into integrated maintenance contracts, forcing distributors to restructure around long-term airline partnerships rather than spot-market transactions.
Growth Catalysts
- FAA PMA Pathway Expansion:Streamlined Parts Manufacturer Approval processes under FAA Order 8110.42D are accelerating PMA-certified component eligibility for narrowbody fleets.
- Low-Cost Carrier MRO Internalization:Budget airlines across Southeast Asia and Latin America are building captive repair stations to capture margin previously flowing to third-party providers.
- Used Serviceable Material Circulation:Tear-down sourcing from retired aircraft in Arizona and California boneyards is creating alternative supply channels for aging fleet support.
Market Restraints
- Titanium and Nickel Superalloy Volatility:Engine component manufacturers face input cost swings from aerospace-grade alloy spot markets concentrated in Russian and Chinese supply.
- OEM Intellectual Property Enforcement:Boeing and Airbus patent litigation against PMA producers creates litigation risk for non-OEM suppliers entering proprietary component categories.
- EASA Part 21J Design Organization Burden:European aftermarket entrants face elevated certification costs from design approval requirements that OEMs already amortize across production volume.
Strategic Opportunities
- Indian MRO Infrastructure Gap:India's nascent domestic repair station network under DGCA oversight offers first-mover positioning as fleet density builds in Mumbai and Delhi corridors.
- Avionics Upgrade Cycles:Mandated ADS-B Out compliance is forcing legacy fleet retrofits, creating sustained demand for glass cockpit component replacements.
- Blockchain Provenance Tracking:Distributed ledger verification of part pedigree is integrating with existing inventory management systems to reduce fraud exposure in used material markets.
Industry Challenges
- Airframe Mechanic Shortage:FAA-certified A&P technician pipelines in the United States are failing to replace retiring workforce cohorts, constraining shop visit throughput.
- Dual-Release Certification Complexity:Simultaneous FAA-EASA approval requirements for cross-registered fleets extend time-to-market for new PMA introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Aftermarket Parts Market |
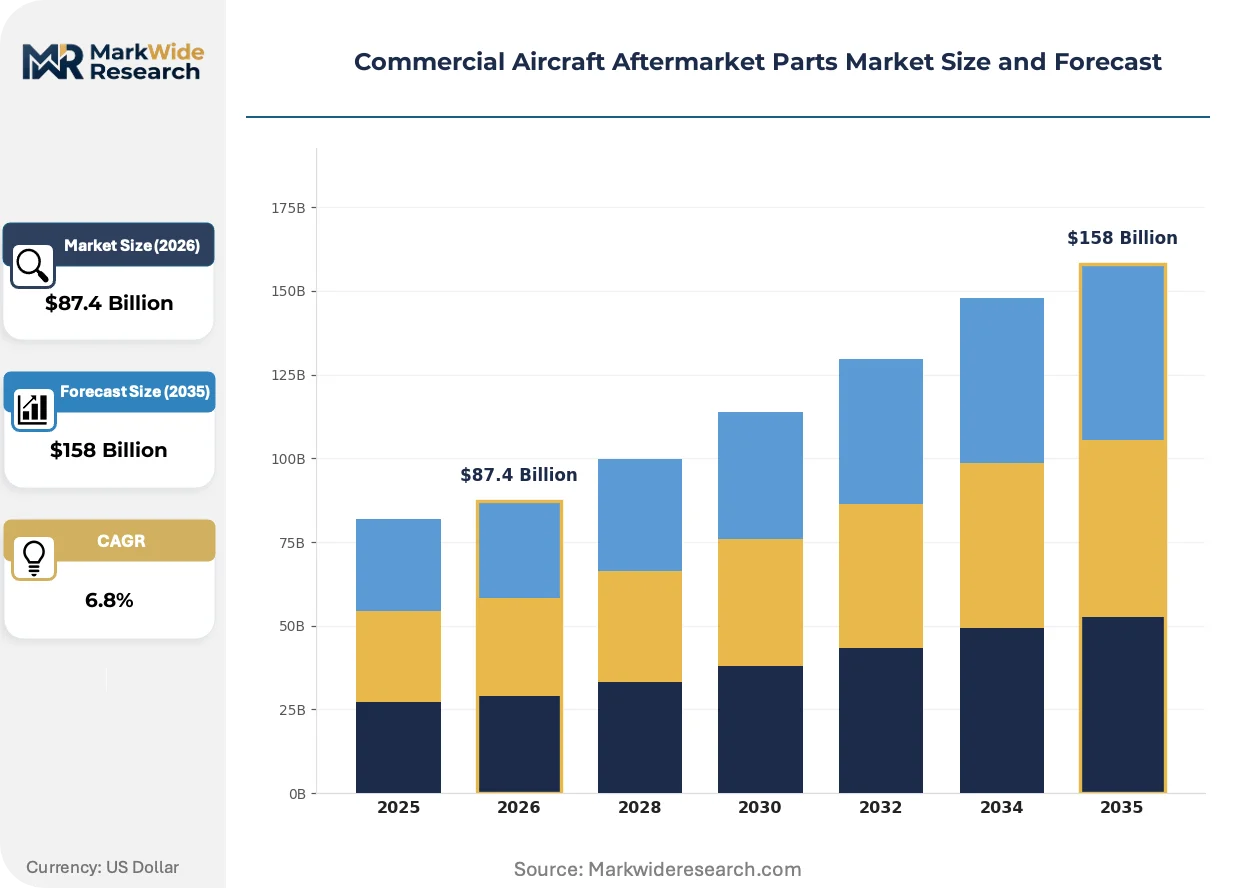
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Engines, Landing Gear, Avionics, Fuel Systems Service Type: Maintenance, Repair, Overhaul, Refurbishment Distribution Channel: OEM, Independent Distributors, Online Retail, Aftermarket Providers End User: Airlines, Cargo Operators, MRO Providers, Private Operators |
| Companies Covered | General Electric Company, AAR Corp., Honeywell International Inc., Moog Inc., Lufthansa Technik, RTX Corporation, A J Walter Aviation Ltd., Park-Hannifin Corporation, Safran SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Aftermarket Parts Market Emerging Trajectories
Additive manufacturing is penetrating engine component repair workflows, compressing lead times for legacy parts no longer in active production. This shift is altering supplier economics across the aftermarket value chain.
Predictive maintenance algorithms are integrating sensor data from engine health monitoring units with MRO scheduling systems. Airlines with dense narrowbody operations are adopting these platforms fastest. The technology is integrating flight-hour data with component life tracking to optimize shop visit timing and reduce unscheduled removals.
EASA's expanding Part 145 environmental audit requirements are mandating solvent reduction and waste-stream documentation across European repair stations. Shops in Germany and France are retrofitting aqueous cleaning systems to maintain certification. Engine overhaul facilities face the steepest compliance costs given their chemical process intensity.
Airline procurement teams are consolidating supplier panels and demanding vendor-managed inventory programs with guaranteed availability clauses. Independent distributors are responding with consignment stocking at airline hub locations. This pattern is most visible among US network carriers restructuring post-pandemic supply relationships.
Commercial Aircraft Aftermarket Parts Market Segmentation
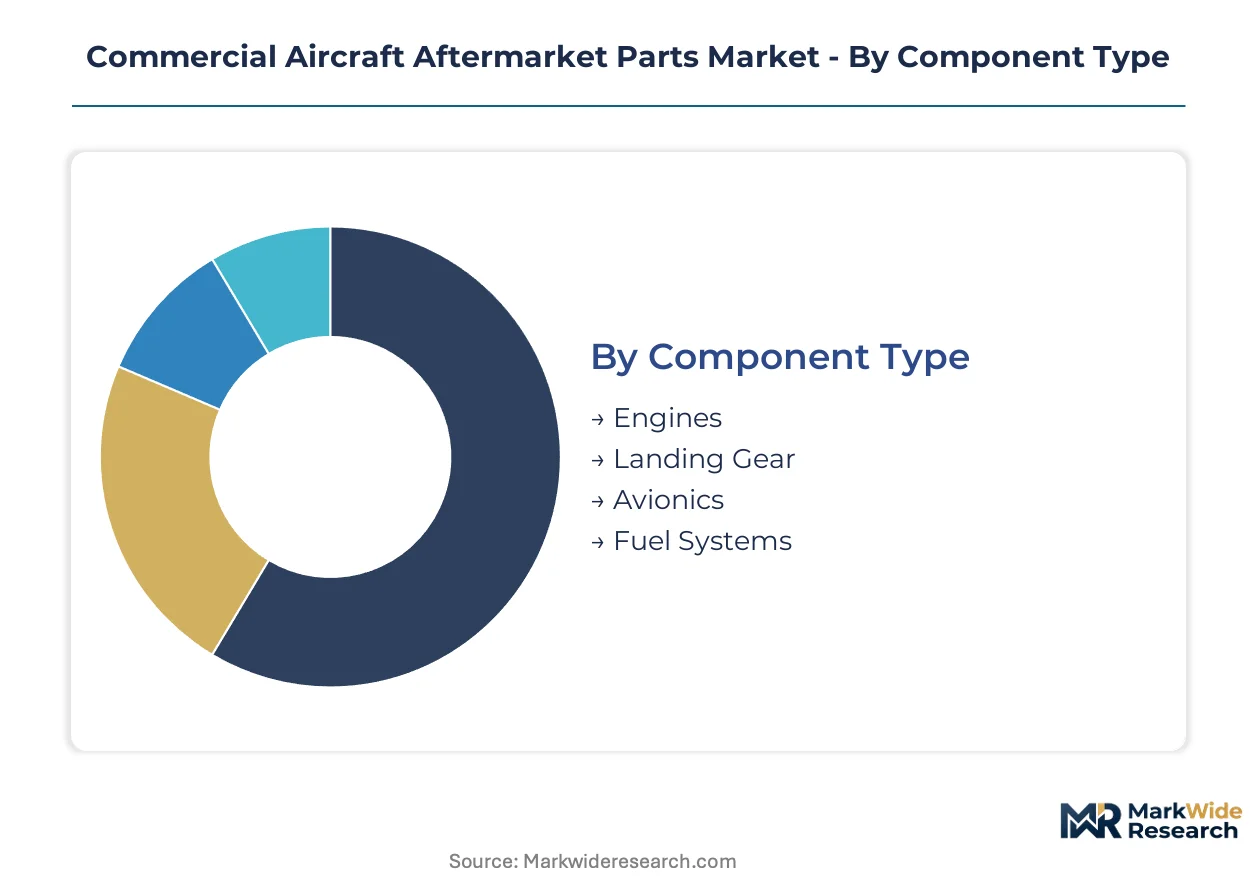
Aftermarket parts procurement varies sharply across aircraft systems, with each component category commanding distinct technical specifications, regulatory pathways, and replacement cadences. Understanding these dimensional splits clarifies where margin concentrates and which upgrade cycles drive near-term purchasing decisions.
Component Type:
Engine and avionics upgrade cycles dominate capital allocation as airlines balance fuel efficiency mandates against airframe longevity constraints.
- Engines:Turbine blades, combustors, and high-pressure compressors manufactured from nickel superalloys and titanium aluminides constitute the highest-value replacement category. Demand clusters around Dallas-Fort Worth and Atlanta maintenance hubs serving aging narrowbody fleets, with FAA airworthiness directives accelerating shop visit frequency for specific thrust variants.
- Avionics:Flight management systems, weather radar, and communication suites require continuous software-hardware refresh cycles. European carriers under EASA oversight are prioritizing ADS-B Out and PBN compliance retrofits, compressing procurement timelines for glass cockpit component bundles.
- Landing Gear:Oleo struts, brake assemblies, and retraction actuators sourced from Arizona boneyard teardown operations.
- Fuel Systems:Pumps, valves, and inerting equipment tied to FAA ignition source prevention mandates.
Engines sit at the top of the volume ranking, with avionics climbing the fastest.
Service Type:
Cost tier differentiation separates routine line maintenance from capital-intensive overhaul events that capture multi-year contractual commitments.
- Overhaul:Complete disassembly, inspection, and restoration of engine modules and landing gear assemblies to zero-time condition. German and French repair stations under EASA Part 145 face elevated environmental compliance costs for chemical processing, reshaping competitive economics for European-based work.
- Repair:Component-level restoration addressing specific defects without full module replacement. Southeast Asian low-cost carriers are internalizing this capability at Kuala Lumpur and Jakarta facilities to capture margin from third-party providers.
- Maintenance:Scheduled inspection and preventive servicing per manufacturer maintenance planning documents.
- Refurbishment:Cosmetic and functional renewal of cabin interiors and secondary systems.
Overhaul commands the steepest pricing tier, while repair gains share fastest among cost-conscious operators.
Distribution Channel:
Supply concentration among authorized channels is fragmenting as airlines diversify procurement risk across multiple sourcing pathways.
- OEM:Factory-original components backed by design authority certification and warranty coverage. Boeing and Airbus leverage proprietary technical data to maintain price positioning on proprietary airframe components.
- Independent Distributors:FAA-certified parts brokers and inventory aggregators operating consignment programs at airline hub locations. AAR Corp. and similar operators dominate US domestic logistics infrastructure.
- Aftermarket Providers:PMA-certified manufacturers and used serviceable material specialists.
- Online Retail:Digital procurement platforms for non-critical consumables and standard hardware.
OEM retains premium positioning on proprietary systems, with independent distributors expanding share fastest through vendor-managed inventory contracts.
End User:
Customer type determines contract structure, with fleet scale and regulatory exposure shaping procurement sophistication.
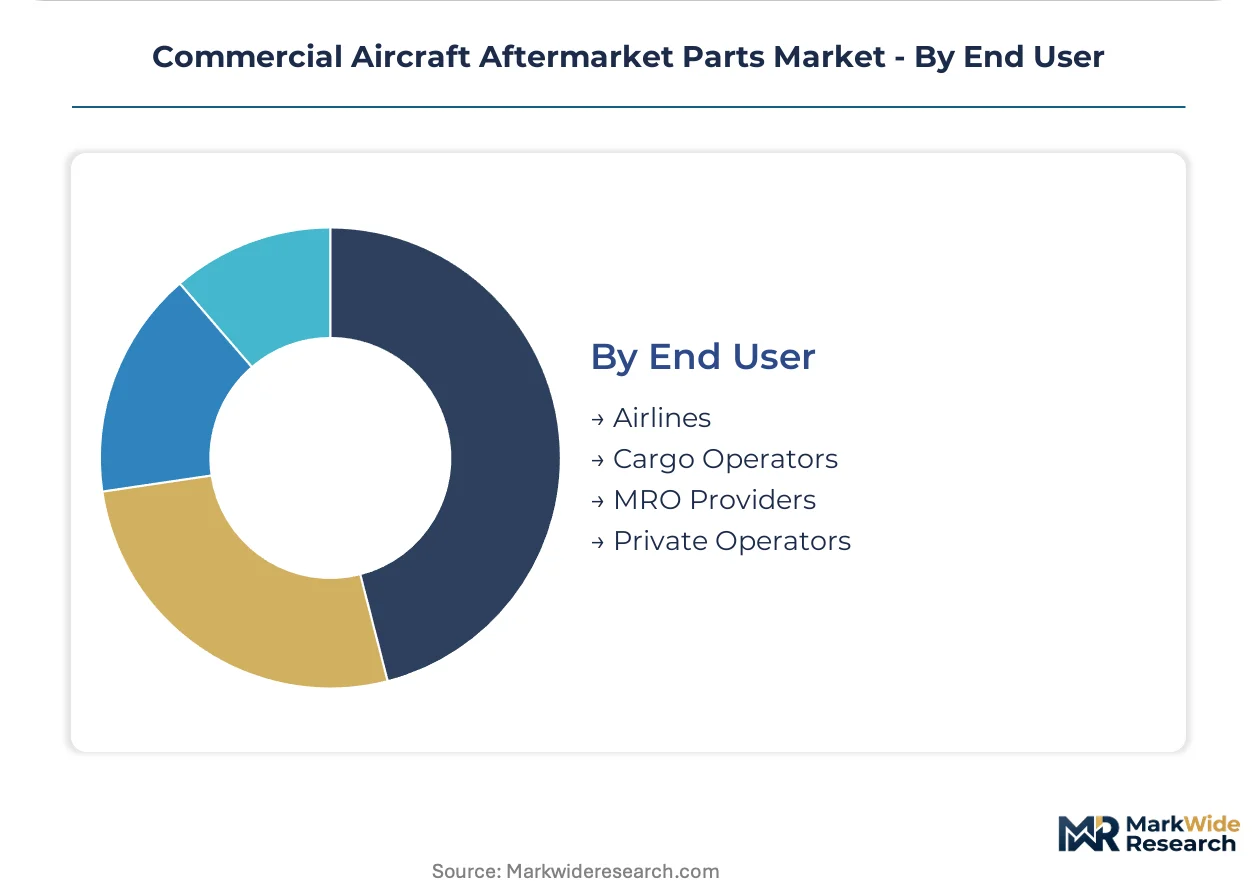
- MRO Providers:Third-party maintenance specialists serving multiple airline customers under long-term service agreements. These operators are consolidating supplier panels and demanding guaranteed availability clauses for high-rotability components.
- Airlines:Network and low-cost carriers with captive engineering departments managing direct parts procurement. US majors are restructuring post-pandemic supply relationships toward integrated service bundling.
- Cargo Operators:Express freight and dedicated freighter fleets with distinct utilization patterns and component life profiles.
- Private Operators:Corporate and charter fleets with lower volume but higher service expectations.
MRO Providers anchor procurement volume, with Airlines restructuring fastest toward outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation maintenance infrastructure traces its modern lineage to post-war US military demobilization, when surplus aircraft and trained mechanics seeded civilian MRO networks. Today's aftermarket parts distribution reflects this heritage, with regulatory frameworks and fleet density shaping geographic demand concentration.
United States
Aging narrowbody fleets at American, Southwest, and Delta drive sustained component replacement cycles, particularly for CFM56 and V2500 engine variants. FAA airworthiness directives on fan blade inspections and fuel tank system integrity accelerate procurement timelines for safety-critical parts. The Dallas-Fort Worth and Atlanta maintenance corridors concentrate heavy overhaul capacity, with Arizona boneyards supplying used serviceable material for cost-conscious operators.
Germany
Lufthansa Technik's captive MRO network anchors European engine overhaul demand, serving Lufthansa Group and third-party airline customers across thrust categories. EASA Part 145 environmental audits mandate solvent reduction and waste-stream documentation, elevating compliance costs for chemical-intensive repair processes. The Hamburg and Frankfurt maintenance clusters retrofit aqueous cleaning systems to maintain certification under tightening ecological standards.
China
Domestic fleet expansion by China Southern, Air China, and China Eastern generates aftermarket volume for LEAP-1A and PW1100G components as initial warranty periods expire. CAAC harmonization with FAA and EASA certification standards facilitates PMA part eligibility for Chinese-registered aircraft. The Tianjin and Guangzhou MRO zones attract joint ventures between state airlines and Western OEMs to localize technical capabilities.
United Arab Emirates
Emirates and Etihad operate superjumbo fleets with distinct component life profiles, creating specialized demand for A380 and 777 aftermarket support. GCAA regulatory alignment with EASA standards enables dual-release certification for parts flowing to European-registered aircraft. Dubai's Al Maktoum maintenance cluster consolidates third-party MRO services for carriers across Africa, South Asia, and the Middle East.
India
IndiGo and Air India's narrowbody density builds fleet-scale maintenance demand, yet domestic repair station capacity under DGCA oversight remains underdeveloped. The government's MRO policy reforms and GST rate reductions aim to retain maintenance spend currently flowing to Singapore and Sri Lanka. Mumbai and Delhi corridors offer first-mover positioning for independent distributors establishing consignment inventory programs.
Commercial Aircraft Aftermarket Parts Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the certification tier dimension, with OEM-authorized channels commanding price positioning against PMA and used material alternatives. The vendor base stratifies into three functional tiers: design-authority holders with proprietary technical data, independent distributors with logistics infrastructure, and PMA manufacturers competing on cost. Consolidation pressure runs through long-term service agreement demands from airline procurement teams, while technology licensing partnerships enable aftermarket entrants to bypass R&D amortization.
Within the OEM-anchored tier, General Electric Company and Honeywell International Inc. represent design-authority incumbents leveraging captive overhaul networks to lock in recurring aftermarket revenue. AAR Corp. occupies a position among independent distributors, exemplifying the logistics-intensive archetype with FAA-certified repair station infrastructure and consignment programs at airline hub locations. These three entities span the competitive spectrum from proprietary component manufacturing to third-party distribution, illustrating how margin capture varies across the value chain.
| Leading Market Players |
|---|
| General Electric Company |
| AAR Corp. |
| Honeywell International Inc. |
| Moog Inc. |
| Lufthansa Technik |
| RTX Corporation |
| A J Walter Aviation Ltd. |
| Park-Hannifin Corporation |
| Safran SA |
| Others |
Supply Flow & Price Mechanics
Airline procurement consolidation into long-term service agreements is forcing distributors to abandon spot-market transactions and absorb inventory risk through consignment programs, compressing margins on standard hardware while premium engine components retain pricing power.
Pricing Analysis
Three-tier pricing structure across OEM-certified, PMA-approved, and used serviceable material levels dominates aftermarket parts procurement. Price differentiation hinges on certification grade—FAA PMA versus factory-original design authority—and volume scale commitments from MRO providers. Cost compression in standard consumables is intensifying because low-cost carriers are internalizing repair capabilities and sourcing directly from teardown operations. Narrowbody fleet operators exhibit the highest price sensitivity, while superjumbo operators maintain lowest sensitivity due to limited alternative sourcing for proprietary A380 and 777 components.
Supply Chain Analysis
Direct-to-OEM channels handle proprietary airframe component demand, while independent distributors manage high-rotability inventory through hub-located consignment programs. Manufacturing concentration spans the United States, Germany, and China for precision-engineered turbine components. Raw material sourcing draws from Russian and Chinese spot markets for aerospace-grade titanium and nickel superalloys. Single-source vulnerability around specialty alloy supply creates exposure to geopolitical disruption. Distribution runs through FAA-certified repair station networks with EASA dual-release capabilities for cross-registered fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where maintenance spend flows from India's underdeveloped DGCA-certified repair infrastructure toward Singapore and Sri Lanka, exploiting labor cost differentials and faster turnaround times.
For Market Incumbents: Deepen captive overhaul network control to lock in long-term airline service agreements before low-cost carriers complete MRO internalization. Expand FAA-EASA dual-release certification coverage to capture cross-registered fleet volume. Prioritize titanium superalloy supply contracts to hedge against Russian and Chinese raw material volatility. For New Entrants and Emerging Players: Begin with avionics component PMA pathways for aging narrowbody retrofits, where FAA Order 8110.42D streamlines approval timelines. India's nascent MRO corridor offers the most penetrable geography given government GST reforms and fleet density buildout. Pursue vendor-managed inventory contracts at Mumbai and Delhi hubs to establish logistics presence before incumbent consolidation hardens. For Investors and Strategic Acquirers: Asymmetric upside sits with independent distributors possessing FAA-certified repair station infrastructure and established airline consignment relationships. The five-to-ten year viability window favors platforms capable of integrating blockchain provenance tracking with legacy inventory systems. Monitor bilateral aviation safety agreement negotiations between FAA and CAAC as the inflection signal for PMA part eligibility expansion into Chinese-registered aircraft.| Strategic Initiative | Industry Significance |
|---|---|
| PMA Certification Pathway Expansion | FAA Order 8110.42D streamlines approval for narrowbody component alternatives, opening proprietary categories to non-OEM competition. |
| Vendor-Managed Inventory Programs | Consignment stocking at airline hub locations transfers inventory risk from carriers to distributors while securing long-term procurement relationships. |
| Dual-Release Certification Investment | Simultaneous FAA-EASA approval capabilities capture cross-registered fleet volume and reduce time-to-market for new part introductions. |
| Blockchain Provenance Integration | Distributed ledger verification reduces fraud exposure in used serviceable material markets and satisfies airline audit requirements. |
| Indian MRO Infrastructure Development | DGCA-certified repair station establishment in Mumbai and Delhi corridors captures maintenance spend currently flowing to Southeast Asian competitors. |
Methodological Framework
Multiple input streams — primary interviews with MRO procurement directors, airline fleet managers, and PMA manufacturer executives, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. FAA airworthiness directive databases, EASA certification registries, and customs import records for aerospace-grade alloys provided structural validation. Conversations with Lufthansa Technik, AAR Corp., and Honeywell International Inc. operational leadership informed service bundling trends and inventory management practices.
Data-stream reconciliation across component type, service tier, distribution channel, and end-user segmentation dimensions produced volume and value estimates across the projection horizon. CAGRs were derived from fleet age profiles, shop visit frequency models, and regulatory mandate compliance timelines. Engine overhaul cycle forecasting incorporated flight-hour utilization patterns from narrowbody versus widebody operations. Avionics upgrade demand modeling tracked ADS-B Out and PBN compliance deadlines under FAA and EASA oversight.
Several conditions sit outside the modeled scope, including unannounced bilateral aviation safety agreements, abrupt OEM patent litigation outcomes, and geopolitical disruption of Russian or Chinese titanium supply. Forecasts reflect assumptions about continued PMA pathway accessibility and stable alloy pricing. Periodic stress-testing of base assumptions is recommended given regulatory harmonization uncertainty and low-cost carrier MRO internalization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market