
 Military Ground Vehicle Actuators Market | 2026-2036
Military Ground Vehicle Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Military Ground Vehicle Actuators Market Foresight
The military ground vehicle actuators market is pivoting on a widening gap between precision electric systems for next-generation combat vehicles and legacy hydraulic units for refurbishment programs. Moog Inc. leverages its servo control heritage to dominate high-reliability electromechanical positions. Curtiss-Wright Corporation anchors its portfolio through nuclear-hardened actuator designs repurposed for armored ground applications. Parker Hannifin Corporation sustains hydraulic dominance in heavy artillery and main battle tank turret drives where load capacity remains paramount.
Military ground vehicle actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion for weapon stabilization, suspension articulation, and hatch operation, typically engineered to withstand shock loads exceeding 20g and temperature extremes from -40°C to +125°C. Electric actuators are displacing hydraulic alternatives in reconnaissance and unmanned platforms where stealth and energy efficiency reduce thermal and acoustic signatures. Servo technology leads in fire-control and targeting applications requiring sub-millimeter positional accuracy, while linear technology occupies the bulk of suspension and door actuation roles where cost constraints favor simpler architectures.
The US Department of Defense's MIL-STD-810 environmental testing protocols and the EU's CE marking requirements under the Machinery Directive constrain design choices for suppliers seeking transatlantic qualification. Germany's KBA and France's defense procurement agency enforce national security vetting that limits actuator sourcing to domestically cleared manufacturers. Stakeholders must monitor how NATO's standardization agreements for interchangeable components interact with each member's industrial base protection policies.
Market Dynamics
The electrification of military ground platforms is compressing actuator replacement cycles as NATO forces retire hydraulic turret drives in favor of electromechanical systems that meet stealth and thermal signature requirements.
Growth Catalysts
- EU Green Deal defense procurement protocols:The EU's emissions benchmarks for military equipment are mandating electric actuators in new armored vehicle programs across member states.
- Main battle tank modernization waves:Germany's KBA certification requirements for turret stabilization systems are accelerating electromechanical retrofits in legacy Leopard fleets.
- Silicon carbide power electronics:Wide-bandgap semiconductors are enabling compact high-torque electric actuators that operate at 125°C ambient without thermal derating.
Market Restraints
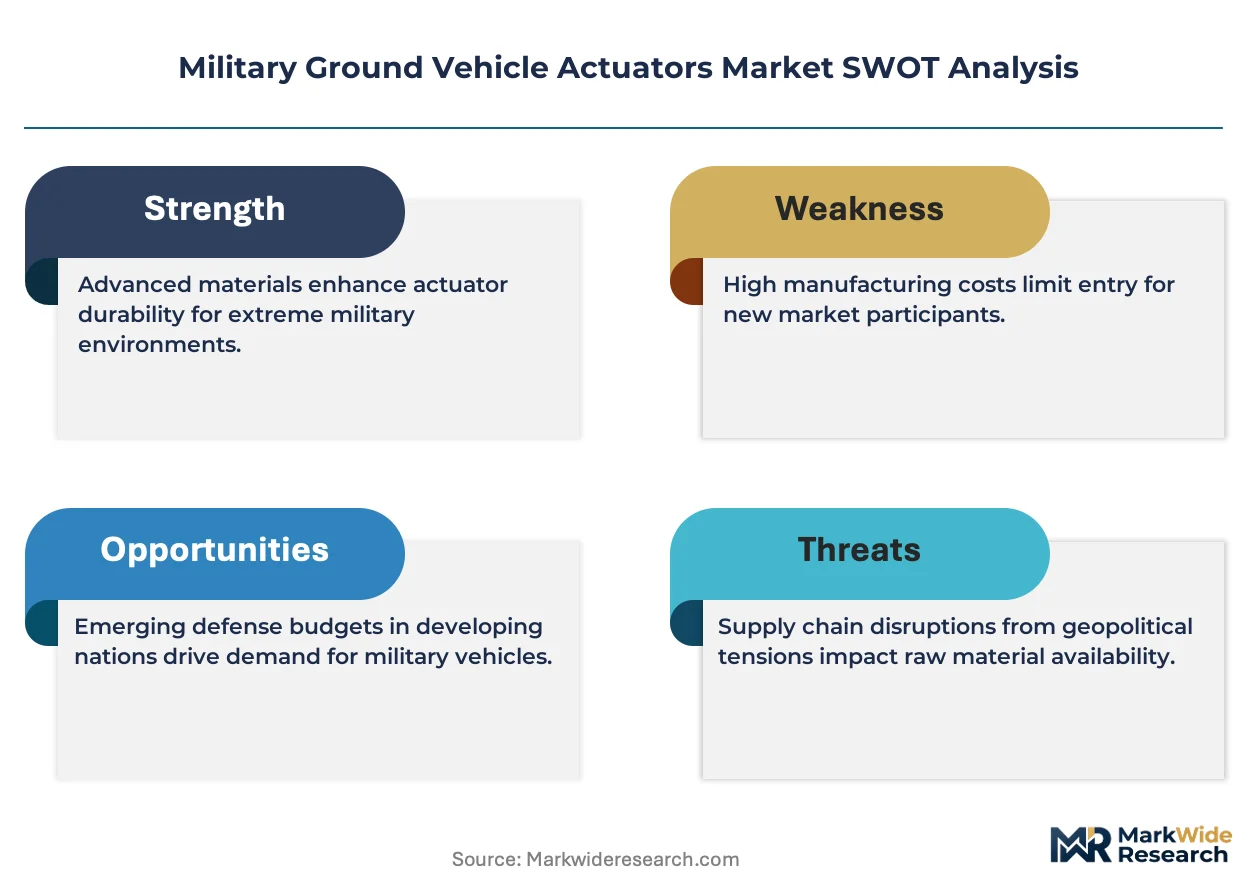
- Rare earth magnet supply concentration:Neodymium and dysprosium processing dependency on single-source jurisdictions is inflating permanent magnet actuator costs and creating 18-month procurement lead times.
- MIL-STD-810H shock qualification barriers:The 20g sustained shock testing requirement for ground vehicle actuators eliminates most commercial-off-the-shelf electric motor suppliers from defense qualification.
- Hydraulic legacy lock-in:Main battle tank turret drives above 50kN·m torque requirements still favor hydraulic architectures where electric alternatives remain unproven at volume.
Strategic Opportunities
- Unmanned ground vehicle actuator demand:Autonomous reconnaissance platforms in South Korea's Defense Acquisition Program Administration pipeline require miniature precision actuators for weapon and sensor articulation.
- Dual-use satellite actuator crossover:Space-qualified electromechanical positioners from satellite boom deployments are transferring to armored vehicle antenna pointing applications.
- US DoD modular open systems approach:The Army's MOSA mandate for interchangeable actuator interfaces is creating aftermarket retrofit opportunities for qualified third-party suppliers.
Industry Challenges
- Electromechanical-hydraulic integration complexity:Hybrid architectures combining electric precision with hydraulic power density require specialized control firmware that exceeds most suppliers' embedded systems capabilities.
- ITAR/EAR export control compliance:US-origin actuator technologies face State Department licensing delays that extend international program timelines by 9-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Ground Vehicle Actuators Market |
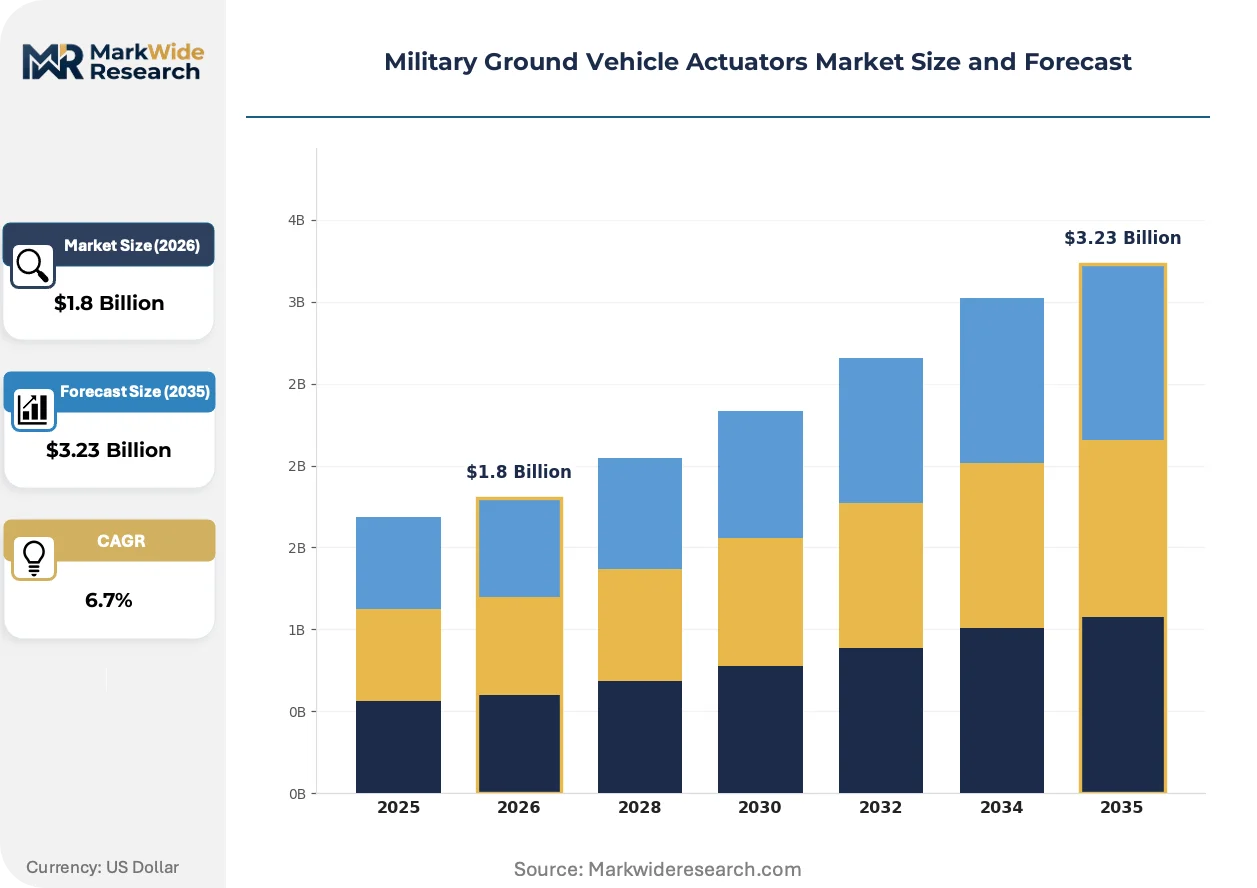
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electric Actuators, Pneumatic Actuators, Mechanical Actuators Use Case: Artillery Systems, Armored Vehicles, Reconnaissance, Mobility Platforms End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions Technology: Servo Technology, Linear Technology, Rotary Technology, Custom Solutions |
| Companies Covered | Triumph Group Inc., Nook Industries Inc., Curtiss-Wright Corporation, Ultra Motion, Kyntronics Inc., Moog Inc., AMETEK Inc., Whippany Actuation Systems, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Ground Vehicle Actuators Market Shifts & Advancements
Actuator architectures are bifurcating between precision electric systems for signature-sensitive platforms and ruggedized hydraulic-electrohydraulic hybrids for heavy armor, with control electronics becoming the primary differentiation layer.
Integrated motor-roller screw actuators are expanding into fire-control and active suspension applications where packaging density and positional accuracy outweigh cost sensitivity. US Army Ground Vehicle Systems Center programs are specifying these units for Next Generation Combat Vehicle prototypes. The technology is expanding into turret drives previously reserved for hydraulic powerpacks by delivering 35kN continuous force in envelopes under 4 liters.
REACH Annex XIV substance restrictions are forcing reformulation of hydraulic fluids and seal elastomers in actuators bound for European defense markets. The ECHA authorization requirements for phthalate plasticizers and certain anti-wear additives are compelling suppliers to qualify bio-synthetic alternatives. German and French armored vehicle programs are responding by accelerating all-electric turret drive specifications that eliminate hydraulic fluid compliance risks entirely.
Platform prime contractors are consolidating actuator sourcing through long-term vendor partnerships rather than transactional component procurement. The shift compresses supplier qualification overhead but locks second-tier actuator manufacturers out of new program competitions. South Korea's Hyundai Rotem and Germany's Rheinmetall are most visible in this pattern, each maintaining captive actuator development relationships that exclude open market bidding for critical motion control subsystems.
Military Ground Vehicle Actuators Market Segmentation
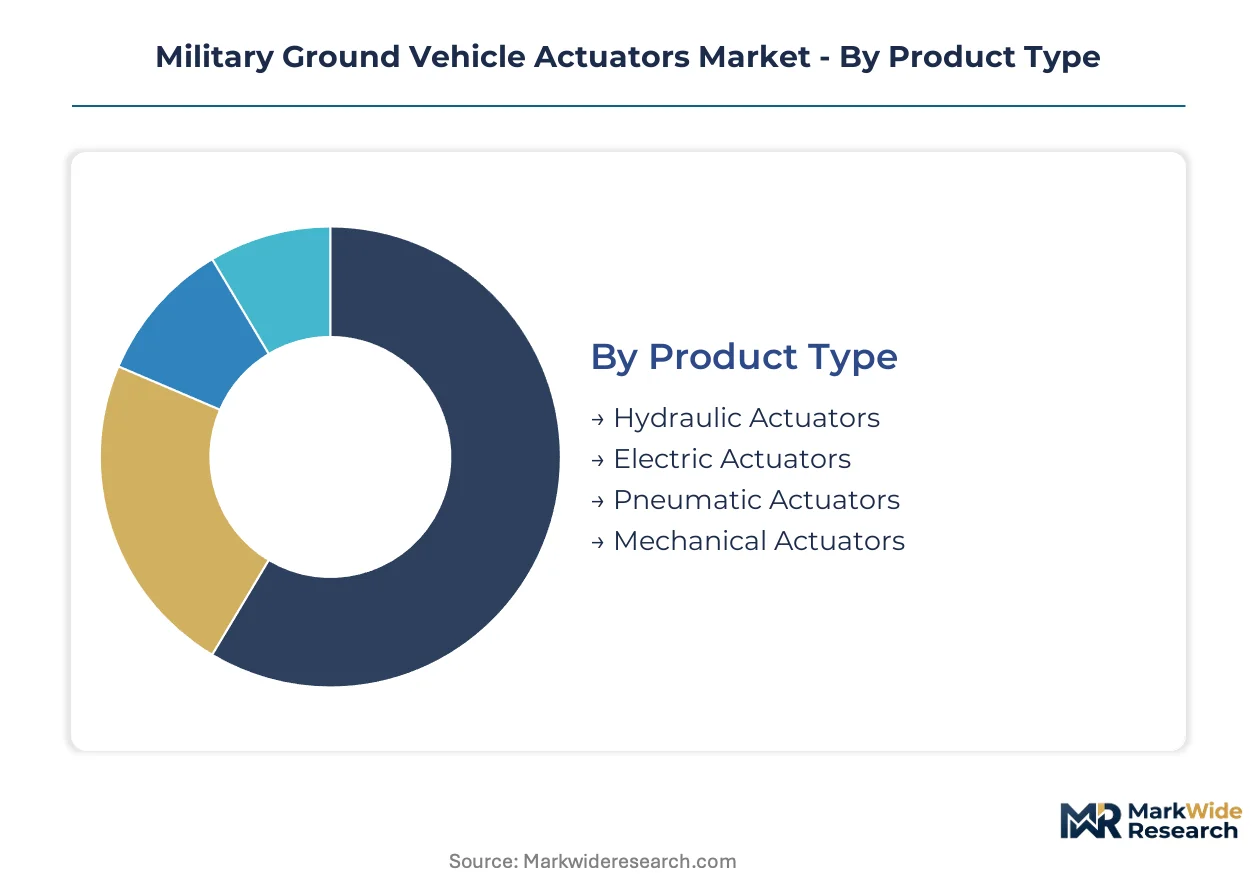
Segmentation in military ground vehicle actuators reveals how capital allocation and technical risk distribute across motion control architectures. Procurement patterns diverge sharply between legacy platform sustainment and next-generation combat vehicle development.
Product Type:
Capital intensity peaks in electric actuator manufacturing where silicon carbide inverters and rare-earth magnet supply chains demand multi-million dollar production lines.
- Hydraulic Actuators:These fluid-power systems deliver torque density above 50kN·m for main battle tank turret drives. Demand concentrates in Germany's Leopard modernization programs where KBA certification requirements preserve hydraulic architectures for heavy armor refurbishment.
- Electric Actuators:Electromechanical systems integrate permanent magnet motors with roller screw mechanisms for sub-millimeter positional accuracy. South Korea's Defense Acquisition Program Administration is specifying these units for autonomous reconnaissance platforms where thermal signature reduction outweighs upfront cost premiums.
- Pneumatic Actuators:Compressed-air systems occupy auxiliary roles in hatch and door mechanisms where load requirements remain modest.
- Mechanical Actuators:Manual screw and cam systems persist in backup safety systems for turret emergency operation.
Most installed capacity flows through hydraulic actuators. Expansion is steepest in electric actuators.
Use Case:
Application complexity scales with platform weight and mission criticality, from precision targeting to terrain negotiation.
- Armored Vehicles:Tracked and wheeled platforms require actuators for turret stabilization, weapon elevation, and active suspension articulation. NATO standardization agreements are driving interoperability specifications across member state procurement.
- Artillery Systems:Self-propelled howitzers demand high-torque elevation and traverse drives. The US Army's Extended Range Cannon Artillery program is specifying electromechanical alternatives to hydraulic legacy systems.
- Reconnaissance:Unmanned ground vehicles utilize miniature precision actuators for sensor gimbal control.
- Mobility Platforms:Logistics vehicles employ linear actuators for load handling and ramp operation.
Armored vehicles absorb the dominant share of procurement volume. Reconnaissance platforms are gaining share fastest as autonomous systems proliferate.
End User:
Customer sophistication varies from operational field units to system integrators managing platform-level integration risk.
- Military Forces:Direct procurement by army and marine corps technical authorities emphasizes field reliability and supply chain security. The US Department of Defense's MOSA mandate is reshaping sourcing toward modular, interchangeable actuator interfaces.
- Defense Contractors:Prime integrators like Rheinmetall and Hyundai Rotem maintain captive actuator development partnerships that compress supplier qualification overhead.
- Government Agencies:Research laboratories fund prototype development for next-generation combat vehicle demonstrations.
- Research Institutions:University-affiliated centers validate actuator performance under extreme environmental conditions per MIL-STD-810H protocols.
Defense contractors channel the majority of component demand. Military forces are accelerating direct procurement as platform electrification mandates tighten.
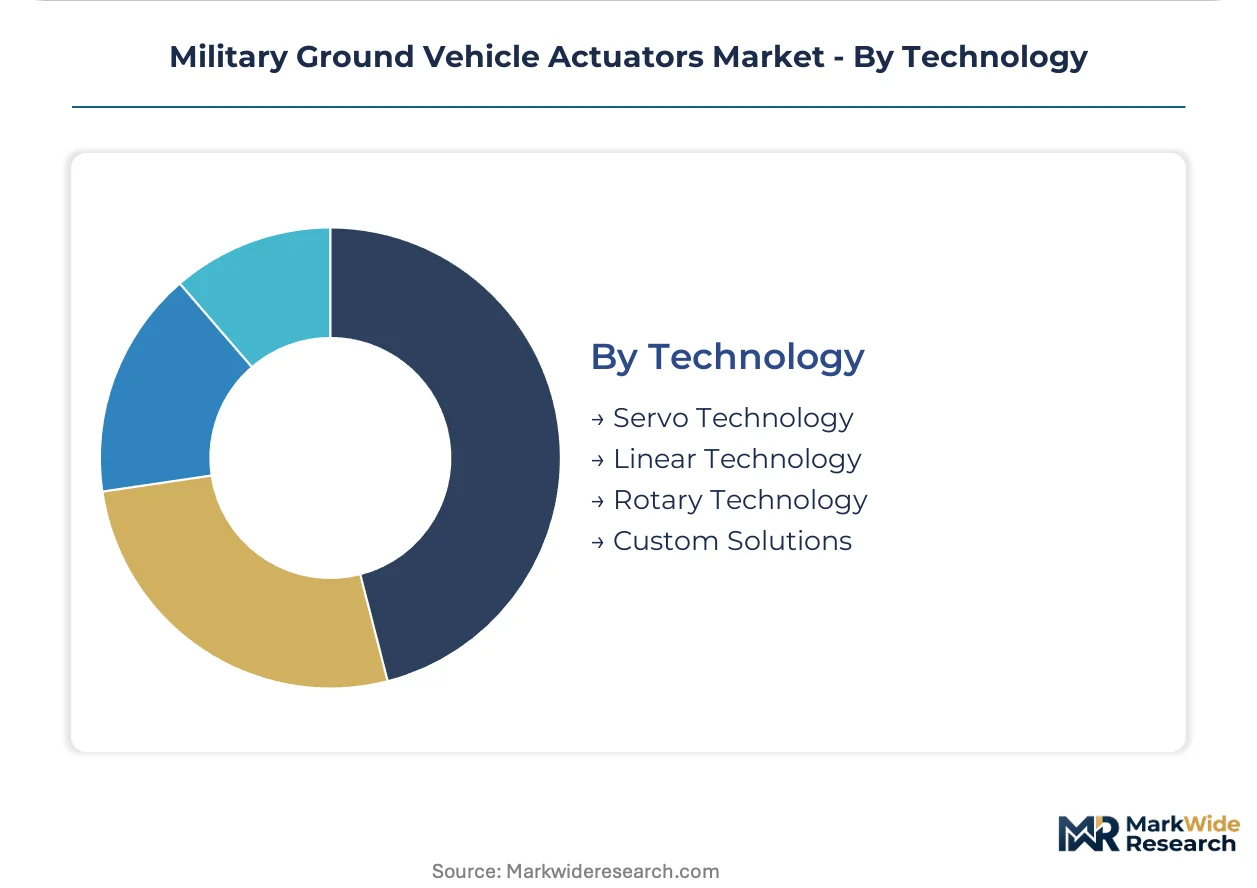
Technology:
Technical differentiation concentrates in control firmware and feedback sensor integration rather than mechanical topology alone.
- Servo Technology:Closed-loop position control systems achieve sub-millimeter accuracy through resolver or optical encoder feedback. Fire-control applications in main battle tanks require this precision for target engagement at extended ranges.
- Linear Technology:Roller screw and ball screw mechanisms convert rotary motion to linear displacement for suspension and hatch actuation. Cost constraints in volume production favor these simpler architectures.
- Rotary Technology:Direct-drive torque motors eliminate gear trains for turret traverse applications.
- Custom Solutions:Application-specific designs address unique packaging or load requirements outside standard product ranges.
Servo technology dominates precision-critical installations. Linear technology commands the largest unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA certification requirements for turret stabilization systems contrast with South Korea's Defense Acquisition Program Administration focus on autonomous reconnaissance platforms, revealing how national procurement priorities diverge across major defense markets.
United States
The US Department of Defense's MOSA mandate for interchangeable actuator interfaces and Next Generation Combat Vehicle prototypes drives electromechanical demand. MIL-STD-810H environmental testing protocols constrain supplier qualification to hardened designs. The Army's Ground Vehicle Systems Center in Michigan anchors prototype development for integrated motor-roller screw actuators.
Germany
Leopard main battle tank modernization waves and KBA certification requirements preserve hydraulic architectures for heavy armor refurbishment. The EU Green Deal defense procurement protocols mandate electric actuators in new armored vehicle programs. Industrial concentration in Bavaria and North Rhine-Westphalia hosts Rheinmetall's captive actuator development partnerships.
South Korea
Hyundai Rotem's platform prime contracting and Defense Acquisition Program Administration unmanned ground vehicle pipelines require miniature precision actuators. Domestic industrial base protection policies limit sourcing to cleared manufacturers. The Seoul Capital Area concentrates autonomous reconnaissance platform development with embedded weapon articulation systems.
France
The defense procurement agency's national security vetting restricts actuator sourcing to domestically cleared manufacturers. REACH Annex XIV substance restrictions accelerate all-electric turret drive specifications to eliminate hydraulic fluid compliance risks. The Île-de-France region hosts prime integrator engineering centers managing captive motion control subsystem partnerships.
United Kingdom
Challenger tank modernization and NATO standardization agreements for interchangeable components drive electromechanical retrofit demand. CE marking requirements under the Machinery Directive constrain design choices for transatlantic qualification. The Midlands defense industrial cluster sustains legacy platform sustainment actuator procurement.
Military Ground Vehicle Actuators Market Competitive Landscape
Top-tier vendors anchor high-reliability electromechanical positions, while mid-tier specialists occupy cost-sensitive linear actuator niches. The market structure reflects tiered consolidation around servo control heritage and nuclear-hardened design repurposing. Strategic archetypes include precision electric specialists, hydraulic power density incumbents, and dual-use satellite crossover entrants. Dominant competitive moves center on long-term vendor partnerships with platform primes and silicon carbide inverter technology licensing.
Within the precision electromechanical tier, Moog Inc. and Curtiss-Wright Corporation exemplify high-reliability positioning derived from servo control and nuclear-hardened engineering lineages respectively. Parker Hannifin Corporation anchors hydraulic dominance where load capacity requirements exceed electric alternatives. These three entities represent distinct competitive archetypes: permanent magnet servo integration, hardened electromechanical repurposing, and fluid-power torque density specialization.
| Leading Market Players |
|---|
| Triumph Group Inc. |
| Nook Industries Inc. |
| Curtiss-Wright Corporation |
| Ultra Motion |
| Kyntronics Inc. |
| Moog Inc. |
| AMETEK Inc. |
| Whippany Actuation Systems |
| Parker Hannifin Corporation |
| Others |
Supply & Pricing Matrix
Platform prime contractors in Germany, the United States, and South Korea concentrate procurement decisions through long-term vendor partnerships, compressing supplier qualification overhead and anchoring contract-based long-term offtake pricing with embedded after-sales service bundles.
Pricing Analysis
Component-only transactions separate from integrated subsystem packages across the market. Three-tier pricing structure across MIL-qualified premium, commercial-hardened standard, and refurbishment economy levels tracks certification grade and thermal envelope performance. Cost compression in the standard tier intensifies because silicon carbide inverter sourcing draws from constrained semiconductor foundry capacity. Defense contractors show least price sensitivity where platform integration risk dominates, while aftermarket retrofitters exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processing for neodymium and dysprosium feedstocks. Manufacturing concentrates in Germany, the United States, and South Korea for final actuator assembly. Raw material dependencies span samarium-cobalt magnets, high-grade steel alloys, and specialized hydraulic seal elastomers. Tariff exposure on processed magnet materials threatens cost stability. Distribution runs through prime contractor captive supply agreements rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with NATO electrification mandates and main battle tank modernization cycles providing predictable replacement demand across multi-year procurement horizons.
For Market Incumbents: Acquire silicon carbide inverter design capabilities to secure thermal performance advantages in next-generation electromechanical turret drives. Deepen backward integration into rare earth magnet recycling to offset Chinese supply concentration. Invest in MIL-STD-810H shock qualification infrastructure to eliminate emerging commercial-off-the-shelf motor suppliers from defense competitions. For New Entrants and Emerging Players: Integrated motor-roller screw miniaturization offers a technology-first wedge into South Korean unmanned ground vehicle actuator specifications. Target autonomous reconnaissance platform sensor gimbal applications where incumbent hydraulic suppliers lack electric precision heritage. Pursue dual-use satellite actuator crossover qualifications to bypass lengthy defense-specific certification cycles. For Investors and Strategic Acquirers: Defense primes with captive motion control partnerships are the most active acquirer in this space, consolidating supplier relationships to compress platform integration risk. Long-term viability centers on electromechanical displacement of hydraulic architectures in heavy armor applications. Watch for Leopard and Abrams modernization program award announcements as inflection indicators for retrofit actuator demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Enables 125°C ambient operation without thermal derating for compact high-torque electric actuators. |
| Long-term Vendor Partnership | Locks prime contractor actuator sourcing through Rheinmetall and Hyundai Rotem captive development relationships. |
| Rare Earth Magnet Recycling Investment | Reduces dependency on Chinese neodymium and dysprosium processing for permanent magnet supply security. |
| MIL-STD-810H Qualification Infrastructure | Eliminates commercial-off-the-shelf electric motor competitors through 20g sustained shock testing barriers. |
| Dual-use Satellite Actuator Crossover | Transfers space-qualified electromechanical positioners to armored vehicle antenna pointing applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged platform prime procurement directors, actuator engineering leads at Tier 1 suppliers, defense agency technical authorities, and aftermarket retrofit program managers. Secondary validation drew from NATO standardization agreement databases, national defense procurement agency filings, EU Green Deal defense protocol documentation, and customs trade records for rare earth magnet flows. Bottom-up segment sizing and top-down macro constraint checks provided cross-verification.
Segment-weighting distributed volume and value across product type, use case, end user, and technology dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to platform replacement cycles and electrification penetration assumptions. Industry-specific inputs included main battle tank modernization program pipelines, unmanned ground vehicle procurement schedules, and silicon carbide power electronics adoption trajectories.
The model holds under stable NATO defense spending and continued rare earth magnet supply concentration; deviation in trade policy or platform program cancellations would shift trajectory. Forecasts reflect documented assumptions about electrification penetration rates and qualification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Russia Defense Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Global Military Vehicle Electrification Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Unmanned Ground Vehicle Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Amphibious Vehicle Market