

Aircraft Panel Fatigue Monitoring Sensor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Panel Fatigue Monitoring Sensor Systems Market Insights
MIL-STD-810H compliance tier is rotating toward the center of procurement specifications for next-generation fatigue monitoring systems. TE Connectivity leverages its embedded sensor architecture to anchor defense contracts across North American platforms. Honeywell International sustains technology leadership through proprietary wireless interrogation methods for bonded composite panels. Luna Innovates competes on fiber optic strain resolution for hot-section engine-adjacent structures.
Aircraft panel fatigue monitoring sensor systems comprise distributed sensing arrays—fiber Bragg gratings, piezoelectric wafer active sensors, and foil strain gauges bonded or embedded within aluminum and composite airframe panels—that detect micro-crack initiation, strain accumulation, and delamination through real-time electromechanical or optical signal transduction. These systems serve the primary industrial purpose of extending safe operational life beyond original design limits while eliminating invasive manual inspection intervals. Fiber optic sensors command the premium tier on long-haul commercial platforms where electromagnetic immunity and multiplexing density justify unit cost, whereas piezoelectric sensors dominate retrofit programs for legacy narrow-body fleets through lower installation complexity and established calibration protocols. Wireless sensor networks are displacing cabled architectures in new OEM programs, though embedded systems retain margin concentration in military applications where tamper-proof integration outweighs upgrade flexibility.
FAA airworthiness directives, EASA continuing airworthiness program requirements, and MIL-STD-810H environmental qualification standards collectively elevate barrier-to-entry for uncertified entrants while mandating traceable calibration chains across installed bases. The FAA's recent emphasis on damage tolerance methodology for aging transport category aircraft directly expands addressable fleet scope for predictive maintenance sensor suites. Stakeholders must monitor evolving composite-specific certification criteria from EASA and the trajectory of Chinese CAAC harmonization with Western structural health monitoring standards.
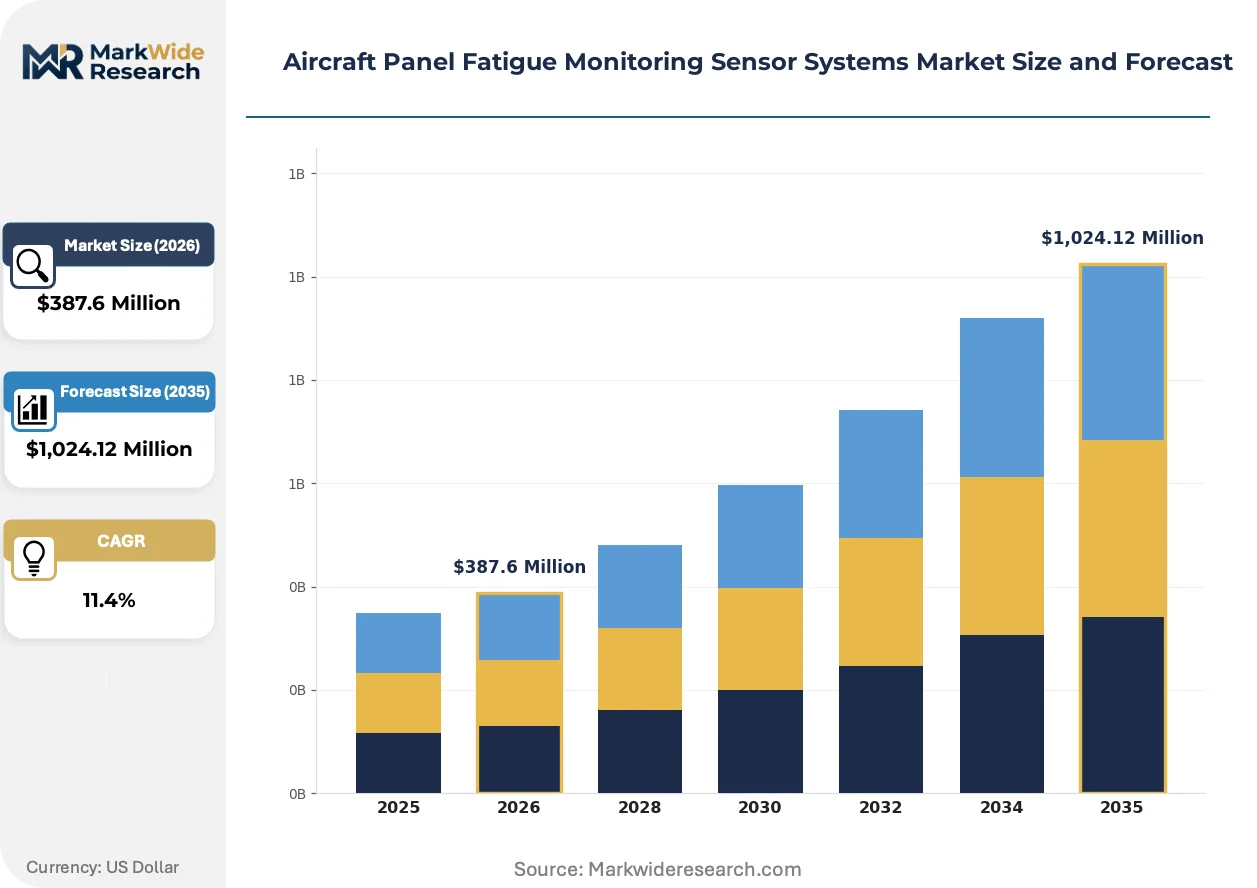
Market Dynamics
Fleet-wide sensor deployment is accelerating as commercial carriers seek to extend airframe certification intervals beyond original design limits, while defense integrators embed hardened systems for mission-critical platforms. This structural pull toward predictive maintenance architectures is compressing traditional manual inspection cycles and reshaping procurement specifications across both OEM and aftermarket channels.
Growth Catalysts
- FAA Damage Tolerance Mandates:The FAA's emphasis on damage tolerance methodology for aging transport category aircraft directly expands the addressable fleet scope for structural health monitoring suites, forcing carriers to adopt certified sensor networks.
- Composite Airframe Proliferation:Boeing 787 and Airbus A350 programs embed fiber optic strain arrays from delivery, establishing precedent for bonded composite panel monitoring that legacy aluminum programs now retrofit to match.
- MIL-STD-810H Qualification Tier:Defense procurement specifications now rotate environmental qualification compliance to center-stage, filtering uncertified entrants while mandating traceable calibration chains across installed military bases.
Market Restraints
- Platinum-Based Sensor Metallurgy:Piezoelectric wafer active sensors rely on platinum electrode deposition, exposing installed base economics to precious metal price volatility that compresses aftermarket margin structures.
- Optical Interrogator Supply Concentration:Fiber Bragg grating systems depend on tunable laser sources concentrated among three dominant photonics suppliers, creating single-source vulnerability for multiplexed sensing architectures.
- EASA Composite-Specific Certification Delays:Pending EASA criteria for bonded sensor integration on carbon fiber reinforced polymer panels have frozen retrofit approvals for European-registered wide-body fleets since draft publication.
Strategic Opportunities
- CAAC Harmonization Trajectory:Chinese aviation regulator alignment with Western structural health monitoring standards would unlock COMAC C919 and ARJ21 production lines for embedded sensor specification, creating captive demand for qualified system integrators.
- Wireless Interrogation Convergence:Ultra-wideband radio frequency methods are converging with energy harvesting micro-generators to eliminate cable harness weight from new OEM narrow-body programs, displacing legacy cabled architectures.
- Hot-Section Adjacent Monitoring:Engine-adjacent panel structures currently escape inspection due to thermal cycling extremes, presenting white space for fiber optic strain resolution technologies rated beyond 300°C continuous operation.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled thermal-mechanical-electromagnetic modeling for sensor placement optimization requires rare cross-trained engineers, elongating design validation cycles for custom airframe integrations.
- Calibration Chain Recertification Burden:FAA traceable calibration mandates force operators to ground aircraft for sensor validation intervals, creating operational friction that undermines promised maintenance interval extensions.
- Legacy 1553 Bus Integration Complexity:Military platform retrofits must bridge modern wireless sensor outputs to MIL-STD-1553 avionics backbones, requiring protocol translation hardware that adds failure modes and weight penalties.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Panel Fatigue Monitoring Sensor Systems Market Trends and Innovations
Sensor architecture is pivoting from discrete point measurement toward distributed sensing fabrics that blanket entire airframe sections. This shift is compressing installation labor, multiplying data resolution, and enabling crack propagation tracking across panel boundaries rather than isolated strain readings.
Photonic crystal fiber technology is miniaturizing. These hollow-core waveguides eliminate silica glass nonlinearities that corrupt signal fidelity in conventional fiber Bragg gratings, enabling strain resolution below 0.1 microstrain. Airbus Defense and Space programs are adopting the architecture for unmanned aerial vehicle wings where electromagnetic immunity and gram-level weight budgets coexist. The structural consequence is that optical interrogation hardware is miniaturizing from rack-mounted chassis to palm-sized modules, collapsing the barrier between laboratory-grade metrology and flight-qualified instrumentation.
EASA's pending Certification Memorandum on Structural Health Monitoring Systems is tightening validation requirements for artificial intelligence-driven damage detection algorithms. The industrial consequence is a bifurcation between rule-based threshold alarm systems that certify faster and machine learning architectures that promise higher fidelity but face elongated approval timelines. Narrow-body retrofit programs are responding by specifying deterministic signal processing chains to avoid regulatory uncertainty, while green-field OEM platforms absorb the delay to embed neural network classifiers.
Airline procurement departments are unbundling sensor hardware from data analytics subscriptions, reversing the bundled SaaS model that dominated early fleet-wide deployments. Maintenance divisions now negotiate separate contracts for interrogator hardware, cloud storage tiers, and predictive algorithm licenses, fragmenting vendor relationships. This disintermediation is most visible among United States legacy carriers operating mixed Boeing-Airbus fleets, where procurement teams seek interchangeability across airframe types rather than OEM-captive sensor ecosystems.
Aircraft Panel Fatigue Monitoring Sensor Systems Market Segmentation
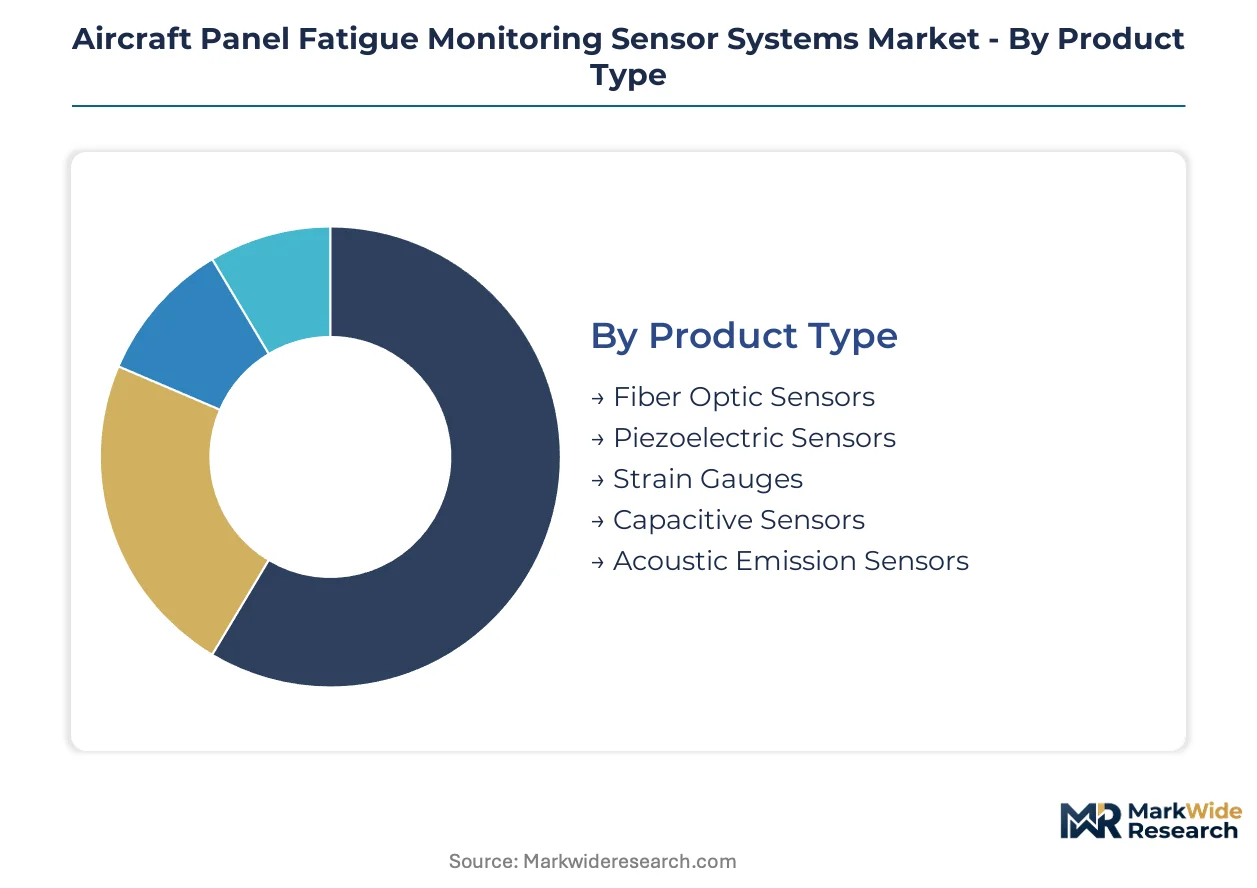
Segmentation in aircraft panel fatigue monitoring sensor systems reveals how procurement specifications diverge across military and commercial channels. Technology choices cascade through installation complexity, certification burden, and lifecycle economics in ways that reshape vendor positioning.
Product Type:
Premium margin pools concentrate in fiber optic architectures where electromagnetic immunity commands pricing power on long-haul platforms.
- Fiber Optic Sensors:Fiber Bragg grating arrays transduce strain through wavelength shift in silica waveguides, achieving multiplexing densities exceeding 100 sensors per fiber. Boeing 787 and Airbus A350 programs specify these from delivery for bonded composite panel monitoring, with retrofit demand now spreading to legacy aluminum fleets seeking equivalent certification intervals.
- Piezoelectric Sensors:Wafer-active piezoceramic elements generate charge proportional to dynamic strain, dominating narrow-body retrofit programs through lower installation complexity and established MIL-STD calibration protocols. Platinum electrode metallurgy exposes aftermarket economics to precious metal volatility that compresses service margins.
- Strain Gauges:Foil resistance grids bonded to metallic substrates provide baseline electromechanical measurement for aluminum airframe applications.
- Capacitive Sensors:Parallel-plate displacement transducers suit proximity-based crack detection in environments where galvanic isolation matters.
- Acoustic Emission Sensors:Piezoelectric transducers detect stress-wave energy release from micro-crack initiation in pressurized fuselage panels.
The dominant share belongs to piezoelectric sensors, while fiber optic sensors are gaining share fastest through composite airframe proliferation.
Technology:
Architecture choices here determine whether programs absorb upfront integration costs or recurring data subscription burdens.
- Wireless Sensor Networks:Ultra-wideband radio frequency interrogation eliminates cable harness weight from new OEM narrow-body programs. Energy harvesting micro-generators paired with ultra-low-power transceivers are displacing legacy cabled architectures in green-field Boeing and Airbus production lines.
- Embedded Systems:Tamper-proof sensor integration within composite layups retains margin concentration in military applications where upgrade flexibility is sacrificed for mission assurance. Defense integrators specify these for platforms requiring MIL-STD-810H qualification without external access ports.
- IoT Integration:Cloud-connected sensor gateways enable fleet-wide aggregation of structural health data across mixed manufacturer bases.
- Remote Monitoring:Satellite-linked interrogation extends coverage to unmanned aerial vehicles and deployed military assets beyond ground station range.
- Data Analytics Platforms:Predictive algorithm licenses are unbundling from hardware procurement, fragmenting vendor relationships as airline maintenance divisions negotiate separate cloud storage and machine learning contracts.
Embedded systems retain the revenue base in defense, though wireless networks are expanding most quickly through commercial OEM adoption.
Application:
Functional purpose dictates sensor density, calibration frequency, and regulatory validation burden.
- Structural Health Monitoring:Continuous strain field mapping across entire airframe sections enables crack propagation tracking beyond isolated point measurements. EASA's pending Certification Memorandum on AI-driven damage detection algorithms is bifurcating procurement between rule-based threshold systems and neural network architectures.
- Predictive Maintenance:Remaining useful life estimation from fatigue accumulation data compresses manual inspection intervals and extends airframe certification limits. FAA damage tolerance mandates for aging transport category aircraft are forcing carrier adoption of certified sensor networks for this purpose.
- Damage Detection:Discrete event identification from acoustic emission or impedance shift targets specific failure modes.
- Load Measurement:Real-time weight and balance verification supports operational efficiency in cargo and passenger configurations.
- Vibration Analysis:Modal frequency tracking identifies fastener loosening and panel resonance shifts.
Predictive maintenance commands the largest installed base, while structural health monitoring is climbing the fastest through distributed sensing fabric adoption.
End User:
Procurement authority and technical specification control vary sharply across this category.
- Aircraft OEMs:Boeing and Airbus embed fiber optic strain arrays from delivery on composite programs, establishing specification precedent that constrains aftermarket alternatives. Their purchasing power extracts volume pricing that compresses supplier margins while locking in multi-decade service relationships.
- Maintenance, Repair & Overhaul:Independent MRO providers retrofit legacy fleets with piezoelectric and wireless architectures, bridging certification gaps for aging aluminum airframes. Their technical autonomy enables mixed-fleet standardization that OEM-captive ecosystems cannot match.
- Airlines:United States legacy carriers operating mixed Boeing-Airbus fleets now unbundle sensor hardware from data analytics subscriptions, seeking interchangeability across airframe types.
- Defense Aviation:Military platforms mandate MIL-STD-810H environmental qualification and traceable calibration chains that filter uncertified entrants.
- Aerospace Engineering Firms:Design consultancies specify custom sensor placements for special mission aircraft and modification programs.
Aircraft OEMs hold the dominant share through embedded specification control, though MRO providers are closing the gap fastest via retrofit program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor exports flow into French and British aerospace assembly lines, while US-manufactured interrogator hardware supplies carriers across East Asia. This trade architecture concentrates specification authority in North American and European regulatory spheres.
United States
Major carriers and defense integrators operate the largest monitored fleets worldwide. FAA airworthiness directives mandate enhanced structural monitoring for aging transport category aircraft, forcing adoption of certified sensor networks. Seattle and Wichita clusters anchor OEM specification control, with Boeing embedding fiber optic arrays from delivery on composite programs.
Germany
Precision sensor manufacturing concentrates in Baden-Württemberg and Bavaria industrial corridors. EASA continuing airworthiness program requirements elevate barrier-to-entry for uncertified entrants while mandating traceable calibration chains. Munich-based engineering consultancies specify custom sensor placements for special mission aircraft modification programs.
France
Airbus operations in Toulouse establish precedent for bonded composite panel monitoring that legacy programs retrofit to match. EASA pending Certification Memorandum on Structural Health Monitoring Systems tightens validation requirements for AI-driven damage detection algorithms. The Île-de-France aerospace cluster drives specification convergence across European-registered wide-body fleets.
United Kingdom
Defense aviation procurement mandates MIL-STD-810H environmental qualification for mission-critical platforms. Bristol and Broughton manufacturing sites embed hardened sensor systems in military airframe production. UK carriers operating mixed Boeing-Airbus fleets now unbundle sensor hardware from data analytics subscriptions.
Japan
METI industrial policy supports precision sensor component manufacturing for aerospace supply chains. Kansai and Chubu regional clusters produce piezoelectric wafer elements and optical interrogator subassemblies. Japanese carriers retrofit legacy narrow-body fleets with wireless architectures to match composite program certification intervals.
Aircraft Panel Fatigue Monitoring Sensor Systems Market Competitive Landscape
Listed leaders compete with private specialists across defense and commercial certification tiers. The vendor base concentrates around three to four dominant system integrators who anchor OEM supply relationships, while tier-two specialists capture retrofit and aftermarket channels. Strategic archetypes include embedded defense contractors, commercial wireless platform developers, and fiber optic precision specialists. Competitive moves center on technology licensing partnerships and vertical integration into interrogator hardware manufacturing.
Among US-based diversified industrials, Honeywell International and TE Connectivity exemplify scale-driven platform developers. Luna Innovations occupies a position within the fiber optic precision tier. HBK and Vishay Precision Group represent European measurement technology specialists. These named entities anchor competitive dynamics without exhausting the participant base.
| Leading Market Players |
|---|
| HBK |
| Vishay Precision Group |
| TE Connectivity |
| Curtiss-Wright |
| Luna Innovations |
| Acellent Technologies |
| Opsens Solutions |
| Honeywell International |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-120-day lead times for tunable laser interrogators from specialized photonics suppliers concentrate pricing power among fiber optic system integrators serving Boeing and Airbus production lines. This inventory compression cascades through the value chain, forcing tier-two retrofit providers toward piezoelectric architectures with shorter procurement cycles and exposed precious metal cost bases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in this market. Certification grade under FAA airworthiness directives and EASA continuing airworthiness programs creates steep price differentiation between MIL-STD-810H qualified systems and uncertified alternatives. Pricing pressure stems from platinum electrode volatility in piezoelectric wafer active sensors, compressing aftermarket service margins. Maintenance, repair and overhaul providers exhibit highest price sensitivity due to unbundled procurement of hardware and analytics subscriptions, while defense integrators absorb premium tiers for mission assurance.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for optical interrogator subassemblies sourced from Japanese and German precision manufacturing clusters. Supply concentrates in the United States for defense-qualified system integration, Germany for fiber Bragg grating fabrication, and Japan for piezoelectric wafer elements. The value chain draws from platinum group metals, silica optical fiber, and specialized photonics packaging. Single-source vulnerability around tunable laser sources creates structural risk. Distribution runs through OEM captive supply agreements for new aircraft programs and independent MRO channels for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against wireless sensor networks displacing legacy cabled architectures in narrow-body OEM programs, a substitution threat accelerating through energy harvesting micro-generator maturation.
For Market Incumbents: Fortify certification moats by accelerating MIL-STD-810H qualification for next-generation fiber optic interrogators before EASA's pending Certification Memorandum tightens validation requirements. Deepen backward integration into photonics packaging to reduce dependency on the three dominant tunable laser suppliers. Lock in multi-decade service relationships with Boeing and Airbus through embedded specification control on composite airframe programs.
For New Entrants and Emerging Players: Lead with hot-section adjacent monitoring applications exceeding 300°C continuous operation, a white space escaping established competitors due to thermal cycling extremes. Target military platform retrofits bridging wireless sensor outputs to MIL-STD-1553 avionics backbones, where protocol translation hardware shortages create penetrable gaps. Pursue CAAC harmonization readiness to capture COMAC C919 and ARJ21 embedded sensor specifications as Chinese aviation regulators align with Western structural health monitoring standards.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming aerospace sensor divisions lacking fiber optic precision capabilities. Long-term viability hinges on positioning for predictive maintenance architecture consolidation as airlines unbundle hardware from analytics subscriptions. Monitor EASA's final Certification Memorandum publication as the inflection signal separating rule-based threshold systems from neural network classifier investments.
| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810H Qualification Acceleration | Defense procurement specifications now filter uncertified entrants while mandating traceable calibration chains across installed military bases. |
| Wireless Interrogation Convergence | Ultra-wideband radio frequency methods paired with energy harvesting micro-generators eliminate cable harness weight from new OEM narrow-body programs. |
| Photonic Crystal Fiber Miniaturization | Hollow-core waveguides eliminate silica glass nonlinearities, enabling strain resolution below 0.1 microstrain for unmanned aerial vehicle applications. |
| AI-Driven Damage Detection Certification | EASA's pending Certification Memorandum bifurcates procurement between rule-based threshold alarm systems and machine learning architectures with elongated approval timelines. |
| Hardware-Analytics Unbundling | United States legacy carriers now negotiate separate contracts for interrogator hardware, cloud storage tiers, and predictive algorithm licenses. |
Research Methodology
Desk research of FAA airworthiness directive filings, EASA continuing airworthiness program documentation, and MIL-STD-810H qualification records preceded structured interviews with aerospace sensor procurement managers, defense platform integration engineers, airline maintenance directors, and MRO technical specification leads. Secondary validation drew from OEM production forecasts, photonics supplier capacity disclosures, and customs trade data for platinum group metal flows. Bottom-up triangulation across installed fleet sensor counts converged with top-down market sizing through OEM delivery projections and retrofit penetration assumptions.
Variance decomposition across the projection horizon isolates volume sensitivity to fleet renewal rates, composite airframe delivery mix, and regulatory mandate implementation timelines. Segmentation modeling captures product type, technology architecture, application purpose, and end-user procurement authority. CAGRs derive from slope-intercept calibration against historical sensor deployment curves and forward fleet expansion schedules. Industry-specific inputs include damage tolerance methodology adoption curves and CAAC harmonization trajectory assumptions.
Underlying assumptions cover stable FAA and EASA regulatory enforcement intensity, with deviation risk concentrated in EASA composite-specific certification delays and platinum price volatility. Forecasts reflect these conditions throughout the modeling period. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.