
 Global Military Vehicle Electrification Market | 2026-2036
Global Military Vehicle Electrification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Vehicle Electrification Market Intelligence
Defense procurement leasing and performance-based logistics contracts is reconfiguring how mid-tier suppliers enter military electrification. Rheinmetall AG leverages its captive powertrain engineering to anchor European armored vehicle hybridization programs. BAE Systems sustains transatlantic competitiveness through in-house production of combat-proven electric drive architectures. GM Defense differentiates by occupying the light tactical segment with commercial-derivative electrification adapted for military duty cycles.
Military vehicle electrification encompasses the integration of battery-electric, hybrid-electric, or fuel-cell powertrains into wheeled and tracked platforms, typically requiring 800V architectures, armored battery enclosures with ballistic protection to STANAG 4569 levels, and silent-watch capabilities for 6–12 hours without engine operation. Its primary purpose is reducing tactical signature while decoupling forward-deployed units from vulnerable liquid-fuel supply convoys. Battery Electric and Hybrid Electric systems currently dominate development spending, with fuel-cell architectures representing the fastest-growing technology pool as hydrogen logistics mature for expeditionary forces. Armored Personnel Carriers command the largest share of platform-level investment, while Reconnaissance Drones are absorbing disproportionate R&D intensity due to their favorable power-to-weight ratios for full electrification.
The US Department of Defense operational energy mandates, NATO STANAG standards for electromagnetic compatibility, and the EU Green Deal defense procurement guidelines collectively shape platform specifications and cross-border market access for electrified systems. EPA and NHTSA emissions frameworks indirectly pressure military vehicle suppliers to demonstrate technology transferability from commercial zero-emission programs. Stakeholders must monitor how battery supply chain security classifications evolve against export control regimes to anticipate which electrification technologies will face sourcing constraints versus accelerated adoption.
Market Dynamics
Defense procurement officers are decoupling vehicle electrification from legacy platform life cycles, compressing technology refresh timelines from 20-year cycles to 8-year sprints as battlefield energy resilience becomes a survivability metric.
Growth Catalysts
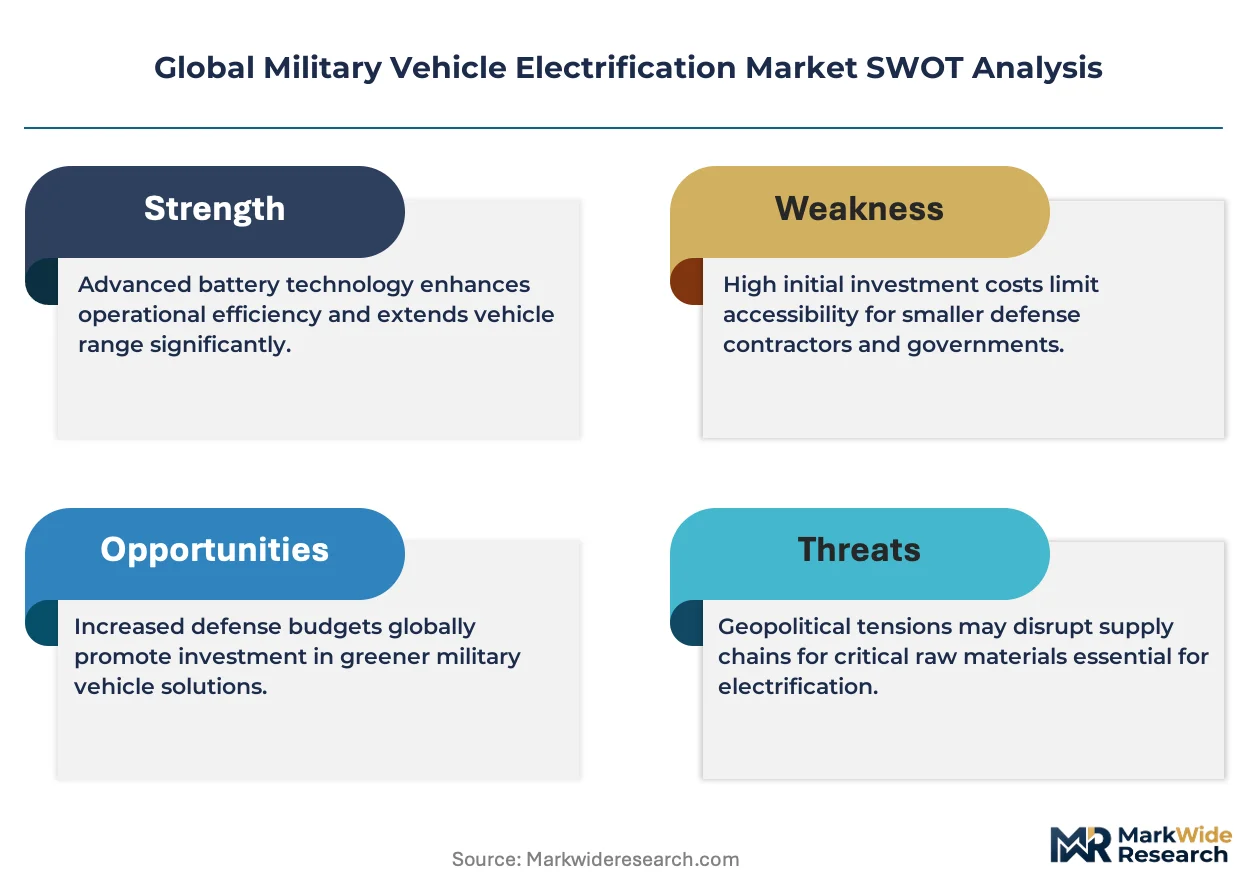
- Operational Energy Mandates:The US Department of Defense's operational energy strategy mandates 50% reduction in liquid fuel consumption for forward-deployed forces by 2030, forcing platform electrification into every new tactical vehicle program.
- STANAG 4569 Ballistic Protection Standards:NATO's harmonized armored vehicle protection requirements now include electromagnetic compatibility clauses that favor 800V architectures with hardened battery enclosures.
- Silicon Carbide Power Electronics:Wide-bandgap semiconductors are cutting inverter losses by 40%, enabling thermal management solutions that fit within existing armored vehicle hull volumes without sacrificing payload.
Market Restraints
- Lithium Supply Chain Concentration:Processing capacity for battery-grade lithium hydroxide concentrates in Chile and Australia, creating single-source vulnerability for defense contractors subject to ITAR export controls.
- STANAG Electromagnetic Compatibility Certification:NATO's 18-month validation timeline for electromagnetic interference hardening adds 30% to platform development schedules, freezing mid-tier suppliers from rapid iteration.
- Diesel-Electric Hybrid Entrenchment:Existing forward maintenance depots and field repair protocols are optimized for mechanical drivetrains, creating path dependency that slows full battery-electric adoption.
Strategic Opportunities
- EU Green Deal Defense Procurement Guidelines:Brussels is embedding carbon intensity thresholds into defense tender evaluations, creating preferential access for electrified platforms in European joint procurement programs.
- Unmanned Ground Vehicle Convergence:Autonomous logistics platforms are merging with electrified powertrains, opening white space for silent resupply convoys operating beyond line-of-sight.
- South Korean Defense Export Financing:Seoul's KODEF export credit agency is bundling battery supply guarantees with vehicle platform sales, penetrating Southeast Asian markets previously locked to US and European suppliers.
Industry Challenges
- Thermal Runaway Containment Engineering:Designing ballistic-resistant battery enclosures that simultaneously vent cell-thermal events without compromising crew compartment integrity requires materials science capabilities scarce outside aerospace.
- Field Repair Technician Retraining:Military maintenance corps lack proficiency in high-voltage isolation procedures and battery management system diagnostics, forcing parallel contractor support structures that inflate through-life costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Vehicle Electrification Market |
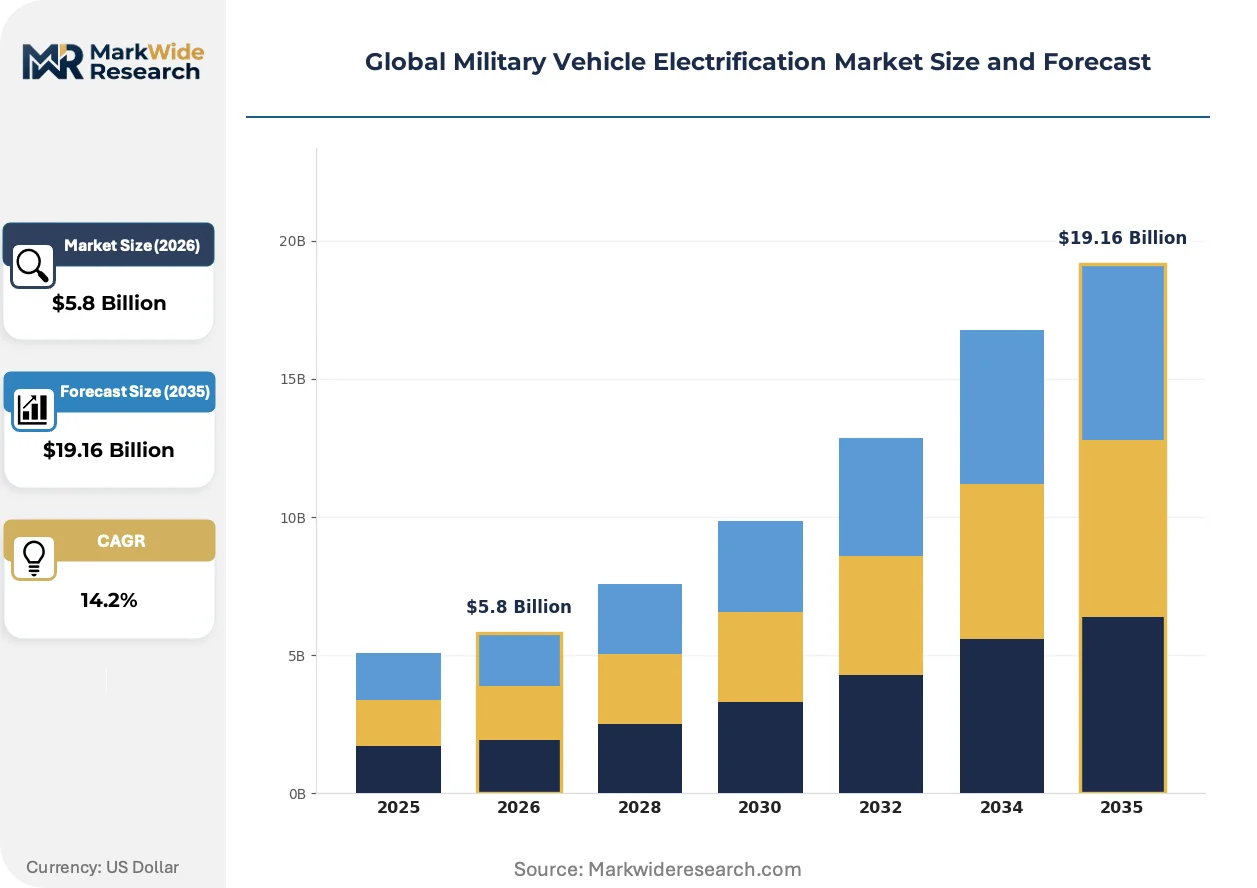
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $19.16 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Armored Personnel Carriers, Tactical Trucks, Combat Engines, Reconnaissance Drones, Support Vehicles Electrification Technology: Battery Electric, Hybrid Electric, Fuel Cell Electric, Regenerative Braking, Solar Assistance Operational Environment: Urban Combat Zones, Desert Operations, Arctic Expeditions, Jungle Warfare, Amphibious Deployment End User: Defense Forces, Homeland Security, Peacekeeping Units, Special Operations, Paramilitary Groups |
| Companies Covered | Leonardo S.p.A., Rheinmetall AG, BAE Systems, KNDS, Textron, Oshkosh Corporation, GM Defense, QinetiQ Group, General Dynamics Land Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Vehicle Electrification Market Strategic Shifts & Innovations
Electrification architectures are fragmenting along mission profiles rather than platform weight classes, with reconnaissance vehicles pursuing full battery-electric propulsion while heavy armor settles on series-hybrid layouts.
Digital twin environments are virtualizing powertrain validation before physical prototyping. BAE Systems and Rheinmetall deploy virtualized thermal and electromagnetic models to compress 24-month hardware test cycles into 6-month simulation suites. This approach is virtualizing the traditional armor-versus-mobility trade-off, allowing engineers to optimize battery placement against ballistic threat arcs without building multiple hull prototypes.
REACH chemical substance restrictions are forcing reformulation of electrolyte solvents and flame-retardant battery pack materials. The European Chemicals Agency's 2023 candidate list expansion for per- and polyfluoroalkyl substances is pushing defense suppliers toward carbonate-based electrolyte alternatives. German and French prime contractors are accelerating in-house cell chemistry programs to insulate supply chains from regulatory-driven material obsolescence.
Leasing structures are displacing capital acquisition for tactical vehicle fleets. The UK Ministry of Defence's Multi-Role Vehicle-Protected program and similar NATO frameworks now emphasize availability-based contracting where OEMs retain battery asset ownership. This transfers degradation risk from militaries to suppliers, concentrating market access among firms with captive battery lifecycle management capabilities in the United States, Germany, and South Korea.
Global Military Vehicle Electrification Market Segmentation
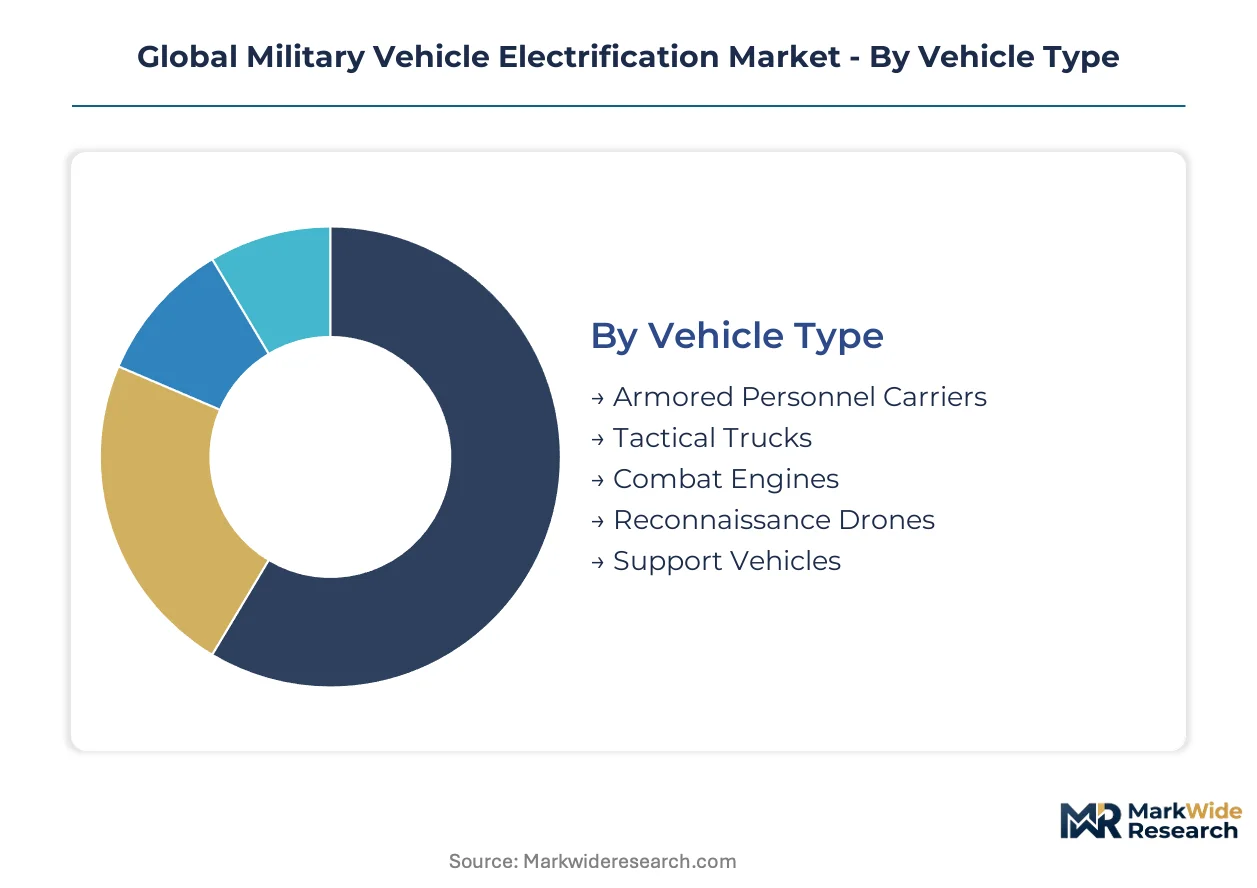
Military vehicle electrification fragments along mission-critical dimensions where powertrain architecture must reconcile tactical requirements with energy resilience. Platform weight, operational tempo, and threat environment collectively determine which electrification modality delivers survivability without compromising mobility.
Vehicle Type:
Use-case spectrum spans from high-intensity combat platforms to unmanned reconnaissance assets, each imposing distinct thermal management and signature constraints.
- Armored Personnel Carriers:These platforms integrate 800V hybrid architectures with STANAG 4569-compliant battery enclosures. Demand concentrates in Germany and the United States where NATO modernization programs prioritize crew survivability alongside fuel logistics reduction.
- Tactical Trucks:Light and medium tactical vehicles accommodate commercial-derivative electrification adapted for military duty cycles. The US Army's operational energy mandates are accelerating procurement of hybrid tactical trucks for forward-deployed brigade support.
- Combat Engines:Main battle tank powertrains remain diesel-dominant due to energy density requirements for 70-ton platforms.
- Reconnaissance Drones:Unmanned aerial systems favor full battery-electric propulsion given favorable power-to-weight ratios.
- Support Vehicles:Recovery and engineering platforms adopt series-hybrid layouts to sustain high-draw auxiliary equipment.
The dominant share belongs to Armored Personnel Carriers, while Reconnaissance Drones are expanding most quickly due to autonomy convergence.
Electrification Technology:
Technology maturity tiers separate field-proven architectures from emerging systems awaiting logistics infrastructure.
- Battery Electric:Lithium-ion and emerging solid-state chemistries power reconnaissance vehicles and unmanned platforms. South Korean defense export financing bundles battery supply guarantees with platform sales, penetrating Southeast Asian markets.
- Hybrid Electric:Series and parallel configurations dominate current procurement, decoupling forward units from vulnerable fuel convoys while retaining diesel range extension.
- Fuel Cell Electric:Hydrogen fuel cells are gaining traction for expeditionary forces where silent watch and extended range converge.
- Regenerative Braking:Kinetic recovery systems reduce brake wear in stop-start urban combat profiles.
- Solar Assistance:Photovoltaic integration extends silent-watch duration for static surveillance positions.
Battery Electric and Hybrid Electric systems absorb the largest development allocations, though Fuel Cell Electric architectures are climbing the fastest as hydrogen logistics mature.
Operational Environment:
Environmental severity dictates thermal management specifications and powertrain derating factors.
- Urban Combat Zones:Stop-start profiles and electromagnetic signature constraints favor full electrification or deep hybridization.
- Desert Operations:Extreme thermal loads stress battery cooling systems; demand centers on US Central Command theaters.
- Arctic Expeditions:Sub-zero temperatures degrade lithium-ion performance, driving demand for solid-state alternatives in Norwegian and Finnish border defense.
- Jungle Warfare:High humidity and corrosion risk require sealed 800V architectures with conformal coating standards.
- Amphibious Deployment:Saltwater immersion protection adds mass penalties that hybrid layouts offset with torque density advantages.
Urban Combat Zones command the largest addressable base, while Arctic Expeditions are gaining share fastest as NATO northern flank posture hardens.
End User:
Procurement authority and mission profiles segment budget availability and technical specification stringency.
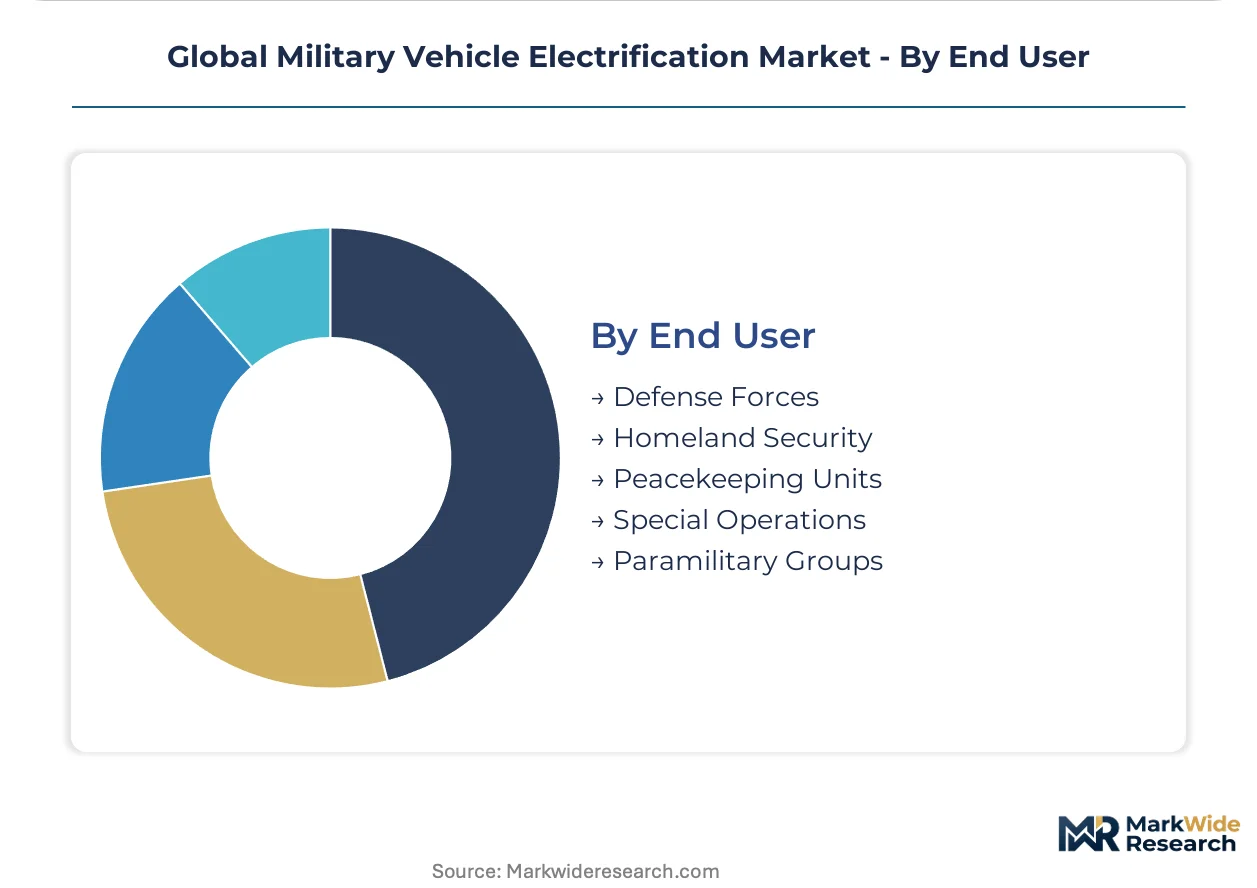
- Defense Forces:National military services drive volume through multi-year platform programs with captive maintenance infrastructure.
- Homeland Security:Border patrol and critical infrastructure protection agencies prioritize commercial-derivative electrification for cost containment.
- Peacekeeping Units:UN and coalition deployments favor interoperability with host-nation charging standards.
- Special Operations:Low-visibility missions demand silent mobility and reduced thermal signature, accelerating full battery-electric trials.
- Paramilitary Groups:State-sponsored irregular forces access electrification through dual-use commercial platforms.
Defense Forces retain the dominant procurement volume, though Special Operations are advancing adoption fastest due to signature-sensitive mission requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers in NATO-aligned nations concentrate demand for hybrid tactical trucks and armored electrification platforms. The United States, Germany, and South Korea anchor development spending through operational energy mandates and export financing mechanisms. Battery supply security and STANAG certification timelines shape cross-border market access.
United States
The US Department of Defense's operational energy strategy mandates 50% liquid fuel reduction for forward-deployed forces by 2030. NHTSA emissions frameworks indirectly pressure military suppliers to demonstrate technology transferability from commercial zero-emission programs. GM Defense in Detroit and Oshkosh Corporation in Wisconsin occupy the light tactical segment with commercial-derivative electrification adapted for military duty cycles.
Germany
Rheinmetall AG leverages captive powertrain engineering to anchor European armored vehicle hybridization programs. EU Green Deal defense procurement guidelines embed carbon intensity thresholds into tender evaluations, creating preferential access for electrified platforms. The KBA regulates electromagnetic compatibility validation for 800V architectures deployed in NATO joint programs.
South Korea
Seoul's KODEF export credit agency bundles battery supply guarantees with vehicle platform sales, penetrating Southeast Asian markets. MFDS oversight of battery safety standards aligns with defense procurement specifications for lithium-ion and solid-state chemistries. Hyundai Rotem and Hanwha Defense in the Seoul Capital Area exemplify the convergence of commercial battery scale with military platform integration.
United Kingdom
The UK Ministry of Defence's Multi-Role Vehicle-Protected program emphasizes availability-based contracting where OEMs retain battery asset ownership. BAE Systems sustains transatlantic competitiveness through in-house production of combat-proven electric drive architectures. QinetiQ Group in Farnborough represents the specialist tier providing electromagnetic hardening and thermal management validation services.
France
KNDS consolidates Franco-German armored vehicle electrification through shared development of series-hybrid powertrains for next-generation combat platforms. ANSM regulatory frameworks for battery transport safety intersect with defense logistics requirements for expeditionary deployment. The Auvergne-Rhône-Alpes cluster around Lyon hosts specialized suppliers for silicon carbide power electronics and wide-bandgap semiconductor integration.
Global Military Vehicle Electrification Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers defined by platform complexity and certification burden. The market structures around three archetypes: prime contractors with captive powertrain engineering, commercial-derivative specialists adapting civilian electrification for military duty cycles, and subsystem suppliers providing electromagnetic hardening and thermal management. Consolidation pressures concentrate among mid-tier suppliers frozen out by 18-month STANAG validation timelines. Dominant competitive moves include strategic partnerships for battery supply security and geographic expansion through export credit bundling.
Among European prime contractors, Rheinmetall AG and KNDS exemplify the captive-engineering archetype integrating hybrid powertrains into armored platform development. BAE Systems occupies a transatlantic position bridging UK availability-based contracting with US operational energy mandates. GM Defense represents the commercial-derivative specialists leveraging civilian battery scale for light tactical vehicle electrification.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Rheinmetall AG |
| BAE Systems |
| KNDS |
| Textron |
| Oshkosh Corporation |
| GM Defense |
| QinetiQ Group |
| General Dynamics Land Systems |
| Others |
Cost & Logistics Intelligence
Chilean and Australian lithium hydroxide processing concentration funnels margin capture toward defense prime contractors with captive battery lifecycle management, while mid-tier suppliers face cost compression from 18-month STANAG certification timelines that freeze rapid iteration.
Pricing Analysis
Certification level (STANAG 4569 electromagnetic compatibility tier) creates the primary spread between prime contractor premiums and mid-tier commodity pricing. Contract-based long-term offtake dominates, with price differentiation hinging on ballistic protection grade and after-sales service bundling. Cost compression in the mid-tier is intensifying because frozen suppliers cannot amortize validation costs across sufficient volume. Homeland security agencies exhibit highest price sensitivity due to commercial-derivative mandates, while special operations units prioritize performance over unit economics.
Supply Chain Analysis
Extended payment terms through KODEF export credit facilities and supply-chain finance programs are anchoring South Korean and German prime contractors against lithium supply volatility. Geographic supply concentrates in Chile, Australia, and China for battery-grade lithium hydroxide, with silicon carbide substrates drawing from Japan and the United States. Single-source vulnerability in Chilean brine processing creates structural risk exposure for ITAR-constrained defense contractors. Distribution runs through NATO-aligned joint procurement frameworks with availability-based contracting terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full battery-electric architectures for heavy armor pose a substitution threat to incumbent series-hybrid positions as solid-state thermal management matures, forcing defensive capability investments before technology leapfrogging accelerates.
For Market Incumbents: Build captive powertrain engineering moats through in-house silicon carbide inverter production and STANAG-certified battery enclosure manufacturing. Rheinmetall and BAE Systems demonstrate this path. Secure lithium supply through backward integration into Australian hard-rock mining partnerships or Chilean offtake agreements to offset single-source concentration risk.
For New Entrants and Emerging Players: Unmanned ground vehicle electrification for NATO northern flank logistics represents the most penetrable entry point, with Arctic-hardened solid-state battery architectures commanding specialist premium positioning. Southeast Asian defense procurement through KODEF-financed bundles offers geographic white space previously locked to established primes. Pursue electromagnetic hardening and thermal management validation as service-based entry vectors rather than platform competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier suppliers holding STANAG certification capabilities but lacking captive battery supply. Long-term viability centers on 5-10 year contracting visibility under availability-based OEM-retained ownership models. Watch hydrogen logistics infrastructure deployment rates as the inflection signal for fuel-cell electric architecture acceleration beyond reconnaissance drone applications.
| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 4569 Electromagnetic Hardening Certification | BAE Systems and Rheinmetall leverage 18-month validation cycles to freeze mid-tier competition from NATO procurement pools. |
| Silicon Carbide Power Electronics Integration | Auvergne-Rhône-Alpes semiconductor cluster enables 40% inverter loss reduction fitting armored hull volume constraints. |
| Battery Supply Guarantee Bundling | KODEF export credit agency penetrates Southeast Asian defense markets through Seoul-linked lithium security commitments. |
| Availability-Based Fleet Contracting | UK Ministry of Defence Multi-Role Vehicle-Protected program transfers degradation risk from militaries to OEM balance sheets. |
| Solid-State Thermal Management Development | MFDS-aligned South Korean cell chemistry programs insulate supply chains from REACH-driven electrolyte solvent obsolescence. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across defense procurement officers, battery system engineers, electromagnetic compatibility validation specialists, and powertrain integration leads at prime contractors. Secondary validation drew from NATO STANAG documentation, EPA and NHTSA emissions filings, EU Green Deal defense procurement guidelines, and customs trade data for lithium hydroxide flows. Bottom-up platform deployment estimates triangulated against top-down operational energy mandate spending allocations.
Calibration against historical procurement cycles and announced program timelines anchored projections across the analysis window. Segmentation dimensions modeled include vehicle type, electrification technology architecture, operational environment severity, and end-user procurement authority. CAGRs were derived from slope analysis of technology adoption curves weighted by STANAG certification pipeline visibility. Forecast inputs incorporated solid-state battery thermal runaway containment engineering progress and hydrogen logistics infrastructure deployment rates.
Macroeconomic conditions sit as an overlay; deviation in lithium price volatility, defense budget allocation priorities, or export control regime expansion would shift the trajectory. Forecasts reflect documented assumptions regarding STANAG validation timeline stability and NATO joint procurement framework continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Infantry Fighting Vehicle (IFV) Market
Military Vehicles
Military Tank Container Market
Military Vehicles
Iran Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Military Ground Robots Market
Military Vehicles
Destroyers Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Riot Control Vehicle Market
Military Vehicles
Military Amphibious Vehicle Market
Military Vehicles
Military Trucks Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Combat Support Vehicle Market
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Japan Defense Market
Military Vehicles
Main Battle Tank Market