
 Spain Rotor Blade Market | 2026-2036
Spain Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Rotor Blade Market Analytics
Carbon fiber specification-tier upgrades is reorganizing procurement priorities among Spanish wind farm operators. Siemens Gamesa Renewable Energy SA anchors domestic manufacturing through its Zamora blade facility, leveraging proximity to Iberian onshore projects. LM Wind Power competes on resin-infusion scale, while Vestas Wind Systems A/S extends its service footprint across Extremadura and Aragon installations.
Spain rotor blades are aerodynamic structures typically exceeding 50 meters in length, fabricated from glass-fiber or carbon-fiber reinforced polymers through vacuum-assisted resin transfer molding to convert kinetic wind energy into rotational mechanical force. Horizontal axis configurations dominate installed capacity, with fiber reinforced polymer materials capturing margin pools through weight reduction and fatigue resistance. Resin infusion processes lead manufacturing throughput, while hand layup persists for prototype and repair segments serving niche marine end users.
Spain's Ministry for Ecological Transition enforces blade recyclability targets under extended producer responsibility frameworks, while CE marking and IEC 61400-23 certification govern structural testing protocols for grid-connected installations. The national renewable auction mechanism ties remuneration to domestic content thresholds, reshaping supplier qualification requirements. Stakeholders must track blade length escalation beyond 80 meters and corresponding transport infrastructure constraints across the Meseta Central corridor.
Market Dynamics
Blade length escalation beyond 80 meters is compressing transport logistics across the Meseta Central corridor and forcing manufacturing proximity to installation sites. This dimensional pressure is restructuring supplier qualification requirements under Spain's national renewable auction mechanism.
Growth Catalysts
- Spain's National Integrated Energy and Climate Plan:Mandated renewable capacity additions tighten blade certification standards and sustain replacement demand across Castilla-La Mancha and Galicia.
- Carbon fiber specification-tier upgrades:Wind farm operators are reorganizing procurement priorities toward lighter, fatigue-resistant composite materials for low-wind-speed northern provinces.
- Extended producer responsibility frameworks:The Ministry for Ecological Transition enforces blade recyclability targets that accelerate circular economy infrastructure investment.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margin pools for glass-fiber reinforced polymer production.
- Transport infrastructure constraints:Road and rail clearances across the Iberian peninsula limit blade segment length and inflate last-mile costs.
- CE marking and IEC 61400-23 certification timelines:Structural testing protocols for grid-connected installations extend product qualification cycles by 8-14 months.
Strategic Opportunities
- Blade recycling and material recovery:Thermoset decomposition technologies unlock secondary raw material streams from end-of-life wind assets.
- Domestic content thresholds:National auction remuneration rules favor suppliers with captive manufacturing in Zamora and surrounding industrial clusters.
- Offshore wind pre-positioning:Port infrastructure investments in Bilbao and Ferrol prepare supply chains for next-generation floating platform blades.
Industry Challenges
- Resin-infusion technician scarcity:Vacuum-assisted transfer molding expertise concentrates at LM Wind Power and Siemens Gamesa facilities, constraining workforce mobility.
- Prototype-to-production scaling friction:Hand layup methods persist for repair segments, creating quality consistency gaps against automated infusion lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Rotor Blade Market |
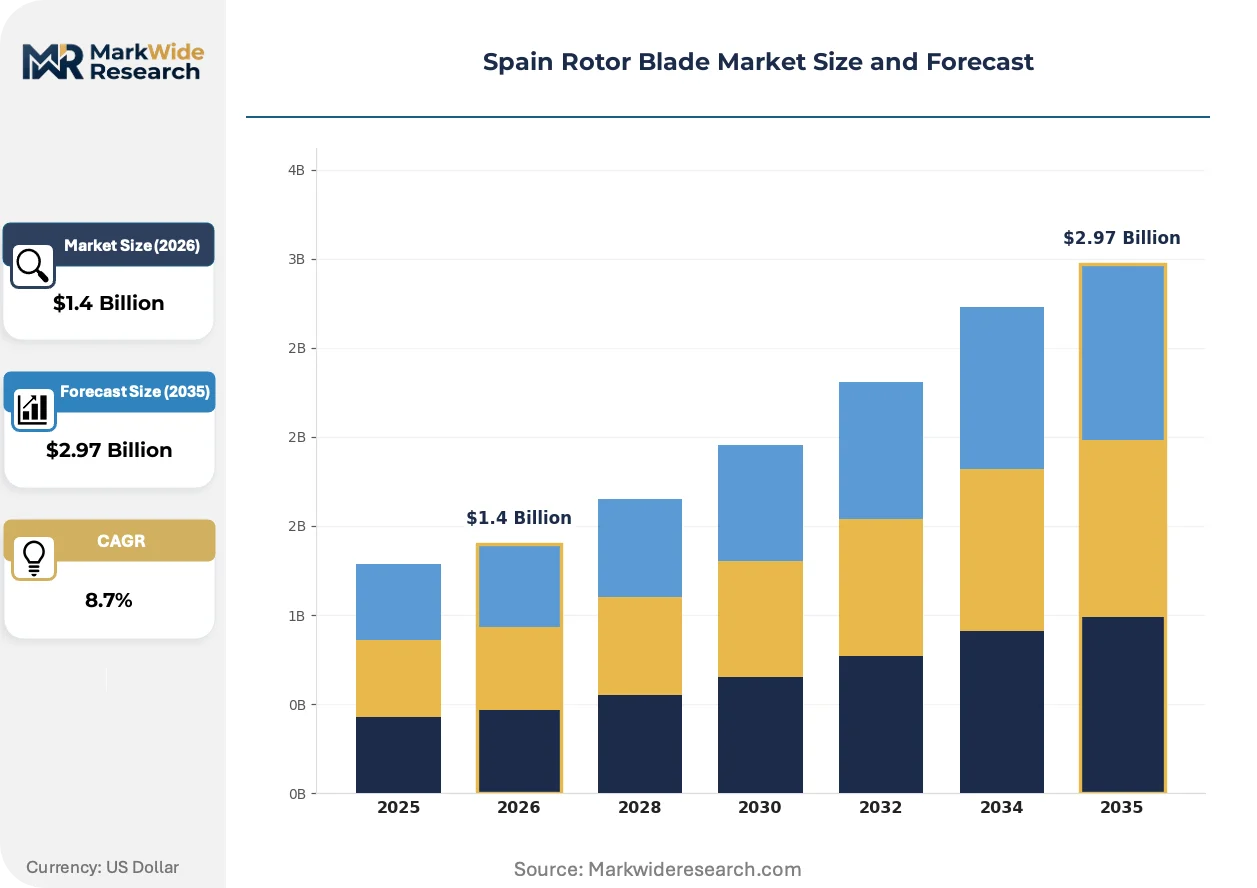
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Ducted Fan, Composite Material Type: Fiber Reinforced Polymer, Aluminum Alloy, Steel, Carbon Fiber End User: Aerospace, Wind Energy, Industrial Machinery, Marine Manufacturing Process: Injection Molding, Hand Layup, Resin Infusion, Machining |
| Companies Covered | Siemens Gamesa Renewable Energy SA, Vestas Wind Systems A/S, LM Wind Power, BayWa r.e. AG, Suzlon Energy Limited, Nordex, Acciona Windpower, TPI Composites, Enercon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Rotor Blade Market Evolving Landscape
Material substitution and manufacturing process intensification are compressing traditional supply chain configurations. Three active developments are restructuring competitive positioning among Spanish blade fabricators and their upstream suppliers.
Carbon fiber reinforcement is decomposing glass-fiber dominance in blades exceeding 60 meters. Onshore wind farm operators in Galicia and Asturias are specifying hybrid layups for low-wind-speed sites. The technology is decomposing legacy resin-to-fiber ratios and forcing retooling investments across Zamora manufacturing corridors.
Spain's Ministry for Ecological Transition is enforcing extended producer responsibility frameworks that mandate blade recyclability targets. Industrial consequence includes mandatory end-of-life collection infrastructure and material traceability systems. Grid-connected installations above 3MW capacity face tightened documentation requirements under domestic content verification protocols.
Service unbundling is fragmenting traditional OEM-aftermarket relationships. Independent blade repair specialists in Extremadura and Aragon are capturing inspection and leading-edge maintenance contracts outside manufacturer service networks. This pattern concentrates in aging onshore fleets where original warranty periods have expired and operators prioritize cost-per-kWh optimization over brand loyalty.
Spain Rotor Blade Market Segmentation
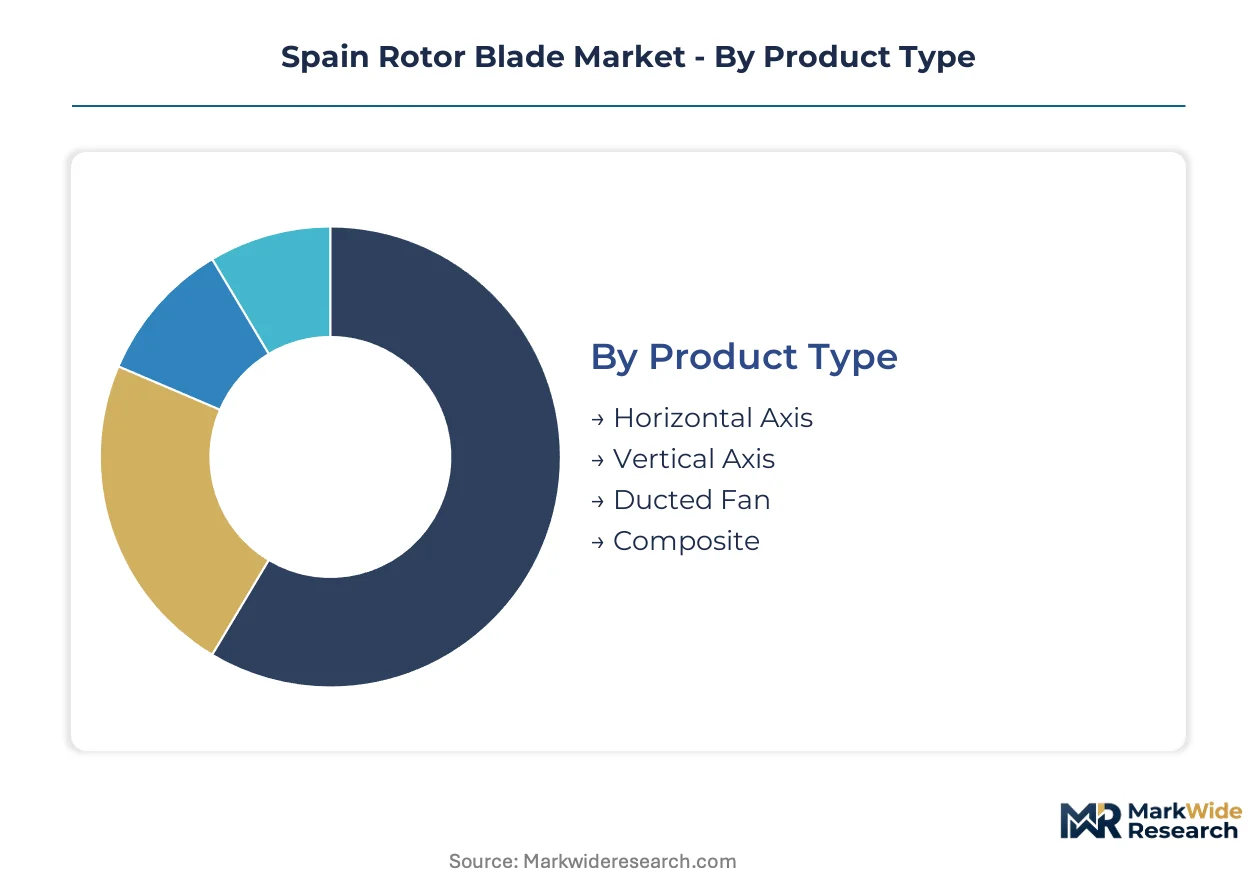
Blade specification tiers in Spain diverge sharply by application physics and certification burden. Material substitution pressures and transport infrastructure constraints reshape which configurations capture procurement budgets across Castilla-La Mancha and Galicia installations.
Product Type:
Horizontal axis configurations face limited substitute threat given their lock-in with grid-scale turbine architectures, while ducted fan designs confront aerodynamic efficiency skepticism from Iberian wind farm operators.
- Horizontal Axis:Dominant aerodynamic architecture for utility-scale installations exceeding 3MW capacity. Demand concentrates across Extremadura and Aragon where Siemens Gamesa and Vestas service networks maintain blade replacement programs for aging onshore fleets.
- Composite:Hybrid material construction combining glass-fiber and carbon-fiber layups for blades surpassing 60 meters. Procurement is tightening in northern provinces where low-wind-speed sites require lighter, fatigue-resistant structures to maintain capacity factors.
- Vertical Axis:Darrieus and Savonius configurations serving distributed generation and urban micro-installations. Niche uptake in industrial self-consumption projects.
- Ducted Fan:Shrouded rotor designs for concentrated wind flow applications. Limited adoption outside prototype marine and building-integrated segments.
Horizontal Axis retains volume leadership; Composite holds the steepest expansion curve.
Material Type:
Cost tier stratification separates commodity glass-fiber from specification-grade carbon fiber, with aluminum and steel occupying repair and legacy replacement niches.
- Fiber Reinforced Polymer:Glass-fiber reinforced polymer remains the baseline specification for onshore blades under 50 meters. Zamora manufacturing corridors process vacuum-assisted resin transfer molding at scale for Iberian projects.
- Carbon Fiber:Specification-tier upgrades for blades exceeding 60 meters and low-wind-speed northern sites. Procurement priorities at Iberdrola and EDP Renewables are reorganizing toward hybrid layups that decompose legacy resin-to-fiber ratios.
- Aluminum Alloy:Repair segment applications and small-scale prototype fabrication. Hand layup methods persist for leading-edge restoration contracts.
- Steel:Structural reinforcement inserts and legacy turbine refurbishment. Declining share as composite fatigue resistance improves.
Fiber Reinforced Polymer dominates installed base volume; Carbon Fiber is climbing the fastest on new capacity additions.
End User:
Application concentration determines blade length, certification intensity, and service lifecycle requirements.
- Wind Energy:Grid-connected installations governed by IEC 61400-23 structural testing and CE marking protocols. Replacement demand is accelerating across Castilla-La Mancha where early 2000s installations approach end-of-design-life.
- Marine:Tidal and offshore wind pre-positioning in Bilbao and Ferrol port clusters. Prototype segments use hand layup methods with thermoset decomposition recovery pathways.
- Aerospace:Wind tunnel testing and small-scale aerodynamic research. Limited commercial scale.
- Industrial Machinery:Ventilation and process cooling applications. Standardized specifications with minimal customization.
Wind Energy commands procurement volume; Marine is gaining share fastest on port infrastructure investments.
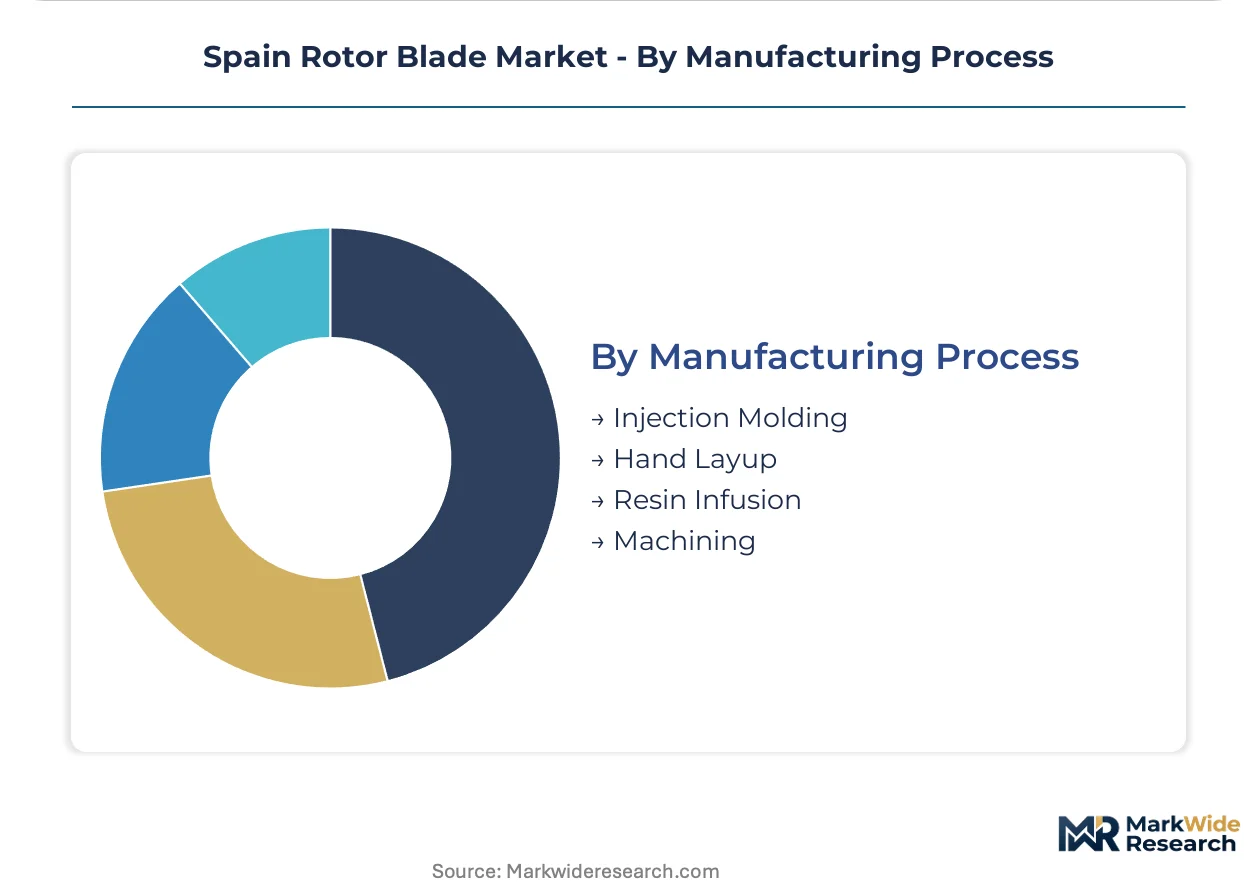
Manufacturing Process:
Volume scale and margin structure separate automated infusion lines from labor-intensive hand layup repair segments.
- Resin Infusion:Vacuum-assisted resin transfer molding dominates throughput at LM Wind Power and Siemens Gamesa Zamora facilities. Technician scarcity constrains workforce mobility across Iberian manufacturing corridors.
- Hand Layup:Prototype fabrication and repair segments serving marine end users. Quality consistency gaps persist against automated infusion lines.
- Injection Molding:Small-component and insert production. Limited to structural hardware and root attachment systems.
- Machining:Root segment finishing and precision balancing operations. Post-cure processing for blade assembly integration.
Resin Infusion anchors production volume; Hand Layup maintains repair segment margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Spanish sub-regions, with northern provinces prioritizing performance specifications for low-wind-speed sites while central regions emphasize logistics cost containment for blade replacement programs.
Castilla-La Mancha
Early 2000s wind farm installations are approaching end-of-design-life, triggering accelerated blade replacement procurement. Spain's National Integrated Energy and Climate Plan mandates renewable capacity additions that tighten certification standards for grid-connected assets. The Meseta Central corridor hosts aging onshore fleets where Siemens Gamesa service networks maintain active maintenance contracts.
Galicia
Low-wind-speed sites in northern provinces are driving specification-tier upgrades toward hybrid carbon-glass fiber layups. The Ministry for Ecological Transition enforces extended producer responsibility frameworks that mandate blade recyclability targets. Port clusters in Ferrol are pre-positioning supply chain infrastructure for next-generation offshore wind developments.
Extremadura
Independent blade repair specialists are capturing inspection and leading-edge maintenance contracts outside OEM service networks. CE marking and IEC 61400-23 certification protocols govern structural testing timelines for grid-connected installations above 3MW capacity. Aging onshore fleets in this region prioritize cost-per-kWh optimization over manufacturer brand loyalty.
Aragon
Vestas Wind Systems extends its service footprint across installations requiring post-warranty maintenance and component replacement. Domestic content thresholds under national renewable auction mechanisms reshape supplier qualification requirements for remuneration eligibility. Manufacturing proximity to installation sites is compressing transport logistics costs for blade segment delivery.
Basque Country
Port infrastructure investments in Bilbao prepare supply chains for floating platform blade pre-assembly and staging operations. Thermoset decomposition technologies for end-of-life material recovery are attracting circular economy infrastructure investment. Marine end users in this coastal region utilize hand layup methods for prototype tidal energy blade segments.
Spain Rotor Blade Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated OEMs controlling resin-infusion scale while independent specialists capture repair segment margins. The market structure concentrates around three strategic tiers: captive manufacturing arms of global turbine manufacturers, independent blade fabricators competing on material substitution timing, and regional service specialists unbundling aftermarket relationships. Dominant competitive moves include backward integration into carbon fiber supply chains and geographic co-location of manufacturing with high-volume installation corridors.
Within the integrated OEM tier, Siemens Gamesa Renewable Energy SA and Vestas Wind Systems A/S exemplify archetypes combining manufacturing scale with captive service networks. LM Wind Power occupies a position representing independent fabrication specialists competing on resin-infusion throughput. These three anchors illustrate how supplier qualification under Spain's domestic content thresholds favors entities with established manufacturing presence in Iberian industrial clusters.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy SA |
| Vestas Wind Systems A/S |
| LM Wind Power |
| BayWa r.e. AG |
| Suzlon Energy Limited |
| Nordex |
| Acciona Windpower |
| TPI Composites |
| Enercon |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Iberian wind farm operators and Zamora-based manufacturers lock in resin-infusion capacity and provide visibility on carbon fiber pricing through the National Integrated Energy and Climate Plan implementation window. This contractual architecture concentrates procurement leverage with Siemens Gamesa and LM Wind Power while exposing independent repair specialists to spot-market epoxy volatility.
Pricing Analysis
Spain's Ministry for Ecological Transition dictates the pricing tier structure through domestic content thresholds that tie auction remuneration to manufacturing location. Three-tier pricing separates CE-marked premium blades from standard IEC-certified units and economy repair segments, with certification intensity driving the widest spreads. Cost compression in glass-fiber reinforced polymer tiers is intensifying because petrochemical feedstock fluctuations compress margin pools. Utility-scale operators in Castilla-La Mancha exhibit lowest price sensitivity due to replacement urgency, while distributed generation projects in Aragon prioritize cost-per-kWh optimization.
Supply Chain Analysis
Port congestion at Bilbao and container availability constraints on Atlantic trade lanes elevate inbound logistics costs for carbon fiber pre-preg shipments from Germany and Japan. Raw material sourcing draws from German epoxy resin suppliers, Japanese carbon fiber producers, and Portuguese glass-fiber operations, with Zamora manufacturing corridors processing vacuum-assisted resin transfer molding at scale. Single-source vulnerability concentrates in specialized resin-infusion technician pools. Distribution runs through captive OEM service networks for grid-connected installations above 3MW, while independent specialists capture leading-edge maintenance contracts outside manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's rotor blade market functions as a service-attach opportunity where inspection and leading-edge maintenance contracts expand faster than new blade manufacturing as aging fleets in Extremadura and Aragon exhaust original warranty periods.
For Market Incumbents: Fortify resin-infusion technician retention through apprenticeship pipelines anchored at Zamora facilities, countering workforce mobility constraints that threaten throughput at LM Wind Power and Siemens Gamesa plants. Deepen backward integration into carbon fiber supply chains to offset specification-tier upgrade costs imposed by low-wind-speed site operators in Galicia. Channel control through captive service networks remains the critical defensive lever against independent repair specialists capturing post-warranty maintenance contracts.
For New Entrants and Emerging Players: CE marking fast-track programs for blades under 50 meters unlock procurement eligibility for grid-connected installations facing compressed certification timelines. Target the marine prototype segment in Basque Country port clusters where hand layup methods persist and thermoset decomposition recovery pathways create circular economy differentiation. Position through material traceability systems that satisfy extended producer responsibility frameworks before larger competitors complete compliance infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward independent blade fabricators with established resin-infusion scale and proximity to Meseta Central transport corridors. Long-term viability across the analysis window hinges on positioning for offshore wind pre-positioning in Ferrol and Bilbao port infrastructure investments. Watch blade length escalation beyond 80 meters as the inflection signal forcing manufacturing co-location with installation sites and restructuring supplier qualification under national auction mechanisms.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Specification Upgrade | Hybrid layups for low-wind-speed Galicia sites decompose legacy resin-to-fiber ratios and force retooling investments. |
| Blade Recycling Infrastructure Buildout | Thermoset decomposition technologies unlock secondary raw material streams from end-of-life Castilla-La Mancha assets. |
| Technician Apprenticeship Pipeline | Vacuum-assisted resin transfer molding expertise concentrates at Zamora facilities, constraining workforce mobility across Iberian corridors. |
| Port Infrastructure Pre-positioning | Bilbao and Ferrol staging operations prepare supply chains for floating platform blade segments in offshore wind. |
| Domestic Content Threshold Compliance | National auction remuneration rules favor suppliers with captive manufacturing in Zamora industrial clusters. |
Research Methodology
Cross-validation between primary interviews with wind farm operators, resin-infusion technicians, and Ministry for Ecological Transition policy officers anchors the qualitative findings against secondary validation from IEC certification databases, customs trade records, and national renewable auction mechanism disclosures. Bottom-up triangulation across manufacturing throughput data from Zamora facilities and top-down demand modeling from Castilla-La Mancha replacement programs ensures coverage of both supply-side capacity constraints and demand-side procurement patterns.
Sensitivity analysis around epoxy resin price volatility and carbon fiber specification-tier adoption rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include blade length tiers, material composition ratios, manufacturing process types, and regional grid-connection capacity classes. CAGRs derive from compound annual growth trajectory analysis applied to replacement demand cycles and new capacity additions under the National Integrated Energy and Climate Plan. Industry-specific inputs incorporate blade recyclability target compliance costs and transport infrastructure clearance constraints across the Meseta Central corridor.
Underlying assumptions cover sustained auction mechanism remuneration rules and resin-infusion technician supply stability, with deviation risk concentrated in petrochemical feedstock price shocks and CE marking timeline extensions. Recalibration cycles align with material shifts in blade length escalation thresholds and circular economy infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Aircraft Structural Health Monitoring Access Panels Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Aircraft Exterior Structure Digital Twin Platforms Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market