
 Aerospace and Defense C-Class Parts Market | 2026-2036
Aerospace and Defense C-Class Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense C-Class Parts Market Analysis
Performance-based logistics contracting is pivoting how defense agencies procure C-class parts, bundling hardware with lifecycle support rather than transactional spare orders. Safran SA leverages its European MRO network to anchor aftermarket service revenue streams. Precision Castparts Corporation sustains manufacturing scale through backward integration into titanium forging. SKF Group differentiates via sensor-integrated bearing systems that enable predictive maintenance contracts.
Aerospace and Defense C-Class Parts encompass low-unit-cost, high-volume consumables including fasteners, gaskets, seals, and bearings manufactured to exacting tolerances typically below 0.001 inch, with primary purpose being structural joining, environmental sealing, and friction reduction across airframes and propulsion systems. Fasteners constitute the largest volume pool given their pervasive use in airframe assembly, while bearings command premium positioning due to material specifications and qualification cycles. Titanium material grades are gaining share in fasteners and seals as platforms prioritize weight reduction without sacrificing fatigue resistance.
FAA airworthiness directives and DFARS supply chain traceability mandates shape procurement protocols for C-class parts sold into US defense programs, while REACH substance restrictions in Europe constrain seal elastomer formulations and surface treatment chemistries. AS9100 quality management standards enforced by prime OEMs function as de facto market access gates for tier suppliers. Stakeholders must monitor evolving conflict-mineral sourcing rules and digital thread requirements that will determine which suppliers retain qualified status on next-generation platforms.
Market Dynamics
Performance-based logistics contracting is consolidating procurement authority into fewer prime integrators, compressing supplier margins while extending contract durations across NATO military aircraft programs.
Growth Catalysts
- F-35 sustainment scale-up:The Pentagon's largest fighter program generates recurring demand for titanium fasteners and seals through centralized supply agreements with tier-one distributors.
- REACH substance phase-outs:ECHA restrictions on hexavalent chromium surface treatments are forcing coating technology upgrades that favor qualified European suppliers with certified alternatives.
- Additive qualification pathways:FAA approval of powder-bed fusion for non-structural brackets is creating new manufacturing routes for low-volume legacy aircraft spares.
Market Restraints
- Titanium sponge volatility:Russian and Chinese supply concentration exposes fastener manufacturers to input cost swings exceeding 30 percent within single contract periods.
- DFARS traceability mandates:Pentagon supply chain documentation requirements add 12-18 month qualification timelines for new bearing suppliers entering defense programs.
- Polymer seal substitution limits:Fluorocarbon elastomer performance ceilings in cryogenic fuel systems prevent material downgrades even when commodity prices spike.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme for aerospace components creates tariff-protected manufacturing slots for foreign joint ventures producing AS9100-certified hardware.
- Digital thread integration:Model-based definition standards are converging with blockchain pedigree tracking to enable automated sourcing decisions for routine consumables.
- UAM airframe buildouts:Urban air mobility prototypes require lightweight fastener counts 3-4x higher per airframe than conventional helicopters, opening volume positions for certified suppliers.
Industry Challenges
- Metallurgical talent scarcity:Titanium forging expertise is concentrating among retiring workforces in California and Texas clusters, constraining capacity expansion timelines.
- Legacy platform documentation gaps:Cold War-era aircraft lack complete digital bills of material, forcing reverse-engineering costs that erode margins on low-volume seal replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense C-Class Parts Market |
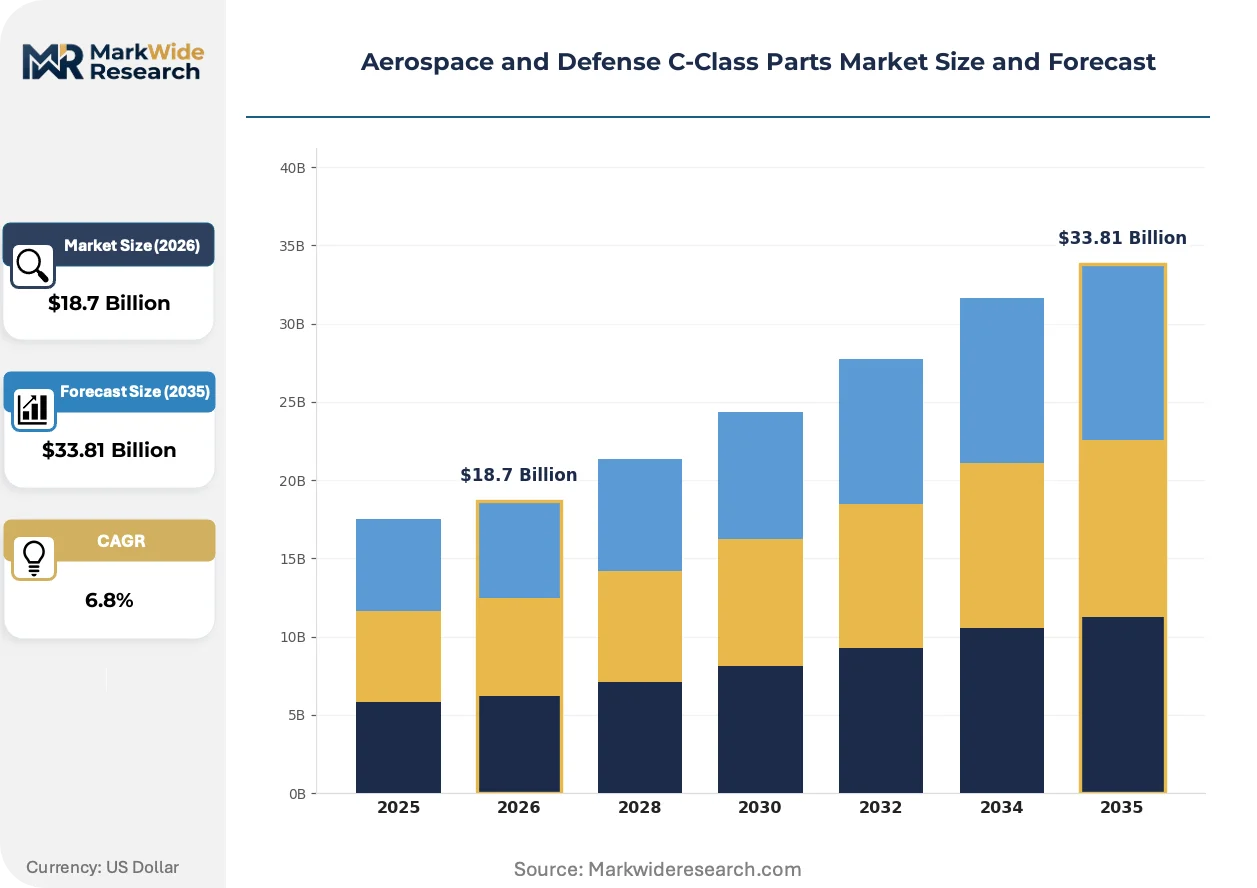
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fasteners, Gaskets, Seals, Bearings Application: Aerospace, Defense, Space Exploration, Unmanned Vehicles Material: Aluminum, Steel, Titanium, Composite End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Integrators |
| Companies Covered | Precision Castparts Corporation, Amphenol Corporation, Arconic Inc., Stanley Black & Decker, Inc., Safran SA, Raytheon Technologies Corporation, NTN Corporation, RBC Bearings Incorporated, SKF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense C-Class Parts Market Emerging Trajectories
Digital manufacturing protocols and predictive maintenance architectures are rewriting qualification requirements for consumable hardware, privileging suppliers with sensor integration capabilities.
Additive manufacturing of titanium bracketry is converging with topology optimization software to produce weight-optimized alternatives to machined legacy parts. Bell Textron and Joby Aviation are qualifying these components for eVTOL primary structures under compressed FAA certification timelines. The technology is converging with automated post-process inspection to reduce touch labor in low-volume production environments.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling seal manufacturers to reformulate fluorocarbon compounds for fuel system applications. ECHA enforcement actions against non-compliant imports are tightening European supply gates. Aerospace OEMs with European final assembly lines are accelerating supplier audits to preempt line-stop risks from material non-conformances.
Consolidated inventory management through prime-led supplier portals is displacing transactional spot-buying for routine consumables. Lockheed Martin and Boeing are mandating vendor-managed inventory programs that shift carrying costs onto tier-two distributors. The practice is most advanced in Texas-based military aircraft sustainment hubs where real-time consumption data feeds automated replenishment algorithms.
Aerospace and Defense C-Class Parts Market Segmentation
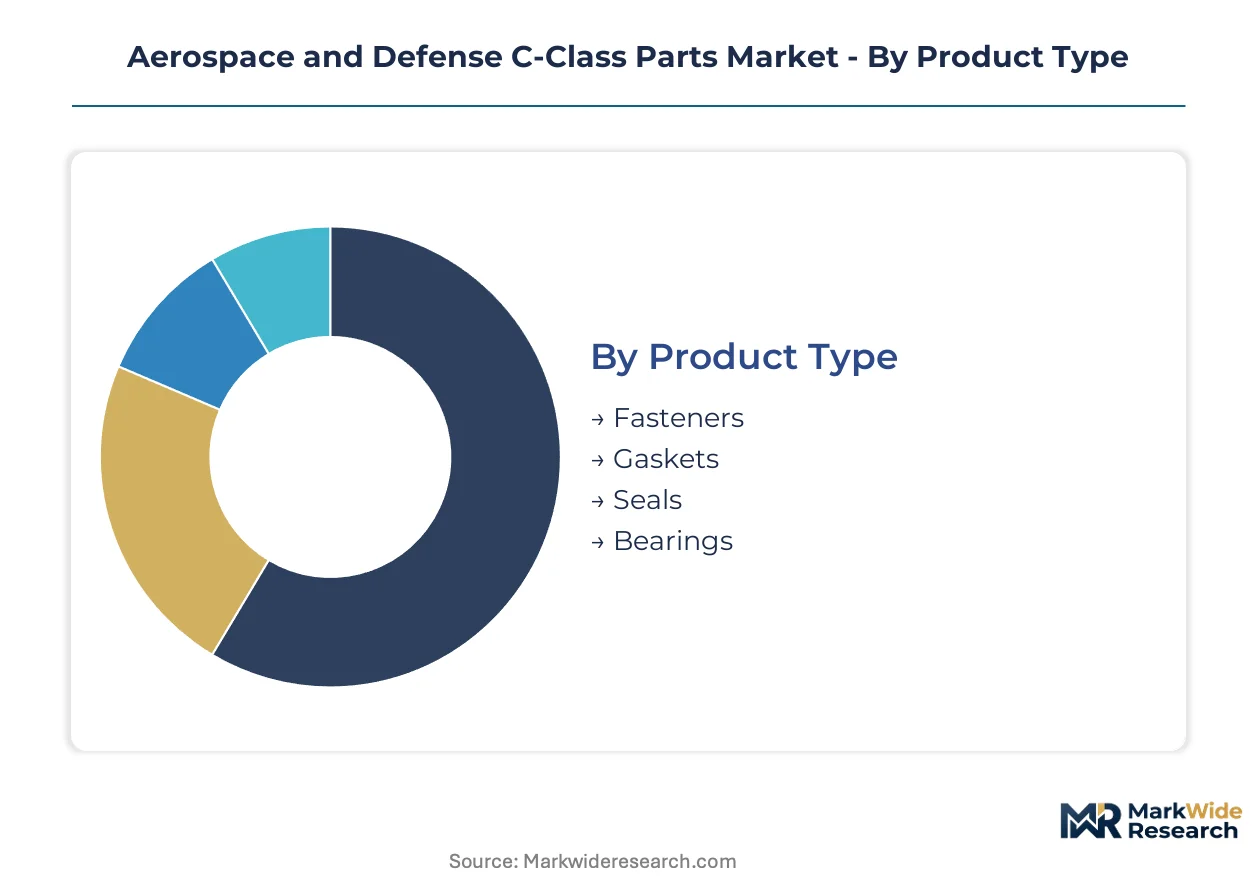
C-class parts procurement patterns diverge sharply across product categories and end-use applications. Upgrade cycles for legacy military platforms and next-generation commercial aircraft create asynchronous demand pulses that suppliers must navigate.
Product Type:
Replacement intensity varies by component durability and platform utilization rates, with high-cycle landing gear and engine zones driving faster hardware turnover than structural assemblies.
- Fasteners:Titanium and corrosion-resistant steel variants dominate airframe joining applications, with threaded and blind rivet configurations specified by Boeing and Lockheed Martin assembly protocols. Demand concentrates in Texas and California aerospace clusters where F-35 and commercial narrowbody production lines operate at full capacity; REACH-compliant surface treatments are becoming mandatory for European-qualified suppliers.
- Bearings:Precision-ground rolling-element designs handle radial and thrust loads across landing gear, engine spools, and flight control actuators, with material grades certified to AMS aerospace specifications. Sensor-integrated smart bearings are gaining traction in predictive maintenance contracts across NATO military fleets; qualification timelines stretch 18-24 months for new entrants.
- Gaskets:Metallic and elastomeric sealing interfaces prevent fluid leakage in fuel, hydraulic, and environmental control systems.
- Seals:Dynamic lip and static compression designs manage pressure differentials and contamination exclusion across propulsion and airframe penetrations.
Volume placements concentrate in fasteners; the faster expansion belongs to bearings.
Application:
Mission profiles and regulatory exposure create distinct procurement rhythms across operating environments.
- Aerospace:Commercial airframe OEMs specify high-cycle fatigue-resistant hardware for narrowbody and widebody production, with single-aisle platforms consuming 60-70% of fastener volumes per shipset. FAA airworthiness directives mandate traceable pedigree documentation; Boeing and Airbus supplier portals now enforce AS9100-certified digital thread compliance.
- Defense:Military aircraft sustainment programs generate recurring demand for consumable hardware through performance-based logistics contracts. Pentagon centralized procurement for F-35, F-15, and F/A-18 fleets funnels orders through Lockheed Martin and Boeing tier-one distributors; DFARS traceability mandates extend supplier qualification timelines.
- Space Exploration:Launch vehicle and satellite hardware faces extreme thermal cycling and vacuum exposure requirements.
- Unmanned Vehicles:UAV and UAS platforms prioritize weight-optimized fastener counts for extended endurance missions.
Defense applications anchor current procurement volumes; aerospace is climbing the fastest as narrowbody production rates recover.
Material:
Weight-performance tradeoffs and corrosion resistance specifications determine material selection across platform generations.
- Titanium:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades deliver strength-to-weight ratios critical for engine mounts, landing gear, and control surfaces. Russian and Chinese sponge supply concentration exposes fastener manufacturers to input cost volatility exceeding 30% within contract periods; domestic forging capacity in California and Texas clusters is tightening.
- Steel:Corrosion-resistant and high-strength low-alloy grades serve structural applications where fatigue life outweighs weight penalties. Cadmium plating restrictions under REACH Annex XVII are forcing European suppliers toward zinc-nickel and ion vapor deposition alternatives; qualification costs favor incumbent producers with certified coating lines.
- Aluminum:2024-T3 and 7075-T6 alloys provide cost-effective solutions for secondary structures and interior hardware.
- Composite:Carbon fiber-reinforced polymer brackets and fittings address galvanic corrosion concerns in mixed-material assemblies.
Steel retains the largest installed base; titanium is gaining share fastest as next-generation platforms prioritize weight reduction.
End User:
Procurement authority consolidation and inventory liability shifts are restructuring supplier relationships across the value chain.
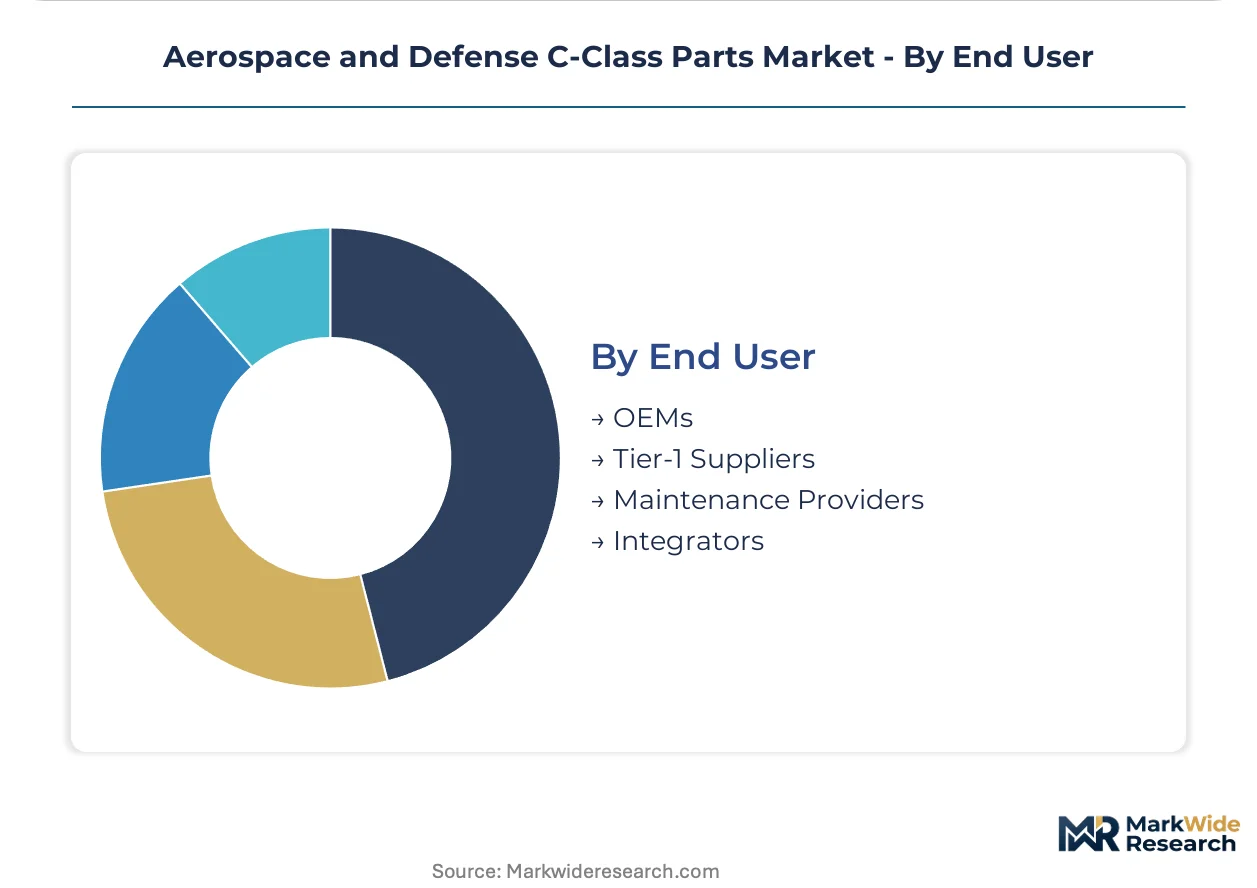
- OEMs:Boeing, Airbus, Lockheed Martin, and Northrop Grumman specify qualified hardware for new production airframes, with vendor-managed inventory programs transferring carrying costs to tier-two distributors. Real-time consumption data from Texas-based military sustainment hubs feeds automated replenishment algorithms.
- Maintenance Providers:MRO operators and airline engineering departments source rotable and expendable hardware for depot-level overhaul and line maintenance. Safran's European MRO network anchors aftermarket service revenue through long-term component availability agreements; predictive maintenance sensor integration is becoming a competitive differentiator.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace sub-tier procurement of qualified hardware for major assemblies.
- Integrators:System-level contractors bundle C-class parts with avionics and structural modules for platform final assembly.
Procurement concentration sits with OEMs; maintenance providers are expanding fastest as fleet ages extend MRO demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established aerospace clusters while consumption spreads across NATO military modernization programs and recovering commercial narrowbody build rates. The United States and France host the dominant manufacturing bases, with procurement authority fragmenting across defense ministries and airline engineering departments.
United States
The Pentagon's F-35 sustainment program and commercial narrowbody recovery at Boeing anchor titanium fastener demand. FAA airworthiness directives and DFARS traceability mandates shape supplier qualification protocols. Texas and California aerospace clusters concentrate forging capacity and tier-one distribution networks serving military sustainment hubs.
France
Safran's European MRO network and Airbus final assembly lines generate recurring seal and bearing procurement. ECHA REACH restrictions on hexavalent chromium surface treatments compel coating technology upgrades. The Toulouse and Paris aerospace corridors host qualified suppliers with certified alternative chemistries.
Germany
MTU Aero Engines and Liebherr-Aerospace drive precision bearing demand for propulsion and flight control systems. The EU Green Deal and CSRD reporting requirements tighten supply chain carbon disclosure standards. Bavaria and Baden-Württemberg precision engineering clusters specialize in AMS-certified rolling-element designs.
United Kingdom
BAE Systems military aircraft programs and Rolls-Royce engine spares sustain consumable hardware volumes. UK Export Control regulations and post-Brexit customs procedures add documentation layers to continental supply chains. The Midlands aerospace cluster maintains legacy platform documentation and reverse-engineering capabilities for Cold War-era seal replacements.
India
Defense indigenization under the PLI scheme for aerospace components creates tariff-protected manufacturing slots for foreign joint ventures. BIS certification and AS9100 quality standards function as market access gates. The Bangalore and Hyderabad aerospace clusters host emerging fastener and bearing production for domestic military programs.
Aerospace and Defense C-Class Parts Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the C-class parts spectrum, with integrated forgers and specialized distributors occupying distinct value chain positions. The market structure tilts toward consolidation at the prime integrator level while fragmenting across tier-two and tier-three hardware specialists. Three archetypes dominate: backward-integrated titanium forgers, sensor-integrated bearing specialists, and European MRO-anchored service providers. Competitive moves center on performance-based logistics contracting and vendor-managed inventory programs that shift carrying costs downstream.
Within the integrated forging tier, Precision Castparts Corporation and Safran SA exemplify divergent geographic anchoring strategies. SKF Group occupies a position in the sensor-integrated bearing archetype, representing the predictive maintenance pivot reshaping aftermarket service contracts. These three entities illustrate how scale, certification depth, and service bundling separate sustainable positions from transactional commodity supply.
| Leading Market Players |
|---|
| Precision Castparts Corporation |
| Amphenol Corporation |
| Arconic Inc. |
| Stanley Black & Decker, Inc. |
| Safran SA |
| Raytheon Technologies Corporation |
| NTN Corporation |
| RBC Bearings Incorporated |
| SKF Group |
| Others |
Supply Flow & Price Mechanics
Titanium sponge feedstock from Russian and Chinese smelters cascades through forging mills in Texas and California into three-tier pricing structures across premium, standard, and economy certification grades. DFARS traceability mandates and REACH-compliant surface treatment investments amplify cost differentials between qualified defense suppliers and commercial-grade competitors.
Pricing Analysis
Cost-down pressure on tier-two distributors accelerates as Lockheed Martin and Boeing vendor-managed inventory programs transfer carrying costs downstream. Pricing stratifies across premium, standard, and economy tiers based on AS9100 certification depth and DFARS pedigree documentation completeness. Aerospace OEMs exhibit lowest price sensitivity given airworthiness liability exposure, while commercial maintenance providers face acute margin compression from consolidated procurement portals. Titanium input volatility exceeding 30 percent within contract periods squeezes fastener manufacturer margins most severely.
Supply Chain Analysis
Regional distribution centers in Texas and California aerospace clusters anchor hub-and-spoke fulfillment patterns serving Pentagon sustainment hubs and Boeing production lines. Supply concentrates in the United States, France, and Germany, with titanium forging capacity tethered to California and Texas metallurgical expertise pools. Raw material dependencies on Russian and Chinese titanium sponge, fluorocarbon elastomer feedstocks, and AMS-certified steel grades create single-source vulnerability exposure. Distribution runs through prime-led supplier portals displacing transactional spot-buying for routine consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where DFARS qualification timelines and REACH compliance investments force sub-scale suppliers toward exit or acquisition.
For Market Incumbents:Cement market position through backward integration into titanium forging capacity in Texas and California clusters to insulate against sponge volatility. Deepen certification moats by pre-empting digital thread and blockchain pedigree requirements before FAA mandates harden. Sensor-integrated bearing capabilities represent the priority defensive lever against predictive maintenance competitors.
For New Entrants and Emerging Players:Enter via India's PLI scheme for aerospace components, where tariff-protected manufacturing slots reward AS9100-certified joint ventures with domestic defense primes. Urban air mobility fastener demand offers the most penetrable volume position given eVTOL airframe fastener counts 3-4x conventional helicopters. Lead with additive manufacturing qualification pathways for legacy aircraft spares to bypass forging capacity constraints.
For Investors and Strategic Acquirers:European MRO network expansion by Safran is the leading indicator that aftermarket service bundling will outpace transactional hardware margins over the projection horizon. Target acquisition candidates with sensor-integrated bearing portfolios and established NATO military fleet contracts. Watch for titanium sponge price inflection signals as Russian supply disruption risk materializes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Forging | Captive sponge-to-fastener supply chains insulate Precision Castparts from Russian input volatility. |
| Sensor-Integrated Bearing Development | SKF Group's smart bearing systems anchor predictive maintenance contracts across NATO fleets. |
| REACH-Compliant Coating Certification | Hexavalent chromium alternatives qualify European suppliers for Airbus and Safran procurement portals. |
| Vendor-Managed Inventory Expansion | Lockheed Martin programs shift carrying costs onto tier-two distributors in Texas sustainment hubs. |
| Digital Thread Integration | Model-based definition standards converge with blockchain pedigree tracking for automated sourcing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with supply chain directors, MRO procurement managers, and quality assurance leads at tier-one distributors with secondary validation from FAA airworthiness directives, ECHA REACH substance restrictions, and DFARS traceability mandates. Bottom-up and top-down triangulation cross-checked production capacity estimates against Pentagon program office procurement disclosures and commercial narrowbody build rate projections.
Segment-level modeling captured product type granularity across fasteners, bearings, gaskets, and seals; application splits across aerospace, defense, space exploration, and unmanned vehicles; material grades spanning titanium, steel, aluminum, and composites; and end-user channels from OEM vendor-managed inventory to maintenance provider spot-buying. CAGRs were derived from production rate elasticities, fleet age demographics, and platform-specific hardware intensity factors across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under titanium sponge supply disruption or accelerated REACH substance phase-out timelines. Forecasts reflect documented assumptions regarding F-35 sustainment scale-up, narrowbody production recovery trajectories, and additive manufacturing qualification velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market