
 Aviation Electro Optical Systems Market | 2026-2036
Aviation Electro Optical Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Electro Optical Systems Market Analysis
Aftermarket service revenue for electro-optical sensor calibration and mission-computer integration is tilting toward platform-agnostic sustainment contracts. Northrop Grumman Corporation leverages its position in distributed aperture systems to capture long-term service obligations across multiple airframes. Lockheed Martin Corporation anchors its electro-optical portfolio through captive integration with the F-35's electro-optical targeting system. Raytheon Technologies Corporation competes on thermal weapon sight refurbishment and depot-level sensor overhaul for legacy rotary-wing fleets.
Aviation electro optical systems integrate photodetectors, stabilized gimbals, and digital signal processors to convert electromagnetic radiation across visible, infrared, and laser wavelengths into actionable imagery or targeting data, typically operating at frame rates exceeding 30 Hz with micro-radian stabilization precision for high-dynamic flight environments. Their primary purpose spans passive surveillance, active laser designation, and all-weather pilotage in both military combat operations and commercial enhanced flight vision applications. Infrared Sensors command the largest product-type allocation due to their ubiquity in missile warning and navigation systems, while Multispectral technology within the technology dimension attracts premium positioning for counter-stealth and decoy-discrimination missions. The Defense application segment sustains the deepest procurement cycles, though Commercial Aviation end users are emerging as a structurally distinct demand pool as EVS-certified installations expand beyond business jets into narrow-body transport categories.
The US FAA mandates electro-optical minimum equipment standards through technical standard orders, while the EU's CE marking framework governs dual-use export classifications for European-origin systems. Israel's national regulator enforces sovereign technology-transfer protocols that condition foreign sales of domestically developed electro-optical components. Stakeholders must monitor how divergent national de minimis rules on foreign content affect cross-border supply arrangements for gimbal assemblies and cooled infrared detectors.
Market Dynamics
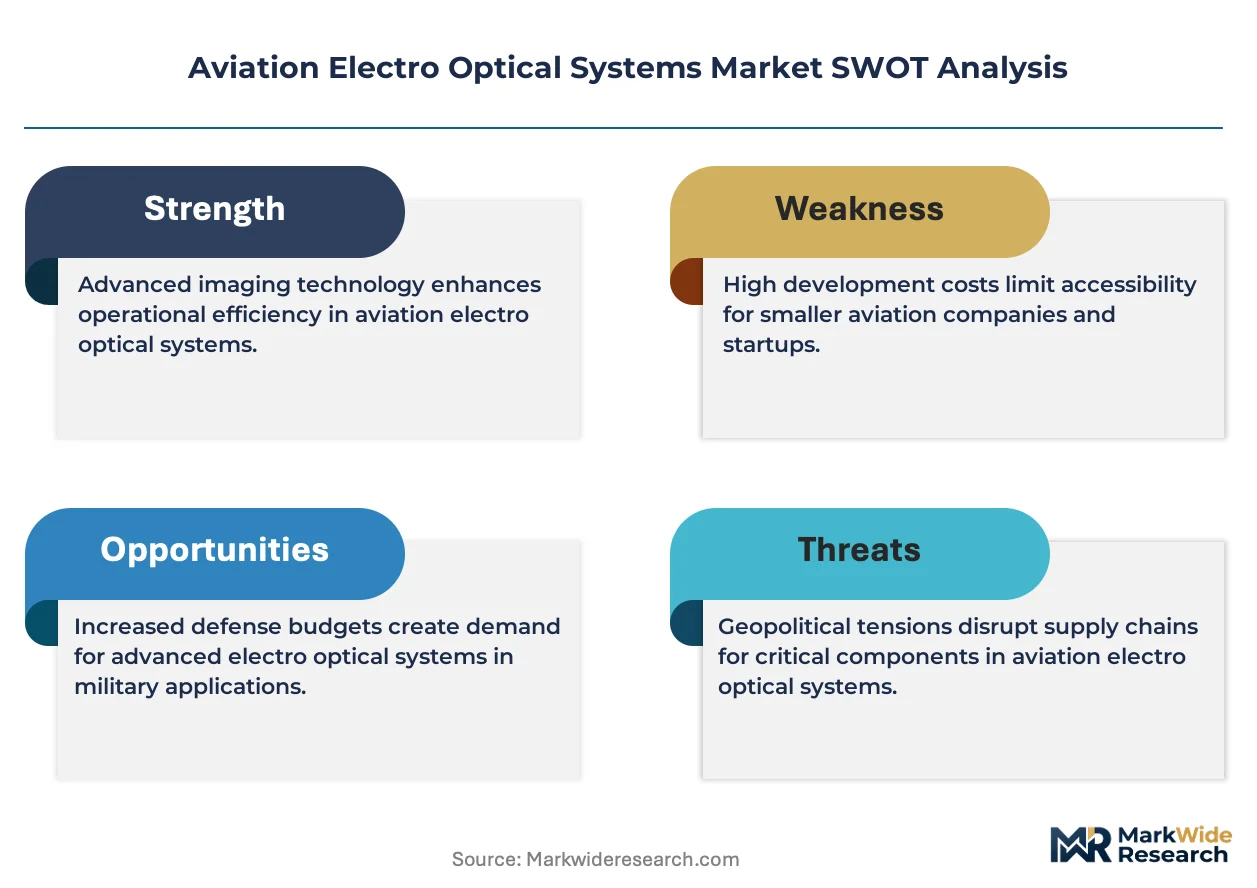
The aviation electro optical systems market pivots on sovereign manufacturing mandates that restrict cross-border technology transfer for cooled infrared detectors and stabilized gimbal assemblies. NATO defense procurement directives and FAA airworthiness standards are compressing supplier qualification timelines while fragmenting certification pathways across jurisdictions.
Growth Catalysts
- FAA Enhanced Vision Mandates:Technical Standard Orders for commercial EVS certification are forcing OEM integration of infrared sensor suites into narrow-body transport categories.
- Israeli Sovereign Transfer Protocols:Domestic content requirements for electro-optical components are expanding local production capacity and creating export-conditioned supply hubs.
- Next-Generation Fighter Sensor Suites:NATO-aligned military procurement of distributed aperture systems is driving demand for multispectral imaging and laser designation capabilities.
Market Restraints
- Cooled Detector Supply Concentration:Mercury-cadmium-telluride focal plane array production concentrates in three sovereign defense industrial bases, creating single-source fragility.
- Dual-Use Export Classification Friction:EU CE marking frameworks and US ITAR regulations impose divergent documentation burdens on gimbal assembly cross-border shipments.
- Micro-Radian Stabilization Talent Scarcity:Precision mechanical engineering expertise for airborne gimbal design pools in Israel, France, and select US defense corridors.
Strategic Opportunities
- Platform-Agnostic Sustainment Contracts:Aftermarket service revenue for sensor calibration and mission-computer integration is migrating toward multi-airframe service obligations.
- Commercial EVS Penetration:FAA-certified enhanced flight vision installations are expanding beyond business jets into single-aisle transport categories.
- Counter-Stealth Multispectral Convergence:Fusion of short-wave infrared and laser rangefinding technologies is opening decoy-discrimination applications against low-observable platforms.
Industry Challenges
- Depot-Level Sensor Overhaul Certification:Legacy rotary-wing fleet refurbishment requires recertification of thermal weapon sights against evolving threat signatures.
- Digital Signal Processor Integration Complexity:Retrofitting 30+ Hz frame rate processors into analog-architecture airframes demands airworthiness requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Electro Optical Systems Market |
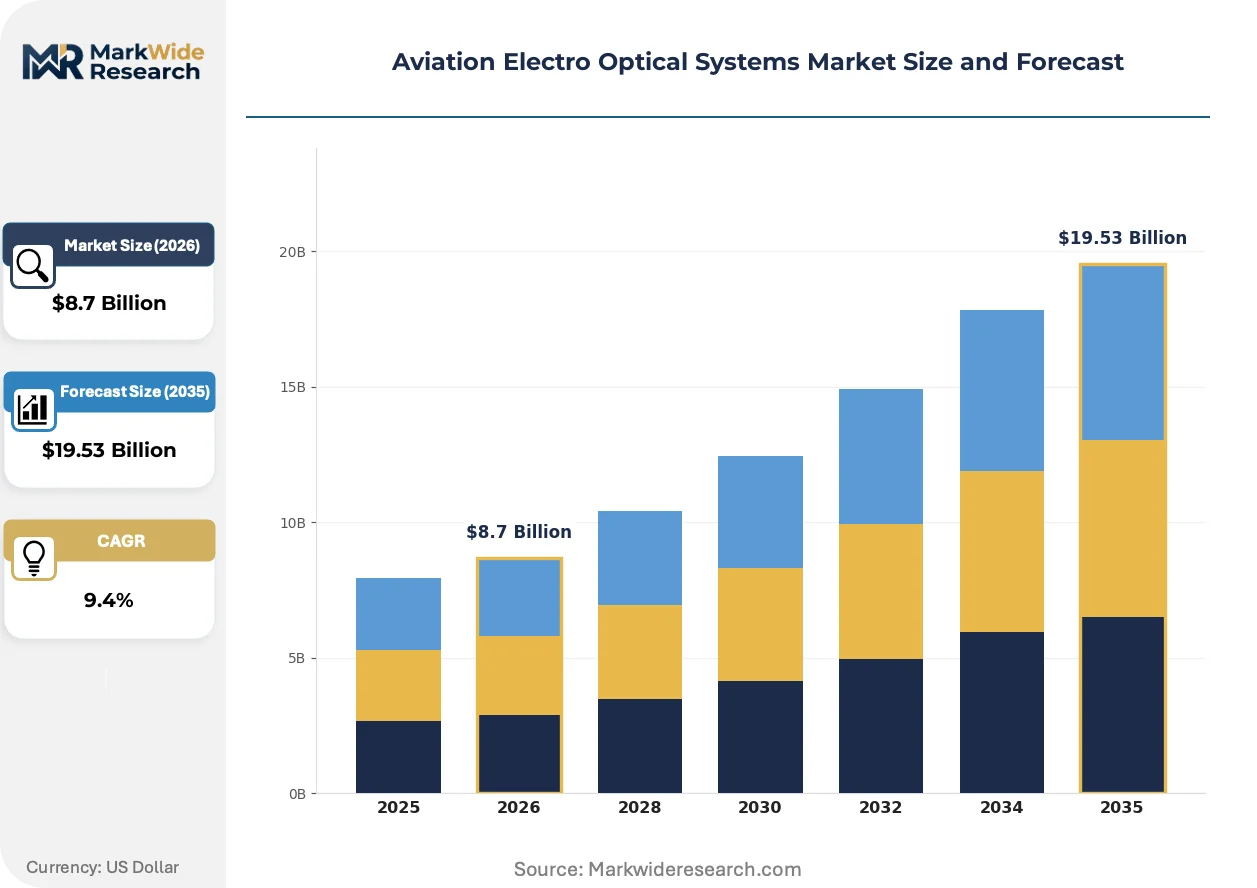
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Laser Targeting Systems, Imaging Systems, Surveillance Systems Technology: Electro-Optical, Laser-Based, Multispectral, Thermal Imaging Application: Reconnaissance, Target Acquisition, Surveillance, Defense End User: Military, Commercial Aviation, Government, Aerospace |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, Raytheon Technologies Corporation, L3Harris Technologies Inc., Teledyne FLIR LLC, Thales Group, BAE Systems Plc, Leonardo S.p.A., Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Electro Optical Systems Market Emerging Trajectories
Aviation electro optical systems are undergoing functional digitization that compresses hardware refresh cycles while expanding software-defined capability boundaries. Three convergent forces are restructuring competitive positioning and procurement patterns.
Multispectral sensor fusion is digitizing the traditional separation between passive surveillance and active targeting functions. Military end-users in NATO procurement channels are adopting short-wave infrared plus laser designator packages at compressed acquisition timelines. The technology is digitizing mission-computer architectures and enabling real-time spectral analysis that previously required ground-station processing.
EU F-Gas Regulation restrictions on sulfur hexafluoride and perfluorocarbon coolants are forcing redesign of closed-cycle sterling coolers for infrared detectors. European OEMs are accelerating transition to linear-drive and pulse-tube cooler architectures to maintain export eligibility. Cooled infrared detector manufacturers in France and Germany face compressed R&D timelines to qualify alternative refrigerant systems before phasedown deadlines.
Defense procurement offices are consolidating sensor suite awards into multi-year platform-agnostic contracts that unbundle hardware from sustainment. Rotary-wing and fixed-wing operators in the United States are shifting from per-airframe service agreements to fleet-wide calibration and overhaul obligations. This behavioral shift concentrates aftermarket revenue with distributors possessing cross-platform technical documentation libraries.
Aviation Electro Optical Systems Market Segmentation
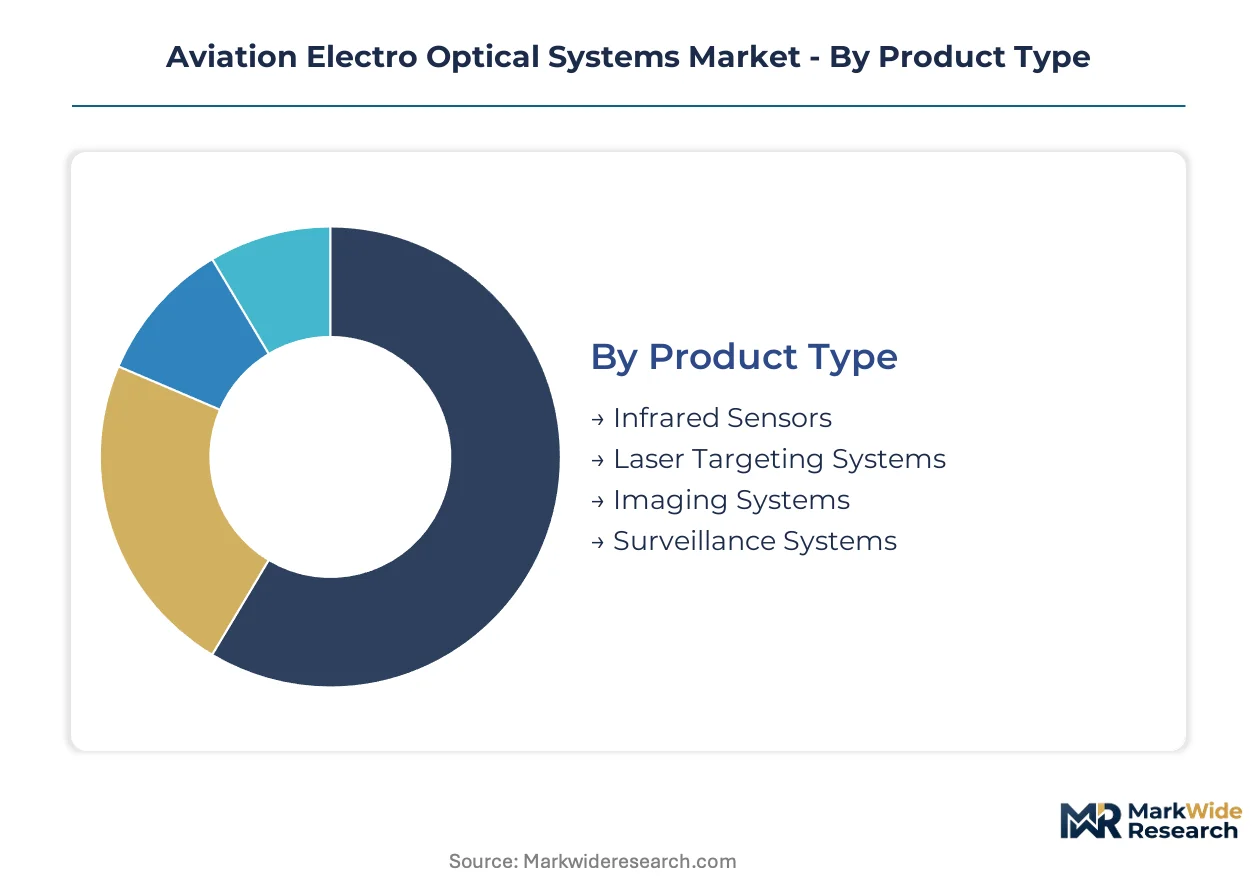
Aviation electro optical systems fragment across four distinct dimensions that govern procurement specifications, integration complexity, and sustainment economics. Each segmentation axis reflects divergent technical requirements between military combat platforms and commercial flight operations.
Product Type:
Use-case spectrum spans passive surveillance through active laser engagement, with each product category demanding specialized stabilization architectures and cooling subsystems.
- Infrared Sensors:Mercury-cadmium-telluride focal plane arrays convert thermal radiation into digital imagery across mid-wave and long-wave spectral bands. NATO-aligned fighter programs in the United States and France are standardizing distributed aperture infrared configurations for missile warning and navigation functions, though cooled detector supply concentrates in sovereign defense industrial bases.
- Laser Targeting Systems:Solid-state laser designators emit coded pulse trains for precision-guided munition handoff, integrating rangefinding with target illumination. Israeli defense procurement channels are expanding laser-targeting integration into rotary-wing attack platforms, constrained by national technology-transfer protocols that condition foreign component sourcing.
- Imaging Systems:High-definition visible-spectrum cameras with digital zoom and image stabilization support pilotage in degraded visual environments.
- Surveillance Systems:Multi-axis gimbal-mounted sensor packages combine electro-optical and infrared channels for persistent wide-area coverage.
Established volume favors Infrared Sensors; emerging adoption favors Laser Targeting Systems.
Technology:
Cost tier stratification separates legacy analog architectures from digitally fused sensor cores requiring advanced signal processing integration.
- Electro-Optical:Conventional charge-coupled device and complementary metal-oxide-semiconductor detectors capture visible-wavelength imagery with mature supply chains and compressed qualification timelines. Commercial aviation applications in the United States are accelerating electro-optical enhanced vision system adoption under FAA Technical Standard Order mandates for narrow-body transport categories.
- Multispectral:Fused short-wave infrared, near-infrared, and visible channels enable spectral signature analysis for decoy discrimination and counter-stealth operations. French defense procurement offices are funding multispectral convergence programs that merge passive imaging with active laser rangefinding for next-generation fighter sensor suites.
- Laser-Based:Coherent light detection and ranging systems provide precision ranging and atmospheric characterization.
- Thermal Imaging:Uncooled microbolometer arrays offer reduced lifecycle cost for applications tolerating lower thermal sensitivity.
Procurement concentration favors Electro-Optical; technology transition favors Multispectral.
Application:
Customer mission profiles dictate sensor packaging constraints, with combat applications prioritizing ruggedization and civil applications emphasizing certification compliance.
- Defense:Integrated sensor suites for fighter aircraft, rotary-wing gunships, and unmanned platforms combine targeting, navigation, and threat warning functions. The United States Department of Defense sustains the deepest procurement cycles through multi-year platform-agnostic sustainment contracts that unbundle hardware from depot-level overhaul obligations.
- Target Acquisition:Precision fire control systems for ground-attack and close-air-support missions require sub-meter geolocation accuracy and rapid handoff to precision munitions.
- Surveillance:Persistent wide-area motion imagery for border patrol and maritime domain awareness emphasizes dwell time and automated target detection.
- Reconnaissance:Stand-off imaging systems for strategic intelligence collection prioritize resolution and spectral diversity over real-time engagement timelines.
Contract value concentrates in Defense; platform expansion concentrates in Target Acquisition.
End User:
Volume distribution separates sovereign military procurement from emerging commercial certification pathways with diverging regulatory oversight.
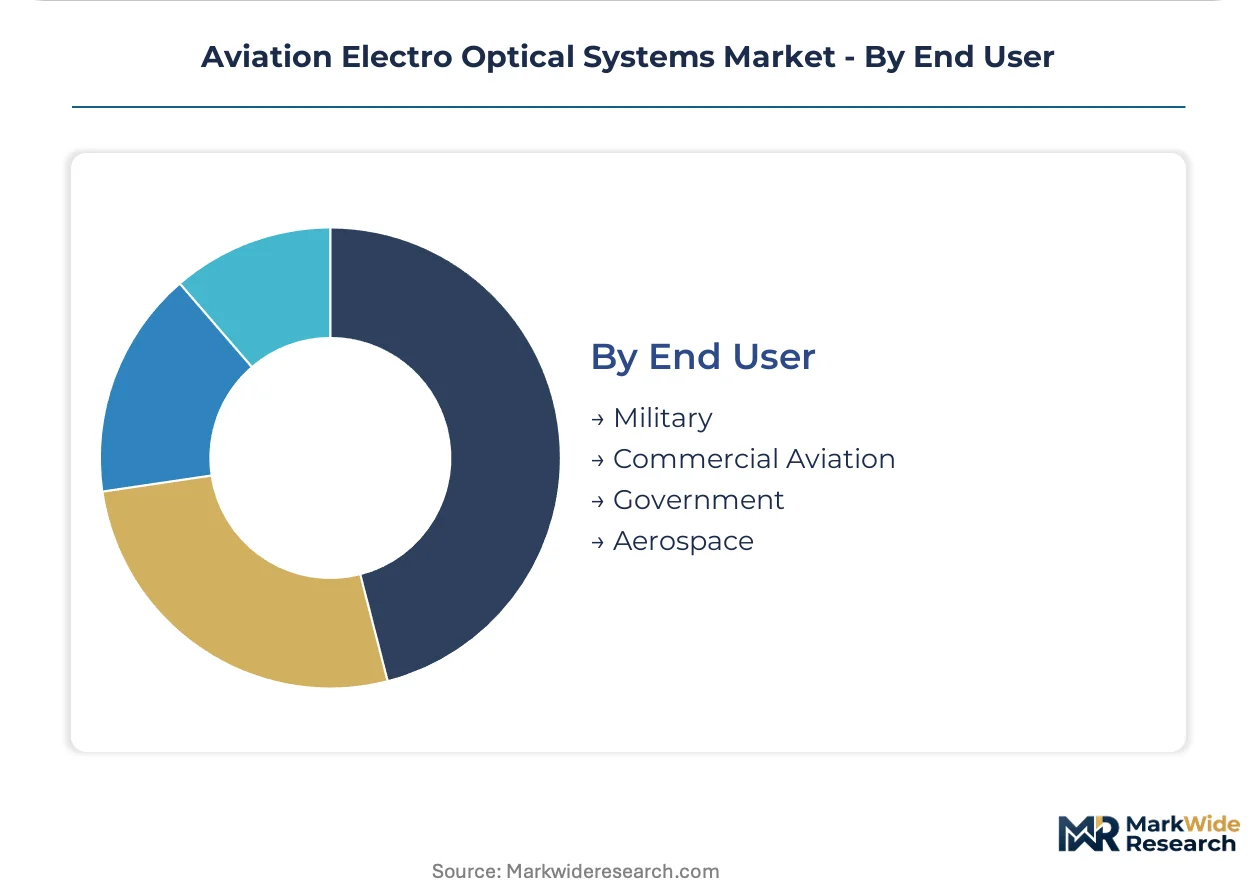
- Military:Combat aircraft, rotary-wing platforms, and unmanned systems operators constitute the foundational demand pool with multi-decade fleet sustainment requirements. Israel's domestic defense industrial base maintains sovereign electro-optical manufacturing capabilities through technology-transfer protocols that condition foreign sales of cooled infrared components.
- Commercial Aviation:Business jet and narrow-body transport operators are adopting FAA-certified enhanced flight vision systems that integrate infrared sensors with head-up displays for all-weather pilotage.
- Government:Border security agencies and maritime patrol services acquire surveillance-optimized configurations with reduced combat hardening.
- Aerospace:Satellite and space launch applications demand radiation-hardened detectors with extreme thermal cycling tolerance.
Procurement depth favors Military; regulatory tailwinds favor Commercial Aviation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: NATO-aligned militaries prioritize distributed aperture infrared configurations for fighter platforms, while commercial aviation operators in the United States accelerate enhanced vision system adoption under FAA mandates. Sovereign technology-transfer protocols in Israel and France sustain captive production ecosystems that resist cross-border component sourcing.
United States
The Department of Defense sustains the deepest procurement cycles through multi-year platform-agnostic sustainment contracts. FAA Technical Standard Orders mandate enhanced flight vision system integration into narrow-body transport categories, compressing OEM qualification timelines. The defense industrial corridor spanning California, Arizona, and Texas concentrates distributed aperture system manufacturing for next-generation fighter programs.
France
French defense procurement offices fund multispectral convergence programs merging passive imaging with active laser rangefinding. The EU F-Gas Regulation restricts sulfur hexafluoride and perfluorocarbon coolants, forcing redesign of closed-cycle sterling coolers for infrared detectors. The Paris-Saclay cluster and Toulouse aerospace corridor host sovereign electro-optical manufacturing capabilities serving both domestic and export markets.
Israel
National technology-transfer protocols condition foreign sales of domestically developed electro-optical components, expanding local production capacity. The country's national regulator enforces sovereign content requirements that limit cross-border gimbal assembly sourcing. The Haifa-Tel Aviv corridor concentrates precision mechanical engineering expertise for micro-radian stabilization systems in rotary-wing attack platforms.
Germany
Linear-drive and pulse-tube cooler architectures are accelerating to maintain export eligibility under phasedown deadlines. CE marking frameworks impose documentation burdens on gimbal assembly cross-border shipments distinct from US ITAR regulations. The Bavaria and Baden-Württemberg industrial regions host cooled infrared detector manufacturers qualifying alternative refrigerant systems.
United Kingdom
BAE Systems anchors domestic electro-optical capabilities through integration with Tempest fighter sensor suite development. UK defense procurement channels emphasize platform-agnostic sustainment contracts that unbundle hardware from depot-level overhaul obligations. The Greater Bristol and Hampshire clusters concentrate thermal weapon sight refurbishment expertise for legacy rotary-wing fleets.
Aviation Electro Optical Systems Market Vendor Landscape
Capability concentration sits with sovereign defense primes possessing micro-radian stabilization expertise; scale advantage sits with diversified aerospace conglomerates spanning multiple airframe programs. The vendor base organizes into three tiers: integrated platform primes, sensor subsystem specialists, and aftermarket sustainment providers. Dominant competitive moves include backward integration into cooled detector supply and consolidation of cross-platform technical documentation libraries for fleet-wide service obligations.
Within the integrated platform prime tier, Northrop Grumman Corporation, Lockheed Martin Corporation, and Raytheon Technologies Corporation exemplify divergent strategic positioning. Northrop Grumman occupies a position anchored in distributed aperture systems with long-term service obligations spanning multiple airframes. Lockheed Martin exemplifies captive integration through electro-optical targeting system alignment with fighter platform production. Raytheon Technologies sits within the aftermarket sustainment vector, concentrating on thermal weapon sight refurbishment and depot-level sensor overhaul for legacy fleets.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| L3Harris Technologies Inc. |
| Teledyne FLIR LLC |
| Thales Group |
| BAE Systems Plc |
| Leonardo S.p.A. |
| Elbit Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in cooled mercury-cadmium-telluride focal plane array production across Israeli and French sovereign defense industrial bases is compressing supplier pricing power while extending qualification timelines for new entrants. This utilization squeeze simultaneously elevates long-term contract premiums and forces commercial aviation buyers toward uncooled microbolometer alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement for military infrared sensor suites, with NATO-aligned defense offices locking five-to-ten-year platform-agnostic sustainment contracts that bundle hardware with depot-level overhaul obligations. Price differentiation hinges on certification tier—FAA Technical Standard Order compliance for commercial enhanced vision systems commands substantial premiums over non-certified configurations—and volume scale, with fleet-wide calibration contracts attracting discounts against per-airframe pricing. Cost compression in uncooled thermal imaging is intensifying as microbolometer manufacturing scales for commercial aviation penetration. Commercial aviation operators exhibit highest price sensitivity, while sovereign military procurement offices prioritize supply security over unit economics.
Supply Chain Analysis
Contract manufacturing for stabilized gimbal assemblies concentrates in Israel, France, and the United States, with Elbit Systems and Thales Group maintaining captive production for micro-radian precision mechanical engineering. Raw material dependencies center on mercury-cadmium-telluride semiconductor substrates, rare-earth optical glass for laser rangefinders, and precision-machined aluminum-titanium alloys for airborne stabilization platforms. Single-source vulnerability pervades cooled detector supply, with production pooling in three sovereign defense corridors resistant to cross-border technology transfer. Distribution runs through defense primes possessing cross-platform technical documentation libraries, fleet-wide service obligations, and airworthiness certification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-agnostic sustainment contracts for sensor calibration and mission-computer integration are expanding faster than hardware sales, creating durable recurring-revenue streams that outperform one-time system procurement.
For Market Incumbents: Entrench position through backward integration into cooled infrared detector supply and consolidation of cross-platform technical documentation libraries. Sovereign technology-transfer protocols in Israel and France threaten component sourcing flexibility, making captive production capacity the priority lever against supply disruption. Defense procurement offices are unbundling hardware from sustainment, requiring incumbents to deepen service-attach capabilities across multiple airframe generations. For New Entrants and Emerging Players: Commercial aviation enhanced vision systems for narrow-body transport categories represent the most penetrable entry point, with FAA Technical Standard Order mandates compressing OEM integration timelines and creating certification-driven demand. Uncooled microbolometer architectures for business jet and regional transport applications offer lower capital barriers than military-qualified cooled systems. A go-to-market angle anchored in FAA certification consulting and rapid airworthiness qualification can differentiate against established defense primes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multispectral sensor fusion programs, as short-wave infrared plus laser designator packages demand integrated R&D investment beyond standalone component manufacturing. Long-term viability over the coming decade favors acquisition targets possessing micro-radian stabilization expertise and existing airworthiness certification authority. The signal to watch is consolidation of aftermarket service contracts into fleet-wide obligations, indicating which technical documentation libraries carry strategic value.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Agnostic Sustainment Contracting | Unbundles hardware from depot-level overhaul, concentrating revenue with cross-platform documentation holders. |
| Backward Integration into Cooled Detectors | Secures supply of mercury-cadmium-telluride focal plane arrays against sovereign technology-transfer restrictions. |
| FAA Certification Pathway Investment | Accelerates commercial enhanced vision system adoption in narrow-body transport categories under Technical Standard Order mandates. |
| Multispectral Sensor Fusion Development | Merges short-wave infrared with laser rangefinding for counter-stealth and decoy-discrimination missions. |
| Alternative Cooler Architecture Transition | Maintains EU export eligibility under F-Gas Regulation phasedown deadlines for sulfur hexafluoride refrigerants. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, electro-optical system integration engineers, FAA certification specialists, and aftermarket sustainment contract managers. Secondary validation drew from Department of Defense budget justification documents, FAA Technical Standard Order filings, EU F-Gas Regulation implementation reports, and customs trade data on electro-optical component shipments. Bottom-up segment sizing triangulated against top-down defense aerospace expenditure models.
Calibration against historical contract award patterns and announced platform production schedules anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, technology tier, application mission profile, and end-user regulatory jurisdiction. CAGRs were derived from fitted growth curves calibrated to procurement cycle timing and airframe replacement schedules. Industry-specific forecast inputs incorporated FAA mandate implementation timelines and NATO fighter platform sensor suite upgrade roadmaps.
Practitioners should monitor sovereign technology-transfer protocol enforcement and cooled detector production capacity utilization for early signals of supply constraint or pricing inflection. Forecasts reflect assumptions regarding defense budget continuity, FAA certification timeline adherence, and EU refrigerant phasedown schedules. Quarterly review of contract award announcements, airworthiness directive publications, and trade flow disruptions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market