
 North America Rotor Blade Market | 2026-2036
North America Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rotor Blade Market Insights
The direct-to-utility procurement channel is narrowing as original equipment manufacturers consolidate preferred supplier lists. TPI Composites leverages its manufacturing footprint across Mexico and the United States to anchor long-term supply agreements with major turbine builders. Vestas Wind Systems sustains vertical integration through captive blade production, while LM Wind Power competes on advanced aerodynamic designs for next-generation turbines.
North America rotor blades are aerodynamic structures typically spanning 50 to 80 meters in length, fabricated from glass-fiber-reinforced epoxy or carbon-fiber composites through resin infusion or prepreg layup processes, designed to convert kinetic wind energy into rotational mechanical power for electricity generation. Horizontal axis configurations dominate installed capacity across the region, while carbon fiber material adoption accelerates in longer blades where stiffness-to-weight ratios determine performance thresholds. The wind energy application segment commands the primary investment flow, with OEM end users driving procurement volume through multi-year framework contracts.
The Federal Aviation Administration coordinates with developers on aviation obstruction lighting and marking standards for tall turbines, while the EPA oversees composite waste streams from decommissioned blades under evolving solid waste frameworks. State-level renewable portfolio standards in Texas, Iowa, and Illinois directly shape offtake velocity and blade replacement cycles. Stakeholders must track emerging extended producer responsibility legislation in multiple jurisdictions that will dictate end-of-life logistics costs and material recovery obligations.
Market Dynamics
The IRA production tax credit extension compresses procurement timelines while simultaneously extending project visibility, forcing blade suppliers to balance immediate capacity ramp-ups against decade-long supply commitments without guaranteed volume floors.
Growth Catalysts
- Production Tax Credit Extension:The IRA's multi-year credit stability enables utility-scale developers in Texas and the Midwest corridor to lock in multi-gigawatt procurement frameworks, pulling forward blade demand from 2028-2030 into current production slots.
- Carbon-Fiber Composite Adoption:Longer blades exceeding 75 meters require stiffness-to-weight ratios only carbon fiber delivers, creating upgrade cycles across Great Plains repowering programs where glass-fiber blades face performance ceilings.
- Great Plains Repowering Density:Wind farm operators in Kansas, Oklahoma, and Nebraska are replacing first-generation turbines with larger units, generating blade replacement volumes that outpace greenfield installations in the region.
Market Restraints
- Epoxy Resin Price Volatility:Petrochemical feedstock fluctuations directly compress blade manufacturer margins, with resin accounting for substantial material cost exposure that cannot be fully passed through under fixed-price framework contracts.
- Mexico-U.S. Border Logistics Concentration:TPI Composites and similar suppliers anchor production in Mexican border states, creating single-point vulnerability to customs delays, tariff policy shifts, or cross-border labor disruptions.
- Blade Length Transport Constraints:Highway corridor clearances and rail car dimensional limits impose hard ceilings on blade segment sizing, forcing manufacturing site placement within constrained radii of installation zones.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Alberta wind development lags Texas penetration by approximately 40%, offering blade suppliers first-mover positioning as provincial renewable mandates tighten.
- Extended Producer Responsibility Legislation:Emerging state-level frameworks in California and New York will mandate material recovery obligations, creating service revenue streams for blade recyclers and logistics operators who pre-position decommissioning infrastructure.
- Resin Infusion Automation Convergence:Robotics integration with closed-mold resin transfer is digitizing quality control and reducing labor-hour intensity, enabling cost-competitive production in higher-wage U.S. interior locations.
Industry Challenges
- Composite Technician Skill Scarcity:The specialized workforce for hand layup and vacuum infusion processes remains concentrated in established manufacturing hubs, constraining greenfield site ramp speeds in emerging demand centers.
- Type Certification Timeline Compression:FAA obstruction lighting coordination and IEC 61400-23 blade testing protocols create multi-month approval gates that misalign with developer construction schedules, forcing inventory pre-builds.
- End-of-Life Logistics Network Gaps:Decommissioned blade collection, transport, and processing infrastructure remains underdeveloped across the Midwest corridor, exposing operators to pending landfill restrictions and recovery cost uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rotor Blade Market |
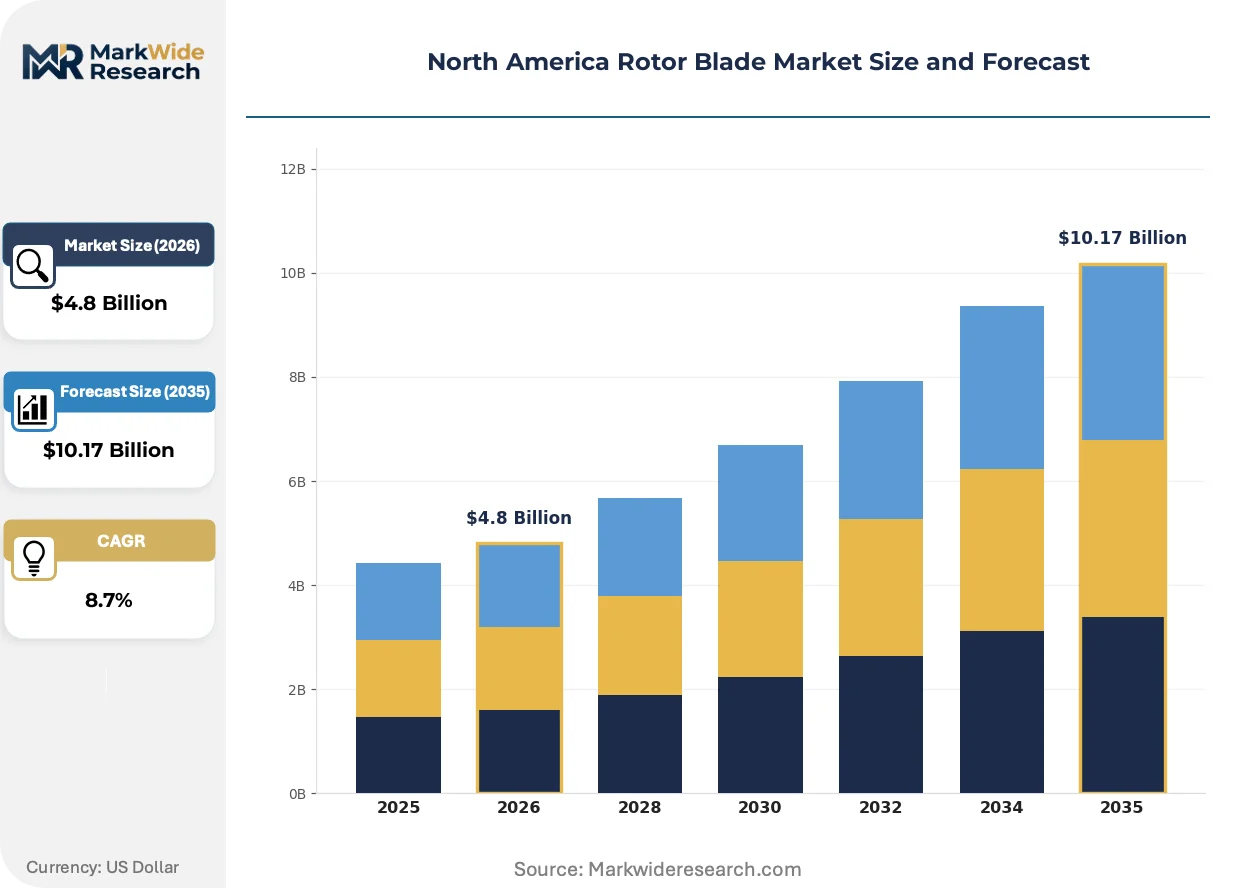
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Ducted Fan, Others Material: Composite, Aluminum, Steel, Carbon Fiber Application: Aerospace, Wind Energy, Marine, Industrial End User: OEMs, Maintenance Providers, Utilities, Research Institutions |
| Companies Covered | TPI Composites, LM Wind Power, Siemens Gamesa Renewable Energy, Vestas Wind Systems, Enercon GmbH, Nordex, MFG Wind, Aeris Energy, Sinoma Wind Power Blade, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rotor Blade Market Trends and Innovations
Digital thread integration across design, manufacturing, and field performance is compressing iteration cycles while regulatory pressure on material circularity is forcing process reinvention across the value chain.
Advanced blade monitoring systems embedding fiber-optic strain sensors and accelerometers are digitizing structural health assessment in real time. Vestas and LM Wind Power deploy these systems on next-generation offshore-capable platforms, enabling predictive maintenance contracts that shift revenue from hardware sales to performance guarantees. The data architecture is digitizing warranty risk allocation between OEMs and wind farm operators.
The EPA's evolving solid waste frameworks for composite decommissioning streams are forcing material recovery investments. State-level landfill restrictions in Iowa and Texas are accelerating pyrolysis and mechanical grinding pilot facilities, with blade manufacturers now contracting feedstock supply agreements before facilities achieve commercial scale. The regulatory trajectory is compressing blade design choices toward disassembly-friendly joint architectures.
Direct-to-utility framework contracts are displacing spot procurement through tier-one OEMs. Developers in Illinois and Ohio now negotiate blade supply directly with TPI Composites and secondary suppliers, bypassing traditional turbine bundling. The channel restructuring concentrates price negotiation leverage with buyers holding multi-site portfolios, compressing supplier margin structures while extending contract durations.
North America Rotor Blade Market Segmentation
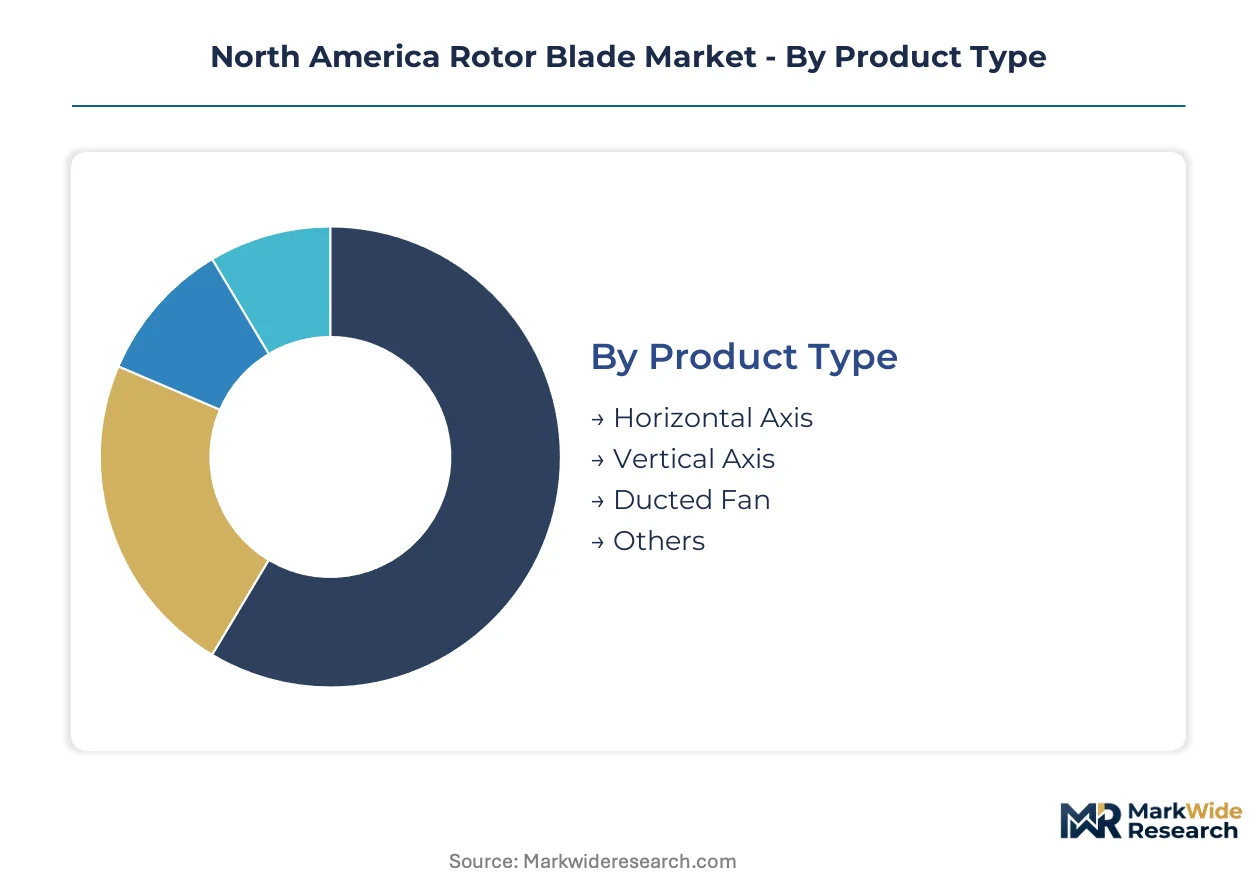
Rotor blade segmentation in North America reveals divergent material trajectories and end-user procurement patterns that reshape supplier priorities. Understanding these divides exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Mature configurations dominate installed base economics while emerging geometries capture niche performance premiums.
- Horizontal Axis:The dominant aerodynamic configuration across utility-scale installations, these blades convert wind flow perpendicular to the rotational plane through pitch-controlled fiberglass or carbon-fiber structures. Demand concentrates in Texas and the Midwest corridor where repowering programs replace first-generation units with longer, higher-efficiency designs. The IRA production tax credit extension locks in multi-year procurement frameworks for this segment.
- Vertical Axis:Darrieus and Savonius designs capture urban distributed generation and remote off-grid applications where omnidirectional wind capture offsets lower peak efficiency. Emerging deployment clusters around research partnerships in Colorado and small-scale commercial pilots in Ontario. FAA obstruction lighting standards impose simpler compliance pathways for shorter vertical structures.
- Ducted Fan:Shrouded configurations concentrate airflow acceleration in constrained sites, finding niche adoption in industrial co-generation and building-integrated installations.
- Others:Experimental and hybrid geometries serve specialized research programs and prototype validation contracts.
Horizontal Axis retains volume leadership; Vertical Axis holds the steepest expansion curve.
Material:
Cost tiers separate commodity glass-fiber from performance-driven carbon fiber adoption, with mid-tier alternatives filling transitional applications.
- Composite:Glass-fiber-reinforced epoxy dominates volume production through resin infusion and prepreg layup processes, anchoring blade supply for Great Plains repowering programs where cost-per-megawatt drives procurement. Epoxy resin price volatility compresses manufacturer margins under fixed-price framework contracts with utilities.
- Carbon Fiber:Stiffness-to-weight ratios enable blades exceeding 75 meters for next-generation turbines, with adoption accelerating where transport constraints and tip-speed optimization justify material premiums. Vestas and LM Wind Power deploy carbon-heavy platforms for offshore-capable designs.
- Aluminum:Legacy metal construction persists in small-scale and replacement blade markets where manufacturing simplicity outweighs fatigue-life limitations.
- Steel:Reinforced hybrid structures serve industrial ventilation and specialized marine propulsion applications outside mainstream wind energy.
Composite retains volume leadership; Carbon Fiber commands the steepest price-premium expansion.
Application:
Customer type concentration varies sharply across end-use sectors, with procurement scale and technical specification intensity diverging accordingly.
- Wind Energy:Utility-scale and distributed generation applications command primary investment flow, with blades spanning 50 to 80 meters converting kinetic energy to rotational mechanical power. Procurement runs through multi-year framework contracts with developers in Illinois, Ohio, and Texas bypassing traditional turbine bundling.
- Aerospace:Propulsion and turbine engine applications demand precision-machined airfoils with tight dimensional tolerances, serving commercial aviation and defense primes through specialized certification protocols.
- Marine:Ship propulsion and tidal energy converters face salt-corrosion resistance requirements and classification society approvals distinct from land-based wind standards.
- Industrial:HVAC, mining ventilation, and process cooling applications prioritize cost minimization over aerodynamic optimization.
Wind Energy retains volume leadership; Marine gains share fastest in coastal state incentive zones.
End User:
Supply concentration aligns with procurement scale, from captive OEM production to fragmented maintenance provider networks.
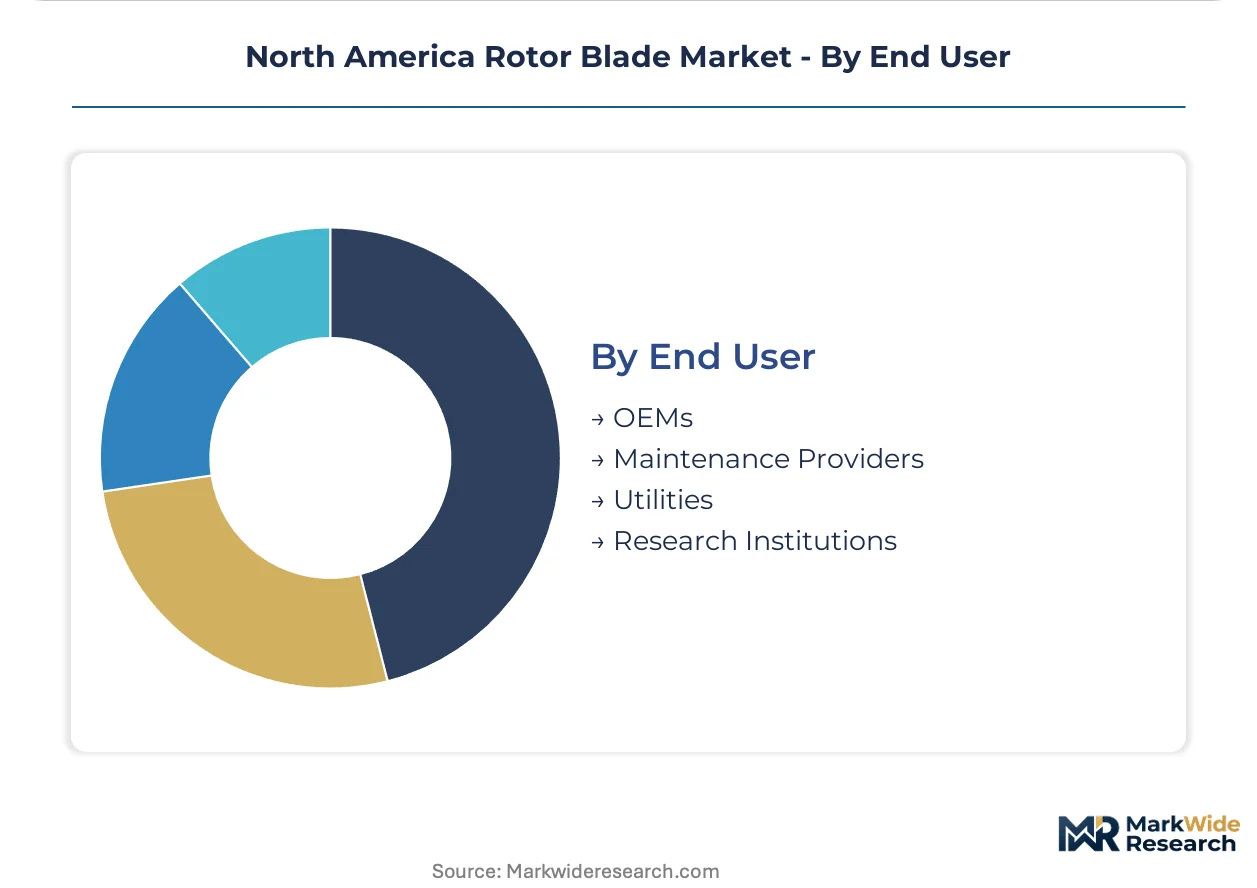
- OEMs:Original equipment manufacturers drive procurement volume through multi-year framework contracts, with Vestas sustaining vertical integration through captive blade production while TPI Composites anchors third-party supply agreements. Direct-to-utility contracting is displacing traditional turbine bundling.
- Utilities:Wind farm operators in Kansas, Oklahoma, and Nebraska are scaling repowering programs that generate blade replacement volumes outpacing greenfield installations. Extended producer responsibility legislation in California and New York will mandate material recovery obligations.
- Maintenance Providers:Third-party service contractors capture blade repair, leading edge protection, and structural reinforcement work outside warranty periods.
- Research Institutions:National laboratories and university programs validate advanced aerodynamic designs and material formulations before commercial scaling.
OEMs retain volume leadership; Utilities show the steepest procurement timeline compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian Prairie developers negotiate from weaker volume positions than Texas counterparts, compressing supplier margins while Midwest utilities leverage repowering density for price concessions.
United States
Texas and the Midwest corridor anchor utility-scale procurement, with Iowa and Illinois developers locking multi-gigawatt frameworks under IRA production tax credit extensions. The FAA coordinates aviation obstruction lighting standards for tall turbines across Great Plains installations. Manufacturing clusters concentrate along the Mexico-U.S. border where TPI Composites operates resin infusion facilities serving both domestic and cross-border demand.
Canada
Saskatchewan and Alberta wind development trails Texas penetration by approximately 40%, creating first-mover positioning for blade suppliers as provincial renewable mandates tighten. Health Canada and provincial regulators oversee composite waste frameworks for decommissioned blades under evolving environmental standards. Manufacturing activity clusters in Ontario and Quebec where resin infusion automation pilots target cost-competitive production for Prairie export markets.
Mexico
Northern border states anchor captive production for U.S. market access, with resin infusion and prepreg layup operations concentrated in Baja California and Chihuahua. Mexican federal environmental regulators coordinate with U.S. EPA on cross-border composite waste protocols for end-of-life blade streams. Industrial parks in Tijuana and Mexicali host glass-fiber and carbon-fiber fabrication facilities serving Texas and California demand corridors.
North America Rotor Blade Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a supply structure that concentrates around turbine OEMs with captive blade production and independent fabricators serving third-party demand. The vendor base splits between vertically integrated turbine builders and specialized composite manufacturers competing on resin infusion automation and carbon-fiber layup expertise. Three archetypes dominate: captive producers, contract manufacturers, and emerging recyclers positioning for extended producer responsibility mandates. Capacity expansion and direct-to-utility contracting represent the dominant competitive vectors as procurement channels bypass traditional turbine bundling.
Among independent fabricators, TPI Composites exemplifies the contract manufacturing archetype with Mexico-U.S. border production positioning, while LM Wind Power and Vestas Wind Systems represent divergent strategic postures—one competing on advanced aerodynamic designs, the other sustaining backward integration through in-house blade supply. These three anchors illustrate how supplier strategies split between geographic arbitrage, technology differentiation, and upstream control over critical components.
| Leading Market Players |
|---|
| TPI Composites |
| LM Wind Power |
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| Enercon GmbH |
| Nordex |
| MFG Wind |
| Aeris Energy |
| Sinoma Wind Power Blade |
| Others |
Pricing and Supply Chain Analysis
Great Plains highway corridor clearances impose dimensional freight premiums that concentrate supply within 500-mile radii of installation zones, compressing margin structures for blades exceeding 75 meters while amplifying price differentiation between standard glass-fiber configurations and carbon-fiber custom orders.
Pricing Analysis
Configured-to-order pricing for carbon-fiber blades commands spreads exceeding standard glass-fiber equivalents by material grade and transport complexity. Contract-based long-term offtake agreements dominate utility procurement, with price differentiation driven by volume scale and IEC 61400-23 certification tier. Cost compression in standard composite segments intensifies as epoxy resin volatility cannot be passed through fixed-price frameworks. Independent maintenance providers exhibit highest price sensitivity; offshore-capable OEMs demonstrate lowest.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculations for border-state manufacturing clusters. Production concentrates in Mexico, the United States, and Canada, with raw material dependencies spanning carbon fiber from Japan and South Korea, epoxy resins from Gulf Coast petrochemical complexes, and balsa core from Ecuador. Single-source vulnerability persists in specialized resin formulations. Distribution runs through direct-to-utility framework contracts displacing traditional turbine bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Decommissioning logistics and blade recycling services constitute the fastest-expanding revenue layer, outpacing hardware sales as extended producer responsibility legislation in California and New York mandates material recovery obligations with recurring service contracts.
For Market Incumbents: Insulate margin structures against direct-to-utility price compression by deepening captive recycling infrastructure and securing exclusive feedstock agreements with pyrolysis pilot facilities. Pre-position decommissioning logistics networks across the Midwest corridor before landfill restrictions tighten. Certification investment in disassembly-friendly joint architectures will differentiate against commodity blade suppliers. For New Entrants and Emerging Players: Saskatchewan and Alberta wind development trails Texas penetration by approximately 40%, offering first-mover positioning as provincial renewable mandates tighten. Target resin infusion automation pilots in Ontario and Quebec for cost-competitive Prairie export supply. Go-to-market leverage rests on pre-contracting with developers ahead of framework procurement windows. For Investors and Strategic Acquirers: Extended producer responsibility mandates reshape the acquisition landscape toward recyclers and logistics operators with pre-positioned decommissioning infrastructure. Long-term viability favors asset-light service platforms over capital-intensive blade manufacturing across the five-to-ten year horizon. Monitor Iowa and Texas landfill restriction timelines as inflection indicators for recovery cost realization.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Pre-Positioning | Extended producer responsibility legislation in California mandates material recovery obligations ahead of facility commercialization. |
| Resin Infusion Automation Investment | Robotics integration with closed-mold resin transfer enables cost-competitive production in higher-wage U.S. interior locations. |
| Direct-to-Utility Framework Contracting | Developers in Illinois and Ohio now negotiate blade supply directly, bypassing traditional turbine bundling with OEMs. |
| Carbon-Fiber Composite Capacity Expansion | Stiffness-to-weight ratios for blades exceeding 75 meters justify material premiums in Great Plains repowering programs. |
| Decommissioning Logistics Network Buildout | Blade collection and processing infrastructure remains underdeveloped across the Midwest corridor, exposing operators to pending restrictions. |
Research Methodology
Operator-level perspectives from wind farm asset managers, utility procurement officers, composite manufacturing plant directors, and EPA regulatory compliance leads anchored the qualitative base. Primary interviews triangulated against secondary validation from EIA generation databases, FERC interconnection filings, IRA implementation guidance, and state renewable portfolio standard tracking. Bottom-up blade demand estimates from repowering program announcements converged with top-down market sizing from OEM production disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with high-case assumptions incorporating accelerated carbon-fiber adoption in offshore-capable platforms and low-case assumptions reflecting prolonged epoxy resin price volatility. Segmentation dimensions modeled include material composition, blade length tier, end-user procurement channel, and regional regulatory cluster. CAGRs derived from unit demand trajectories and material mix shifts, with forecast inputs incorporating FAA obstruction lighting coordination timelines and IEC 61400-23 certification throughput rates.
Practitioners should monitor IRA production tax credit extension renewal debates, Mexico-U.S. tariff policy shifts, and pyrolysis facility commercialization delays for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Heat Shield Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market