
 Military Aircraft Actuation System Market | 2026-2036
Military Aircraft Actuation System Market Size, Share, and Industry Trends Forecast 2026-2036
Military Aircraft Actuation System Market Analysis
Carbon-fiber-reinforced polymer is broadening design freedom in actuator housings and linkages, trimming weight without sacrificing load-bearing capacity. Curtiss-Wright Corporation leverages its heritage in aerospace controls to sustain dominance in electromechanical flight control actuators for fixed-wing military platforms. Safran S.A. anchors European supply chains through integrated landing gear and actuation architectures. Moog Inc. specializes in high-reliability servo valves that compete across both hydraulic and hybrid-electric system tiers.
A military aircraft actuation system converts electrical, hydraulic, or pneumatic energy into precise mechanical motion to position flight control surfaces, landing gear, and weapon stations, typically operating at pressures exceeding 3,000 psi in hydraulic configurations and achieving positional accuracy within fractions of a degree. Electric actuators are gaining share as platforms shift from centralized hydraulic distribution to distributed electromechanical architectures, reducing maintenance intervals and leak vulnerability. Fly-by-wire technology leads technology segmentation by installed base, though smart actuation with embedded health monitoring represents the fastest-expanding margin pool as predictive maintenance protocols spread through defense procurement specifications.
The FAA, EASA, and MIL-STD-810 collectively shape airworthiness certification and environmental qualification thresholds that govern actuator design verification, with electromagnetic interference hardening and thermal shock resistance as mandatory test vectors. The U.S. Department of Defense supplements these through specific airframe program requirements that flow down to subsystem vendors via DFARS contracting clauses. Stakeholders must monitor how the U.S. Air Force's Next Generation Air Dominance program and parallel European FCAS initiatives recalibrate performance specifications for actuation bandwidth and failure-mode resilience.
Market Dynamics
The transition from centralized hydraulic distribution to distributed electromechanical architectures is compressing maintenance intervals and reshaping supplier value capture across military aircraft programs.
Growth Catalysts
- Fly-by-wire modernization mandates:The U.S. Department of Defense prioritizes control surface electrification across tactical aircraft fleets, creating sustained procurement pull for dual-channel electromechanical units.
- FAA and EASA redundancy directives:Airworthiness standards for flight control systems now mandate fail-operational architectures, accelerating certification demand for fault-tolerant actuator designs.
- Carbon-fiber-reinforced polymer adoption:Advanced composites in actuator housings trim weight while preserving load-bearing capacity, enabling performance gains in next-generation fighter platforms.
Market Restraints
- Specialized alloy supply concentration:Titanium and high-grade aluminum sourcing clusters in limited supplier bases, exposing programs to input cost volatility and delivery risk.
- Electromagnetic interference hardening costs:MIL-STD-461 testing requirements for electromechanical units impose non-recurring engineering burdens that compress margins on low-volume contracts.
- Hydraulic system path dependency:Legacy platform sustainment contracts lock installed bases into fluid-power maintenance, slowing full-fleet electrification timelines.
Strategic Opportunities
- Embedded health monitoring integration:Smart actuation with predictive maintenance protocols aligns with U.S. Air Force Condition-Based Maintenance Plus initiatives, opening software-enabled service revenue streams.
- Next Generation Air Dominance actuation bandwidth:Specified performance thresholds for extreme maneuverability create white space for high-frequency response electromechanical designs.
- European FCAS development funding:Franco-German-Spanish joint programs channel R&D investment toward integrated landing gear and flight control architectures.
Industry Challenges
- Dual-use semiconductor sourcing:ITAR-controlled servo drive electronics face foundry capacity constraints, stretching lead times for qualified components.
- System integration complexity:Electromechanical actuators must interface with legacy hydraulic infrastructure during hybrid transition phases, multiplying interface validation cycles.
- Specialized actuator engineering talent scarcity:Deep expertise in aerospace mechatronics concentrates at prime contractors and select Tier-1 suppliers, constraining workforce mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Aircraft Actuation System Market |
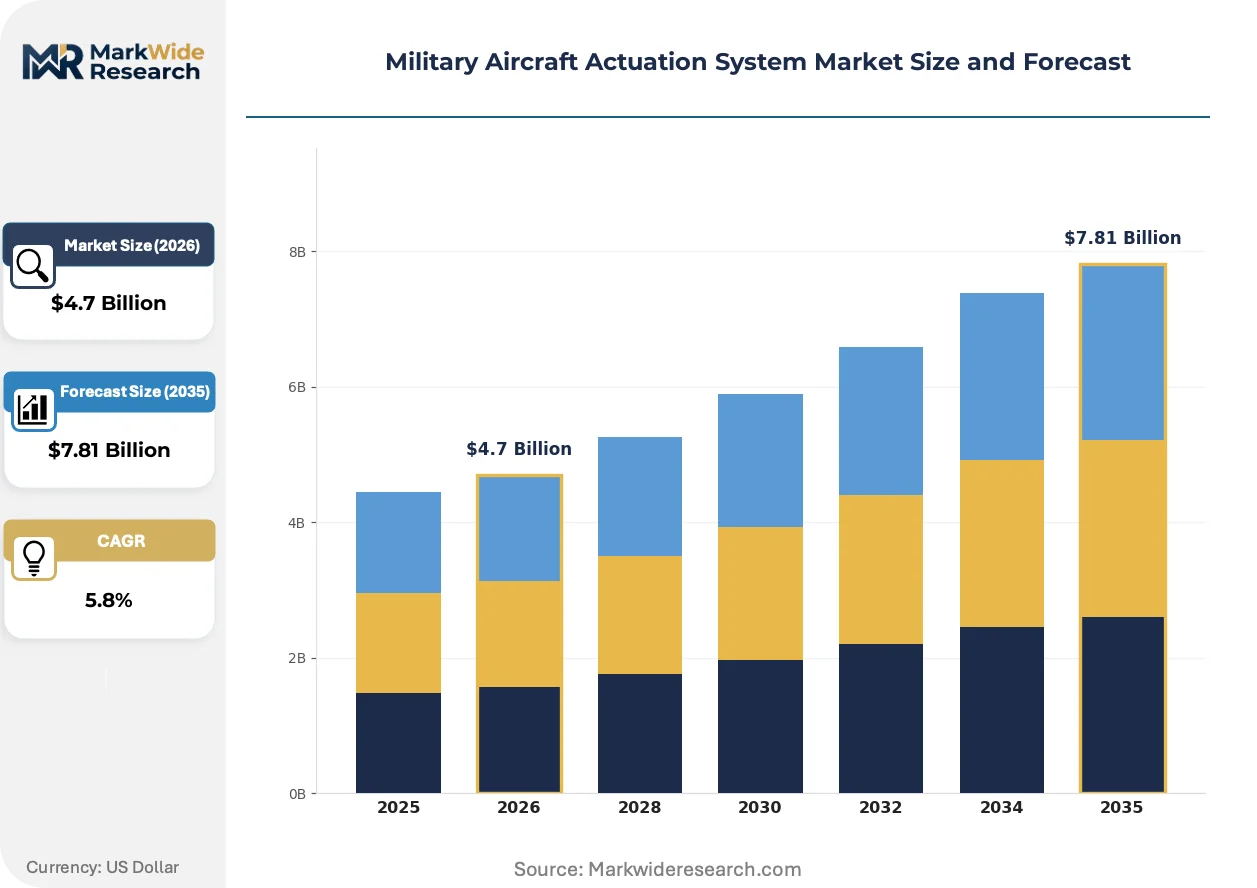
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Actuators, Electric Actuators, Pneumatic Actuators, Mechanical Actuators Technology: Electromechanical, Fly-by-Wire, Smart Actuation, Traditional Systems End User: Military Aviation, Defense Contractors, Government Agencies, Aerospace Manufacturers Application: Flight Control, Landing Gear, Weapon Control, Auxiliary Systems |
| Companies Covered | Curtiss-Wright Corporation, Safran S.A., Moog Inc., Liebherr Group, Triumph Group Inc., Honeywell International Inc., Woodward Inc., Eaton Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Aircraft Actuation System Market Emerging Trajectories
Power electronics miniaturization and embedded sensing are converging to redefine actuator intelligence, shifting competitive advantage toward firms mastering electromechanical-software integration.
Distributed electromechanical actuation is decentralizing flight control authority across airframe surfaces, replacing centralized hydraulic manifolds with localized motor-drive units. Defense procurement offices in the United States and United Kingdom are mandating this architecture for new-start programs. The shift compresses hydraulic line maintenance and eliminates single-point failure modes in fluid distribution.
EASA's updated Certification Specifications for Large Aeroplanes now explicitly address electromechanical actuator failure modes and jamming scenarios, tightening verification protocols for European suppliers. Manufacturers must demonstrate fault detection latency below specified thresholds to achieve type certification. The regulation most affects electromechanical specialists serving Airbus Defence and Space platforms and derivative military transports.
Performance-based logistics contracts are displacing traditional spares-provisioning agreements for actuator fleets. The U.S. Defense Logistics Agency now indexes contractor payments to operational availability metrics rather than unit delivery. This model concentrates in rotorcraft and tactical aircraft programs where mission-readiness requirements are most stringent.
Military Aircraft Actuation System Market Segmentation
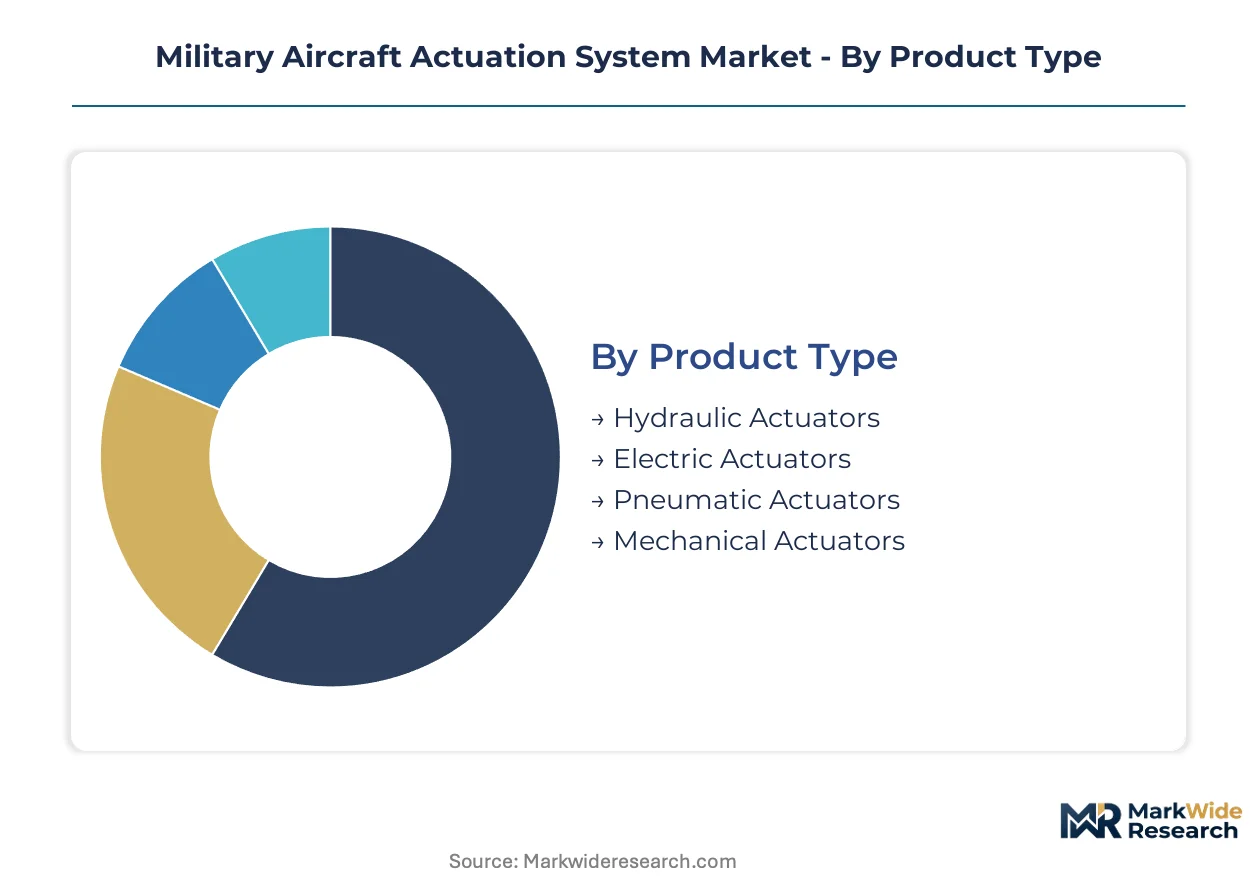
Segmentation in military aircraft actuation systems reveals how procurement priorities diverge across platform generations and operational requirements. Buyers weigh legacy fleet sustainment against next-generation performance specifications, creating distinct demand pockets within each category.
Product Type:
Platform modernization cycles drive selection between proven hydraulic architectures and emerging electric alternatives, with cost-risk trade-offs varying by aircraft service life remaining.
- Hydraulic Actuators:These systems operate at pressures exceeding 3,000 psi using centralized fluid distribution manifolds. The U.S. Air Force F-15 and F-16 sustainment programs sustain procurement volume, though leak vulnerability and maintenance interval compression constrain long-term positioning.
- Electric Actuators:Distributed electromechanical units convert electrical energy to precise mechanical motion through motor-drive architectures. Department of Defense fly-by-wire modernization across tactical aircraft fleets accelerates adoption, trimming hydraulic line maintenance and eliminating single-point failure modes.
- Pneumatic Actuators:Compressed-air systems serve auxiliary functions and emergency backup roles in legacy bomber platforms.
- Mechanical Actuators:Direct mechanical linkages persist in trainer aircraft and certain rotary-wing applications where simplicity outweighs precision requirements.
Hydraulic actuators lead on scale through installed base dominance; electric actuators lead on momentum through next-generation platform specifications.
Technology:
Certification burden and integration complexity separate mature architectures from emerging intelligence-embedded alternatives, with defense procurement offices mandating fault-tolerant designs for new-start programs.
- Fly-by-Wire:Electronic flight control systems replace mechanical linkages between cockpit and control surfaces. The U.S. Department of Defense prioritizes this architecture across tactical aircraft fleets, creating sustained demand for dual-channel electromechanical units with fail-operational redundancy.
- Smart Actuation:Embedded health monitoring and predictive maintenance protocols align with U.S. Air Force Condition-Based Maintenance Plus initiatives. These systems command premium positioning through software-enabled service revenue streams and operational availability contracting.
- Electromechanical:Motor-drive actuation without embedded intelligence serves as transition technology in hybrid architectures.
- Traditional Systems:Purely mechanical and hydraulic architectures without electronic augmentation serve legacy platform sustainment.
Fly-by-Wire leads on scale through installed base and procurement mandate; Smart Actuation climbs the fastest through predictive maintenance protocol adoption.
End User:
Contracting vehicle and specification authority determine supplier access, with defense primes integrating subsystems differently than direct government procurement.
- Military Aviation:Armed forces operate the installed base and define operational requirements flowing to subsystem vendors. The U.S. Air Force Next Generation Air Dominance program recalibrates performance specifications for actuation bandwidth and failure-mode resilience.
- Defense Contractors:Prime airframe manufacturers integrate actuation systems and manage tiered supply chains. Boeing Defense, Space & Security and Lockheed Martin Aeronautics exert specification control through DFARS contracting clauses.
- Government Agencies:Defense Logistics Agency performance-based logistics contracts index payments to operational availability metrics.
- Aerospace Manufacturers:Commercial-military crossover suppliers serve derivative military transport platforms.
Military Aviation leads on scale through operational fleet ownership; Defense Contractors lead on momentum through next-generation development program control.
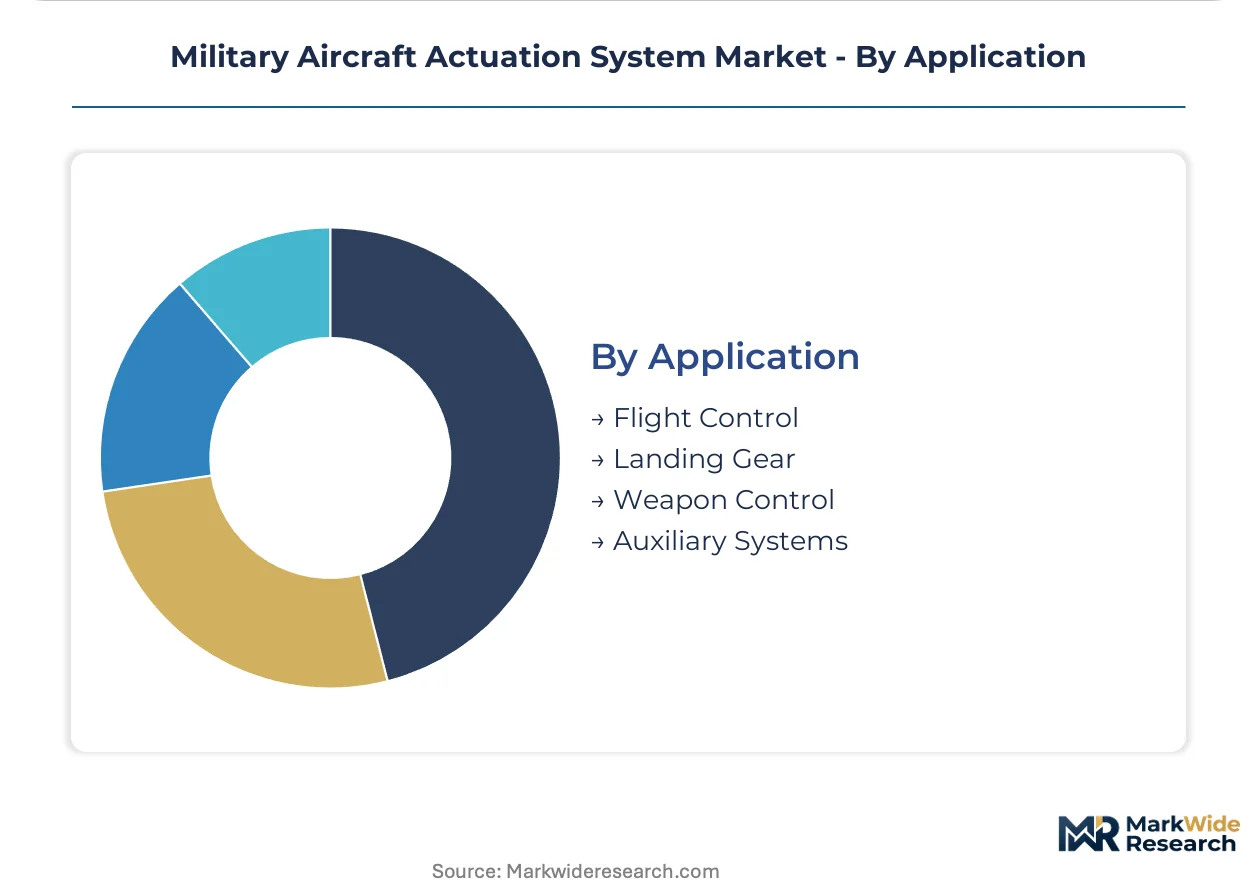
Application:
Mission-criticality and failure-mode tolerance shape specification stringency, with flight control systems facing the most rigorous certification thresholds.
- Flight Control:Primary and secondary control surface positioning demands positional accuracy within fractions of a degree. FAA and EASA airworthiness directives on redundancy accelerate certification requirements for dual-channel electromechanical units with demonstrated fault detection latency below specified thresholds.
- Landing Gear:Extension, retraction, and steering actuation operates under high-load, shock-intensive conditions. Safran S.A. anchors European supply chains through integrated landing gear and actuation architectures serving Airbus Defence and Space platforms.
- Weapon Control:Station positioning and bay door actuation requires rapid response under electromagnetic interference-hardened conditions per MIL-STD-461.
- Auxiliary Systems:Cabin pressurization, fuel management, and utility actuation face reduced certification burden.
Flight Control leads on scale through system count and specification premium; Landing Gear leads on momentum through integrated architecture consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States defense industrial base concentrates actuation system engineering talent around Washington DC corridor clusters and California aerospace hubs, with prime contractors driving specification authority through DFARS contracting clauses.
United States
The Department of Defense prioritizes fly-by-wire modernization across tactical aircraft fleets, creating sustained procurement pull for dual-channel electromechanical units. FAA airworthiness directives on flight control redundancy accelerate certification requirements for fault-tolerant designs. Defense contractors in the Washington DC-Baltimore corridor and Southern California aerospace clusters manage tiered supply chains flowing specification requirements to subsystem vendors.
France
Franco-German-Spanish FCAS development channels R&D investment toward integrated landing gear and flight control architectures. EASA updated Certification Specifications for Large Aeroplanes tighten verification protocols for electromechanical actuator failure modes and jamming scenarios. Toulouse and Paris-Saclay aerospace clusters anchor European supply chains for next-generation fighter platform actuation.
United Kingdom
UK Ministry of Defence procurement offices mandate distributed electromechanical architectures for new-start combat air programs. Military aviation safety regulations require electromagnetic interference hardening per DEF STAN standards for servo drive electronics. Bristol and Greater London aerospace engineering centers concentrate electromechanical-software integration capabilities for smart actuation development.
Germany
FCAS joint program participation recalibrates performance specifications for actuation bandwidth and failure-mode resilience in extreme maneuverability envelopes. Luftwaffe technical airworthiness requirements flow through national military aviation authority certification protocols. Munich and Hamburg metropolitan regions host systems integration specialists serving Airbus Defence and Space military transport platforms.
Israel
Israeli Air Force operational requirements emphasize electromagnetic interference-hardened weapon control actuation for rapid response station positioning. National defense procurement regulations prioritize dual-use semiconductor sourcing resilience for ITAR-controlled servo drive components. Tel Aviv and Haifa technology corridors concentrate aerospace mechatronics engineering talent for indigenous fighter platform development.
Military Aircraft Actuation System Market Vendor Landscape
Global majors compete with regional champions across defense procurement contracting, with prime airframe manufacturers exerting specification control through program-specific technical requirements. The vendor landscape organizes around three strategic archetypes: heritage aerospace controls specialists with electromechanical flight control legacies, integrated landing gear and actuation architecture providers, and high-reliability servo valve competitors spanning hydraulic and hybrid-electric tiers. Dominant competitive moves include strategic partnerships for next-generation platform development and portfolio diversification into predictive maintenance software services.
Within the heritage aerospace controls tier, Curtiss-Wright Corporation exemplifies sustained positioning in electromechanical flight control actuators for fixed-wing military platforms. Safran S.A. occupies a position anchoring European supply chains through integrated system architectures. Moog Inc. represents the high-reliability component specialist archetype competing across hydraulic and hybrid-electric system tiers. These three entities illustrate how technical specialization and geographic concentration shape competitive positioning in defense actuation procurement.
| Leading Market Players |
|---|
| Curtiss-Wright Corporation |
| Safran S.A. |
| Moog Inc. |
| Liebherr Group |
| Triumph Group Inc. |
| Honeywell International Inc. |
| Woodward Inc. |
| Eaton Corporation |
| Parker Hannifin Corporation |
| Others |
Supply Flow & Price Mechanics
Captive titanium and high-grade aluminum sourcing through backward integration into specialized alloy supply chains anchors both supply security and pricing power for prime contractors. Defense procurement offices leverage DFARS contracting clauses to lock in multi-year offtake agreements, compressing margin volatility for integrated suppliers while exposing non-integrated vendors to spot-market exposure.
Pricing Analysis
Input-cost pass-through from titanium billet and rare-earth magnet suppliers dominates contract pricing structures, with dual-channel electromechanical units commanding premium positioning over single-channel alternatives. Price differentiation separates ITAR-certified production lines from commercial-grade equivalents, while volume-scale procurement through the Defense Logistics Agency reduces per-unit acquisition costs for fleet-wide modernization programs. Pricing pressure stems from foundry capacity constraints for qualified servo drive electronics, stretching lead times and inflating non-recurring engineering burdens. Tier 2 subsystem vendors exhibit highest price sensitivity due to limited backward integration, whereas primes with in-house alloy sourcing maintain margin resilience.
Supply Chain Analysis
Titanium sponge supply rests on Japanese and Russian producers, with downstream forging concentrated in United States and European aerospace clusters. Rare-earth permanent magnets draw from Chinese separation facilities, while high-reliability semiconductors source from United States and Israeli foundries subject to ITAR controls. Single-source vulnerability concentrates in qualified servo valve machining and carbon-fiber preform weaving, where certification timelines block rapid supplier switching. Distribution runs through prime contractor tiered supply chains flowing from Washington DC-Baltimore corridor engineering centers to Southern California integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense actuation procurement offers geographic-arbitrage potential through divergent electromagnetic interference hardening costs between United States MIL-STD-461 testing requirements and European DEF STAN equivalency pathways.
For Market Incumbents: Lock in long-term titanium offtake agreements before spot-market volatility intensifies, and accelerate embedded health monitoring software development to capture performance-based logistics revenue streams. Threat from ITAR-controlled semiconductor foundry capacity constraints demands captive wafer allocation or joint venture partnerships with qualified suppliers. Certification investment in EASA updated jamming-scenario protocols represents the critical lever for European platform access. For New Entrants and Emerging Players: Tier 2 electromechanical component suppliers present the most penetrable channel partner type for smart actuation subsystem insertion, particularly those serving rotorcraft aftermarket sustainment. White space concentrates in predictive maintenance software services aligned with U.S. Air Force Condition-Based Maintenance Plus initiatives, and in high-frequency response designs for Next Generation Air Dominance bandwidth specifications. Go-to-market execution should prioritize performance-based logistics contracting vehicles over traditional spares-provisioning agreements. For Investors and Strategic Acquirers: Roll-up economics work for electromechanical-software integration specialists because defense procurement offices are consolidating vendor lists around firms mastering embedded sensing and predictive analytics capabilities. Five-to-ten year viability hinges on positioning within Next Generation Air Dominance and European FCAS development program supply chains. Acquisition target archetype: mid-cap smart actuation developers with demonstrated fault-detection latency performance below EASA thresholds. Signal to watch: U.S. Defense Logistics Agency contract awards indexing payments to operational availability metrics rather than unit delivery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Forging | Secures qualified alloy supply for F-35 and NGAD actuator housings against Russian export volatility. |
| Embedded Health Monitoring Platform Launch | Aligns with U.S. Air Force Condition-Based Maintenance Plus software revenue requirements. |
| EASA Certification Pathway Investment | Opens Airbus Defence and Space military transport and derivative platform procurement access. |
| Dual-Use Semiconductor Joint Venture | Addresses ITAR-controlled foundry capacity constraints stretching qualified component lead times. |
| Performance-Based Logistics Contract Conversion | Shifts revenue model from unit delivery to operational availability metrics demanded by Defense Logistics Agency. |
Methodological Framework
Bottom-up platform-level modeling reconciled against top-down defense procurement tracking forms the analytical core of this study. Primary interviews with electromechanical engineering directors, supply chain managers at prime contractors, Defense Logistics Agency contracting officers, and EASA certification specialists combined with secondary validation from FAA airworthiness directive filings, DoD budget justification documents, and SEC 10-K aerospace segment disclosures. Triangulation across bottom-up actuator unit forecasts and top-down program-level procurement allocations ensures methodological rigor.
Input-output matrices map titanium alloy consumption, rare-earth magnet demand, and servo drive electronics procurement against projected platform production rates across the analysis window. Segmentation dimensions include product type, technology architecture, application criticality, and end-user contracting vehicle, with CAGRs derived from regression analysis of historical procurement patterns and program office modernization timelines. Forecast inputs incorporate electromagnetic interference hardening cost trajectories and embedded sensor cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Next Generation Air Dominance program schedule shifts and Franco-German-Spanish FCAS funding continuity. Forecasts reflect documented assumptions regarding ITAR semiconductor foundry capacity expansion and titanium sponge supply diversification. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Aviation Actuator System Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Electronic Ignition System Market