
 Aerospace Couplers Market | 2026-2036
Aerospace Couplers Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Couplers Market Analysis
Modular quick-connect configurations is broadening buyer choice across hydraulic, pneumatic, and electrical subsystems. Eaton Corporation leverages captive manufacturing of titanium-alloy fittings for pressure-rated aerospace lines. Parker Hannifin Corporation anchors its position through backward integration into seal elastomer compounding. ITT Inc. competes on hermetic connector architectures for engine-mounted applications.
Aerospace couplers are precision-engineered fluid and signal interface devices, typically machined from 6061-T6 aluminum or Ti-6Al-4V titanium with operating pressure ratings exceeding 3000 psi, designed to enable rapid connection and disconnection of lines during assembly, maintenance, and mission-critical operations. Hydraulic couplers dominate current procurement volumes due to persistent demand from flight control and landing gear systems, while fiber optic couplers represent the fastest-expanding material category as fly-by-light architectures displace copper harnesses in next-generation avionics backbones. Electrical couplers sustain above-average margin pools where shielding against electromagnetic interference commands specification premiums.
The FAA mandates flammability and fatigue testing under 14 CFR Part 25 airworthiness standards, while EASA enforces comparable CS-25 certification through its Cologne-based rulemaking directorate; both frameworks directly shape product development timelines and supplier qualification costs. China's CAAC aligns with these standards through bilateral safety agreements but adds domestic GB/T testing protocols for locally assembled platforms. Stakeholders must monitor how emerging hydrogen propulsion architectures will redefine seal compatibility specifications and pressure-cycle testing regimes.
Market Dynamics
The transition from copper-based electrical harnesses to fiber optic architectures in next-generation aircraft is compressing connector replacement cycles and forcing recertification of legacy hydraulic interfaces across narrow-body production lines.
Growth Catalysts
- 14 CFR Part 25 fatigue mandates:FAA airworthiness standards for quick-disconnect systems are accelerating fleet-wide retrofit programs among US-based carriers.
- Hydrogen propulsion R&D:Seal compatibility testing for cryogenic fuel lines is opening specification windows for advanced elastomer compounds in engine-mounted couplers.
- China narrow-body assembly:Final production lines in Shanghai and Tianjin are pulling connector volumes for COMAC C919 derivative programs.
Market Restraints
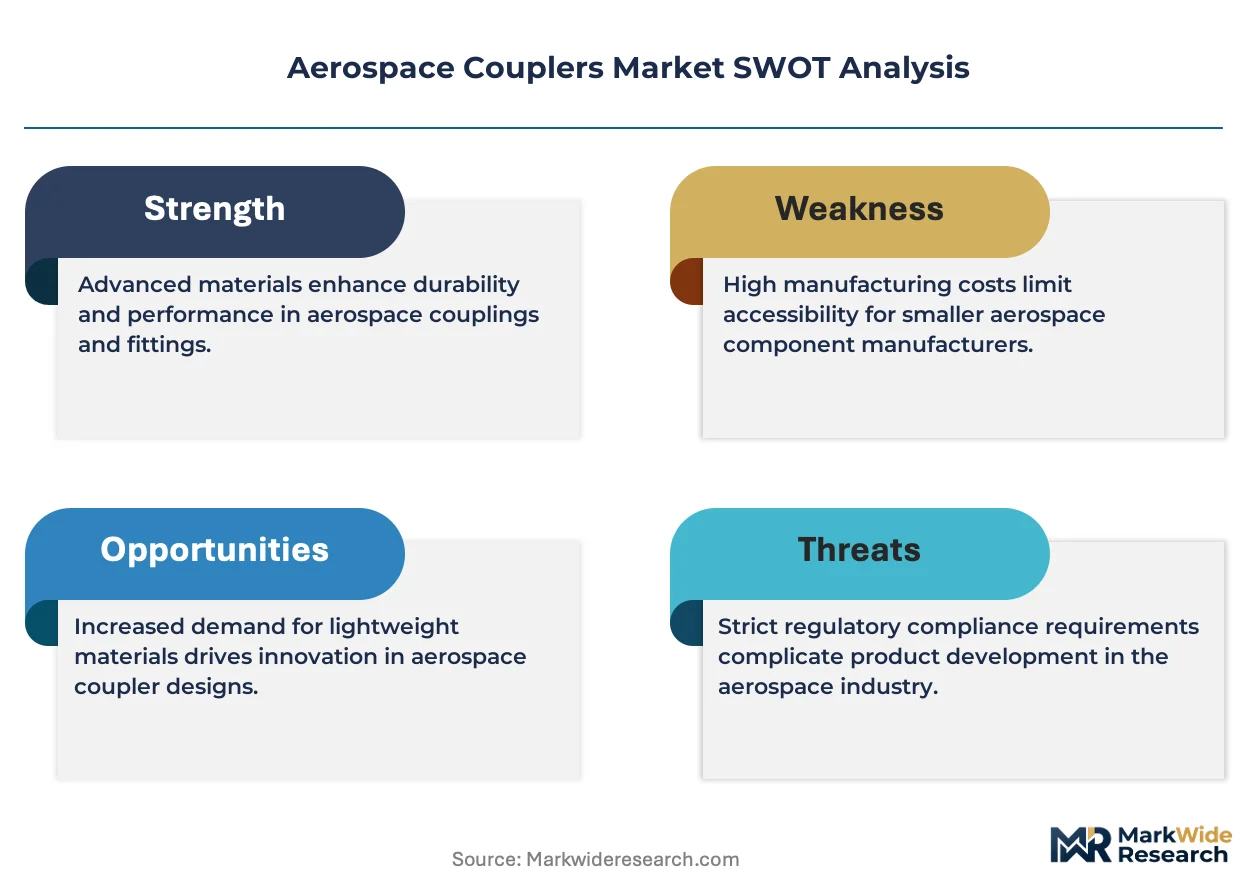
- Titanium alloy supply concentration:Sponge production in Russia and Kazakhstan creates input cost volatility for Ti-6Al-4V fittings.
- EASA CS-25 certification timelines:Cologne-based testing protocols extend supplier qualification periods to 18-24 months for hermetic electrical variants.
- Additive manufacturing substitution:3D-printed titanium lattices threaten machined aluminum couplers in non-pressurized avionics applications.
Strategic Opportunities
- India MRO expansion:Bangalore and Hyderabad maintenance clusters lack indigenous quick-connect supply, creating import substitution potential.
- EU Green Deal SAF mandates:Sustainable aviation fuel compatibility testing protocols favor seal architectures with broader chemical resistance profiles.
- Fly-by-light convergence:Fiber optic and power electronics integration in wing-mounted systems demands hybrid electro-optical coupler designs.
Industry Challenges
- AS9100D auditor scarcity:Aerospace quality management certification bottlenecks delay supplier onboarding for tier-two machine shops.
- Legacy platform obsolescence:Boeing 737 NG and Airbus A320ceo phase-out schedules compress remaining service-life connector procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Couplers Market |
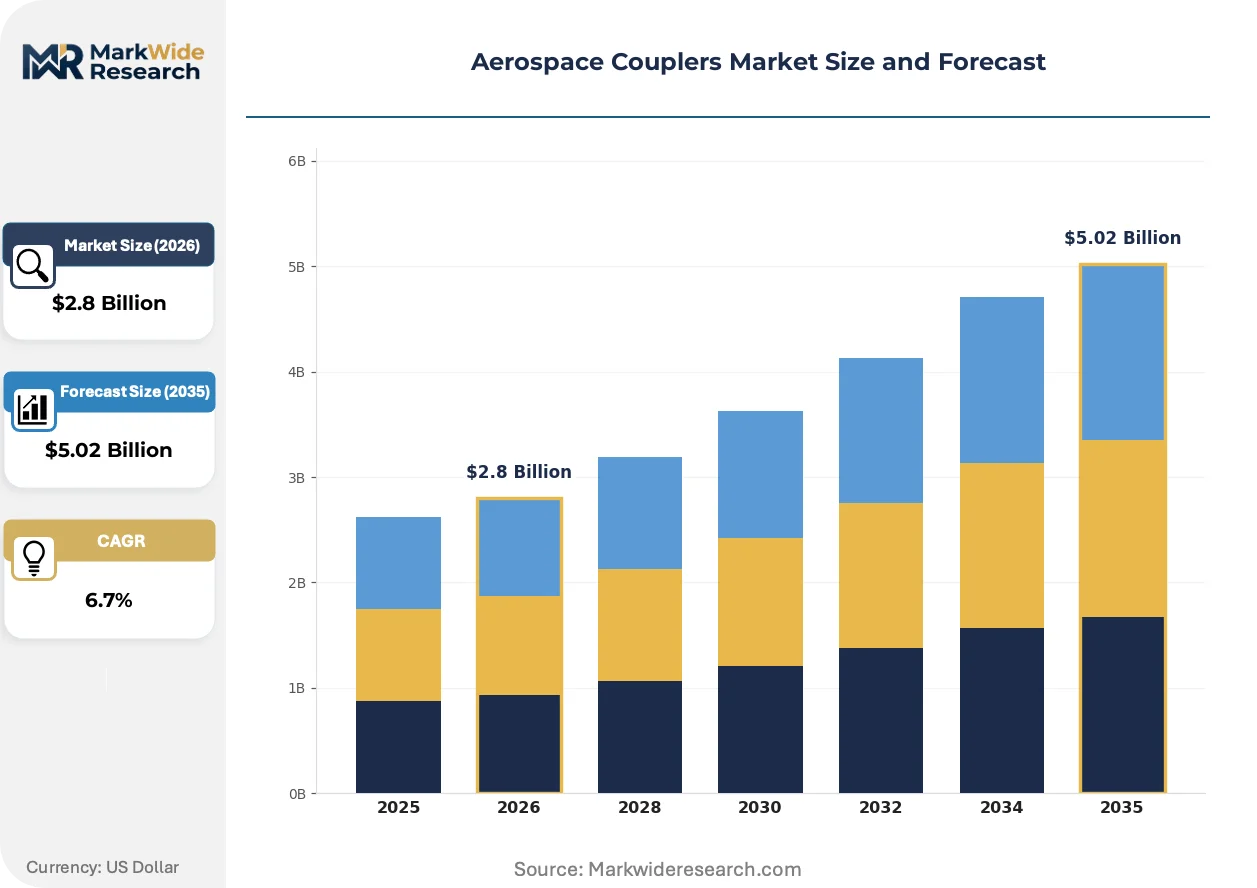
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Couplers, Pneumatic Couplers, Electrical Couplers, Fiber Optic Couplers Material: Aluminum, Stainless Steel, Titanium, Composite Application: Aerospace Engineering, Aircraft Maintenance, Spacecraft Systems, Avionics End User: Commercial Aviation, Military Operators, Aerospace Manufacturers, Maintenance, Repair, and Overhaul (MRO) Providers |
| Companies Covered | Eaton Corporation, Parker Hannifin Corporation, ITT Inc., Stäubli International AG, Senior plc, Crane Co., GKN Aerospace, TE Connectivity Ltd., Coupling Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Couplers Market Emerging Trajectories
Material science advances and certification protocol evolution are converging to redefine interface architectures. Three developments warrant particular attention from procurement and engineering stakeholders.
Additive manufacturing is modularizing titanium-alloy coupler production. Tier-one suppliers now print lattice-structured fittings with internal flow channels previously impossible to machine. Airlines with in-house engineering capabilities are adopting these configurations for non-critical pneumatic lines. The technology is modularizing supplier-customer relationships by enabling print-on-demand spare fulfillment rather than minimum-order-quantity casting runs.
REACH Annex XVII restrictions on perfluorinated compounds are forcing seal compound reformulation across European supply chains. ECHA's 2023 PFAS restriction proposal targets PTFE and FKM elastomers common in hydraulic couplers. German and French connector specialists are accelerating hydrogenated nitrile and thermoplastic polyurethane alternatives. Engine-mounted applications face the steepest retesting burden given temperature and pressure extremes.
Power-by-the-hour maintenance contracts are compressing component ownership models. Lessors and regional carriers now demand serialized traceability and predictive replacement scheduling embedded in coupler RFID tags. MRO networks in Southeast Asia are piloting blockchain-verified component histories. The behavioral shift is most pronounced in narrow-body lease portfolios where utilization rates exceed 14 hours daily.
Aerospace Couplers Market Segmentation
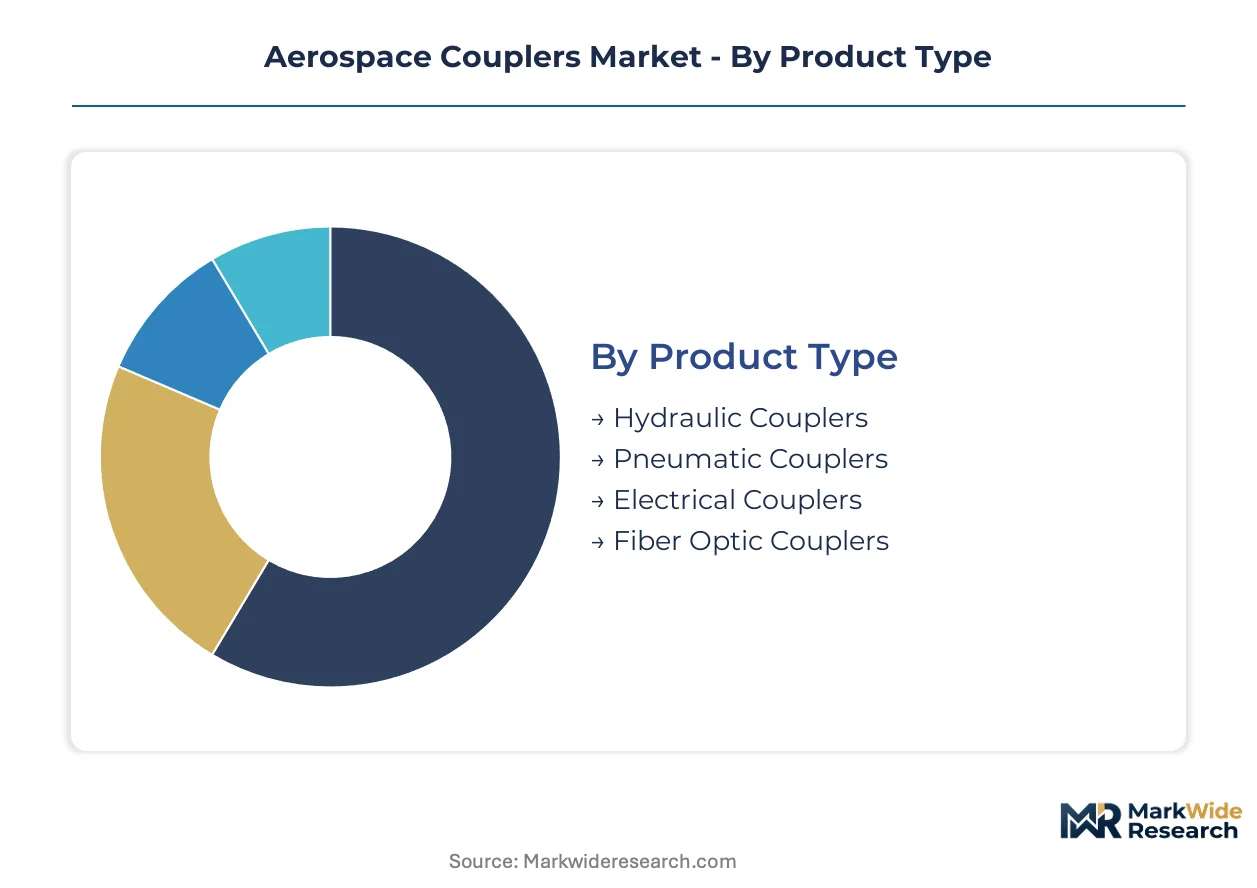
Aerospace coupler procurement splits sharply between flight-critical hydraulic systems commanding specification premiums and commodity pneumatic lines competing on unit economics. Understanding where volume concentrates versus where margins accumulate enables supplier positioning across certification tiers.
Product Type:
Hydraulic and electrical variants dominate current procurement tonnage, while fiber optic architectures are capturing specification share in next-generation platforms.
- Hydraulic Couplers:Machined from 6061-T6 aluminum or Ti-6Al-4V titanium with pressure ratings exceeding 3000 psi, these precision fittings enable rapid connection of flight control and landing gear lines. Demand concentrates in narrow-body final assembly lines across the United States, China, and Germany where fleet expansion is accelerating connector replacement cycles.
- Electrical Couplers:Hermetic connector architectures with electromagnetic interference shielding command above-average margin pools in engine-mounted applications. Procurement from US-based carriers is intensifying under FAA 14 CFR Part 25 fatigue mandates requiring fleet-wide retrofit programs.
- Pneumatic Couplers:Non-pressurized avionics applications where additive manufacturing threatens machined aluminum alternatives.
- Fiber Optic Couplers:Fly-by-light architectures displacing copper harnesses in next-generation avionics backbones.
Today's leader: Hydraulic Couplers. Tomorrow's challenger: Fiber Optic Couplers.
Material:
Titanium and aluminum split the market between premium pressure-rated applications and cost-optimized pneumatic lines, with composites emerging at the technology frontier.
- Titanium:Ti-6Al-4V sponge supply from Russia and Kazakhstan creates input cost volatility for pressure-rated fittings in hydraulic systems.
- Aluminum:6061-T6 remains the workhorse for non-critical pneumatic and avionics couplers where weight savings justify specification.
- Stainless Steel:Corrosion-resistant variants for marine-environment military applications and cryogenic fuel line testing protocols.
- Composite:Polymer-matrix configurations gaining traction in satellite and unmanned aerial vehicle platforms where electromagnetic transparency matters.
Titanium commands the premium tier. Composites are climbing the fastest.
Application:
Engineering and maintenance applications diverge in certification burden, with spacecraft systems imposing the most stringent qualification timelines.
- Aerospace Engineering:New platform development programs in Shanghai, Tianjin, and Toulouse pulling connector volumes for derivative aircraft designs.
- Aircraft Maintenance:Power-by-the-hour contracts in Southeast Asian MRO networks are piloting blockchain-verified component histories with serialized RFID traceability.
- Spacecraft Systems:Hermetic sealing and thermal cycling specifications under EASA CS-25 protocols extend supplier qualification to 18-24 months.
- Avionics:Fiber optic integration in wing-mounted systems demanding hybrid electro-optical coupler architectures.
Maintenance represents the volume anchor. Spacecraft Systems set the technology frontier.
End User:
Commercial aviation fleet expansion is outpacing military procurement, while MRO providers are consolidating bargaining power through predictive maintenance platforms.
- Commercial Aviation:Narrow-body lease portfolios with utilization rates exceeding 14 hours daily are compressing component ownership models toward serialized lifecycle tracking.
- Maintenance, Repair, and Overhaul (MRO) Providers:Bangalore and Hyderabad maintenance clusters lack indigenous quick-connect supply, creating import substitution potential for certified suppliers.
- Military Operators:Sustainment budgets for legacy platforms facing phase-out schedules that compress remaining service-life procurement windows.
- Aerospace Manufacturers:COMAC C919 production lines in China pulling connector volumes with domestic GB/T testing protocols layered atop bilateral safety agreements.
Commercial Aviation holds the volume base. MRO Providers are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace coupler manufacturing traces its industrial lineage to post-war precision machining clusters in the United States and Germany, where defense procurement established the metallurgical and certification foundations that now govern global supply.
United States
Boeing 737 MAX and 777X production lines in Renton and Everett drive hydraulic coupler procurement volumes. FAA 14 CFR Part 25 fatigue mandates accelerate fleet-wide retrofit programs among domestic carriers. Wichita's Air Capital cluster houses specialized machine shops supplying quick-disconnect fittings for flight control systems.
China
COMAC C919 derivative programs in Shanghai and Tianjin pull connector volumes for narrow-body final assembly. CAAC aligns with FAA and EASA standards through bilateral safety agreements while adding domestic GB/T testing protocols. Xi'an's aerospace manufacturing base is scaling titanium-alloy machining capacity for pressure-rated hydraulic lines.
Germany
Airbus A320 family production in Hamburg and Toulouse-bound component flows sustain electrical coupler demand for engine-mounted applications. EASA CS-25 certification protocols extend supplier qualification timelines. Bavaria's precision engineering corridor around Munich specializes in hermetic connector architectures with electromagnetic interference shielding.
France
SAF compatibility testing under EU Green Deal mandates favors seal architectures with broader chemical resistance profiles. ANSM oversight of aerospace material safety intersects with EASA rulemaking for hydrogen propulsion R&D. Toulouse-Blagnac's aeronautical cluster integrates fiber optic couplers into fly-by-light avionics backbones.
India
Bangalore and Hyderabad maintenance clusters lack indigenous quick-connect supply, creating import substitution potential for certified suppliers. DGFT import licensing frameworks shape tier-two supplier onboarding timelines. The Delhi-Mumbai Industrial Corridor is attracting aerospace component investments targeting MRO provider consolidation.
Aerospace Couplers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and material specification, with hermetic electrical variants and titanium-alloy pressure-rated fittings commanding specification premiums that machined aluminum pneumatic lines cannot match. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive aerospace divisions, specialized connector engineering houses with deep certification expertise, and regional fabricators serving non-flight-critical subsystems. Consolidation pressure is intensifying through backward integration into seal elastomer compounding and additive manufacturing partnerships for lattice-structured titanium production.
Within the diversified industrial tier, Eaton Corporation and Parker Hannifin Corporation exemplify scale-driven positioning through upstream control over critical material inputs. ITT Inc. occupies a specialist position anchored in hermetic connector architectures. These three entities represent contrasting competitive vectors: conglomerate breadth versus engineering depth versus application-specific certification dominance.
| Leading Market Players |
|---|
| Eaton Corporation |
| Parker Hannifin Corporation |
| ITT Inc. |
| Stäubli International AG |
| Senior plc |
| Crane Co. |
| GKN Aerospace |
| TE Connectivity Ltd. |
| Coupling Corporation of America |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainable aviation fuel mandates gate qualified supply and premium-tier pricing access, as seal compound reformulation for SAF compatibility testing separates certified suppliers from commodity fabricators. Buyers face bifurcated procurement landscapes where hermetic electrical variants command specification premiums machined aluminum pneumatic lines cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material specification. Price differentiation rests on FAA 14 CFR Part 25 fatigue certification status and Ti-6Al-4V titanium content versus 6061-T6 aluminum substitution. Cost compression in pneumatic avionics tiers is intensifying because additive manufacturing threatens machined legacy configurations. Regional carriers and lessors operating narrow-body lease portfolios exhibit highest price sensitivity, while spacecraft systems buyers prioritize qualification timelines over unit economics.
Supply Chain Analysis
Regional distribution centers in Wichita, Hamburg, and Shanghai orchestrate hub-and-spoke patterns for flight-critical hydraulic fittings. Manufacturing concentrates in the United States, Germany, and China where final assembly lines for Boeing 737 MAX, Airbus A320 family, and COMAC C919 programs pull connector volumes. Raw material dependencies center on Ti-6Al-4V sponge from Russia and Kazakhstan, seal elastomer compounds from German and French specialists, and 6061-T6 aluminum billet from domestic smelters. Single-source vulnerability in titanium sponge creates input cost volatility. Distribution runs through tier-one supplier direct-ship programs and authorized distributor networks serving MRO clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as fly-by-light avionics architectures displace copper harnesses and force recertification toward premium fiber optic and hermetic electrical specifications.
For Market Incumbents: Deploy backward integration into seal elastomer compounding to offset REACH Annex XVII PFAS restriction impacts on PTFE and FKM supply. Capture additive manufacturing partnerships for lattice-structured titanium production before 3D-printed alternatives commoditize non-pressurized pneumatic tiers. Eaton Corporation and Parker Hannifin Corporation exemplify this defensive posture through captive material control. For New Entrants and Emerging Players: MRO providers in Bangalore and Hyderabad maintenance clusters present underserved buyer archetypes lacking indigenous quick-connect supply. Target import substitution opportunities by qualifying under DGFT licensing frameworks and AS9100D protocols faster than incumbent certification timelines. Lead with serialized RFID traceability and blockchain-verified component histories aligned with power-by-the-hour contract demands. For Investors and Strategic Acquirers: Roll-up economics work for specialized connector engineering houses because EASA CS-25 and FAA 14 CFR Part 25 certification bottlenecks create durable moats around qualified supplier bases. Focus on tier-two machine shops with hermetic sealing expertise and existing aerospace OEM relationships. Watch hydrogen propulsion R&D progress as the inflection indicator for cryogenic seal compatibility specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Elastomer Compounding | Captive supply of hydrogenated nitrile compounds insulates against ECHA PFAS restriction timelines. |
| Additive Manufacturing Partnership for Titanium Lattices | Print-on-demand spare fulfillment disrupts minimum-order-quantity casting economics for non-critical lines. |
| AS9100D Certification Investment | Quality management accreditation unlocks tier-one supplier status for narrow-body final assembly programs. |
| Hybrid Electro-Optical Coupler Development | Fly-by-light convergence in wing-mounted systems demands integrated fiber optic and power electronics interfaces. |
| Blockchain-Verified Component History Platform | Serialized traceability aligns with lessor predictive maintenance contracts exceeding 14-hour daily utilization rates. |
Methodological Framework
Coverage spans the United States, China, Germany, France, and India, with primary inputs from each aerospace manufacturing cluster. Primary interviews engaged procurement directors at narrow-body final assembly lines, MRO operations managers in Southeast Asian maintenance hubs, quality assurance leads at tier-one hydraulic system suppliers, and regulatory affairs specialists navigating FAA, EASA, and CAAC certification pathways. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 rulemaking updates, COMAC production announcements, customs trade data for titanium alloy imports, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up connector volume estimates triangulated against top-down fleet expansion projections from aircraft OEM production schedules.
Granularity-level framing modeled product type, material specification, application, and end user dimensions at the country-cluster level across the analysis window. Hydraulic, electrical, pneumatic, and fiber optic coupler categories were separately forecasted with titanium, aluminum, stainless steel, and composite material splits. Commercial aviation, MRO provider, military operator, and aerospace manufacturer end-user segments incorporated utilization rate assumptions and replacement cycle dynamics. CAGRs were derived from fleet age profiles, certification mandate implementation schedules, and derivative aircraft program launch timelines. Hydrogen propulsion R&D expenditure trajectories and SAF compatibility testing protocol adoption curves informed scenario-weighted outputs.
Underlying measurement precision varies by segment; hydraulic couplers in narrow-body production carry tighter precision than spacecraft systems given longer qualification timelines and smaller addressable volumes. Forecasts reflect assumptions around FAA and EASA regulatory stability, titanium sponge supply continuity, and additive manufacturing adoption rates in non-flight-critical applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Aircraft Pylon and Strut Fairing Retrofit Kits Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Structural Health Monitoring Access Panels Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market